

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Anti‑Fog Polycarbonate Film & Sheet Market Poised for 5.45% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-07-13
Anti-Fog Polycarbonate Film and Sheet Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive snapshot
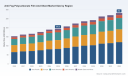
PW Consulting’s latest market study on Anti-Fog Polycarbonate Film and Sheet delivers an evidence-based line of sight for executives planning through 2026 and beyond. Using 2025 as the base year, our top-line forecast shows the market expanding from an estimated USD 194.5 Million in 2025 to approximately USD 282.0 Million by 2032, representing a compound annual growth rate (CAGR) of 5.45% over the 2026–2032 forecast window. These headline numbers capture both steady underlying demand across safety, architectural and display end-markets and a wave of structural change on the supply side that will determine winners and losers in the next 18–36 months.
Anti Fog Polycarbonate Film And Sheet Market
Why 2026 is a strategic inflection point
-
Decision cadence is accelerating. Capital allocation, contracting and product roadmaps locked in during 2026 will crystallize players’ competitive positions for the remainder of the decade. Manufacturers that act early on capacity alignment, formulation innovation and regulatory compliance will capture disproportionate share of the moderate but persistent growth trajectory outlined above.
Anti Fog Polycarbonate Film And Sheet Market -
Cost and regulatory shocks are amplifying execution risk. Recent feedstock price volatility and the emergence of new regulatory constraints are raising both input cost uncertainty and compliance costs—pressures that require tactical changes in procurement, pricing and product formulation.
Anti Fog Polycarbonate Film And Sheet Market -
Product differentiation is becoming table stakes. With market concentration moderately elevated (CR3 and CR5 metrics indicate top-tier incumbents control a meaningful share), specialized coatings (e.g., long-duration hydrophilic anti-fog, PFAS-free chemistries) and service capabilities (custom fabrication, certified supply chains) are decisive competitive levers.
Market dynamics shaping strategic choices
-
End-market mix and technology convergence: Growth in medical and safety visors, architectural glazing, refrigerated displays and select automotive applications continues to underpin demand for anti-fog polycarbonate substrates. At the same time, display and optical performance requirements are encouraging suppliers to combine anti-fog functionality with anti-scratch, UV-stability and optical-grade clarity.
-
Supply chain and cost pressures: Feedstock dynamics have tightened supplier margins and prompted near-term cost pass-through conversations across the value chain. Procurement teams should anticipate continued volatility and adopt hedging and supplier diversification strategies rather than relying on historical spot-price patterns.
-
Regulatory and sustainability drivers: Tighter chemical regulatory controls and growing buyer demand for sustainable solutions are accelerating R&D toward low-impact, durable anti-fog treatments. At least one major coating supplier has launched PFAS-free alternatives, signaling a technology pivot that will influence product acceptance in environmentally regulated markets.
-
Capacity and geography: Strategic capacity expansions announced in late 2025 and early 2026 are set to reshape regional supply balances. New multiwall and sheet production facilities and increased coating capacity will ease supply in targeted end-markets but will also raise competitive intensity in commodity-grade segments.
Competitive landscape — practical reading
The market exhibits a moderate level of concentration: the three- and five-firm concentration ratios indicate that top suppliers hold substantial influence but do not form an impenetrable oligopoly. This structure creates space for specialized and regional players to thrive alongside global raw-material and coating specialists.
-
Global integrated suppliers: Firms with upstream polymer capabilities and proprietary coating systems retain advantages in scale, product consistency and certified supply chains. Their strategic playbooks center on deep technical partnerships with OEMs, multi-year supply agreements, and platform-based product families that bundle anti-fog, anti-scratch and UV resistance.
-
Regional manufacturers and fabricators: A cohort of agile manufacturers—particularly in Asia—competes on fast lead times, custom fabrication and cost competitiveness. These players are attractive partners for regional OEMs and distributors seeking tailored sheet dimensions and rapid prototyping services.
-
Coating specialists and licensors: Independent coating technology companies differentiate through formulation IP (including environmentally preferable chemistries) and application know-how. Their success depends on licensing deals, turnkey coating services and co-development agreements with sheet manufacturers and OEMs.
Notable vendor developments in the last 18 months illustrate these dynamics: a capacity expansion partnership creating a large North American multiwall sheet facility scheduled for 2026; the commercial introduction of PFAS-free anti-fog coatings; and public guidance from a regional manufacturer on extended durability formulations for high-humidity environments. Individually these moves matter; aggregated, they signal a market pivot toward higher-value, compliance-forward offerings.
Implications for corporate decision-makers in 2026
PW Consulting’s research translates to six concrete imperatives firms should prioritize this year.
-
Recalibrate procurement and pricing strategies: Move from reactive spot purchasing to structured supplier agreements with embedded cost-remediation triggers. Incorporate index-linked clauses, multi-supplier panels and strategic safety stocks to mitigate feedstock shocks.
-
Differentiate through formulation and certification: Invest selectively in coating partnerships or licensing arrangements that deliver PFAS-free and long-duration anti-fog performance. For OEMs in regulated sectors, prioritize suppliers with transparent supply-chain certifications and compliance roadmaps.
-
Optimize capacity and footprint decisions: Evaluate incremental capacity versus contract manufacturing. Use scenario models to stress-test capacity investments against demand shifts from key end-markets (medical PPE, architectural glazing, refrigerated display sectors).
-
Embed sustainability in product roadmaps: Develop a staged substitution plan for legacy chemistries and align product introductions with emerging regulatory timetables. Marketing messaging tied to demonstrable lifecycle benefits can unlock premium pricing in some segments.
-
Pursue targeted M&A and alliance plays: Look to acquire capabilities (coatings, surface treatments, fabrication tech) that accelerate time-to-market for value-added products. Strategic alliances with coating specialists or regional fabricators can be a lower-capex route to capability acquisition.
-
Strengthen commercial go-to-market and warranty frameworks: As product complexity grows, customers will demand clearer warranties, performance metrics and replacement policies. Standardized test protocols and third-party validation will reduce buyer friction.
What the full PW Consulting report delivers (select highlights)
This preview intentionally avoids disclosing segment-level allocations and company revenue breakdowns to preserve the competitive value of our proprietary analysis. The complete report, however, equips decision-makers with operational tools and diagnostics they can act on in 2026:
-
Actionable scenario forecasts and demand-sensitivity models designed for supply-planning and investment appraisal across a seven-year horizon.
-
Supplier scorecards and an RFP playbook to accelerate qualification of coated sheet and film providers, including technical KPIs, environmental compliance checklists and cost-to-serve templates.
-
Coating technology matrix mapping durability, environmental footprint and cost implications—plus a short-list of proven formulation partners for rapid pilot programs.
-
Regulatory impact map with timelines and compliance pathways tailored to major markets; a decision tree to prioritize reformulation, relabelling or market exit options.
-
Commercial negotiation frameworks for long-term supply agreements, including model contractual clauses for cost pass-through, quality disputes and technology migration.
-
Deal tracker and capacity atlas summarizing recent plant openings, announced expansions and strategic partnerships—presented with confidence intervals to help planners assess availability risk.
How to use this intelligence in Q1–Q2 2026
-
Procurement leaders: Use the scenario models to rebalance supplier exposure before mid-year contract renewals; prioritize suppliers offering validated low-emission coatings and multi-year price hedges.
-
R&D and product managers: Launch two parallel pilots—one focused on environmentally preferable anti-fog chemistries and another on hybrid anti-fog/anti-scratch solutions—to de-risk product transitions while protecting legacy volumes.
-
Strategy and corporate development teams: Screen acquisition targets among coating specialists and regional fabricators to accelerate vertical capability acquisition without committing to brownfield expansions outright.
-
Regulatory and quality teams: Build cross-functional compliance playbooks that convert regulatory requirements into internal product acceptance thresholds and supplier audit protocols.
Final note — a preview, not the whole story
This commentary is crafted as a strategic preview: it outlines the major trends, competitive dynamics and pragmatic decisions that will determine market positions through 2026. In keeping with the “preview” purpose, this piece omits our full segmentation tables and company-level revenue and market-share data—analytics that are available in the complete PW Consulting study and its accompanying datasets.
Next steps
For procurement teams, product leaders and corporate development teams seeking the full suite of analytics—including downloadable models, supplier scorecards and regulatory roadmaps—contact PW Consulting to access the full Anti-Fog Polycarbonate Film and Sheet Market report and workbook. Our analysts can also deliver a tailored briefing and a 90-minute workshop to translate the report’s scenarios into an actionable 2026 playbook for your organization.
For detailed analysis of this topic, please visit the official page: Anti Fog Polycarbonate Film And Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Automotive DSP Amplifier Market to Grow at a Robust 8.75% CAGR Through 2032
By pmarketresearch, 2026-07-13
Automotive DSP Amplifier Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
As OEMs, Tier‑1s, semiconductor suppliers and aftermarket specialists position themselves for the next phase of vehicle electrification and premium cabin experiences, PW Consulting’s latest Automotive DSP Amplifier Market study provides the prescriptive intelligence required to convert uncertainty into decisive action in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes market sizing, technology evolution, supply‑chain stress tests and competitive playbooks — enabling stakeholders to prioritize investments, partnerships and product roadmaps with confidence.
Automotive Dsp Amplifier Market
Macro trajectory: growth that demands strategic response
The DSP amplifier sector has transitioned from a niche premium segment into a mainstream enabler of immersive in‑vehicle audio and active cockpit experiences. Our topline model shows the global market expanding from approximately USD 1.85 billion in 2020 to roughly USD 2.98 billion in 2025, and continuing to grow through the forecast horizon to exceed USD 5.3 billion by 2032, at a compound annual growth rate (CAGR) of 8.75% across 2026–2032. This scale and momentum create both opportunity and structural challenges: margins will be sustained for differentiated players, while commoditization pressures will intensify for purely hardware-centric offerings.
Automotive Dsp Amplifier Market
Why this report matters for 2026 decisions
- Decision timing: Suppliers deciding on capacity expansion, semiconductor sourcing contracts, or strategic hires need a 12–18 month lead time. Our scenario‑based demand curves and supply‑constraint overlays convert market growth into concrete capacity and procurement timelines.
- Technology roadmap alignment: Whether to prioritize high‑efficiency Class‑D power stages, integrated DSP platforms, or multi‑channel modularity is a make‑or‑break choice. We map technology adoption vectors to vehicle segments and two implementation horizons (near‑term: 2026–2028; medium term: 2029–2032).
- Commercial strategy: The premiumization of in‑car audio creates recurring software and integration revenue opportunities. The report quantifies value pools for hardware, software licensing, calibration services and aftermarket upgrades — so commercial teams can design margin-accretive offerings rather than competing on price alone.
- M&A and partnerships: With a moderately concentrated supply base (CR3 ~42.5%, CR5 ~58.3%), the market favors bolt‑on acquisitions and strategic alliances. Our vendor heatmaps identify which segments are ripe for consolidation and which capabilities should be acquired versus developed in‑house.
What the report contains — actionable, executable intelligence
PW Consulting’s study was developed to be operator‑useful, not just academic. Highlights of the analytical toolkit provided include:
Automotive Dsp Amplifier Market
- Top‑down and bottom‑up market sizing with sensitivity analysis across three adoption scenarios (base, accelerated EV premium, and constrained supply).
- Multi‑dimensional forecast (2026–2032) that connects market value to vehicle production, trim penetration rates and per‑vehicle average selling price (ASP) trajectories.
- Vendor benchmarking: product portfolio mapping, go‑to‑market positioning, and technology capability scoring for leading players across OEM and aftermarket channels.
- Technology deep dives: Class‑D amplifier efficiency curves, digital input architectures, software stack requirements for real‑time DSP, and integration best practices for multi‑channel and active noise applications.
- Supply‑chain risk matrix: semiconductor node dependencies, raw material exposure (including rare earth risks), and mitigation pathways such as multi‑sourcing and buffer inventory strategies.
- Regulatory and qualification playbook: practical steps to meet AEC‑Q100 and functional safety expectations, plus recommended test and validation regimes for automotive‑grade audio components.
- Commercial playbook: pricing strategies for OEM bids, aftermarket warranty models, feature‑based monetization (e.g., sound signature packs, OTA DSP updates), and channel mix optimization.
- M&A screening framework: prioritized capability targets, valuation multipliers observed in the sector, and integration checklists for technology and go‑to‑market assimilation.
Competition and capability map: who matters and why
The competitive landscape is populated by a mix of specialized audio houses, established automotive electronics brands and semiconductor incumbents. Notable participants include Audiotec Fischer (Germany), Audison and Mosconi (Italy), Alpine Electronics (Japan), AudioControl and ARC Audio (USA), and semiconductor leaders such as STMicroelectronics, Texas Instruments, Analog Devices and NXP. Each brings a distinct strategic posture:
- Audiotec Fischer: recognized for high‑end DSP amplification and award‑winning products and software tools that cater to audiophile aftermarket customers and boutique OEM integrations.
- Audison and Mosconi: focused product roadmaps for compact, high‑performance DSP amplifiers that bridge aftermarket and OEM supplier demands.
- Alpine Electronics: leveraging Hi‑Res and Status‑level DSP platforms to support OEM differentiated audio packages and integrated cockpit initiatives.
- AudioControl and ARC Audio: strong in signal processing and pro‑audio feature sets attractive to premium OEM and aftermarket installers.
- Semiconductor suppliers (ST, TI, Analog Devices, NXP): driving foundational performance envelopes through integrated Class‑D drivers, DSP cores, and domain‑specific accelerators — increasingly blurring lines between software and silicon in audio subsystems.
Recent industry events underscore the pace and direction of innovation: Audiotec Fischer’s HELIX V EIGHT DSP ULTIMATE and associated PC software received independent recognition in 2025, signaling product and toolchain maturity in premium segments. Semiconductor vendors continue to launch automotive‑grade, high‑frequency Class‑D parts and advanced audio processors, reflecting OEM demand for higher efficiency, lower EMI and greater digital integration.
Market dynamics to watch in 2026
- Electrification as an accelerant: EVs change the acoustic baseline and enable new features (active sound design, bass compensation). Suppliers must align DSP roadmaps to exploit EV‑specific value pools.
- Supply constraints and rare earth exposure: Semiconductor volatility and material shortages persist through 2026; procurement strategies will determine who can reliably meet OEM serial timelines.
- Regulatory and qualification gatekeepers: Compliance with AEC‑Q100 and automotive functional safety is a non‑negotiable cost of entry. Early investments in qualification shorten time‑to‑production and reduce warranty risk.
- Software monetization and OTA lifecycles: The product is increasingly defined by software calibration and user experience. Companies that can deliver seamless OTA updates, tuning services and curated sound profiles command higher lifetime value.
- Consolidation pressure: With a CR3 of about 42.5% and CR5 near 58.3%, strategic consolidation is likely where mid‑tier manufacturers seek scale to compete on OEM contracts and global distribution.
Strategic imperatives for 2026 — an executive checklist
- Harden supply chains now: secure multi‑sourced contracts for key power ICs and DSP cores; incorporate rare‑earth substitution plans where feasible.
- Prioritize modular platforms: design architectures that allow feature‑additive upgrades (software‑defined DSP modules, channel expansion kits) to capture aftermarket upsell.
- Form semiconductor partnerships: co‑develop reference platforms with Tier‑1 or chip vendors to reduce integration risk and accelerate validation cycles.
- Embed software monetization: create licensing and OTA pipelines for sound profiles, adaptive tuning and premium audio subscriptions.
- Invest in qualification and test automation: reduce time‑to‑production for AEC‑Q100 and functional safety sign‑offs through in‑house or partner test rigs.
- Screen M&A targets tactically: focus on capabilities that close gaps (calibration software, cloud services, installation networks) rather than bolt‑on product SKUs alone.
What we don’t disclose here — and why you’ll want the full report
To preserve the trailer nature of this briefing, we are intentionally omitting granular regional, application and model‑level revenue splits that are essential for deal underwriting, production planning and pricing strategy. The full PW Consulting report includes these high‑resolution tables, vendor‑level revenue breakdowns, ASP trajectories by vehicle class, and downloadable data models that support bespoke scenario simulations — resources that many executives will find indispensable when finalizing 2026 budgets and capital allocations.
Concluding perspective
By 2026, the Automotive DSP Amplifier market will no longer be just an audio add‑on; it will be a differentiated pillar of the in‑vehicle experience stack, tightly integrated with infotainment, active noise management and even brand identity. Companies that treat this segment as a cross‑functional strategic initiative — combining resilient supply chains, modular hardware, monetizable software and disciplined compliance — will capture the most value as the market doubles in scale through the forecast horizon. PW Consulting’s report translates that strategic horizon into tactical steps, keyed to the timing and risk profile that matter to executives making 2026 commitments.
For access to the complete dataset, vendor scorecards, and executable playbooks referenced in this summary, visit the PW Consulting Automotive Research page or contact our client services team to schedule a briefing and data license. The detailed intelligence will accelerate decision certainty in a market where timing and integration expertise determine winners.
For detailed analysis of this topic, please visit the official page: Automotive Dsp Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: New Biomass Power Equipment Market Insight Forecasts 6.99% CAGR
By pmarketresearch, 2026-07-13
Biomass Power Equipment Market: Strategic Intelligence for 2026 Decision-Making
As energy transition priorities harden and decarbonization policies proliferate, biomass power remains one of the most actionable routes for utilities, project developers, and industrial energy consumers seeking dispatchable renewable baseload or combined heat-and-power (CHP) solutions. PW Consulting’s latest market study on the Biomass Power Equipment Market synthesizes macro trends, competitive positioning, technology pathways and investment-grade decision tools designed to inform capital allocation and go-to-market choices in 2026 and beyond.
Biomass Power Equipment Market
Market snapshot: scale, trajectory, and what it means for 2026
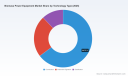
Our modelling traces the market’s trajectory from an estimated industry base of roughly $89.5 billion in 2020 to about $125.5 billion in 2025, driven by a blend of retrofit activity, new-build CHP projects and rising feedstock commercialization. The market is projected to expand further through the 2026–2032 forecast window at a compound annual growth rate of approximately 7%, reaching the low‑to‑mid hundreds of billions by the end of the period.
Biomass Power Equipment Market
For executives and investment committees eyeing 2026 as a pivotal planning horizon, three implications emerge immediately: (1) deployment windows remain open for large-scale equipment providers and modular gasifier suppliers as demand scales, (2) policy tailwinds create near-term subsidy and financing opportunities that can materially alter project economics, and (3) operational readiness — in the form of flexible fuel handling, grid integration and O&M competence — will differentiate winners from the pack.
Biomass Power Equipment Market
Why this report matters to corporate strategy in 2026
- Actionable sizing for capital planning. The report provides a consolidated market-size view and scenario-level revenue trajectories to calibrate capacity additions and supply-chain commitments for the next five to seven years.
- Policy and incentive modelling tied to project NPV. We translate major policy levers — from regional renewable targets to investment tax credits — into scenario outcomes that materially affect payback and IRR assumptions for projects initiated in 2026.
- Technology and feedstock risk assessment. Rather than high-level commentary, the study offers a hierarchical risk framework to quantify feedstock price exposure, combustion versus gasification pathway risks, and lifecycle carbon accounting sensitivities that are critical for financing decisions.
- Procurement and vendor selection playbooks. The report includes procurement checklists, contractual levers for lead‑time management, and vendor evaluation matrices that counsel on negotiated warranties, spare-parts pooling and performance guarantees.
Core growth drivers and headwinds (what to prioritize in 2026)
- Policy acceleration. Binding renewable targets and carbon pricing continue to tilt economics toward biomass in several jurisdictions. Where incentives (investment tax credits, feed-in premiums) are available, they compress payback timelines for projects started in the 2026 window.
- Carbon economics. Elevated carbon allowance prices increase the delta in operating cost between coal and biomass-fired assets; this drives conversion projects and coal-to-biomass retrofits where infrastructure permits.
- Feedstock and logistics risk. Feedstock availability and pricing volatility — for example, industry monitoring showed wood pellet benchmarks around the low hundreds of dollars per metric ton in late 2024 — remain a primary source of operating uncertainty and must be hedged via long-term contracts, diversified feedstock strategies or vertical integration.
- Capex and component constraints. Equipment and balance-of-plant components continue to command significant capital intensity; grate stoker systems and related plant modules exhibited multi‑million-dollar per-MW cost ranges in recent projects, affecting project sizing and financing structures.
Competitive landscape: what leading suppliers are doing
The supply side of biomass power equipment reflects a mix of large engineering groups delivering turnkey plants and specialist manufacturers catering to small-to-medium deployments. While the market retains a degree of fragmentation with meaningful opportunities for new entrants, incumbent capabilities around turnkey delivery, flue gas treatment, and turbine integration are decisive in large projects.
- Valmet (Espoo, Finland). Strengths: end-to-end CHP offerings and deep experience in fluidized bed and grate technologies. Strategic implication: its turnkey orientation makes it a candidate for utility-scale tenders and partner of choice where single-vendor responsibility is prioritized. Recent commissioning activity in Asia underscores its execution strength in export markets.
- ANDRITZ (Graz, Austria). Strengths: fluidized bed combustion expertise and project EPC capability. Strategic implication: attractive for projects that prioritize fuel flexibility and modular scalability; its order pipeline in Europe signals continued demand for medium-scale installations.
- Babcock & Wilcox (Akron, USA). Strengths: vibrating grate and hybrid stoker systems optimized for co-firing. Strategic implication: well positioned for operators seeking retrofit solutions where co-firing with coal or biomass blends is the transition path. Recent grid-connection milestones in the UK demonstrate commercial readiness.
- Mitsubishi Power (Yokohama, Japan). Strengths: integration of high-efficiency steam cycles and advanced combustion controls. Strategic implication: technology leader for projects targeting operational efficiency gains and emissions optimization; recent efficiency milestones indicate near-term tech maturation.
- Siemens Energy and GE Vernova. Strengths: turbine and generator technologies adapted to biomass plant specifics, plus control systems for variable fuel inputs. Strategic implication: preferred partners when integrating biomass generators into broader utility fleets or hybrid renewable portfolios.
- Regional specialists (e.g., Kraftwerke Mannheim, Zibo Zichai). Strengths: localized operational experience and small-to-medium scale gasifier manufacturing. Strategic implication: competitive choices for regionally specific projects where local supply chains and service networks matter.
Recent vendor activity — from Valmet’s 2024 commissioning in Japan to ANDRITZ’s orders and Babcock & Wilcox’s commercial grid connections — confirms active procurement windows and an appetite for proven, modular solutions. These vendor moves should influence procurement timetables for 2026 project pipelines.
What the report contains — practical, decision-ready outputs
- Executive dashboard and investment heatmaps. Quick-read views that rank markets and subsegments by near-term investability, policy support intensity and feedstock risk.
- Scenario economics and sensitivity models. Spreadsheet models that allow buyers to toggle carbon price, feedstock cost, capex and subsidy assumptions to produce project-level NPVs and IRRs.
- Vendor benchmarking and procurement templates. Scored matrices, RFP templates and contract clauses tailored to delivery and performance risk mitigation for boilers, turbines and gasifiers.
- Technology deep dives. Comparative analysis of combustion, anaerobic digestion and gasification pathways, with operational trade-offs, scaling vectors and maintenance profiles.
- Feedstock strategy playbook. Practical guidance on long-term offtake, co-processing options, pelletization economics and logistics optimization.
- Regulatory and carbon-policy tracker. A living annex summarizing major policy instruments and how they translate to cashflow impacts for projects initiated in 2026.
How to use this intelligence in 2026
- For corporate strategy teams: Use the scenario models to stress-test capital allocation choices under different subsidy and carbon-price regimes. Prioritize projects with flexible fuel capability if regulatory uncertainty is high.
- For project developers: Align procurement calendars with vendor lead times highlighted in the report; consider staged procurement to manage parts supply and commissioning risk.
- For investors and lenders: Apply the report’s standardized due-diligence checklist to evaluate off-take security, feedstock contracts and technology performance guarantees before term-sheet commitments.
- For equipment manufacturers: Use the competitive benchmarking to refine product roadmaps — efficiency improvements, lower O&M footprints and fuel-flexibility features deliver measurable differentiation.
Final perspective: a 2026 playbook
Biomass power equipment is entering a phase where policy tailwinds, carbon economics and technology maturation combine to create discrete windows of commercial opportunity. Projects that secure feedstock, lock-in favorable incentive structures, and partner with vendors that can guarantee delivery and performance will enjoy superior economics. Conversely, projects that neglect feedstock diversification or underestimate component lead times face the dual risk of cost overruns and missed revenue windows.
PW Consulting’s Biomass Power Equipment Market report is designed as a practical, transaction‑oriented toolkit for 2026 decision-makers — combining market sizing, scenario economics, vendor intelligence and procurement instruments. The public summary conveys the directional growth case and strategic implications; the full report includes the granular segmentation, downloadable financial models and vendor scoring that underpin defensible capital decisions.
Next steps
Stakeholders ready to convert strategic insight into action are invited to review the full research package for complete segmentation data, the detailed vendor scorecards and the ready-to-use financial models. Access to these materials will enable CFOs, strategy leads and project developers to move from directional conviction into executable project timelines for 2026.
For detailed analysis of this topic, please visit the official page: Biomass Power Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Recovered Carbon Black Market Poised to Reach USD 1,539.4 Million by 2032 at 11.5% CAGR, Led by Tire Manufacturing and Europe
By pmarketresearch, 2026-07-13
Recovered Carbon Black (rCB) Market — Strategic Briefing for 2026 Decision-Makers
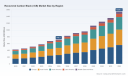
PW Consulting’s latest Recovered Carbon Black (rCB) Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) crystallizes why rCB will move from niche sustainability story to a commercially material input for rubber, plastics and specialty applications. Our modeling shows the rCB market continuing a robust compound annual growth rate (CAGR) of 11.5% through the 2026–2032 forecast window, with the global market already exceeding the three‑quarter billion mark in the 2025 base year and projected to more than double by the early 2030s in USD terms. For executives preparing 2026 budgets and three‑to‑five year strategic plans, the report converts macro momentum into practical next steps: where to secure feedstock, how to structure offtake and certification clauses, and which technology and partnership choices most directly de‑risk commercialization.
Recovered Carbon Black Rcb Market
Why this report matters for 2026 strategic planning
-
Actionable timing: 2026 is a pivot year. The industry has moved past pilot plants and demonstration runs; several commercial facilities have come online and will materially affect available supply and pricing dynamics in short order. Our forecast and scenario modules translate these capacity shifts into implications for procurement, pricing and margin capture.
Recovered Carbon Black Rcb Market -
Policy-commercial convergence: regulatory classifications and voluntary sustainability standards are converging to create credible commercial pathways for circular carbon products. Companies that wait for perfect clarity risk losing access to the best feedstock, premium customers, and collaborative incentives.
Recovered Carbon Black Rcb Market -
Investment readiness: whether you are an OEM, tire maker, compounder, or investor, the report provides the financial and operational templates needed to size and stress-test rCB projects under realistic price, feedstock and quality constraints.
Key market dynamics shaping 2026 decisions
-
Growth trajectory and scale: The rCB market has expanded rapidly in the last half‑decade and our base‑to‑forecast modeling shows sustained high‑teens to low‑double‑digit growth rates across the medium term. This is driven by feedstock availability, policy support in major markets, and industrial adoption curves — particularly in tire reinforcement and non‑tire rubber compounds.
-
Feedstock and price signals: Scrap tire availability is abundant but not costless. Recent data points show upward pressure on scrap tire pricing in major markets as recycling demand increases. Procurement strategies that lock in secure supply and integrate logistics will have a distinct advantage.
-
Regulatory enablers: In key jurisdictions, classification of tire pyrolysis outputs as recovery rather than waste allows rCB to enter commercial supply chains – enabling resale, traceability and the application of sustainability credentials. Parallel to regulation, voluntary certification frameworks (such as ISCC PLUS) are rapidly becoming a prerequisite for premium placements.
-
Certification and product differentiation: ISCC PLUS and similar mass‑balance approaches are establishing pathways for traceability and sustainability claims. Early adopters who align production process, mass balance accounting and third‑party certification can command better access to sustainability‑conscious offtakers.
-
Quality ceiling: Technical limitations remain. rCB typically exhibits a lower carbon purity range than the highest‑grade virgin carbon black; this constrains immediate substitution in the most performance‑sensitive applications (for example, some high‑end tire treads). The report’s technical appendix examines the current purity band and practical blending strategies to maximize market penetration without compromising product integrity.
-
Market concentration and competitive posture: The rCB market is neither highly fragmented nor tightly consolidated. A handful of technology‑led producers account for a meaningful share of capacity and influence pricing and technical benchmarks. This creates both opportunities for strategic partners and a rationale for scale investments by incumbents.
Competitive landscape — who to watch (and why it matters)
-
Pyrolyx AG (Germany) — An early mover with commercial pyrolysis capability. Pyrolyx’s transition from pilot to commercial scale means more predictable supply for European offtakers and provides a reference for industrial‑scale quality equivalence with traditional carbon black grades. Recent capacity expansion signals that the company is positioning to be a long‑term supplier to both tire and industrial rubber markets.
-
Black Bear Carbon B.V. (Netherlands) — Backed by a major OEM, Black Bear’s industrialization efforts reflect the strategic interest of large manufacturers in securing circular inputs. Its developments indicate how OEM partnership and sponsorship can accelerate technology de‑risking, create preferential offtake arrangements, and shift bargaining power toward certified, high‑purity rCB producers.
-
Enviro AB (Sweden) — Certification achievements highlight the premium associated with independently verified sustainability claims. Enviro’s ISCC PLUS certification is an operative example of how traceability credentials can unlock certain customer segments and justify price differentials for certified material.
-
Hi‑Green Carbon Limited (India) — Represents the drive to scale pyrolysis-driven rCB production in high‑demand, cost‑sensitive markets. Domestic policy levers (taxes, import duties) create unique trade flows that regional players must navigate; Indian producers will have a cost‑competitiveness angle, tempered by local taxation and logistics nuances.
Recent development signals and strategic implications
-
Commercial plant openings and capacity ramps are no longer hypothetical. When commercial plants reach industrial throughput, buyers will need to move from purchasing spot shipments to negotiating multi‑year offtake and quality‑assurance contracts.
-
Certifications are becoming a market entry fee for higher‑value channels. Producers that cannot demonstrate traceability and sustainability accounting will find themselves restricted to lower‑value, price‑sensitive segments.
-
Supply influx from new plants will create transient price volatility. Buyers with flexible procurement strategies and blending capabilities can capture value during supply gluts; producers without offtake agreements face margin compression.
What the PW Consulting report delivers — practical, executable content
-
Market sizing with scenario analysis: Base, upside and downside demand curves across the 2026–2032 window, with clear levers that materially impact outcomes (feedstock cost, certification uptake, substitution rates).
-
Commercial playbooks: Negotiation templates for multi‑year offtake, recommended contract provisions (quality tolerances, certification clauses, feedstock traceability, penalty and make‑good terms), and pricing indexation options to hedge feedstock volatility.
-
Technical and application guidance: Grade benchmarking, blending strategies to extend rCB use into higher‑performance applications, and material testing roadmaps for OEM qualification.
-
CapEx/Opex modelling: Unit economics for greenfield and brownfield rCB projects, sensitivity analyses and payback timelines under multiple feedstock and sales price scenarios.
-
Supply‑chain and logistics playbook: Sourcing maps, collection network design, inventory strategies and recommended partner archetypes (aggregators, toll processors, logistics integrators).
-
M&A and partnership frameworks: Value creation pathways for investors, strategic buyers and technology licensors — including earn‑out structures and JV models that align incentives across the value chain.
-
Risk matrix and mitigation strategies: Regulatory, technical, market and reputational risks with prioritized actions and contingency triggers for 2026 planning cycles.
How to use the research in your 2026 planning cycle
-
Procurement: Implement a staged sourcing strategy that secures feedstock and offtake for the near term while retaining optionality to scale into higher volumes as product qualifications complete.
-
R&D & Quality: Invest in blending and compound testing to maximize substitution without compromising performance. Prioritize ISCC or equivalent certification if targeting premium channels.
-
Manufacturing & CapEx: Stage capacity expansion decisions to coincide with verified demand commitments from OEMs and compounders. Early movers should prioritize modular designs to manage technological uncertainty.
-
Corporate strategy: Consider strategic partnerships with technology providers and certified producers to accelerate market entry and reduce time‑to‑qualification.
FAQ — key constraints and how to address them
-
Is rCB a full substitute for virgin carbon black? Not yet. rCB purity typically falls below the top performance range of virgin carbon black, which restricts immediate one‑for‑one substitution in the highest‑stress tire treads. The practical remedy is strategic blending and route‑to‑qualification programs targeting non‑tread and secondary rubber markets first.
-
How material are trade and tax barriers? They matter. Regional tax regimes (for example, import duties or GST treatments in some markets) will meaningfully affect cross‑border flows and should be baked into trade and sourcing scenarios.
-
Do certifications matter commercially? Yes. ISCC PLUS and equivalent certifications are increasingly a commercial prerequisite for premium contracts and OEM sustainability claims.
Closing and next steps
PW Consulting’s rCB Market report converts a clear macro growth story into a practical, executable intelligence product for 2026 decision‑making. We combine market sizing, competitive benchmarking, technical guidance and commercial playbooks so that procurement leads, product engineers, and corporate development teams have a common, actionable view of risk and opportunity.
In keeping with our “trailer” approach, we have showcased the strategic contours and practical uses of the intelligence in this briefing while withholding the granular regional and application splits and company‑level capacity tables that are central to transaction execution. For the full dataset, interactive models, and downloadable negotiation templates, please visit the PW Consulting report page to access the complete Recovered Carbon Black Market report and supporting annexes.
For detailed analysis of this topic, please visit the official page: Recovered Carbon Black Rcb Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Targeted Drugs for Multiple Myeloma Market Reaches USD 25,850 Million in 2025, Forecasted to Grow at a 6.45% CAGR Through 2032
By pmarketresearch, 2026-07-13
Targeted Drugs for Multiple Myeloma: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
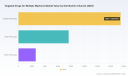
PW Consulting’s forthcoming market research on targeted drugs for multiple myeloma synthesizes clinical progress, regulatory inflection points, reimbursement trends, and competitive positioning into a single decision-grade resource for life-science executives, investors, and payers planning activity in 2026. The global market, measured in USD million, has demonstrated resilient expansion through the mid-2020s and — under our base forecast assumptions — is set to continue growing at a mid-single-digit compound annual growth rate (CAGR) across the 2026–2032 horizon. This preview highlights the strategic value of the full report without disclosing the proprietary, transaction-sensitive segment detail readers will find in the paid study.
Targeted Drugs For Multiple Myeloma Market
Market trajectory and what it means for 2026
Multiple myeloma has shifted from a disease treated primarily with broad cytotoxic and backbone agents toward one increasingly dominated by targeted modalities: monoclonal antibodies, bispecific antibodies, CAR-T therapies, antibody–drug conjugates (ADCs), proteasome inhibitors, and novel oral targeted agents. By 2025 the total market reached a mature scale that supports differentiated specialty launches and novel combination strategies. Our modeling — using a 2026–2032 forecast window — anticipates steady, structurally supported growth driven by continued label expansions, uptake of off-the-shelf bispecifics, expanded CAR-T access, and shifting reimbursement approaches that increasingly tie approval and payment to surrogate endpoints such as minimal residual disease (MRD) negativity.
Targeted Drugs For Multiple Myeloma Market
For corporate strategists, the near-term takeaway is clear: 2026 decisions will center on sequencing, combination economics, and access pathways rather than pure volume expansion alone. Companies that can align clinical positioning with payer-validated endpoints and that optimize route-to-market costs for cellular and bispecific platforms will capture disproportionate commercial share.
Targeted Drugs For Multiple Myeloma Market
Competitive dynamics — who is moving the market and why it matters
-
Large biopharma incumbents remain dominant, with a concentrated top tier that continues to shape prescribing patterns and standards of care. Market concentration metrics show that the leading three and five firms hold the majority of realized revenue, creating both a barrier and an opportunity for newer entrants that offer clear differentiation.
-
Strategic product portfolios span mature monoclonal antibodies and proteasome inhibitors to next-generation oral CELMoDs, bispecific T-cell engagers, CAR-T constructs, and ADCs. Recent regulatory events have further rebalanced competitive dynamics: a leading company secured approvals for a bispecific in combination with an established CD38 monoclonal antibody, while other players announced positive Phase 3 results for next‑generation oral agents. These milestones accelerate the shift toward earlier use of novel targeted combinations and increase the clinical importance of tolerability and real-world manageability.
-
Fast-moving modality convergence — where companies combine or bundle CAR-T, bispecifics, antibodies, and oral agents into clinically rational sequences — will determine mid-decade winners. Firms able to protect margin through manufacturing scale, service differentiation (e.g., patient monitoring, REMS simplification adoption), and compelling combination data will command premium pricing and preferential formulary placement.
Regulatory and reimbursement inflection points shaping 2026 strategies
Regulatory authorities have tightened the link between surrogate endpoints and accelerated pathways while simultaneously offering clearer guidance on acceptable endpoints. In particular, acceptance of MRD negativity in the context of accelerated approvals changes both clinical development strategy and commercial expectations; companies can pursue shorter paths to market for certain regimens but must be prepared to demonstrate long-term benefit in pooled or confirmatory analyses.
Concurrently, safety- and monitoring-related regulatory simplifications for some cellular therapies (including reduced REMS obligations based on real-world safety evidence) materially lower the operational friction and cost of CAR-T deployment. These shifts create a more favorable reimbursement backdrop for complex therapies, but payers remain exacting — demanding health-economic justification for durable responses and real-world survivorship gains.
Patent cliffs, pricing pressure, and the response playbook
Generic entry for older backbone drugs will continue to exert pressure on combination economics and profit pools. Where a legacy agent becomes less costly, manufacturers of novel targeted therapies must re-evaluate price-setting, rebate strategies, and bundle offers that include diagnostics or services. Our full report models a range of pricing and access scenarios, showing how generic erosion catalyzes both downside risk for incumbents and opportunity for novel agents that demonstrably improve depth of response or time-to-next-therapy.
Modality-specific considerations for corporate planning
-
Bispecific antibodies: Rapid approvals and commercial uptake put a premium on outpatient logistics, dosing schedules, and demonstrable real-world safety. Market entrants should prioritize simplified delivery and strong safety management programs to gain rapid formulary traction.
-
CAR-T therapies: Reduced monitoring requirements and streamlined REMS increase scalability, but manufacturing capacity, cost-per-treatment, and center accreditation remain gating factors. Strategic partnerships with contract manufacturers and hub-and-spoke delivery models are critical near-term priorities.
-
Oral next-generation targeted agents (CELMoDs and others): Positive Phase 3 data for oral agents expands late-line options and creates pressure for head-to-head positioning versus biologics in certain niches. Companies should invest in biomarker strategies and adherence programs to safeguard real-world effectiveness.
-
ADCs and other targeted therapies: Regional approvals and combination approvals are creating niche pockets of opportunity — particularly where tolerability profiles support long-term dosing in maintenance settings.
What PW Consulting’s report contains — practical assets for 2026 decision-makers
Our full market study is designed as an operational playbook with the following deliverables:
-
Robust market-sizing and forecasting model (2020–2032) with scenario functionality to stress-test outcomes under different clinical, regulatory, and pricing assumptions. Users can run custom scenarios for launch timing, uptake, and price elasticity.
-
Competitor intelligence modules that synthesize clinical trial readouts, recent approvals, pipeline timing, and strategic intent for leading firms. These modules include SWOT-style implications for commercialization and M&A.
-
Commercial playbooks for each modality (bispecifics, CAR‑T, monoclonal antibodies, CELMoDs, proteasome inhibitors, ADCs), covering access strategies, stakeholder engagement maps, and payer negotiation scripts tailored to current MRD-focused reimbursement frameworks.
-
Deal origination and valuation matrices prioritizing licensing, bolt-on acquisition targets, and manufacturing partners; our valuation sensitivities capture the impact of generic entry, label expansions, and accelerated approval conversion requirements.
-
Health‑economic models and country-level reimbursement pathways (coverage decision timelines, HTA submission templates, and price/volume levers) — with clear recommendations on evidence generation required to secure favorable coverage in 2026.
-
Go-to-market readiness checklists for commercial and medical teams, including patient support design for high-touch therapies and digital health options to optimize adherence and outcomes.
How 2026 decisions should change based on our analysis
-
Prioritize combination strategies that align with MRD-driven endpoints. Given regulatory emphasis on MRD, companies should design pivotal combinations and confirmatory plans that address both accelerated approval criteria and payer evidence requirements.
-
De-risk launches through service-led differentiation. For high-cost modalities, the path to formulary acceptance runs through demonstrated reductions in total cost of care, predictable safety profiles, and scalable patient support that lowers real-world complication rates.
-
Pursue manufacturing and commercial partnerships proactively. Capacity constraints for cell therapies and the need for geographic reach favor strategic alliances or M&A focused on fill/finish and cold-chain logistics.
-
Use flexible valuation frameworks. The interplay of generic backbone erosion, accelerated approvals, and real-world evidence conversion creates valuation upside — and downside — that must be modeled dynamically for 2026 M&A decisions.
Why this preview — and why now
We publish this preview to surface the strategic contours that will matter for 2026 while withholding granular, commercially sensitive segment breakouts that are included in the full report. The combination of ongoing approvals, regulatory guidance around MRD, simplification of monitoring for selected cellular therapies, and the timing of generic entry for legacy agents creates a compressed decision window: execute now on evidence generation, manufacturing scale, and payer alignment or accept materially higher barriers to entry after key approvals and formularies harden.
Next steps
For pharmaceutical and biotech executives planning near-term launches, investors evaluating M&A targets, or payer organizations preparing coverage frameworks, PW Consulting’s complete report provides the actionable forecasts, competitor playbooks, and reimbursement strategies required to convert clinical innovation into commercial success in 2026 and beyond. Visit our publication page to access the full study and the executable models that underpin our forecasts.
For detailed analysis of this topic, please visit the official page: Targeted Drugs For Multiple Myeloma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.5% CAGR for High‑Purity Tungsten Market Through 2032
By pmarketresearch, 2026-07-13
High Purity Tungsten Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting today publishes a forward-looking market study on High Purity Tungsten that translates raw market dynamics into executable strategy for corporate leaders preparing for 2026. Built on a six‑year historical base (2020–2025) and a seven‑year forecast horizon (2026–2032), the report synthesizes supply, demand, pricing and regulatory inflection points into a single actionable playbook. Our objective is simple: give executives the clarity they need to make high‑stakes choices this year—capacity investments, supply‑chain design, M&A and commercial negotiation—while preserving proprietary granularity for subscribers.
High Purity Tungsten Market
Why 2026 is a Decision Year
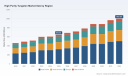
High purity tungsten is at the intersection of geopolitics, upstream raw‑material volatility and technology‑driven demand. PW Consulting’s topline market model shows the global industry expanding from the mid‑hundreds of millions (USD, revenue basis) in 2020 to roughly USD 645 million in 2025, before proceeding to just over USD 1.0 billion by 2032—implying a compound annual growth rate of approximately 6.5% through the forecast period. That steady, above‑trend growth masks episodic shocks (pricing spikes, export controls, tariff actions) that materially affect commercial outcomes in 12–18 month windows. Our report isolates those shocks and translates them into practical decision options for 2026.
High Purity Tungsten Market
What the Report Delivers (Operationally Focused)
- Supply‑chain diagnostics: A layered map of feedstock flows (APT and oxides), reduction and downstream finishing, highlighting bottlenecks and points of leverage for buyers and producers alike.
- Scenario modelling: Three plausible market paths (baseline, constrained‑supply, demand‑surge) with trigger points and contingency playbooks that quantify margin and working capital sensitivity.
- Price and inventory playbooks: Tactical hedging approaches and inventory ladders calibrated to current APT and oxide volatility, including break‑even analyses for forward buying versus just‑in‑time procurement.
- Project and capacity prioritization: A framework for evaluating greenfield and brownfield expansions—including cash‑flow modeling, payback bands and priority gating for 2026 CAPEX.
- Competitive and M&A playbook: Screening criteria for targets and partners, valuation heuristics for tungsten assets, and integration checklists tailored to high‑purity production.
- Regulatory and geopolitical watchlist: Country‑level policy scenarios, tariff and export control matrices, and recommended advocacy strategies for producers and industrial users.
- Supplier scorecards and technical benchmarks: Comparative assessments of commercial producers across technical purity, vertical integration, geographic resilience and customer service metrics.
Market Dynamics—Key Themes Every Executive Must Track
- Supply tightness and input cost pressure. Raw feedstock volatility has re‑emerged as a central value driver. Market indicators show significant price appreciation in key intermediates across 2025–early 2026, and Rotterdam and domestic benchmarks both reflected material upward movements during the period. For procurement teams, this shifts the calculus on forward purchase commitments and justifies new tender structures.
- Trade policy as a supply management lever. Recent trade actions—including higher tariffs and export controls enacted by major consuming and producing countries—are no longer hypothetical. These instruments have already begun to reshape arbitrage flows and increase the value of near‑sourced capacity for sensitive end markets.
- Geographic rebalancing of primary supply. New mine starts and advanced exploration projects in multiple jurisdictions are changing long‑term mine supply expectations, but lead times and permitting timelines mean near‑term relief is limited. Policymakers’ industrial strategies (including strategic funding) are shortening development cycles for certain projects, a dynamic that buyers and investors must anticipate.
- Consolidation and concentration. The high purity tungsten market exhibits moderate concentration: top tier manufacturers capture a meaningful share of global revenue, and an expanded cohort of mid‑tier specialists serve niche purity, form and supply‑security needs. This structure creates windows for strategic partnerships while also reinforcing pricing power for well‑integrated incumbents.
Competitive Landscape — Who Matters and Why
Our competitive mapping profiles global manufacturers with differentiated strategic positions: fully integrated producers with upstream reduction capability; specialist powder makers focused on ultra‑high‑purity grades; and multinational refractory‑metals groups that combine materials depth with global distribution channels. Key players analyzed in the report include long‑standing manufactures in North America, Europe and East Asia, as well as major conglomerates and regional champions. Each profile includes operational footprints, technology strengths, and a calibrated view on partner or acquisition fit for different buyer archetypes.
High Purity Tungsten Market
- Profiles of major integrated manufacturers: Our assessment details how integration from APT/oxide reduction to finished mill products creates margin resiliency and supply security, and identifies which asset archetypes are most attractive for mid‑market consolidators.
- Independent specialists and niche suppliers: We examine the technical differentiation that enables suppliers to capture premium pricing—purity control, particle engineering, and form factor expertise (targets, sputtering materials, wires and rods).
- Concentration metrics: The market exhibits mid‑range concentration among the largest vendors—enough to affect negotiation dynamics but not so concentrated as to prevent new entrants with the right technical or geographic play.
Note: The report contains company‑level scorecards and anonymized supplier benchmarking that reveal negotiating levers and supplier risk profiles—intentionally withheld here to preserve the premium value of the full dataset.
Regulatory & Geopolitical Drivers to Watch in 2026
- Export controls and tariffs. Recent policy shifts have already disrupted traditional routing and increased landed costs for some buyers. The interplay between export licensing and trade remedy tools is now a core input to sourcing strategies.
- Strategic industrial funding. Several jurisdictions are deploying funding mechanisms to accelerate domestic tungsten project development; these interventions shorten development lead times for a subset of projects and change the timing of future supply additions.
- Environmental permitting and community interface. Local permitting outcomes remain a gating risk for greenfield projects; developers with robust stakeholder strategies materially de‑risk schedules and value.
Recent Market Signals (What Our Watchlist Flagged)
- Project advancement and resource activity in multiple jurisdictions signaled stronger developer confidence and a re‑rating of medium‑term mine output.
- Notable policy actions on trade and export licensing have already compressed arbitrage and pushed buyers to formalize resilient sourcing strategies.
- Raw material benchmarks recorded sharp moves in 2025–early 2026, reinforcing the premium for secure offtake and integrated conversion capacity.
Our research team maintains a living timeline of these events and their modeled impact on mid‑term pricing and availability—an asset included with the full report subscription.
Actionable Recommendations for 2026
- For producers: prioritize staged capacity expansion with offtake‑backed financing. Focus first on modular units that reduce technical execution risk and allow rapid scale‑up should demand accelerate.
- For industrial buyers: develop a layered sourcing strategy that blends strategic long‑term contracts, secured offtake with creditworthy upstream partners, and a calibrated inventory cushion tied to demand‑sensitivity thresholds.
- For investors and private equity: screen targets for both technical differentiation (high‑purity process IP) and vertical integration potential; value accretion comes fastest where integration reduces feedstock exposure or creates proprietary customer solutions.
- For governments and policymakers: design permitting timelines and funding mechanisms that shorten but do not preempt rigorous environmental and community engagement—successful projects will be those that secure social license as well as capital.
How This Report Helps You Make Better Choices in 2026
PW Consulting’s High Purity Tungsten report converts complex, often noisy signals into discrete strategic moves. It does so by combining a transparent quantitative model (historical calibration 2020–2025; forecast 2026–2032) with qualitative intelligence—company diagnostics, policy mapping and scenario playbooks. The product is not a collection of static numbers: it is an executable plan for decisions that materially affect margin, supply continuity and strategic optionality in 2026.
To preserve the commercial integrity of our analysis and encourage executive engagement, this release intentionally omits granular regional and application split tables and company‑level proprietary metrics. These data are included in the full report and the interactive dashboard, which provide drill‑downs to support negotiation, M&A diligence and procurement optimization.
Next Steps & Access
Executives preparing 2026 budgets, procurement cycles or capital allocation plans should consider the report a decision‑support system rather than background reading. Subscribers gain access to the full dataset, downloadable scenario models, supplier scorecards and a confidential advisory session with PW Consulting’s metals & materials team to translate findings into an implementation timeline.
For more information on the report contents, licensing options and subscription access to the interactive model, please visit our website or contact PW Consulting’s industry practice. Our team can provide bespoke briefings tailored to executive, commercial and technical audiences.
For detailed analysis of this topic, please visit the official page: High Purity Tungsten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Millimeter-Wave Radar for Unmanned Driving Market to Expand at 19.7% CAGR — From USD 16.43B in 2025 to USD 48.73B by 2032
By pmarketresearch, 2026-07-13
Millimeter Wave Radar For Unmanned Driving Market — Strategic Briefing for 2026
PW Consulting presents a high-conviction executive briefing derived from our forthcoming Millimeter Wave Radar For Unmanned Driving Market report. Built for boardrooms, corporate strategy teams, and senior product leaders weighing investment or partnership choices in 2026, this note synthesizes the macro trajectory, competitive dynamics, and the practical decision levers that will shape winners and losers in the next phase of automotive autonomy.
Millimeter Wave Radar For Unmanned Driving Market
Market Trajectory: A rapid, but non-linear, growth story
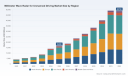
The mmWave radar market for unmanned driving has moved from niche sensing to a core enabler of automated mobility. Our base-year assessment (2025) places the global market at USD 16,430.0 Million, following a compound annual growth rate (CAGR) of 19.7% over the historical 2020–2025 period. The market expands further under our central forecast through 2030, reflecting accelerating adoption across ADAS tiers and early unmanned platforms, with a projected peak in the broader forecast window before near-term normalization as technology maturates and price erosion takes hold.
Millimeter Wave Radar For Unmanned Driving Market
For 2026 decision-making, the headline is simple: volume and value expansion continue, but the path is conditioned heavily by supply-side capacity, regulatory timing, and the competitive moves of a concentrated supplier base. In short, the opportunity is large; the window to shape platform-level requirements and supplier economics is short.
Millimeter Wave Radar For Unmanned Driving Market
Why the report matters to executives in 2026
- Timing of procurement and integration decisions: With production milestones and giga-scale series orders emerging, procurement teams must align multi-year sourcing to avoid costly rework or single-source exposure.
- Technology differentiation: Advances in SoC-level processing, 4D imaging radar, and digital-on-chip approaches are reshuffling which suppliers can convert trials into mass production.
- Regulatory and spectrum risk: Mandates on active safety features and heterogenous regional spectrum allocations require scenario-driven product roadmaps and geo-specific deployment plans.
- Supply chain resilience: Semiconductor availability and RF manufacturing capacity remain primary bottlenecks; strategic inventory and supplier development will materially impact time-to-market.
What PW Consulting’s report delivers (practical contents)
The published study is engineered for operations and strategy execution, not only market commentary. Key actionable modules include:
- Transparent market sizing and a reproducible forecast model (2026–2032) with scenario toggles for supply disruption, regulation shifts, and pricing pressure.
- Supply chain map and sourcing heatmap highlighting chokepoints across RF MMIC, front-end assemblies, and test & calibration capacity.
- Technology deep-dives — performance trade-offs between legacy frequency bands and emerging high-resolution 4D imaging approaches, with integration guidance for sensor-fusion stacks.
- Competitive playbooks with capability matrices, OEM win themes, and supplier readiness checklists for pilot-to-production scale-up.
- Commercial models — pricing elasticity, expected ASP trends, and tender negotiation frameworks tuned for 2026 procurement cycles.
- M&A and partnership targeting framework mapping strategic targets to capability gaps (radar SoC IP, production tooling, perception software).
- Regulatory and spectrum impact scenarios that translate policy timelines into revenue and launch-risk metrics.
Competitive landscape — concentrated but dynamic
The mmWave radar ecosystem is meaningfully concentrated: our concentration metrics indicate that the top three suppliers account for nearly half of market share (CR3 ~48.5%), and the top five approach two-thirds of the market (CR5 ~62.8%). That structure produces a dual dynamic—large incumbents move supply curves and set industrial standards, while aggressive specialists drive disruptive technology adoption.
Profiles and strategic takeaways for leading players:
- Robert Bosch GmbH (Gerlingen, Germany): Strong in SoC-level solutions, Bosch’s SX600/SX601 family demonstrates an integrated approach—combining radar signal processing with AI inference on-chip. Strategic implication: incumbents with SoC IP are positioned to capture higher-value system content if integration paths with perception software are secured early.
- Continental AG (Hanover, Germany): Continental’s 6th-generation ARS620 program has reached large-scale production milestones and has secured multi-year series orders. Strategic implication: suppliers controlling production scale and tiered pricing can squeeze smaller entrants unless differentiation on resolution or cost is compelling.
- Denso Corporation (Kariya, Japan): Focused on long-range detection and robust sensor fusion. Strategic implication: OEMs targeting highway automation and urban robotaxi corridors will prioritize suppliers with proven long-range performance and integration support.
- Valeo, HELLA, Aptiv, ZF: These tier-one integrators offer modular radar modules and system-level integration, making them natural partners for vehicle manufacturers seeking turnkey sensing stacks.
- Arbe Robotics & Uhnder: Newer entrants specializing in 4D imaging and digital radar-on-chip are proving disruptive in perception stacks, showcased at industry events and early partnerships. Strategic implication: platform owners should pilot imaging radar for edge-case detection while validating mass-production economics.
- Texas Instruments & Infineon: As core semiconductor suppliers, they remain critical for roadmap certainty. Strategic implication: locking long-lead agreements with chip-level suppliers is a material hedging instrument against supply volatility.
Recent signals that should shape 2026 strategy
- Major production milestones and series orders from top suppliers are compressing time-to-market expectations for OEMs and Tier-1s; alignment on standards and interface definitions is urgent.
- New SoC launches and co-development partnerships (notably between leading semiconductor vendors and traditional automotive suppliers) are accelerating feature parity across supplier classes.
- Regulatory mandates for active safety and regional spectrum licensing timelines will create heterogenous deployment windows—requiring geographically differentiated commercialization plans.
- Persistent semiconductor supply and skilled RF labor shortages increase the value of localized manufacturing and supplier diversification strategies.
Strategic recommendations for 2026 decision-makers
- Adopt a phased supplier engagement model: secure capacity with incumbents for baseline volumes while contracting pilot slots with specialist imaging-radar firms to validate edge-case performance.
- Negotiate chip and module agreements with explicit escalation and penalty clauses tied to spectrum/regulatory delays; prioritize suppliers with multi-node fabrication or alternative silicon pathways.
- Invest in sensor-fusion middleware and perception validation frameworks now—hardware differentials narrow quickly; software-defined advantages persist longer.
- Prioritize talent and automation investments in RF test and calibration; these are the operational enablers of quality at scale and a hedge against labor scarcity.
- Embed regulatory scenario planning into product launch gates—spectrum allocation or mandate timing can shift go-to-market by quarters, not weeks.
- Use an M&A playbook to acquire niche capabilities (4D imaging IP, radar SoC design houses, or specialized test equipment suppliers) rather than attempting in-house greenfield builds under time pressure.
Risks to monitor and leading indicators
Key risks that should be tracked continuously include semiconductor availability, spectrum allocation outcomes in priority markets, and the cadence of OEM series adoption announcements. Leading indicators we monitor weekly are supplier-volume commitments, fab utilization rates for high-frequency processes, regulatory docket movements on radar spectrum, and integration wins announced by OEMs and robotaxi platforms.
Conclusion — why engage with the full study
This briefing highlights the strategic inflection points executives must act on in 2026: the market’s growth trajectory is substantial, consolidation and technology races are accelerating, and the margin for execution error is shrinking. PW Consulting’s full report supplies the operational-level analyses, procurement templates, modeled scenarios, and supplier scorecards required to convert strategic intent into measurable outcomes.
For deployment-ready insights — including granular regional and application segmentation, supplier-level commercial benchmarks, and our interactive forecasting model — access the complete Millimeter Wave Radar For Unmanned Driving Market report at PW Consulting. The publicly released briefing intentionally omits detailed subsegment tables and contract-level intelligence to preserve client differentiation; the full dataset and playbooks are available to licensed subscribers and corporate clients.
For detailed analysis of this topic, please visit the official page: Millimeter Wave Radar For Unmanned Driving Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Emergency Rescue Drone Market to More Than Double from USD 312.5 Million in 2025 to USD 710.12 Million by 2032, Fueled by a 12.45% CAGR
By pmarketresearch, 2026-07-13
Emergency Rescue Drone Market: Strategic Playbook for 2026 — PW Consulting Industry Brief
Executive snapshot
The emergency rescue drone market is no longer a niche adjunct to traditional first-responder capabilities — it is a core operational capability reshaping how agencies, NGOs, and private emergency services prepare for and react to crises. Our latest PW Consulting market study — anchored on a base year of 2025 with a historical window covering 2020–2025 and a forward-looking forecast through 2032 — synthesizes commercial adoption, technology maturation, regulatory inflection points, and procurement realities into an actionable intelligence package for 2026 decision-makers.
Emergency Rescue Drone Market
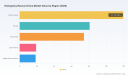
Key macro context: measured in USD (Million), the market expanded from USD 142.35 Million in 2020 to USD 312.50 Million in 2025. Under current assumptions, PW Consulting forecasts growth to USD 710.12 Million by 2032, reflecting a compounded annual growth rate (CAGR) of 12.45% across the 2026–2032 forecast window. Market structure remains moderately concentrated, with the three largest players accounting for a material share of industry revenues and the top five capturing a clear majority — dynamics that materially affect competitive strategy, supplier selection, and M&A calculus.
Emergency Rescue Drone Market
Why 2026 is a strategic inflection point
-
Regulatory alignment is unlocking scale. Government and public-safety adoption has moved from experimental to programmatic. Recent policy developments — including streamlined processes for Drone as First Responder (DFR) deployments and heightened supply-chain security requirements — materially reduce barriers to fielding prepositioned and rapidly deployable systems at municipal and state levels.
Emergency Rescue Drone Market -
Technology is transitioning from capability parity to differentiated mission outcomes. Advances in autonomy, sensor fusion (especially thermal and low-light imaging), secure communications, and VTOL endurance architectures are enabling drones to conduct real search-and-rescue and disaster-relief missions independently and as integrated elements of multi-capability response teams.
-
Procurement and supply-chain resilience are now procurement criteria. As defense and public-safety customers formalize acquisition frameworks, compliance requirements (notably national security-oriented sourcing standards) and the availability of certified components — for example, NDAA-compliant batteries and parts — have become gating factors in award decisions.
Strategic implications for 2026 decisions
-
Operators (public safety, NGOs, utilities): Prioritize readiness investments that create operational uptime, not only unit counts. This means investments in prepositioned stations, trained DFR workflows, and sustainment contracts rather than one-off platform purchases. Scenario-based procurement that ties capability to response times and operational metrics will outperform simple platform buy cycles.
-
OEMs and system integrators: Adopt a modular product and services model. Buyers will favor vendors who can demonstrate certified supply chains, predictable lifecycle support, and systems that integrate into existing incident command and communications architectures. Long-lead material sourcing (batteries, secure comms) and compliance certification are critical competitively differentiating investments.
-
Investors and corporate development teams: Seek opportunities where technology leadership combines with defensible distribution to public-sector accounts. Given market concentration among a limited set of incumbents, bolt-on acquisitions that add NDAA-compliant manufacturing, recurring service revenue, or geographic access to public-safety contracts can accelerate scale with lower execution risk.
-
Policy and procurement offices: Recast RFPs to reward mission outcomes and sustainment rather than purely unit cost. Incorporate compliance checklists and interoperability tests into award criteria and consider performance-based contracts that align vendor incentives to operational availability.
Competitive landscape — players to watch
The market presents a juxtaposition of specialized public-safety innovators and established tactical UAS suppliers. PW Consulting’s competitive analysis focuses on capabilities and strategic posture rather than headline market shares, identifying where each firm is positioned to capture the next wave of adoption.
-
BRINC Drones (Seattle, WA) : A focused public-safety playbook built around indoor and tactical response. BRINC’s product suite targets Drone-as-First-Responder programs and constrained-environment missions where two-way communications, glass-penetration tools, and ruggedized designs matter. Notably, BRINC announced a production and capability expansion in March 2026 — a doubled manufacturing footprint and the next-generation Guardian platform — signaling an intent to scale 24/7 operational deployments.
-
Skydio (San Mateo, CA) : Autonomy as a competitive moat. Skydio’s systems emphasize AI-driven navigation and obstacle avoidance in complex environments, with payload capabilities (including thermal sensors) tailored to search-and-rescue and public-safety operators. The firm’s strength lies in ease-of-use and reduced training overhead, important attributes for agencies with constrained aircrew resources.
-
AeroVironment (Arlington, VA) : Tactical and defense-fluent systems with a track record in rapid-deployment ISR. AeroVironment’s portfolio is compelling where interoperability with defense and multi-domain command structures is required, and where proven endurance and VTOL/Fixed-Wing hybrid solutions support extended missions.
-
Draganfly (USA/Canada) : North American manufacturing emphasis and specialization in mission payloads. Draganfly’s strategic positioning benefits buyers prioritizing regional production and tailored sensor configurations for complex emergency scenarios.
-
ZenaDrone (USA) : Focused long-range search-and-rescue capability with real-time telemetry. The company’s emphasis on range and persistent data links is attractive for jurisdictions that need to cover extensive geographies with fewer launch points.
-
Ascent Aerosystems (USA) : Compact, robust coaxial designs optimized for space-constrained and tactical operations. Ascent’s engineering focus supports integrations into vehicles and rapid-deployment kits for first responders.
Market structure and competitive dynamics
The emergency rescue drone market is neither a pure fragmentation nor a duopoly: concentration metrics show a meaningful presence of leading players, yet sufficient space for specialized innovators and systems integrators. This environment favors partnerships — OEMs aligning with certified manufacturing partners, sensor firms integrating with autonomy stacks, and service providers bundling training and sustainment into subscription offerings. For buyers, the implication is clear: you can achieve both capability and vendor diversification, but procurement frameworks must account for interoperability and lifecycle assurance.
Operational playbooks and what our report delivers
PW Consulting’s report is designed as an operational playbook for leaders making procurement, investment, and programmatic decisions in 2026. It combines strategic analysis with step-by-step tools to accelerate deployment while managing program risk. Highlights include:
-
Scenario-driven capability matrices linking mission profiles (urban SAR, disaster relief, medical delivery) to recommended architectures (multi-rotor, fixed-wing, hybrid), endurance profiles, and sensor suites.
-
Procurement checklists and RFP language templates that operationalize compliance (including national security-related sourcing), lifecycle support, and interoperability tests.
-
Supplier due-diligence frameworks — assessing manufacturing footprint, certification status, component traceability (with emphasis on battery and communications supply chains), and sustainment economics.
-
Operational readiness scorecards for DFR programs: measures for stationing, crew training, mission rehearsal cadence, and maintenance turnaround times required to deliver mandated response SLAs.
-
Investment and M&A playbooks for strategic buyers: valuation sensibilities for recurring service revenue, integration risk assessments, and scenarios for rapid scale via acquisitions.
Risk vectors and mitigation priorities
-
Supply-chain and compliance risk: NDAA and similar sourcing standards are non-negotiable for many government programs. Buyers should require component-level certification and conduct supplier audits early in the procurement process.
-
Operational integration risk: Drones are seldom a standalone capability. They must be interoperable with incident command systems, comms networks, and medical dispatch workflows. Prioritize vendors with proven integrations and open APIs.
-
Technology obsolescence: Rapid advances in autonomy and sensors can render platforms suboptimal within procurement cycles. Structure contracts to allow payload upgrades and modular avionics refreshes without full platform replacement.
-
Regulatory change: The same regulatory developments that unlock deployment can also shift compliance requirements. Maintain a regulatory-monitoring function and build contractual clauses that address changing certification regimes.
Actionable recommendations for 2026
-
Reframe procurement around operational outcome metrics (response time, area coverage per launch, mission success rates) and tie payments to availability and sustainment KPIs.
-
Invest in a hybrid sourcing strategy: partner with proven incumbents for baseline platforms while selectively piloting fast-moving innovators for specialized mission sets.
-
Prioritize NDAA-compliant supply chain visibility and battery certification as gating criteria for any program intended for public-safety or defense alignment.
-
Establish a centralized integration lab or framework to validate vendor claims across sensors, autonomy stacks, and RF comms before awarding long-term contracts.
Next step — why the full report matters
This briefing articulates the strategic contours decision-makers need in 2026. The full PW Consulting Emergency Rescue Drone Market report contains the actionable datasets, vendor scorecards, procurement templates, and scenario-modeled forecasts required to move from strategy to execution. While this summary highlights market scale and structural forces, detailed segmentation, vendor-level financials, regional program analyses, and downloadable procurement templates are available exclusively in the complete report.
For organizations planning capital allocations, R&D roadmaps, or program launches in 2026, the PW Consulting study is intended to compress months of bespoke advisory work into a single, repeatable playbook — enabling faster, lower-risk decisions where lives and public trust depend on performance.
For detailed analysis of this topic, please visit the official page: Emergency Rescue Drone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com