

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Walk-In Humidity Chambers Market Poised for 6.3% CAGR as Electronics and Automotive Testing Drive Growth
By pmarketresearch, 2026-07-13
Walk-In Humidity Chambers Market 2026: Strategic Imperatives for Industrial and Life-Science Stakeholders
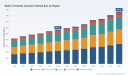
As PW Consulting’s lead industry analyst, I present a concise executive preview of our new Walk-In Humidity Chambers Market report — a practitioner’s guide built to inform capital allocation, product roadmaps, and supply-chain strategy as organizations plan for 2026 and beyond. The market for walk-in humidity chambers reached approximately USD 566.5 Million in 2025 and is forecasted to expand at a compound annual growth rate (CAGR) of 6.3% through our 2026–2032 horizon, reaching an estimated USD 868.9 Million by 2032. Those topline dynamics reflect accelerating demand across regulated stability testing, automotive and battery testing, electronics qualification, and large-format aerospace and defense validation.
Walk In Humidity Chambers Market
Why this report matters for 2026 decision cycles
- Actionable timing: Capital planning cycles and capacity expansion decisions initiated in 2026 will almost entirely capture the next wave of demand through the late 2020s. Our models show the market is transitioning from replacement-driven purchases to growth-led capacity investments in multiple end markets.
- Risk-informed sourcing: Supply-chain friction for critical components — stainless‑steel interiors, specialized insulation, high-performance compressors and precision humidity sensors — is elevating lead times and cost volatility. The report quantifies exposure vectors and presents mitigations for procurement and design teams.
- Regulatory alignment: Pharmaceutical and biotech buyers must navigate ICH, FDA, GMP, ISO 17025 and CE conformity. We translate those requirements into product specifications and test protocols that procurement and compliance functions can operationalize.
- Competitive context for M&A and partnerships: Industry moves in 2025–2026 indicate consolidation and capacity investments. Our intelligence highlights targets, capability overlaps, and white-space niches for strategic acquirers and OEM partners.
Report scope — practical contents for operators and investors
This report blends quantitative market sizing with practical playbooks. Core deliverables include:
Walk In Humidity Chambers Market
- Extensive market sizing and seven-year forecasts (2026–2032), with scenario layers for base, upside, and stress cases to support capital budgeting and sensitivity analysis.
- Multi-dimensional segmentation across type (steady-state vs. dynamic/cyclic), application (pharma, electronics, automotive/EV, aerospace & defense, others), and region, accompanied by non-disclosed breakouts and normalized historical trends. (Note: detailed sub-segment values are available in the full report on the source webpage.)
- Vendor benchmarking: product capabilities, delivery lead times, aftermarket services, software/monitoring stacks, and compliance credentials — enabling rapid shortlist development for procurement RFIs.
- Technology and specification matrices mapping ICH and industry test protocols to chamber performance requirements (temperature stability, humidity range, uniformity, recovery times, and energy consumption).
- Supply-chain heat maps identifying single-source risks (compressors, specialty insulations, humidity sensors) and recommended supplier diversification strategies.
- CapEx and Total Cost of Ownership (TCO) models that incorporate energy efficiency, maintenance, calibration, and validation costs to support build vs. buy decisions.
- M&A and partnership playbooks: priority targets and capability complements, integration pitfalls, and near-term value-creation levers (cross-sell, standardization, service expansion).
- Operational checklists and commissioning protocols for large-format installations, including GMP/ICH validation templates and remote monitoring configuration guidance.
Market dynamics shaping strategy in 2026
- Demand mix is diversifying. Established drivers such as pharmaceutical stability testing continue to invest in ICH-compliant walk-in rooms, while growth from automotive EV battery testing, electronics qualification, and aerospace systems is broadening the performance envelope suppliers must meet.
- Regulatory stringency increases product specification floor. ICH and other regulatory regimes obligate tighter tolerance on temperature and humidity control and more rigorous monitoring and record-keeping — favoring vendors with validated software stacks and audit-ready documentation.
- Material- and component-level constraints are non-trivial. Stainless steel interiors, high-performance insulation, precision compressors, and humidity sensors are focal points where supplier concentration can create bottlenecks — a key reason to include procurement contingency clauses and long-lead sourcing strategies in 2026 contracts.
- Energy and sustainability are rapidly moving from nice-to-have to cost driver. Energy-efficient designs and recoverable heat strategies materially affect TCO over typical chamber lifecycles and are increasingly evaluative criteria for capital approvers.
Competitive landscape — what market leaders are doing
The competitive field combines specialized European OEMs, North American builders, and Asia-based suppliers with global distribution footprints. Our report profiles market participants and recent strategic moves that are reshaping the industry dynamic.
Walk In Humidity Chambers Market
- BINDER GmbH (Tuttlingen, Germany) — Known for ICH-focused walk-in chambers with precise temperature and humidity envelopes and FDA-compliant monitoring options. Its acquisition activity in 2025 signals an appetite for capability consolidation and a push to broaden its solution stack for pharmaceutical customers.
- Russells Technical Products (Holland, MI, USA) — Offers modular W-Series solutions designed for demanding temp/humidity/altitude testing and adaptable construction for small walk-in to drive-in applications, making them a go-to for industrial test labs needing flexibility.
- Weiss Technik North America (Grand Rapids, MI, USA), including the CSZ lineage — Brings decades of environmental simulation experience and is investing in expanded manufacturing capacity to shorten lead times for large-format orders.
- Associated Environmental Systems (AES) (North Chelmsford, MA, USA) — Recent facility expansion nearly doubled manufacturing footprint, enabling faster delivery and higher throughput for custom and high-load chambers.
- Darwin Chambers Company (St. Louis, MO, USA) — Concentrates on pharmaceutical stability and GMP storage solutions, emphasizing installation and lifecycle efficiency for regulated customers.
- Parameter Generation & Control (A BINDER Company) (Black Mountain, NC, USA) — Provides standard walk-in stability rooms with quick-delivery lines and ICH compliance, now under the BINDER umbrella to expand product and service breadth.
- Testron Group (Guangzhou, China, with US operations) — Offers sustainable ISO14001 designs and localized support, competing on price-performance and scalability for industrial and pharmaceutical clients.
- Wewon Environmental Chambers (Dongguan, China) — Supplies large specimen temperature-humidity solutions across multiple industries with focus on cost-effective large-format builds.
Market concentration is moderate: the combined share of the top three and top five firms indicates space for both incumbents and focused challengers. The report quantifies concentration and competitive positioning and prescribes go-to-market responses based on firm-scale and capability.
Strategic playbook for stakeholders in 2026
- For OEMs: Prioritize modular designs and fast-delivery product lines to capture replacement and near-term project demand; pursue software and monitoring IP to meet regulatory auditability requirements; consider bolt-on acquisitions to accelerate access to pharma‑validated technologies.
- For end-users (pharma, automotive, electronics, aerospace): Shift procurement evaluation from sticker price to lifecycle cost criteria — validate energy, calibration, and service models; embed supplier performance clauses for lead times and spares; mandate compliance and audit-ready documentation in contracts.
- For investors and M&A teams: Evaluate targets that close capability gaps in control systems, validation services, or regional manufacturing footprints. The market’s expansion and evolving specification floor create arbitrage for acquirers who can consolidate aftermarket services and standardize components.
- For supply‑chain managers: Lock long-lead items via multi-year purchase agreements, build strategic second-source relationships for compressors and humidity sensors, and invest in inventory buffers for critical interior materials where practical.
Operational caution and opportunity
Several practical cautions emerge from our analysis. First, specification creep driven by regulatory and test complexity can materially increase costs if design partners are not engaged early in project scoping. Second, well-intended sustainability retrofits require careful life-cycle analysis to validate payback under the buyer’s operating profile. Third, rapid capacity expansion without regional service ecosystems risks creating stranded assets if after‑sales support cannot scale.
Conversely, opportunities exist in: expanding remote monitoring and predictive-maintenance services, offering validated quick‑delivery lines for regulated sectors, and developing energy-recovery packages that materially reduce customer TCO.
How to use the full report
The PW Consulting Walk-In Humidity Chambers Market report is constructed to be directly operable: it includes downloadable CapEx/TCO models, supplier scorecards, RFP language templates, and a prioritized action list for 90- to 720-day horizons. For executives making 2026 strategic and budgetary decisions, the report functions as both a market map and a decision‑support toolkit.
To preserve the integrity of competitive positioning and to encourage direct engagement, segmented numeric tables, regional and application value breakdowns, and detailed vendor revenue splits are summarized in the full report available at the source webpage. The preview above provides the strategic frame; the full dataset provides the transaction-level detail required to execute.
Closing perspective
The walk-in humidity chambers market is entering a structurally different phase: measured growth, rising specification floors, and component-level supply risk are combining to advantage suppliers who can offer validated systems, fast delivery, and reliable after‑sales ecosystems. For buyers and investors initiating planning cycles in 2026, the choices made now about vendor selection, capacity commitments, and component sourcing will materially influence cost and operational resilience across the next investment cycle. Our report is designed to shorten the path from insight to execution — equipping teams to convert market growth into durable advantage.
For detailed analysis of this topic, please visit the official page: Walk In Humidity Chambers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Fuel Vapor Canisters Market Hits USD 2,952.2 Million in 2025, Poised for 3.42% CAGR Through 2032
By pmarketresearch, 2026-07-13
Automotive Fuel Vapor Canisters Market: Strategic Imperatives for 2026 Decision-Makers
Executive summary
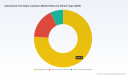
As regulatory envelopes tighten and material supply chains recalibrate, automotive fuel vapor canisters are re-emerging as a strategic node for OEMs, tier suppliers, aftermarket specialists, and investors. PW Consulting’s latest market assessment—anchored on a 2025 base year and projecting into the 2026–2032 forecast window—finds the global market poised to resume steady growth, with an expected compound annual growth rate of 3.42% through the forecast period. In monetary terms, the market sits near USD 2,952.2 Million in 2025 and is projected to expand materially by 2032 under baseline scenarios.
Automotive Fuel Vapor Canisters Market
Why this matters in 2026
Three converging forces make the fuel vapor canister category an unusually strategic opportunity this year. First, regulators have introduced more prescriptive evaporative-emission test procedures and canister performance expectations—most prominently the CARB protocols that specify butane-based breakthrough testing and minimum canister sizing for higher tank pressures. Second, material dynamics for activated carbon—the principal adsorbent in modern canisters—are creating both risk and value: feedstock variability and specification-driven qualification are elevating supplier selection into a core procurement decision. Third, competitive consolidation and targeted product program expansions across both OE and aftermarket channels are reshaping go-to-market vectors.
Automotive Fuel Vapor Canisters Market
What the full report delivers (operationally actionable)
- Quantified market trajectory: forward-looking scenarios across 2026–2032 that translate macro demand drivers into procurement volumes and revenue curves for planning horizons.
- Regulatory compliance playbook: a step-by-step interpretation of CARB and peer agency protocols with implications for canister capacity, media testing (including 2‑gram breakthrough methods), and validation cycles.
- Supplier risk & resilience matrix: multi-factor scores for carbon media, componentry, and complete canister suppliers—covering feedstock exposure, production fungibility, testing infrastructure, and lead-time sensitivity.
- Design and cost-to-serve analytics: scenario-modeled trade-offs between activated-carbon grades, multi-layer pack geometries, and plastic/composite enclosure architectures that impact BOM cost, weight, and service life.
- Aftermarket and service strategies: white-space maps for extended-coverage programs, repair-vs-replace economics, and warranty exposure under expanded emissions testing regimes.
- M&A and partnership screening: shortlists of candidate segments and capability clusters where consolidation or licensing delivers the fastest route to regulatory-compliant scale.
Market dynamics and the regulatory inflection
The recent CARB adoption of tightened running-loss standards and prescriptive testing protocols for 2026+ model years changes the design calculus for canisters. Specifications such as butane working-capacity thresholds and defined stabilization cycling are not academic; they drive canister media selection, sizing envelopes, and purge-control logic. Global equivalents—from EPA to Euro and China programs—are harmonizing toward more stringent evaporative loss control, compelling suppliers to validate multi-condition performance (diurnal, hot-soak, and running loss) rather than a single nominal metric.
Automotive Fuel Vapor Canisters Market
This regulatory push magnifies two strategic imperatives: first, accelerated qualification timelines for carbon media and modular canister systems; second, investment in lab capacity and test protocols by suppliers and OEMs to de-risk launches. Companies that postpone validation until late-stage vehicle development will face compressed launch windows and higher warranty risk.
Competitive landscape: incumbents, specialists, and aftermarket players
The category exhibits a balance of tier-one integrated suppliers, specialty carbon producers, and aftermarket consolidators. Leading engineered-systems suppliers bring platform-scale, regulatory know-how, and integration capability; niche players provide specialized media chemistry and rapid product programs for aftermarket and retrofit applications.
- PHINIA Inc.: With decades of global EVAP experience and modular designs capable of addressing small tank systems through large capacity applications, PHINIA’s strength is in platform-flexible architectures and integration of telemetry/OBD-ready devices. Their modularity is an asset for OEMs seeking commonality across fuel-system architectures.
- A. Kayser Automotive Systems GmbH: A market leader in activated-carbon canister systems with proven full-system offerings—valves, venting, and purge infrastructures. Kayser’s engineering depth makes it a preferred partner where end-to-end emission control responsibility is outsourced.
- MAHLE GmbH: Integrates canister solutions into broader fuel- and thermal-management portfolios, offering advantages where system-level trade-offs (combustion routing, thermal loads) are decisive for certifiability.
- Standard Motor Products, Inc. (SMP): An aftermarket powerhouse that continues to expand late-model coverage. Recent program expansions (notably in early 2026 and mid-2025) underline the aftermarket’s role as a demand buffer and a channel for extended-warranty and fleet servicing strategies.
- MotoRad: Focused on EVAP hardware with pragmatic cost-performance positioning, this supplier is a relevant option for price-sensitive channels and regional aftermarket distribution.
- Ingevity Corporation: A leading producer of hardwood-based activated carbon media; its feedstock control and media forms (granules, pellets, honeycomb) provide a tangible competitive advantage where media performance is the dominant differentiator.
Overall, the category shows moderate to high consolidation: a small set of incumbent suppliers account for the majority of market share, while a second layer of specialized players competes on media technology, program speed, and aftermarket reach. This concentration creates predictable channels for partnerships but also elevates supplier-selection rigor for buyers who must balance performance, lead times, and regulatory provenance.
Strategic recommendations for 2026 decision cycles
- Prioritize regulatory-first product roadmaps: Make CARB-derived test cases the baseline for validation workstreams, even if initial deployment is outside CARB jurisdictions. This future-proofs platforms and simplifies multi-market homologation.
- Qualify multiple carbon media sources today: Where possible, dual-qualify media types across performance bands (standard, high-capacity, and automotive-durable) to avoid single-feedstock exposure and to enable price negotiation leverage.
- Invest in in-house or partnered lab capability: Shorten time-to-qual by bringing critical tests—breakthrough curves, butane loading, cyclic purge—closer to the engineering teams; third-party test cycles introduce calendar risk.
- Reassess aftermarket strategies as complement, not substitution: Expanded OEM certification requirements create aftermarket opportunities in retrofit, service, and extended-coverage parts—but they also raise liability and quality thresholds for independent suppliers.
- Prepare procurement hedges for activated carbon: Map feedstock risk (e.g., hardwood, coal, coconut) and consider forward contracts or JV arrangements with media producers where volume commitments are acceptable.
- Use CR-based sourcing triggers: Where the supply base shows consolidation, introduce performance-tied contracts and modular design incentives to maintain competitive tension and to reduce single-supplier lock-in.
- Evaluate M&A and technology licensing: For companies seeking rapid capability extension, licensing of validated media formulations or acquisition of lab/testing capability provides a faster route to compliance-readiness than greenfield development.
Near-term tactical checklist for 90–180 day execution
- Run a CARB-compliance gap assessment against current canister designs and supplier test certificates.
- Initiate a two-source qualification for high-capacity activated carbon media, including sample round-robins on breakthrough testing.
- Negotiate program-level options with primary suppliers that include holdback volumes and expedited change-order lanes for regulatory-driven redesigns.
- Expand aftermarket SKU coverage where SMP-style late-model programs indicate demand dark spots—prioritize fleet and commercial vehicle segments with concentrated service networks.
- Deploy a supplier scorecard that integrates lab-certification status, lead-time resilience, and raw-material exposure to feed into strategic sourcing decisions.
Final perspective
By 2026, the fuel vapor canister market has evolved from a component-level commodity into a regulated, design-sensitive submarket where media science, validation capability, and regulatory acumen determine commercial success. PW Consulting’s analysis shows a market growing on a steady trajectory through 2032, but the path to capture upside is uneven: firms that treat canister strategy as a cross-functional program—integrating regulation, materials science, procurement, and aftermarket strategy—will capture disproportionate value.
PW Consulting’s full Automotive Fuel Vapor Canisters Market report provides the granular segmentation, regional demand mapping, supplier scorecards, and model-level program trackers that procurement, engineering, and strategy teams need to execute their 2026 plans with confidence. For the complete dataset, scenario dashboards, and executable playbooks, please visit PW Consulting’s report page to access the full intelligence package.
For detailed analysis of this topic, please visit the official page: Automotive Fuel Vapor Canisters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Fuel & Oil Aircraft Aerospace Filters Market Poised for 5.25% CAGR Through 2026–2032
By pmarketresearch, 2026-07-13
Fuel, Fuel Oil & Aerospace Filters: Strategic Imperatives from PW Consulting’s 2026 Market Outlook
Executive preview
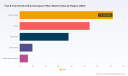
PW Consulting’s latest market study on the Fuel, Fuel Oil & Aircraft Aerospace Filters market offers a concise, decision-ready lens for executives preparing strategy in 2026. Built on a five-year historical baseline (2020–2025) and a seven-year forecast window (2026–2032), the report synthesizes macro demand trajectories, supplier positioning, regulatory inflection points and technology transition scenarios. At a macro level, the market expanded from approximately USD 142.35 Million in 2020 to USD 179.65 Million in 2025, and is projected to grow to USD 191.55 Million in 2026 on the way to an estimated USD 257.51 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 5.25% across the forecast period. These topline dynamics frame a market that is stable, consolidated and undergoing strategic reorientation around SAF compatibility, water-management technologies and aftermarket resilience.
Fuel Fuel Oil Aircraft Aerospace Filters Market
Why this matters for 2026 corporate decisions
-
Capital allocation and R&D prioritization: The mid-single-digit CAGR and near-term acceleration in retrofit and OEM demand make 2026 the inflection year to reweight R&D and capex toward SAF-compatible media, advanced coalescer designs and sensor-enabled monitoring. Firms that realign product roadmaps now will capture premium service and retrofit pockets through 2032.
Fuel Fuel Oil Aircraft Aerospace Filters Market -
M&A and partnership timing: With market concentration skewing toward a handful of incumbent suppliers (the top three firms account for a meaningful share of revenue while the top five exhibit material additional concentration), 2026 remains a window for bolt-on acquisitions to secure technology access or aftermarket footprints before consolidation intensifies.
Fuel Fuel Oil Aircraft Aerospace Filters Market -
Supply chain & procurement strategy: Raw material cost exposure and the higher cost of SAF production create two related pressures: suppliers must validate media compatibility and purchasers must build redundant sources for critical filter media and housing components to avoid single-point disruptions.
-
Regulatory compliance and service offerings: Evolving regulation—most notably SAF blending mandates and industry filtration standards—requires companies to expand product validation programs and to offer compliance-as-a-service propositions to airline and MRO customers.
What the report delivers (practical tools inside)
-
Actionable market model: A dynamic, downloadable model with topline and scenario-driven forecasts (base year 2025; forecast horizon 2026–2032) that supports what-if analysis on SAF penetration, fuel quality incidents and regulatory pathways.
-
Decision matrices & product roadmaps: Prioritized technology roadmaps linking filtration media, coalescer/separator architectures and sensor integration to likely OEM and MRO adoption curves. Roadmaps include investment sizing guidance and ROI benchmarks.
-
Procurement & sourcing playbook: Tactical guidance for procurement teams focused on hedging raw material exposure, qualifying alternative suppliers, and structuring long-term agreements to secure critical filtration elements.
-
Go-to-market frameworks for suppliers: Segmented commercial playbooks tailored to OEMs, airline fleets, MROs and defense procurement authorities—each with recommended pricing, service bundling and certification pathways.
-
Risk register and mitigation templates: Ready-to-use incident response protocols for contamination events (e.g., DEF-related crystallization), fuel quality excursions and rapid regulatory shifts.
Competitive landscape: who to watch
The market is served by a mix of global engineering groups, specialty filtration houses and niche aerospace suppliers. PW Consulting’s competitive analysis profiles the leading actors by technology capability, aftermarket reach and strategic trajectory—assessing strengths and potential gaps without disclosing proprietary segment share breakouts in this preview.
-
Parker Hannifin Corporation (Cleveland, Ohio, USA) – Renowned for its Velcon aviation fuel filtration portfolio, Parker remains a technology leader in micronic filters, coalescers and separators across aircraft and ground fuel-handling. Recent product strategy shifts signal accelerated migration to next-generation water-barrier technologies following the phase-out of certain legacy monitoring products.
-
Donaldson Company, Inc. (Minneapolis, Minnesota, USA) – A major filtration specialist that broadened its aviation focus through the strategic acquisition of a key filtration peer in 2026, enhancing cartridge and mission-critical fuel filtration capabilities for OEM and aftermarket channels.
-
Pall Corporation (Port Washington, New York, USA) – A longstanding supplier of high-performance fuel filters compatible with SAF blends and deployed across major commercial fleets. Pall continues to leverage fleet-support contracts to reinforce its position in engine- and system-level filtration.
-
Porvair Filtration Group (Fareham, UK) – Specialist manufacturer focused on custom filters and last-chance protection, with particular strength in tank and system-level inerting and straining solutions.
-
Safran (Paris, France) – Integrates filtration solutions within broader aerospace equipment portfolios, supplying both commercial and military platforms and emphasizing system-level compatibility and certification workflows.
-
Eaton Corporation (Dublin, Ireland) – Provides filtration components and integrated systems for aircraft applications, with a focus on modularity and integration into hydraulic and fuel system architectures.
-
Selected specialists – Regional and niche players such as Tempest Aero Group, Chase Filters & Components, Global Filtration and Norman Filter Company continue to serve general aviation, defense and PMA markets with tailored solutions and certification expertise.
Recent market moves and what they mean
-
Strategic M&A (2026): The completion of Donaldson’s acquisition of a filtration specialist in May 2026 accelerates consolidation in cartridge and mission-critical filtration—an important signal for mid-sized suppliers weighing exit or scaling options.
-
Product lifecycle shifts (2025–2026): Notices about the phase-out of certain legacy water-monitoring products have prompted both suppliers and airline customers to accelerate validation programs for alternative water-barrier technologies, creating near-term retrofit demand.
-
Fleet support continuity: Continued fleet-level partnerships—exemplified by major suppliers maintaining contracts with large carriers—highlight the value of long-term service agreements as diffrentiators in a concentrated market.
Regulatory and operational tailwinds & headwinds
-
SAF mandates and compatibility pressures: Policy frameworks that require minimum SAF blends at airports are re-shaping material compatibility requirements for filters. While SAF adoption supports decarbonization targets, its higher production cost and different physicochemical properties demand accelerated media testing and recertification programs.
-
Industry filtration standards: Standards such as the two-stage filtration requirements continue to be updated, raising the bar for separation of water and particulates and nudging buyers toward validated two-stage and sensor-enabled solutions.
-
Fuel contamination risks: Operational threats like DEF contamination—known to crystallize and clog filters—underscore the need for more robust last-chance and sensor-supported filtration strategies across airline and MRO operations.
Strategic playbook: four actions for 2026
-
Prioritize SAF compatibility certification now: Begin accelerated compatibility testing and certification for filter media and seals in 2026. Early movers will win retrofit programs and avoid costly fleet downtime as SAF blends increase.
-
Monetize service and diagnostics: Bundle filtration hardware with predictive maintenance and contamination-detection services. Sensor-enabled filters and connected MRO platforms create high-margin recurring revenue streams and deepen customer lock-in.
-
Hedge supply risk through modular sourcing: Qualify at least two alternate media suppliers and modularize filter housings to enable rapid substitution without recertification delays. This reduces exposure to raw material price shocks tied to energy-intensive SAF inputs.
-
Explore targeted M&A or strategic alliances: For firms seeking growth through acquisition, 2026 is advantageous for deals that add certification expertise, OEM access or digital diagnostics—particularly where the buyer can fold acquired IP into a broader aftermarket ecosystem.
How PW Consulting’s report supports implementation
Beyond high-level advisories, the report supplies the executable artifacts that senior teams need to move from strategy to action: a scenario-driven financial model, validated product roadmaps, a supplier qualification checklist, and playbooks for both procurement and aftermarket commercialization. The research also maps concentration metrics that illuminate competitive entry barriers and acquisition target profiles while preserving client confidentiality on detailed segment shares.
Closing: the strategic window in 2026
The Fuel, Fuel Oil & Aircraft Aerospace Filters market is not only growing—moving from roughly USD 179.65 Million in 2025 to an expected USD 191.55 Million in 2026 and on a path to about USD 257.51 Million by 2032 at a ~5.25% CAGR—but it is also being reshaped by regulation, contamination risk and technology shifts. For executives, 2026 represents a critical year to pivot: invest in SAF‑ready products, secure supply chains, monetize diagnostics and selectively consolidate. PW Consulting’s full report distills the evidence, tools and competitor intelligence necessary to turn these imperatives into executable 12–24 month plans.
Next steps
This preview highlights the strategic value of the full analysis while intentionally withholding detailed segment-level splits to preserve proprietary insights and encourage direct access to our primary research resources. For teams planning capital allocation, M&A screening or product roadmap updates in 2026, PW Consulting’s full report provides the granular data and end‑to‑end playbooks required to de‑risk decisions and capture upside. Visit our report page to request the complete dataset, model and executive briefing.
For detailed analysis of this topic, please visit the official page: Fuel Fuel Oil Aircraft Aerospace Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Charging Card Market Set to Surge with a Robust 18.24% CAGR
By pmarketresearch, 2026-07-13
EV Charging Card Market 2026: Strategic Imperatives from PW Consulting’s Latest Market Intelligence
PW Consulting today publishes an executive-level briefing that previews the strategic contours of the EV charging card market as businesses prepare for accelerated deployments and commercialisation decisions in 2026. Our full market research report — built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon — synthesises primary interviews, proprietary transaction-level data, and technical network analysis to transform noisy market headlines into actionable strategy.
Ev Charging Card Market
Why this matters in 2026
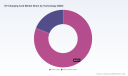
The EV charging card sector is no longer a niche accessory of public charging infrastructure: it sits at the intersection of authentication, revenue collection, roaming, and customer experience. After rapid expansion through 2025, PW Consulting’s macro-model estimates the global EV charging card market reached roughly USD 1.35 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 18.24% through our 2026–2032 projection window, moving to a materially larger addressable market by the early 2030s.
Ev Charging Card Market
For corporate strategy teams, infrastructure investors, charging network operators (CNOs), mobility service providers (MSPs), and OEMs, this presents three urgent imperatives for 2026 decisions:
Ev Charging Card Market
- Prioritise interoperable access solutions that reduce customer friction across roaming networks and vehicle platforms.
- Design business models that balance card-enabled subscription revenue with in-app and contactless payment innovations.
- Build procurement and partner strategies that hedge regulatory change and supply‑chain shifts while capturing scale economies in authentication hardware and backend clearing.
What PW Consulting’s report delivers — practical, board-ready outputs
We structured the research to support implementation-focused decisions in 2026. The report contains:
- Market sizing and growth scenarios calibrated to policy inflection points and deployment cadence, presented with upside/ downside pathways for network operators and card issuers.
- Competitive landscaping and capability mapping for card technology, payment clearing, and roaming stacks — enabling quick identification of white-space partnerships and acquisition targets.
- Go-to-market playbooks for CNOs and utilities that include product positioning, pricing archetypes, and channel strategies tailored for fleet, public, and private access markets.
- Procurement templates and TCO models for card issuance and backend integration, including vendor selection criteria and an implementation risk checklist.
- Commercial negotiation levers and contract clauses for roaming agreements, invoicing consolidation, and service-level commitments designed to protect margins as networks scale.
- Scenario-based ROI calculators and an operational roadmap for migrating from legacy RFID-centric access to hybrid RFID/NFC/plug-and-play authentication models.
- An executive dashboard of leading industry KPIs (activation rates, network roaming ratios, average transaction value trends) that boards and investment committees can adopt as quarterly governance metrics.
These deliverables are intentionally practical: the aim is to convert strategic intent into executable 90–180 day initiatives, rather than provide a purely academic view of the sector.
Competitive dynamics — what to watch in 2026
The competitive map is mixed: vertically integrated OEMs, dedicated CNOs, energy incumbents, equipment vendors, and specialised roaming aggregators all hold meaningful positions. Market concentration metrics in our assessment indicate a moderate level of concentration, with the top three and top five firms capturing a meaningful but not overwhelming share of market activity — a sign that scale matters, but that niche specialists and regional integrators still have room to compete.
Across the vendor set, strategic behaviours to monitor include:
- OEMs leveraging proprietary cards and integrated authentication to lock in captive fleets and brand-aligned drivers — a strategy that can accelerate customer lifetime value but poses cross‑brand friction risks.
- CNOs and aggregators expanding protocol compatibility and roaming partnerships, moving from local coverage to multi-network propositions that prioritise convenience over single‑network loyalty.
- Energy and infrastructure incumbents bundling card-based access with retail energy contracts and managed services, turning cards into acquisition and retention tools for broader energy portfolios.
- Equipment suppliers embedding access logic in hardware, enabling seamless plug-and-play authorisation for fleets and commercial sites while creating aftermarket service revenues.
Notable company moves highlighted in our intelligence include rapid connector and protocol rollouts by fast-charging networks to accommodate growing vehicle compatibility, and regional product launches that emphasise secure tap-and-go authentication. These tactical shifts signal where interoperability and customer convenience are becoming non-negotiable.
Policy, infrastructure and supply-chain forces reshaping strategy
Three external dynamics will be decisive for corporate planners in 2026:
- Regulatory mandates and corridor build-out: New mandates that require public fast chargers along major routes are accelerating standardized access solutions to ensure interoperability. Companies must build for compliance and for the commercial opportunities of new highway deployments.
- Rapid station expansion: Significant additions to DC fast charging capacity in large markets are concentrating customer flows at higher-capacity hubs — raising the value of frictionless authentication at those locations and accelerating the need for robust, scalable card-clearing and roaming platforms.
- Supply-chain and localisation pressure: Tariff regimes and onshoring incentives in key markets are shifting procurement choices for hardware-linked components, which has implications for unit economics of card issuance and for timelines when scaling physical distribution of cards and keys.
Practically, these trends translate into actionable strategy: lock down roaming partners for corridor rollout, replicate highest-margin site configurations at scale, and redesign supplier agreements to include clauses for localisation and component substitution to avoid deployment delays.
Strategic playbook for 2026
Based on quantitative modelling and qualitative interviews, PW Consulting recommends a three-track approach for leadership teams planning 2026 initiatives:
- Operationalise interoperability. Prioritise multi-protocol support (RFID, NFC, app-based tokens) and adopt contractual terms for roaming settlements that reduce reconciliation friction. Pilot co-branded cards and wallet integrations to test customer uptake before widescale issuance.
- Monetise customer journeys. Use charging cards as a surface to deliver bundled services (priority reservations, tailored energy tariffs, fleet reporting). Adopt subscription and micropayment hybrids to diversify revenue and to smooth seasonal utilisation volatility.
- De‑risk supply and compliance. Revisit procurement timelines under new trade and localisation regimes, and lock contingency supply lines for key authentication hardware. Build regulatory-compliance milestones into deployment roadmaps to keep infrastructure spend aligned with grant and incentive windows.
For investors and M&A teams, there is immediate opportunity in firms that bridge technical clearing capability with market reach — firms that can neutralise friction across networks and aggregate billing stand to capture asymmetric returns as charging demand consolidates around fewer clearing points.
Where PW Consulting’s intelligence creates value
Clients tell us the most valuable insights are those that convert uncertainty into a prioritised action plan. This briefing previews the tactical guidance and near-term roadmaps in our full report, which is deliberately structured to support 2026 decision cycles:
- Board-level risk assessments tied to capital deployment timelines.
- Operational playbooks that reduce time-to-service at newly commissioned sites.
- Commercial templates that preserve yield while expanding network footprints.
We emphasise that while our public briefing highlights the drivers and strategic choices, the full report contains the underlying scenarios, sensitivity analyses, and the granular KPIs that business leaders and investment committees will need to make informed, executable decisions in 2026. In keeping with our “trailer” approach, we intentionally withhold certain granular segmentation tables and proprietary microdata here to ensure subscribers access the complete dataset and model outputs on the report portal.
Next steps for executive teams
As 2026 planning cycles begin, executive teams should treat the EV charging card domain not as an ancillary middleware issue but as a central lever for customer experience, revenue architecture, and competitive defence. Immediate actions include:
- Commission a rapid interoperability audit across current card, back-end clearing, and roaming relationships.
- Run a scenario-based financial sensitivity test on payment mix shifts (cards vs app vs contactless) to understand margin volatility.
- Engage shortlisted technology and roaming partners to negotiate pilot parameters that can be scaled within 12 months.
PW Consulting’s full report offers the templates, scenario models, and partner matrices to accelerate those actions into board-approved investments.
About this briefing
This insight is authored by PW Consulting’s EV Infrastructure practice, combining quantitative market modelling (base year 2025; historical 2020–2025; forecast 2026–2032) with primary interviews across CNOs, OEMs, utilities, and fleet operators. Our market model uses the currency USD (revenue unit: Million) and is designed to support capital allocation and commercial diligence in 2026.
To access the complete report with regional and technology segmentation tables, sensitivity scenarios, and operational toolkits — and to request a bespoke briefing for your executive team — please visit the report page linked in the press release. Our team is available to run tailored workshops that map these insights directly onto your 2026 planning calendar.
For detailed analysis of this topic, please visit the official page: Ev Charging Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Telescopic Jack Market Set to Expand at a 5.48% CAGR During 2026–2032, Fueling Global Demand
By pmarketresearch, 2026-07-13
Telescopic Jack Market 2026 Strategic Preview — PW Consulting Insights
As companies prepare budgets and strategic plans for 2026, PW Consulting’s latest Telescopic Jack Market report offers a concise, decision-ready view of a market that is expanding steadily and becoming materially more strategic across industrial, infrastructure and mobility sectors. This executive release outlines the report’s strategic value for 2026 decision-makers — the evidence base, competing plays, regulatory and materials dynamics to monitor, and the near-term moves that materially affect competitiveness. For full segmentation tables, granular scenario outputs and proprietary datasets, please refer to the report download page.
Telescopic Jack Market
Why 2026 is a Pivotal Year
The telescopic jack market has moved from a niche engineering segment into a dependable industrial market with cross-sector relevance. Between 2020 and 2025 the market expanded from roughly USD 562 million to USD 733 million (base year 2025). Our model projects continued expansion through the forecast window to reach an approximate USD 1.06 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.48% over the 2026–2032 forecast period.
Telescopic Jack Market
That trajectory implies predictable demand for core lifting solutions, while also signalling growing opportunities for product innovation (e.g., electrification and synchronized multi-stage designs), aftermarket services, and rental models. For 2026 planning cycles, the chief implication is that firms must balance capacity investments with service and modularity-focused go-to-market plays rather than betting purely on volume-driven strategies.
Telescopic Jack Market
What the PW Consulting Report Delivers (Practical, Actionable Content)
- Investment-grade market sizing: Historic and modeled market values for 2020–2032 with scenario-level variance for near-term shocks.
- Supplier benchmarking framework: A practical scorecard that scores manufacturers on engineering capability, certifications, manufacturing footprint, product breadth, rental/service capability, and commercial terms.
- Procurement playbooks: Contract structures, risk allocation clauses, and inventory strategies tailored for capital equipment and rental fleets.
- Product economics: Techno-commercial comparisons of multi-stage hydraulic, pneumatic and electric telescopic solutions — TCO drivers, service intervals, and retrofit considerations.
- Regulatory and standards impact analysis: How ASME, CSA, API and welding/quality standards affect technical specifications, lead times, cost drivers and liability exposure.
- Supply chain & raw material stress-testing: Scenarios for steel price volatility, capacity constraints, and mitigation tactics such as hedging and dual-sourcing.
- M&A and partnership playbook: Criteria and valuation levers for bolt-on acquisitions, joint ventures, and distribution partnerships in key end-use verticals.
Competitive Landscape — Patterns and Strategic Positions
The market is moderately concentrated: the top three suppliers account for roughly one third of market revenues, while the top five approach half of the market. This concentration profile creates both predictable supplier behavior and pockets of regional specialization that buyers and investors can exploit.
Key strategic archetypes emerge among incumbent and specialist firms:
- Elevator-specialist OEMs (e.g., EECO): Companies focused on elevator applications differentiate through compliance with elevator-specific safety codes and high-strength componentry. Their value proposition centers on certified designs, synchronized cylinder systems and integration into vertical-transportation OEM supply chains.
- Synchronized hydraulic innovators (e.g., ITI Hydraulik): Suppliers who emphasize smooth travel, constant-speed deployment and multi-section synchronization reduce installation scope and civil work for clients — a salient selling point where holeless or inground constraints apply.
- Infrastructure and tank-erection specialists (e.g., Bygging, Astha): These firms combine product design with rental and on-site services for large-diameter, thin-walled structures — their competitive moat is a mix of operational know-how, safety systems and project-level risk management.
- Compact-stroke and machinery-lifting vendors (e.g., Powerjac): Target applications that require higher stroke within constrained footprints; these designs appeal to industrial maintenance and heavy machinery sectors.
- Automotive and commercial vehicle niche players (e.g., Compac): Air-hydraulic floor and transmission jacks optimized for low minimum heights and long strokes serve repair shops and fleet maintenance — where speed, ergonomics and safety features dominate purchasing criteria.
- Regional industrial suppliers (e.g., Taha International): Focused on robustness and cost competitiveness for domestic industries, often supporting localized supply and aftermarket networks.
For corporate strategists, these archetypes reveal potential partnership and competitive plays: OEM partnerships to embed proprietary designs, service-led expansions to convert sales into annuities, and regional acquisitions to rapidly secure distribution and rental penetration.
Regulatory and Materials Dynamics — Signals to Watch
Two structural dynamics will shape supplier economics and buyer risk in 2026:
- Standards-driven product design: Elevator jacks and other lift systems increasingly require compliance with high-integrity codes (e.g., ASME A17.1/CSA B44) and project standards (e.g., API considerations for tank erection). Product redesigns to meet these codes can extend lead times and raise unit costs but also create defensible differentiation for compliant suppliers.
- Raw material and fabrication quality: High-strength carbon steel remains the dominant input for pistons, cylinders and load-bearing structures. Welding and fabrication follow AWS guidelines and, for some manufacturers, CWB certification. Volatility in steel markets and capacity constraints in certified fabrication centers are immediate supply-side risks planners should model in 2026 procurement cycles.
Practical consequence: buyers must include compliance validation and certified fabrication clauses in RFPs, and procurement teams should stress-test supplier capacity for certified welding and material traceability before awarding multiyear contracts.
Risks, Scenarios and Triggers for 2026 Decisions
PW Consulting’s report models three near-term scenarios to help firms calibrate capital and commercial choices in 2026:
- Base case: Steady demand following the consensus CAGR (~5.5%), moderated lead times and selective price pressure from raw material normalization. Optimal for measured capacity investments and expanding service offerings.
- Upside case: Acceleration driven by concentrated infrastructure programmes or fleet electrification pilots that prefer modular or electrically-actuated jacks, creating premium pricing windows for qualified suppliers.
- Downside/shock case: Steel price spikes, certification bottlenecks or a major supplier production disruption — scenarios that favor inventory cushions, dual-sourcing and accelerated supplier qualification processes.
Key triggers to monitor through 2026: regulatory updates that alter elevator or tank erection requirements, trade policy affecting steel flows, and capacity announcements from major manufacturing hubs.
Four Tactical Moves for 2026 (What Winning Firms Are Doing)
- Embed service revenue models: Convert 1–2% of installed base into rental or managed-service contracts to stabilize margins and capture aftermarket value over multi-year horizons.
- Certify and future-proof designs: Prioritize ASME/CSA/API conformity and documentation of welding/traceability processes — buyers will pay a premium for provable compliance during tender evaluations.
- Modular product roadmaps: Invest in modular, retrofit-friendly jack architectures to address both new-build and retrofit demand without duplicative SKUs.
- Supply chain hedging and validation: Establish dual sources for critical forged/rolled steel components and qualify secondary fabrication partners with CWB/AWS capabilities to reduce lead-time risk.
How Executives Should Use This Report in 2026 Planning
Procurement leaders will use the report’s supplier scorecards to re-run strategic sourcing events and to redesign contract terms to include certification milestones and operational KPIs. R&D and product teams should align their roadmaps to the techno-economic profiles in the report (e.g., electrification potential vs. hydraulic incumbency), while M&A teams can apply the acquisition playbook to prioritize tuck-in targets that accelerate service and rental capabilities.
Investors and C-suite executives evaluating expansion should treat the market’s 5.48% CAGR and the report’s scenario outputs as a starting point: combine them with company-specific margin and capacity diagnostics, and use the report’s valuation bridges to stress-test acquisition returns under the upside and downside scenarios outlined above.
Next Steps — Where to Get the Full Intelligence
This preview highlights the strategic vantage points and tactical moves that distinguish winners in 2026 planning. The full PW Consulting Telescopic Jack Market report contains the datasets, regional and application splits, supplier scorecards and downloadable model files necessary to execute on the recommendations above. For procurement RFP templates, due-diligence checklists, and a detailed M&A value-mapping workbook — please access the report on our website.
PW Consulting’s industry team stands ready to brief executive committees and procurement boards with a tailored 60–90 minute workshop that translates report findings into a 2026 action plan, complete with prioritized initiatives and implementation timelines.
Contact PW Consulting to arrange a briefing or to request the full report and annexes.
For detailed analysis of this topic, please visit the official page: Telescopic Jack Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: General Bio‑Based Polyamide Market to Expand at a 15.02% CAGR Through 2032, Report Finds
By pmarketresearch, 2026-07-13
General Bio-Based Polyamide Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study finds the global General Bio-Based Polyamide market at an inflection point. Measured on a 2025 base year, total industry revenues stand in the low‑single‑digit billions (USD, million units), and our modelling shows a robust compound annual growth rate of 15.02% through the 2026–2032 forecast window. Under our central scenario the market expands materially by 2032, reflecting accelerated adoption across mobility, consumer, and industrial applications as OEMs and brand owners pursue carbon reduction targets and material substitution strategies.
General Bio Based Polyamide Market
Why this report matters for 2026 strategic decisions
-
High-growth but capital‑intensive transition: Double‑digit CAGR implies rapid demand formation, yet upstream feedstock dynamics and conversion capacity remain the gating factors for many product formats. Timing of capacity additions and contractual offtakes will determine who captures scale economics.
General Bio Based Polyamide Market -
Regulation and procurement are moving from optional to mandatory: EU regulatory drivers and corporate net‑zero procurement policies are accelerating commercialisation for certified bio‑attributed grades. Certification frameworks and lifecycle accounting will increasingly influence supplier selection and price premiums.
General Bio Based Polyamide Market -
Market concentration favours select integrated players: Our concentration metrics indicate a moderately concentrated supplier base with clear leaders in integrated castor‑to‑polyamide value chains, and a second tier focused on mass‑balance and bio‑attributed offerings. Competitive positioning today predicts share capture in the near term.
What PW Consulting’s General Bio‑Based Polyamide report delivers (practical assets)
-
Decision‑grade market model: a transparent, editable financial model calibrated to 2020–2025 historicals and our 2026–2032 scenarios, enabling boardrooms to stress‑test volume, price and margin outcomes under alternate feedstock, policy and technology assumptions.
-
Go‑to‑market playbooks: segmented commercial strategies for OEMs, compounders and converters, including recommended contracting structures (indexation vs fixed pricing, revenue‑sharing, strategic JV templates) and customer qualification roadmaps.
-
Supplier scorecards and investment checklists: comparative assessments across technology readiness, feedstock integration, certification status (ISCC and equivalents), carbon intensity, supply reliability and capital intensity — built to fast‑track sourcing decisions and capex approvals.
-
Supply chain stress tests and sourcing blueprints: scenario analyses for feedstock shocks, logistics disruptions and policy shifts with actionable mitigation options (multi‑sourcing, buffer inventories, forward buying, synthetic biology pathways).
-
Regulatory and incentive matrix: jurisdictional overview of regulatory levers and incentive schemes shaping adoption — including procurement preferences, allowances, and compliance timelines critical to 2026 investment windows.
Five strategic imperatives for executives planning in 2026
-
Secure feedstock optionality now. Castor oil remains a primary renewable precursor for many bio‑polyamides. Historical price volatility in key derivatives has been material, so procurement strategies should combine medium‑term contracts, diversified sourcing geographies, and exploration of alternative bio‑monomers and biotechnological routes to reduce single‑source exposure.
-
Prioritise certified supply chains. Certification (e.g., ISCC PLUS and equivalent schemes) is no longer a marketing badge alone: it is a commercial prerequisite for many automotive and consumer supply chains. Early alignment with certified suppliers or investment in certified mass‑balance capacity creates preferential access to OEM programs.
-
Design for function, not just “bio.” Material selection must balance lifecycle emissions, performance (moisture uptake, thermal stability, mechanical properties) and manufacturability. Co‑development agreements with tier‑1 material suppliers can compress validation timelines and reduce adoption friction for regulated applications such as under‑hood automotive parts and medical devices.
-
Adopt a staged capacity play. Given the market’s projected expansion, late entrants risk higher unit costs. Conversely, premature brownfield investments without offtake guarantees increase balance‑sheet risk. We recommend staged capacity expansion tied to binding offtake contracts and technology de‑risking milestones.
-
Embed lifecycle transparency into commercial offers. Buyers increasingly value verified carbon intensity metrics (for example, low kg CO2e/kg production chains enabled by renewable energy integration). Companies that can present auditable cradle‑to‑gate data will command premium pricing and faster adoption.
Competitive landscape — positioning and strategic moves
The competitive map is shaped by vertically integrated specialty producers, incumbent polymer majors leveraging bio‑attribution, and technology‑native entrants developing novel monomer pathways. Key strategic archetypes we observe:
-
Integrated castor‑to‑polyamide leaders: firms with control across feedstock processing to finished resin are able to optimise carbon intensity and security of supply and therefore occupy premium positions for demanding end markets.
-
Mass‑balance and bio‑attributed incumbents: polymer majors are extending product portfolios via biogenic credits and ISCC‑certified mass‑balance offerings to serve existing customers seeking lower‑carbon alternatives without major processing shifts.
-
Specialist biotech and monomer innovators: agents producing odd‑carbon chain diamines or alternative routes (e.g., cadaverine routes, sebacic acid substitutes) are targeting textile fibers and niche engineering applications where property differentials create value.
Notable recent developments underscore these dynamics: a major specialty producer commissioned a transparent bio‑based polyamide unit in Southeast Asia to materially increase supply of mid‑bio‑content grades for eyewear, electronics and medical uses; a leading chemical group launched extended mass‑balanced biocircular PA6 resins with certification credentials suitable for decarbonisation programs; and integrated producers report production carbon footprints for certain PA11 chains that are a fraction of fossil equivalents thanks to renewable electricity and process efficiency gains. These moves change the commercial calculus for buyers and suppliers alike.
Risk matrix and headwinds to monitor in 2026
-
Raw material price swings: upstream feedstock markets have shown significant month‑to‑month variability, which can compress margins and complicate long‑term procurement unless hedged or contractually managed.
-
Certification and greenwashing scrutiny: inconsistent accounting and labelling could trigger buyer scepticism; robust, auditable chain‑of‑custody practices are essential.
-
Application qualification timelines: heavily regulated segments (automotive safety, medical devices) have long validation cycles. Companies must plan multi‑year qualification programs to synchronise material readiness with product roadmaps.
-
Technology and substitution risk: advances in recycling, alternative polymers or biosynthetic monomers could alter cost curves and performance benchmarks; continuous technology monitoring is required.
How PW Consulting helps your 2026 playbook
Our report is designed as an executable commercial and technical playbook for senior executives, procurement leads and innovation teams. It combines a scenario‑driven financial model, supplier and technology diagnostics, and pragmatic contracting templates to guide investment, sourcing and product development decisions through 2026 and beyond. The study also quantifies market concentration dynamics and highlights which supplier archetypes are most likely to scale in our central and downside scenarios.
Call to action — where to find the full intelligence
This briefing deliberately highlights strategic conclusions while withholding detailed regional, product and application breakouts to preserve the integrated intelligence contained in the full study. For access to the complete dataset, editable forecasting model, supplier scorecards, and our detailed end‑use segmentation (including downloadable charts and procurement playbooks), visit the PW Consulting report landing page or contact our research desk to arrange a briefing. The next 12–18 months will determine who secures scale economics in a market projected to more than double from the 2025 base under our central forecast — acting with data, contracts and validated technology roadmaps will be decisive.
For detailed analysis of this topic, please visit the official page: General Bio Based Polyamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Booming Home Pet Deworming Market — Poised to Reach USD 4,976 Million by 2032 with a 6.75% CAGR
By pmarketresearch, 2026-07-13
Home Pet Deworming Medicine Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting presents a forward-looking industry briefing drawn from our forthcoming Home Pet Deworming Medicine Market report (base year 2025, historical series 2020–2025, forecast 2026–2032). This briefing distills the macro trajectory, competitive posture, supply‑chain and regulatory inflection points, and the precise decision tools executives will need to convert market momentum into profitable action in 2026. The full report contains the proprietary segmentation tables, granular scenario outputs and go‑to‑market playbooks that are intentionally withheld here to preserve client value and to drive direct access to the source analysis.
Home Pet Deworming Medicine Market
Macro trajectory: robust, predictable growth
The home pet deworming medicine market has moved from a clear recovery phase into sustained expansion. Our historical analysis shows the market rising from USD 2,272.32 Million in 2020 to USD 3,150.0 Million in 2025. Under the baseline case in our forecast (2026–2032), the market continues to expand at a compound annual growth rate of 6.75%, with the market expected to surpass USD 4,975.99 Million by 2032. This profile — steady mid‑single‑digit CAGR coupled with resilient demand drivers — creates a planning horizon well suited to both near‑term tactical moves and multi‑year strategic investments.
Home Pet Deworming Medicine Market
Why 2026 is a pivotal year for corporate strategy
- Acceleration of consumer self‑care behaviors: Pet owners continue to favor at‑home remedies, boosting demand for OTC and veterinarian‑recommended over‑the‑counter formats. Companies that make 2026 the year of channel and packaging innovation can capture disproportionate share.
- Regulatory and generic pressure: The recent regulatory approvals expanding generic fenbendazole options change competitive dynamics. Firms must reassess price elasticity and lifecycle management for branded assets.
- Supply‑chain concentration risks: API production concentrations (notably in Asia Pacific) create both cost advantages and vulnerability to supply disruption — a critical factor for sourcing strategies and inventory policy.
- Portfolio rationalization opportunity: The market concentration metrics (CR3 ≈ 48.2% and CR5 ≈ 62.4%) indicate a moderately consolidated market where mid‑tier players can win by focusing on segmentation, convenience formats and channel specialization.
Actionable implications for 2026 corporate plans
Leaders who treat 2026 as the year to operationalize strategic options will benefit. Our report equips companies with applied tools; below are the high‑impact initiatives we recommend evaluating this year:
Home Pet Deworming Medicine Market
- Differentiated format plays: Invest selectively in chewables, spot‑on delivery innovations, or palatable suspensions based on channel economics and margin profiles. Prioritize formats that enable premium pricing through convenience and compliance features.
- Channel orchestration: Rebalance downstream investments across veterinary channels, retail chains and e‑commerce. Implement SKU rationalization and targeted promotions to improve inventory turns without sacrificing share in core outlets.
- Generic defense and lifecycle tactics: Launch defendable label extensions, collateralized clinical messaging, and bundled offerings to blunt margin erosion where generics are emerging.
- Supply resilience and vertical levers: Secure multi‑source API contracts, qualify alternate manufacturing sites, and model inventory buffers using the stress‑test scenarios in our annex to reduce stockout risk.
- M&A and partnership scouting: Use our screened target list and valuation templates to accelerate tuck‑ins that add channel capabilities, formulation expertise, or regulatory dossiers.
Competitive landscape — reading the field in 2026
The market’s mid‑consolidation state favors leaders that combine scale with innovation. Below are strategic profiles and implications for each core competitor we analyze in depth in the report.
- Zoetis (Parsippany, NJ, USA) — Strengths: well‑recognized companion animal portfolio and established liquid dewormer offerings. Strategic implication: defend prescription‑based channels, accelerate pet‑owner education programs to sustain premium positioning.
- Merck Animal Health (Rahway, NJ, USA) — Strengths: broad‑spectrum fenbendazole‑based products and strong vet relations. Strategic implication: leverage clinical credibility to offset generic entries and explore bundling dewormers with parasite prevention regimens.
- Elanco Animal Health (Greenfield, IN, USA) — Strengths: multi‑parasite chewable tablets and recent emergency authorizations in adjacent parasiticide categories. Strategic implication: exploit regulatory agility to fast‑track label extensions and capture episodic demand; consider rapid rollouts of novel dosing formats.
- Virbac (Fort Worth, TX, USA) — Strengths: flavored chewables and differentiated formulation expertise. Strategic implication: double down on palatability and compliance messaging to win owners prioritizing ease of administration.
- PetIQ (Eagle, ID, USA) — Strengths: OTC reach and value positioning in mass channels. Strategic implication: optimize private‑label economics and loyalty programs to sustain volume amid price competition.
- Boehringer Ingelheim (Ingelheim, Germany) — Strengths: global R&D and companion animal heritage. Strategic implication: focus on innovation pipelines that create distance from low‑cost generics through clinical differentiation.
- Ceva Santé Animale (Libourne, France) — Strengths: targeted parasiticide portfolio and regional strengths. Strategic implication: pursue selective partnerships to expand distribution in underpenetrated channels.
- Dechra Pharmaceuticals (Northwich, UK) — Strengths: niche veterinary formulations. Strategic implication: target premium veterinarian channels with specialized dosing formats and compliance tools.
- Central Garden & Pet / Farnam (Walnut Creek, CA, USA) — Strengths: consumer brand equity for home use formulations. Strategic implication: invest in retail merchandising and digital guidance to reduce misuse and increase repeat purchase.
- Durvet (Blue Springs, MO, USA) — Strengths: distribution breadth for affordable products. Strategic implication: collaborate on co‑branded value packs and geographic expansion in cost‑sensitive markets.
These competitor summaries are complemented in the full report by matrixed capability assessments (R&D, manufacturing scale, channel strength, pricing resilience) and scenario‑based market share trajectories that reveal plausible winners and losers under fast/slow generic adoption.
Regulatory and supply dynamics that will determine winners
- Generic entries and labeling compliance: The January 2026 FDA approval of the first generic fenbendazole oral suspension (Defendazole by Norbrook) for livestock underscores a shifting regulatory landscape. While the approval currently targets cattle and goats, it accelerates the development pathway for generics and heightens downward pricing pressure across fenbendazole‑containing portfolios. Additionally, over‑the‑counter pet dewormers such as pyrantel pamoate and praziquantel remain subject to strict labeling requirements; compliance will be a differentiator in retailer and veterinary procurement decisions.
- API geography and cost levers: Fenbendazole API production is concentrated in Asia Pacific (notably India and China). This concentration supports cost efficiency for manufacturers that secure long‑term contracts, but it also raises exposure to geopolitical and trade policy shifts. We provide a procurement decision tree in the report to quantify this tradeoff.
- Ad hoc emergency authorizations: The November 2025 emergency use authorization for a related parasiticide highlights how episodic regulatory decisions can create short‑term demand spikes. Companies with flexible manufacturing and rapid distribution pathways can monetize these windows.
What the PW Consulting report contains (practical, executable deliverables)
Our full market study is intentionally operational. Key deliverables include:
- Top‑line and bottom‑line forecasts (2020–2032) with Monte Carlo sensitivity bands for pricing, adoption and generic entry scenarios.
- Segmentation models by format, channel and animal cohort with interactive pivot tables (note: detailed segment tables and regional/application breakdowns are available only in the paid report).
- Competitive scorecards and 24‑month tactical playbooks for new product launches, value‑pack rollouts and private‑label strategies.
- Supply‑chain risk simulations, API sourcing roadmaps and recommended inventory buffers calibrated to service‑level targets.
- M&A screening list with valuation templates, synergies estimates and integration checklists for bolt‑on and platform acquisitions.
- Pricing elasticity studies and promotion optimization models designed for retail and veterinary channels.
How leading teams use this intelligence in 90–180 day sprints
- Commercial leaders: Use the SKU rationalization and pricing modules to lift gross margin ahead of anticipated generic pressure.
- R&D and product managers: Prioritize formulations that improve compliance and reduce dosing errors; pilot at scale using our launch playbook.
- Supply chain and procurement: Execute the API dual‑sourcing play and test contract durations that balance price and continuity risk.
- M&A teams: Shortlist targets using our acquisition filter; run the included integration stress tests before bid submission.
Next steps — where to go for the detailed intelligence
This briefing is designed to accelerate decision‑making in 2026 by highlighting the levers that matter most. For corporate teams preparing capital allocations, product roadmaps, or M&A strategies, the full PW Consulting Home Pet Deworming Medicine Market report provides the confidential segment tables, vendor scorecards and financial models required to finalize plans with confidence. Access to the complete dataset and executable templates is available via PW Consulting's report portal.
To discuss customized briefings, scenario runs tailored to your portfolio, or to obtain the full report and its proprietary appendices, contact PW Consulting’s animal health practice. Our analysts are ready to run bespoke variants of the model to reflect your price points, channel mixes and product pipeline.
For detailed analysis of this topic, please visit the official page: Home Pet Deworming Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Defense Asset Management Software Market Set to Rise from USD 1,945.5 Million in 2025 to USD 3,432.72 Million by 2032 at an 8.45% CAGR
By pmarketresearch, 2026-07-13
Defense Asset Management Software Market: Strategic Imperatives for 2026 Decision-Makers
Executive preview — why 2026 is the inflection year
PW Consulting’s newest market research on Defense Asset Management Software delivers an operationally focused, decision-grade briefing for defense prime contractors, government CIOs, program integrators, and systems suppliers preparing strategy and procurement plans in 2026. The market is no longer a niche of bespoke point solutions; it is scaling into an enterprise-class software category with mainstream commercial practices. Our analysis shows the market expanded from roughly USD 1.30 billion (2020) to approximately USD 1.95 billion in our 2025 base year (USD Million), and we forecast continued acceleration to USD 3.43 billion by 2032, reflecting a compound annual growth rate (CAGR) of 8.45% across the 2026–2032 forecast window. This pace, coupled with concurrent policy and technology shifts, makes 2026 the critical year to define platform strategies, compliance roadmaps, and procurement vehicles that will determine operational performance and sustainment economics for the decade ahead.
Defense Asset Management Software Market
What this report delivers — pragmatic, executable insights
-
Actionable vendor selection framework: a repeatable, defense-tailored scoring methodology that weighs compliance posture, systems integration effort, sustainment lifecycle costs, and operations-readiness outcomes. The full scoring matrix and vendor rankings are reserved for the complete report to preserve commercial sensitivity and encourage direct engagement.
Defense Asset Management Software Market -
TCO and procurement playbooks: scenario-based total cost of ownership templates that quantify trade-offs between rapid cloud adoption versus on-premise deployment in regulated environments, including guidance on negotiating enterprise licensing, SaaS ATO timelines, and FinOps guardrails.
Defense Asset Management Software Market -
Security and compliance blueprints: checklists and implementation patterns aligned to DoD-led directives (including SaaS ATO and enterprise licensing expectations), CMMC-related asset management practices, DLMS transformation considerations, and DCMA IT asset governance clauses.
-
Integration and change-management guides: practical steps to integrate asset data across ERP, MRO, logistics systems and platform sustainment chains with templates for API governance, data normalization, and legacy data transformation (DLMS-compliant mapping patterns are included in the premium content).
-
Risk- and capabilities-based roadmaps: three programmatic scenarios (Conservative Modernization, Hybrid Acceleration, and All-in Cloud) that link investment profiles to readiness outcomes and workforce implications—complete with sequencing recommendations for 24‑36 month implementation horizons.
Macro drivers shaping budget and procurement decisions in 2026
Several structural drivers underpin the market growth trajectory. First, a sustained push toward software-defined sustainment—where predictive maintenance, AI-enabled diagnostics, and data fusion inform maintenance cycles—has elevated software to a mission-critical asset class. Second, federal and service-level policies are reducing adoption barriers for cloud and SaaS solutions by clarifying ATO pathways and enterprise licensing mechanisms. Third, legacy modernization needs (data trapped in non-standard formats, DLMS compliance gaps) are creating a sizable services and systems-integration overlay that multiplies opportunities beyond pure-license revenue.
Operationally, specialized human labor—clearance-holding systems engineers, integrator SMEs, and sustainment logisticians—remains one of the largest near-term cost drivers. Expect procurement teams to contend with higher professional services loads during rollout, even as software vendors promote subscription economics.
Regulatory and program context: what to fact into 2026 plans
-
DoD Software Modernization Implementation Plan (FY25–26): This initiative is a turning point. It establishes clearer SaaS ATO processes, encourages enterprise licensing vehicles, and calls out FinOps for software-defined capabilities. These changes materially shorten timelines for approved cloud options while increasing emphasis on enterprise-level contracting.
-
CMMC and asset-management controls: CMMC 2.0 embeds asset management practices into cybersecurity maturity—mandating more explicit asset identification, documentation, and lifecycle controls for contractors aiming at certain contract bands. Compliance-driven requirements will influence vendor choice and design.
-
DLMS and DCMA requirements: Systems that track military inventory must support DLMS standards or provide robust transformation layers. DCMA guidance on centralized software license tracking and ESI participation further reshapes procurement levers and license management strategies.
Competitive landscape — strategic positions and tactical moves
The market is characterized by a mix of global enterprise software vendors, defense primes, specialized solution providers, and niche integrators. Rather than publish a numeric concentration table here, our analysis describes a market where a handful of large vendors maintain substantial influence through integrated suites and global delivery capabilities, while mid-market specialists and defense-native firms compete on domain-specific features, integration speed, and regulatory know‑how.
-
Major enterprise suites (IBM, SAP, Oracle, Infor): These vendors compete on breadth—offering end-to-end asset lifecycle platforms, ERP integration, and enterprise-grade security. Their strength is in scale, existing contracting relationships, and ecosystem services. Their differentiation comes from verticalized modules and partner networks that accelerate DoD-scale deployments.
-
Defense platforms and systems integrators (Lockheed Martin, Northrop Grumman, CGI): Primes and large integrators embed asset management within sustainment and logistics programs, often coupling software with hardware sustainment contracts. Their offering is attractive for platform-level sustainment but may present vendor-lock considerations for cross-platform interoperability.
-
Specialists and mid-market vendors (IFS, Dassault Systèmes, Prometheus Group, Ramco, Hexagon, AssetWorks, eQuip Software): These players excel in domain fit—aviation MRO, fleet management, or enterprise asset management tailored to defense conventions. They often win proofs-of-concept through agility, lower initial TCO, and quicker compliance alignment.
-
Strategic implications: Expect the market to be active on three fronts in 2026—feature-driven OEM updates (AI, predictive analytics), partnership-and-integration plays linking niche capabilities into enterprise backbones, and procurement-focused accelerator services that reduce ATO friction. Our full report maps vendor strengths against defense procurement priorities and includes guidance on negotiating licensing clauses, service levels, and data reciprocity.
How recent developments alter 2026 tactical roadmaps
-
Policy acceleration (DoD CIO, Apr 2025): The clarified position on SaaS ATO and enterprise licensing reduces approval uncertainty and makes hybrid-cloud adoption a realistic option for many programs. Procurement teams should incorporate ATO timelines into milestone-based contracting rather than as afterthoughts.
-
Program-level modernization (USAF Kessel Run, Feb 2026): Initiatives emphasizing data fusion and AI for operations bleed into asset and operations management programs. Decision-makers will increasingly require vendors to demonstrate data-fusion capabilities and extensible AI modules that can be validated against mission outcomes.
-
Vendor capability evolution (IBM, Jan 2026; Dassault Systèmes, Mar 2025): Major suppliers are responding with AI-enhanced modules and platform updates aimed at aerospace and defense workflows. Short-form pilots can validate AI use cases quickly, but procurement should build validation gates into contracts to manage model drift and sustainment risk.
Practical recommendations for 2026 procurement and program teams
-
Design procurements around interoperability and data portability. Insist on DLMS transformation tools and exportable canonical data models as a baseline requirement.
-
Price and contract for professional services explicitly. Because specialized labor is a persistent cost driver, separate managed services lanes or fixed-price integration milestones where possible.
-
Adopt staged ATO and FinOps checkpoints. Use the DoD’s SaaS ATO playbook to pace capability delivery and tie payments to validated security posture and operational outcomes.
-
Prioritize vendor ecosystem compatibility. Where readiness and cross-platform sustainment are priorities, favor vendors with demonstrated integrations to ERP, MRO, and logistics tooling used across defense portfolios.
-
Build AI validation and governance into contracts. Require transparency into model inputs, retraining schedules, and performance thresholds tied to maintenance outcome metrics.
Why PW Consulting’s report matters for 2026 decisions
Our research combines rigorous market sizing—anchored to a 2025 base (approximately USD 1,945.5 Million) and a forecast of USD 3,432.72 Million by 2032 at a 8.45% CAGR for 2026–2032—with operationally tested tools for procurement, integration, and sustainment. The report is deliberately structured to be a playbook: it translates market dynamics into costed decision trees, vendor due-diligence checklists, and programmatic roadmaps that can be deployed by PMOs and CIO offices within 90–180 day planning cycles.
To preserve competitive integrity and drive the necessary vendor and contract-level diligence, the report presents high-resolution segmentation, vendor scores, and modeled outcomes behind a gated analysis. This “trailer” approach ensures readers can evaluate the strategic thrust and operational recommendations here and then access the full intelligence set—segment-level forecasts, vendor scorecards, and scenario TCO models—through PW Consulting’s report portal.
Next steps for leaders
-
Use this briefing as the basis for an immediate 30‑60 day audit: inventory current asset management footprints, identify critical data transformation needs for DLMS, and map existing vendor contracting terms against ATO and FinOps expectations.
-
Commission a 90‑day pilot with clear success criteria tied to maintenance deferral reduction, readiness improvement, or logistics cycle-time reductions—prioritizing providers that can demonstrate both domain fit and cloud/security posture alignment.
-
Engage PW Consulting for the full report and tailored workshops to convert the market insights into procurement-ready RFP language, commercial negotiation playbooks, and an implementation sequencing plan aligned to program deliverables.
PW Consulting’s Defense Asset Management Software Market report is crafted to inform the strategic choices that will define sustainment economics and readiness through the next decade. For program teams preparing 2026 budgets and transformation roadmaps, the report is the operational short-cut between market intelligence and executable program design.
For detailed analysis of this topic, please visit the official page: Defense Asset Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com