

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Fuel & Oil Aircraft Aerospace Filters Market Poised for 5.25% CAGR Through 2026–2032

Fuel, Fuel Oil & Aerospace Filters: Strategic Imperatives from PW Consulting’s 2026 Market Outlook
Executive preview
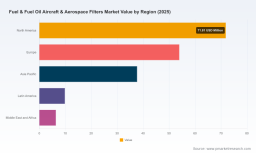
PW Consulting’s latest market study on the Fuel, Fuel Oil & Aircraft Aerospace Filters market offers a concise, decision-ready lens for executives preparing strategy in 2026. Built on a five-year historical baseline (2020–2025) and a seven-year forecast window (2026–2032), the report synthesizes macro demand trajectories, supplier positioning, regulatory inflection points and technology transition scenarios. At a macro level, the market expanded from approximately USD 142.35 Million in 2020 to USD 179.65 Million in 2025, and is projected to grow to USD 191.55 Million in 2026 on the way to an estimated USD 257.51 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 5.25% across the forecast period. These topline dynamics frame a market that is stable, consolidated and undergoing strategic reorientation around SAF compatibility, water-management technologies and aftermarket resilience.
Fuel Fuel Oil Aircraft Aerospace Filters Market
Why this matters for 2026 corporate decisions
-
Capital allocation and R&D prioritization: The mid-single-digit CAGR and near-term acceleration in retrofit and OEM demand make 2026 the inflection year to reweight R&D and capex toward SAF-compatible media, advanced coalescer designs and sensor-enabled monitoring. Firms that realign product roadmaps now will capture premium service and retrofit pockets through 2032.
Fuel Fuel Oil Aircraft Aerospace Filters Market -
M&A and partnership timing: With market concentration skewing toward a handful of incumbent suppliers (the top three firms account for a meaningful share of revenue while the top five exhibit material additional concentration), 2026 remains a window for bolt-on acquisitions to secure technology access or aftermarket footprints before consolidation intensifies.
Fuel Fuel Oil Aircraft Aerospace Filters Market -
Supply chain & procurement strategy: Raw material cost exposure and the higher cost of SAF production create two related pressures: suppliers must validate media compatibility and purchasers must build redundant sources for critical filter media and housing components to avoid single-point disruptions.
-
Regulatory compliance and service offerings: Evolving regulation—most notably SAF blending mandates and industry filtration standards—requires companies to expand product validation programs and to offer compliance-as-a-service propositions to airline and MRO customers.
What the report delivers (practical tools inside)
-
Actionable market model: A dynamic, downloadable model with topline and scenario-driven forecasts (base year 2025; forecast horizon 2026–2032) that supports what-if analysis on SAF penetration, fuel quality incidents and regulatory pathways.
-
Decision matrices & product roadmaps: Prioritized technology roadmaps linking filtration media, coalescer/separator architectures and sensor integration to likely OEM and MRO adoption curves. Roadmaps include investment sizing guidance and ROI benchmarks.
-
Procurement & sourcing playbook: Tactical guidance for procurement teams focused on hedging raw material exposure, qualifying alternative suppliers, and structuring long-term agreements to secure critical filtration elements.
-
Go-to-market frameworks for suppliers: Segmented commercial playbooks tailored to OEMs, airline fleets, MROs and defense procurement authorities—each with recommended pricing, service bundling and certification pathways.
-
Risk register and mitigation templates: Ready-to-use incident response protocols for contamination events (e.g., DEF-related crystallization), fuel quality excursions and rapid regulatory shifts.
Competitive landscape: who to watch
The market is served by a mix of global engineering groups, specialty filtration houses and niche aerospace suppliers. PW Consulting’s competitive analysis profiles the leading actors by technology capability, aftermarket reach and strategic trajectory—assessing strengths and potential gaps without disclosing proprietary segment share breakouts in this preview.
-
Parker Hannifin Corporation (Cleveland, Ohio, USA) – Renowned for its Velcon aviation fuel filtration portfolio, Parker remains a technology leader in micronic filters, coalescers and separators across aircraft and ground fuel-handling. Recent product strategy shifts signal accelerated migration to next-generation water-barrier technologies following the phase-out of certain legacy monitoring products.
-
Donaldson Company, Inc. (Minneapolis, Minnesota, USA) – A major filtration specialist that broadened its aviation focus through the strategic acquisition of a key filtration peer in 2026, enhancing cartridge and mission-critical fuel filtration capabilities for OEM and aftermarket channels.
-
Pall Corporation (Port Washington, New York, USA) – A longstanding supplier of high-performance fuel filters compatible with SAF blends and deployed across major commercial fleets. Pall continues to leverage fleet-support contracts to reinforce its position in engine- and system-level filtration.
-
Porvair Filtration Group (Fareham, UK) – Specialist manufacturer focused on custom filters and last-chance protection, with particular strength in tank and system-level inerting and straining solutions.
-
Safran (Paris, France) – Integrates filtration solutions within broader aerospace equipment portfolios, supplying both commercial and military platforms and emphasizing system-level compatibility and certification workflows.
-
Eaton Corporation (Dublin, Ireland) – Provides filtration components and integrated systems for aircraft applications, with a focus on modularity and integration into hydraulic and fuel system architectures.
-
Selected specialists – Regional and niche players such as Tempest Aero Group, Chase Filters & Components, Global Filtration and Norman Filter Company continue to serve general aviation, defense and PMA markets with tailored solutions and certification expertise.
Recent market moves and what they mean
-
Strategic M&A (2026): The completion of Donaldson’s acquisition of a filtration specialist in May 2026 accelerates consolidation in cartridge and mission-critical filtration—an important signal for mid-sized suppliers weighing exit or scaling options.
-
Product lifecycle shifts (2025–2026): Notices about the phase-out of certain legacy water-monitoring products have prompted both suppliers and airline customers to accelerate validation programs for alternative water-barrier technologies, creating near-term retrofit demand.
-
Fleet support continuity: Continued fleet-level partnerships—exemplified by major suppliers maintaining contracts with large carriers—highlight the value of long-term service agreements as diffrentiators in a concentrated market.
Regulatory and operational tailwinds & headwinds
-
SAF mandates and compatibility pressures: Policy frameworks that require minimum SAF blends at airports are re-shaping material compatibility requirements for filters. While SAF adoption supports decarbonization targets, its higher production cost and different physicochemical properties demand accelerated media testing and recertification programs.
-
Industry filtration standards: Standards such as the two-stage filtration requirements continue to be updated, raising the bar for separation of water and particulates and nudging buyers toward validated two-stage and sensor-enabled solutions.
-
Fuel contamination risks: Operational threats like DEF contamination—known to crystallize and clog filters—underscore the need for more robust last-chance and sensor-supported filtration strategies across airline and MRO operations.
Strategic playbook: four actions for 2026
-
Prioritize SAF compatibility certification now: Begin accelerated compatibility testing and certification for filter media and seals in 2026. Early movers will win retrofit programs and avoid costly fleet downtime as SAF blends increase.
-
Monetize service and diagnostics: Bundle filtration hardware with predictive maintenance and contamination-detection services. Sensor-enabled filters and connected MRO platforms create high-margin recurring revenue streams and deepen customer lock-in.
-
Hedge supply risk through modular sourcing: Qualify at least two alternate media suppliers and modularize filter housings to enable rapid substitution without recertification delays. This reduces exposure to raw material price shocks tied to energy-intensive SAF inputs.
-
Explore targeted M&A or strategic alliances: For firms seeking growth through acquisition, 2026 is advantageous for deals that add certification expertise, OEM access or digital diagnostics—particularly where the buyer can fold acquired IP into a broader aftermarket ecosystem.
How PW Consulting’s report supports implementation
Beyond high-level advisories, the report supplies the executable artifacts that senior teams need to move from strategy to action: a scenario-driven financial model, validated product roadmaps, a supplier qualification checklist, and playbooks for both procurement and aftermarket commercialization. The research also maps concentration metrics that illuminate competitive entry barriers and acquisition target profiles while preserving client confidentiality on detailed segment shares.
Closing: the strategic window in 2026
The Fuel, Fuel Oil & Aircraft Aerospace Filters market is not only growing—moving from roughly USD 179.65 Million in 2025 to an expected USD 191.55 Million in 2026 and on a path to about USD 257.51 Million by 2032 at a ~5.25% CAGR—but it is also being reshaped by regulation, contamination risk and technology shifts. For executives, 2026 represents a critical year to pivot: invest in SAF‑ready products, secure supply chains, monetize diagnostics and selectively consolidate. PW Consulting’s full report distills the evidence, tools and competitor intelligence necessary to turn these imperatives into executable 12–24 month plans.
Next steps
This preview highlights the strategic value of the full analysis while intentionally withholding detailed segment-level splits to preserve proprietary insights and encourage direct access to our primary research resources. For teams planning capital allocation, M&A screening or product roadmap updates in 2026, PW Consulting’s full report provides the granular data and end‑to‑end playbooks required to de‑risk decisions and capture upside. Visit our report page to request the complete dataset, model and executive briefing.
For detailed analysis of this topic, please visit the official page: Fuel Fuel Oil Aircraft Aerospace Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com