

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
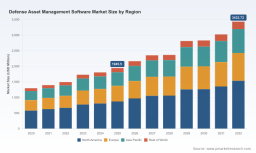
PW Consulting: Defense Asset Management Software Market Set to Rise from USD 1,945.5 Million in 2025 to USD 3,432.72 Million by 2032 at an 8.45% CAGR

Defense Asset Management Software Market: Strategic Imperatives for 2026 Decision-Makers
Executive preview — why 2026 is the inflection year
PW Consulting’s newest market research on Defense Asset Management Software delivers an operationally focused, decision-grade briefing for defense prime contractors, government CIOs, program integrators, and systems suppliers preparing strategy and procurement plans in 2026. The market is no longer a niche of bespoke point solutions; it is scaling into an enterprise-class software category with mainstream commercial practices. Our analysis shows the market expanded from roughly USD 1.30 billion (2020) to approximately USD 1.95 billion in our 2025 base year (USD Million), and we forecast continued acceleration to USD 3.43 billion by 2032, reflecting a compound annual growth rate (CAGR) of 8.45% across the 2026–2032 forecast window. This pace, coupled with concurrent policy and technology shifts, makes 2026 the critical year to define platform strategies, compliance roadmaps, and procurement vehicles that will determine operational performance and sustainment economics for the decade ahead.
Defense Asset Management Software Market
What this report delivers — pragmatic, executable insights
-
Actionable vendor selection framework: a repeatable, defense-tailored scoring methodology that weighs compliance posture, systems integration effort, sustainment lifecycle costs, and operations-readiness outcomes. The full scoring matrix and vendor rankings are reserved for the complete report to preserve commercial sensitivity and encourage direct engagement.
Defense Asset Management Software Market -
TCO and procurement playbooks: scenario-based total cost of ownership templates that quantify trade-offs between rapid cloud adoption versus on-premise deployment in regulated environments, including guidance on negotiating enterprise licensing, SaaS ATO timelines, and FinOps guardrails.
Defense Asset Management Software Market -
Security and compliance blueprints: checklists and implementation patterns aligned to DoD-led directives (including SaaS ATO and enterprise licensing expectations), CMMC-related asset management practices, DLMS transformation considerations, and DCMA IT asset governance clauses.
-
Integration and change-management guides: practical steps to integrate asset data across ERP, MRO, logistics systems and platform sustainment chains with templates for API governance, data normalization, and legacy data transformation (DLMS-compliant mapping patterns are included in the premium content).
-
Risk- and capabilities-based roadmaps: three programmatic scenarios (Conservative Modernization, Hybrid Acceleration, and All-in Cloud) that link investment profiles to readiness outcomes and workforce implications—complete with sequencing recommendations for 24‑36 month implementation horizons.
Macro drivers shaping budget and procurement decisions in 2026
Several structural drivers underpin the market growth trajectory. First, a sustained push toward software-defined sustainment—where predictive maintenance, AI-enabled diagnostics, and data fusion inform maintenance cycles—has elevated software to a mission-critical asset class. Second, federal and service-level policies are reducing adoption barriers for cloud and SaaS solutions by clarifying ATO pathways and enterprise licensing mechanisms. Third, legacy modernization needs (data trapped in non-standard formats, DLMS compliance gaps) are creating a sizable services and systems-integration overlay that multiplies opportunities beyond pure-license revenue.
Operationally, specialized human labor—clearance-holding systems engineers, integrator SMEs, and sustainment logisticians—remains one of the largest near-term cost drivers. Expect procurement teams to contend with higher professional services loads during rollout, even as software vendors promote subscription economics.
Regulatory and program context: what to fact into 2026 plans
-
DoD Software Modernization Implementation Plan (FY25–26): This initiative is a turning point. It establishes clearer SaaS ATO processes, encourages enterprise licensing vehicles, and calls out FinOps for software-defined capabilities. These changes materially shorten timelines for approved cloud options while increasing emphasis on enterprise-level contracting.
-
CMMC and asset-management controls: CMMC 2.0 embeds asset management practices into cybersecurity maturity—mandating more explicit asset identification, documentation, and lifecycle controls for contractors aiming at certain contract bands. Compliance-driven requirements will influence vendor choice and design.
-
DLMS and DCMA requirements: Systems that track military inventory must support DLMS standards or provide robust transformation layers. DCMA guidance on centralized software license tracking and ESI participation further reshapes procurement levers and license management strategies.
Competitive landscape — strategic positions and tactical moves
The market is characterized by a mix of global enterprise software vendors, defense primes, specialized solution providers, and niche integrators. Rather than publish a numeric concentration table here, our analysis describes a market where a handful of large vendors maintain substantial influence through integrated suites and global delivery capabilities, while mid-market specialists and defense-native firms compete on domain-specific features, integration speed, and regulatory know‑how.
-
Major enterprise suites (IBM, SAP, Oracle, Infor): These vendors compete on breadth—offering end-to-end asset lifecycle platforms, ERP integration, and enterprise-grade security. Their strength is in scale, existing contracting relationships, and ecosystem services. Their differentiation comes from verticalized modules and partner networks that accelerate DoD-scale deployments.
-
Defense platforms and systems integrators (Lockheed Martin, Northrop Grumman, CGI): Primes and large integrators embed asset management within sustainment and logistics programs, often coupling software with hardware sustainment contracts. Their offering is attractive for platform-level sustainment but may present vendor-lock considerations for cross-platform interoperability.
-
Specialists and mid-market vendors (IFS, Dassault Systèmes, Prometheus Group, Ramco, Hexagon, AssetWorks, eQuip Software): These players excel in domain fit—aviation MRO, fleet management, or enterprise asset management tailored to defense conventions. They often win proofs-of-concept through agility, lower initial TCO, and quicker compliance alignment.
-
Strategic implications: Expect the market to be active on three fronts in 2026—feature-driven OEM updates (AI, predictive analytics), partnership-and-integration plays linking niche capabilities into enterprise backbones, and procurement-focused accelerator services that reduce ATO friction. Our full report maps vendor strengths against defense procurement priorities and includes guidance on negotiating licensing clauses, service levels, and data reciprocity.
How recent developments alter 2026 tactical roadmaps
-
Policy acceleration (DoD CIO, Apr 2025): The clarified position on SaaS ATO and enterprise licensing reduces approval uncertainty and makes hybrid-cloud adoption a realistic option for many programs. Procurement teams should incorporate ATO timelines into milestone-based contracting rather than as afterthoughts.
-
Program-level modernization (USAF Kessel Run, Feb 2026): Initiatives emphasizing data fusion and AI for operations bleed into asset and operations management programs. Decision-makers will increasingly require vendors to demonstrate data-fusion capabilities and extensible AI modules that can be validated against mission outcomes.
-
Vendor capability evolution (IBM, Jan 2026; Dassault Systèmes, Mar 2025): Major suppliers are responding with AI-enhanced modules and platform updates aimed at aerospace and defense workflows. Short-form pilots can validate AI use cases quickly, but procurement should build validation gates into contracts to manage model drift and sustainment risk.
Practical recommendations for 2026 procurement and program teams
-
Design procurements around interoperability and data portability. Insist on DLMS transformation tools and exportable canonical data models as a baseline requirement.
-
Price and contract for professional services explicitly. Because specialized labor is a persistent cost driver, separate managed services lanes or fixed-price integration milestones where possible.
-
Adopt staged ATO and FinOps checkpoints. Use the DoD’s SaaS ATO playbook to pace capability delivery and tie payments to validated security posture and operational outcomes.
-
Prioritize vendor ecosystem compatibility. Where readiness and cross-platform sustainment are priorities, favor vendors with demonstrated integrations to ERP, MRO, and logistics tooling used across defense portfolios.
-
Build AI validation and governance into contracts. Require transparency into model inputs, retraining schedules, and performance thresholds tied to maintenance outcome metrics.
Why PW Consulting’s report matters for 2026 decisions
Our research combines rigorous market sizing—anchored to a 2025 base (approximately USD 1,945.5 Million) and a forecast of USD 3,432.72 Million by 2032 at a 8.45% CAGR for 2026–2032—with operationally tested tools for procurement, integration, and sustainment. The report is deliberately structured to be a playbook: it translates market dynamics into costed decision trees, vendor due-diligence checklists, and programmatic roadmaps that can be deployed by PMOs and CIO offices within 90–180 day planning cycles.
To preserve competitive integrity and drive the necessary vendor and contract-level diligence, the report presents high-resolution segmentation, vendor scores, and modeled outcomes behind a gated analysis. This “trailer” approach ensures readers can evaluate the strategic thrust and operational recommendations here and then access the full intelligence set—segment-level forecasts, vendor scorecards, and scenario TCO models—through PW Consulting’s report portal.
Next steps for leaders
-
Use this briefing as the basis for an immediate 30‑60 day audit: inventory current asset management footprints, identify critical data transformation needs for DLMS, and map existing vendor contracting terms against ATO and FinOps expectations.
-
Commission a 90‑day pilot with clear success criteria tied to maintenance deferral reduction, readiness improvement, or logistics cycle-time reductions—prioritizing providers that can demonstrate both domain fit and cloud/security posture alignment.
-
Engage PW Consulting for the full report and tailored workshops to convert the market insights into procurement-ready RFP language, commercial negotiation playbooks, and an implementation sequencing plan aligned to program deliverables.
PW Consulting’s Defense Asset Management Software Market report is crafted to inform the strategic choices that will define sustainment economics and readiness through the next decade. For program teams preparing 2026 budgets and transformation roadmaps, the report is the operational short-cut between market intelligence and executable program design.
For detailed analysis of this topic, please visit the official page: Defense Asset Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com