

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Walk-In Humidity Chambers Market Poised for 6.3% CAGR as Electronics and Automotive Testing Drive Growth

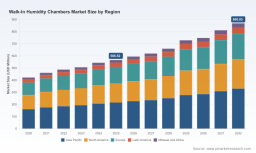
Walk-In Humidity Chambers Market 2026: Strategic Imperatives for Industrial and Life-Science Stakeholders
As PW Consulting’s lead industry analyst, I present a concise executive preview of our new Walk-In Humidity Chambers Market report — a practitioner’s guide built to inform capital allocation, product roadmaps, and supply-chain strategy as organizations plan for 2026 and beyond. The market for walk-in humidity chambers reached approximately USD 566.5 Million in 2025 and is forecasted to expand at a compound annual growth rate (CAGR) of 6.3% through our 2026–2032 horizon, reaching an estimated USD 868.9 Million by 2032. Those topline dynamics reflect accelerating demand across regulated stability testing, automotive and battery testing, electronics qualification, and large-format aerospace and defense validation.
Walk In Humidity Chambers Market
Why this report matters for 2026 decision cycles
- Actionable timing: Capital planning cycles and capacity expansion decisions initiated in 2026 will almost entirely capture the next wave of demand through the late 2020s. Our models show the market is transitioning from replacement-driven purchases to growth-led capacity investments in multiple end markets.
- Risk-informed sourcing: Supply-chain friction for critical components — stainless‑steel interiors, specialized insulation, high-performance compressors and precision humidity sensors — is elevating lead times and cost volatility. The report quantifies exposure vectors and presents mitigations for procurement and design teams.
- Regulatory alignment: Pharmaceutical and biotech buyers must navigate ICH, FDA, GMP, ISO 17025 and CE conformity. We translate those requirements into product specifications and test protocols that procurement and compliance functions can operationalize.
- Competitive context for M&A and partnerships: Industry moves in 2025–2026 indicate consolidation and capacity investments. Our intelligence highlights targets, capability overlaps, and white-space niches for strategic acquirers and OEM partners.
Report scope — practical contents for operators and investors
This report blends quantitative market sizing with practical playbooks. Core deliverables include:
Walk In Humidity Chambers Market
- Extensive market sizing and seven-year forecasts (2026–2032), with scenario layers for base, upside, and stress cases to support capital budgeting and sensitivity analysis.
- Multi-dimensional segmentation across type (steady-state vs. dynamic/cyclic), application (pharma, electronics, automotive/EV, aerospace & defense, others), and region, accompanied by non-disclosed breakouts and normalized historical trends. (Note: detailed sub-segment values are available in the full report on the source webpage.)
- Vendor benchmarking: product capabilities, delivery lead times, aftermarket services, software/monitoring stacks, and compliance credentials — enabling rapid shortlist development for procurement RFIs.
- Technology and specification matrices mapping ICH and industry test protocols to chamber performance requirements (temperature stability, humidity range, uniformity, recovery times, and energy consumption).
- Supply-chain heat maps identifying single-source risks (compressors, specialty insulations, humidity sensors) and recommended supplier diversification strategies.
- CapEx and Total Cost of Ownership (TCO) models that incorporate energy efficiency, maintenance, calibration, and validation costs to support build vs. buy decisions.
- M&A and partnership playbooks: priority targets and capability complements, integration pitfalls, and near-term value-creation levers (cross-sell, standardization, service expansion).
- Operational checklists and commissioning protocols for large-format installations, including GMP/ICH validation templates and remote monitoring configuration guidance.
Market dynamics shaping strategy in 2026
- Demand mix is diversifying. Established drivers such as pharmaceutical stability testing continue to invest in ICH-compliant walk-in rooms, while growth from automotive EV battery testing, electronics qualification, and aerospace systems is broadening the performance envelope suppliers must meet.
- Regulatory stringency increases product specification floor. ICH and other regulatory regimes obligate tighter tolerance on temperature and humidity control and more rigorous monitoring and record-keeping — favoring vendors with validated software stacks and audit-ready documentation.
- Material- and component-level constraints are non-trivial. Stainless steel interiors, high-performance insulation, precision compressors, and humidity sensors are focal points where supplier concentration can create bottlenecks — a key reason to include procurement contingency clauses and long-lead sourcing strategies in 2026 contracts.
- Energy and sustainability are rapidly moving from nice-to-have to cost driver. Energy-efficient designs and recoverable heat strategies materially affect TCO over typical chamber lifecycles and are increasingly evaluative criteria for capital approvers.
Competitive landscape — what market leaders are doing
The competitive field combines specialized European OEMs, North American builders, and Asia-based suppliers with global distribution footprints. Our report profiles market participants and recent strategic moves that are reshaping the industry dynamic.
Walk In Humidity Chambers Market
- BINDER GmbH (Tuttlingen, Germany) — Known for ICH-focused walk-in chambers with precise temperature and humidity envelopes and FDA-compliant monitoring options. Its acquisition activity in 2025 signals an appetite for capability consolidation and a push to broaden its solution stack for pharmaceutical customers.
- Russells Technical Products (Holland, MI, USA) — Offers modular W-Series solutions designed for demanding temp/humidity/altitude testing and adaptable construction for small walk-in to drive-in applications, making them a go-to for industrial test labs needing flexibility.
- Weiss Technik North America (Grand Rapids, MI, USA), including the CSZ lineage — Brings decades of environmental simulation experience and is investing in expanded manufacturing capacity to shorten lead times for large-format orders.
- Associated Environmental Systems (AES) (North Chelmsford, MA, USA) — Recent facility expansion nearly doubled manufacturing footprint, enabling faster delivery and higher throughput for custom and high-load chambers.
- Darwin Chambers Company (St. Louis, MO, USA) — Concentrates on pharmaceutical stability and GMP storage solutions, emphasizing installation and lifecycle efficiency for regulated customers.
- Parameter Generation & Control (A BINDER Company) (Black Mountain, NC, USA) — Provides standard walk-in stability rooms with quick-delivery lines and ICH compliance, now under the BINDER umbrella to expand product and service breadth.
- Testron Group (Guangzhou, China, with US operations) — Offers sustainable ISO14001 designs and localized support, competing on price-performance and scalability for industrial and pharmaceutical clients.
- Wewon Environmental Chambers (Dongguan, China) — Supplies large specimen temperature-humidity solutions across multiple industries with focus on cost-effective large-format builds.
Market concentration is moderate: the combined share of the top three and top five firms indicates space for both incumbents and focused challengers. The report quantifies concentration and competitive positioning and prescribes go-to-market responses based on firm-scale and capability.
Strategic playbook for stakeholders in 2026
- For OEMs: Prioritize modular designs and fast-delivery product lines to capture replacement and near-term project demand; pursue software and monitoring IP to meet regulatory auditability requirements; consider bolt-on acquisitions to accelerate access to pharma‑validated technologies.
- For end-users (pharma, automotive, electronics, aerospace): Shift procurement evaluation from sticker price to lifecycle cost criteria — validate energy, calibration, and service models; embed supplier performance clauses for lead times and spares; mandate compliance and audit-ready documentation in contracts.
- For investors and M&A teams: Evaluate targets that close capability gaps in control systems, validation services, or regional manufacturing footprints. The market’s expansion and evolving specification floor create arbitrage for acquirers who can consolidate aftermarket services and standardize components.
- For supply‑chain managers: Lock long-lead items via multi-year purchase agreements, build strategic second-source relationships for compressors and humidity sensors, and invest in inventory buffers for critical interior materials where practical.
Operational caution and opportunity
Several practical cautions emerge from our analysis. First, specification creep driven by regulatory and test complexity can materially increase costs if design partners are not engaged early in project scoping. Second, well-intended sustainability retrofits require careful life-cycle analysis to validate payback under the buyer’s operating profile. Third, rapid capacity expansion without regional service ecosystems risks creating stranded assets if after‑sales support cannot scale.
Conversely, opportunities exist in: expanding remote monitoring and predictive-maintenance services, offering validated quick‑delivery lines for regulated sectors, and developing energy-recovery packages that materially reduce customer TCO.
How to use the full report
The PW Consulting Walk-In Humidity Chambers Market report is constructed to be directly operable: it includes downloadable CapEx/TCO models, supplier scorecards, RFP language templates, and a prioritized action list for 90- to 720-day horizons. For executives making 2026 strategic and budgetary decisions, the report functions as both a market map and a decision‑support toolkit.
To preserve the integrity of competitive positioning and to encourage direct engagement, segmented numeric tables, regional and application value breakdowns, and detailed vendor revenue splits are summarized in the full report available at the source webpage. The preview above provides the strategic frame; the full dataset provides the transaction-level detail required to execute.
Closing perspective
The walk-in humidity chambers market is entering a structurally different phase: measured growth, rising specification floors, and component-level supply risk are combining to advantage suppliers who can offer validated systems, fast delivery, and reliable after‑sales ecosystems. For buyers and investors initiating planning cycles in 2026, the choices made now about vendor selection, capacity commitments, and component sourcing will materially influence cost and operational resilience across the next investment cycle. Our report is designed to shorten the path from insight to execution — equipping teams to convert market growth into durable advantage.
For detailed analysis of this topic, please visit the official page: Walk In Humidity Chambers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com