

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: General Bio‑Based Polyamide Market to Expand at a 15.02% CAGR Through 2032, Report Finds

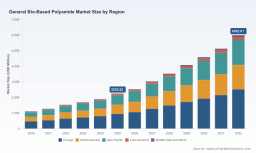
General Bio-Based Polyamide Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study finds the global General Bio-Based Polyamide market at an inflection point. Measured on a 2025 base year, total industry revenues stand in the low‑single‑digit billions (USD, million units), and our modelling shows a robust compound annual growth rate of 15.02% through the 2026–2032 forecast window. Under our central scenario the market expands materially by 2032, reflecting accelerated adoption across mobility, consumer, and industrial applications as OEMs and brand owners pursue carbon reduction targets and material substitution strategies.
General Bio Based Polyamide Market
Why this report matters for 2026 strategic decisions
-
High-growth but capital‑intensive transition: Double‑digit CAGR implies rapid demand formation, yet upstream feedstock dynamics and conversion capacity remain the gating factors for many product formats. Timing of capacity additions and contractual offtakes will determine who captures scale economics.
General Bio Based Polyamide Market -
Regulation and procurement are moving from optional to mandatory: EU regulatory drivers and corporate net‑zero procurement policies are accelerating commercialisation for certified bio‑attributed grades. Certification frameworks and lifecycle accounting will increasingly influence supplier selection and price premiums.
General Bio Based Polyamide Market -
Market concentration favours select integrated players: Our concentration metrics indicate a moderately concentrated supplier base with clear leaders in integrated castor‑to‑polyamide value chains, and a second tier focused on mass‑balance and bio‑attributed offerings. Competitive positioning today predicts share capture in the near term.
What PW Consulting’s General Bio‑Based Polyamide report delivers (practical assets)
-
Decision‑grade market model: a transparent, editable financial model calibrated to 2020–2025 historicals and our 2026–2032 scenarios, enabling boardrooms to stress‑test volume, price and margin outcomes under alternate feedstock, policy and technology assumptions.
-
Go‑to‑market playbooks: segmented commercial strategies for OEMs, compounders and converters, including recommended contracting structures (indexation vs fixed pricing, revenue‑sharing, strategic JV templates) and customer qualification roadmaps.
-
Supplier scorecards and investment checklists: comparative assessments across technology readiness, feedstock integration, certification status (ISCC and equivalents), carbon intensity, supply reliability and capital intensity — built to fast‑track sourcing decisions and capex approvals.
-
Supply chain stress tests and sourcing blueprints: scenario analyses for feedstock shocks, logistics disruptions and policy shifts with actionable mitigation options (multi‑sourcing, buffer inventories, forward buying, synthetic biology pathways).
-
Regulatory and incentive matrix: jurisdictional overview of regulatory levers and incentive schemes shaping adoption — including procurement preferences, allowances, and compliance timelines critical to 2026 investment windows.
Five strategic imperatives for executives planning in 2026
-
Secure feedstock optionality now. Castor oil remains a primary renewable precursor for many bio‑polyamides. Historical price volatility in key derivatives has been material, so procurement strategies should combine medium‑term contracts, diversified sourcing geographies, and exploration of alternative bio‑monomers and biotechnological routes to reduce single‑source exposure.
-
Prioritise certified supply chains. Certification (e.g., ISCC PLUS and equivalent schemes) is no longer a marketing badge alone: it is a commercial prerequisite for many automotive and consumer supply chains. Early alignment with certified suppliers or investment in certified mass‑balance capacity creates preferential access to OEM programs.
-
Design for function, not just “bio.” Material selection must balance lifecycle emissions, performance (moisture uptake, thermal stability, mechanical properties) and manufacturability. Co‑development agreements with tier‑1 material suppliers can compress validation timelines and reduce adoption friction for regulated applications such as under‑hood automotive parts and medical devices.
-
Adopt a staged capacity play. Given the market’s projected expansion, late entrants risk higher unit costs. Conversely, premature brownfield investments without offtake guarantees increase balance‑sheet risk. We recommend staged capacity expansion tied to binding offtake contracts and technology de‑risking milestones.
-
Embed lifecycle transparency into commercial offers. Buyers increasingly value verified carbon intensity metrics (for example, low kg CO2e/kg production chains enabled by renewable energy integration). Companies that can present auditable cradle‑to‑gate data will command premium pricing and faster adoption.
Competitive landscape — positioning and strategic moves
The competitive map is shaped by vertically integrated specialty producers, incumbent polymer majors leveraging bio‑attribution, and technology‑native entrants developing novel monomer pathways. Key strategic archetypes we observe:
-
Integrated castor‑to‑polyamide leaders: firms with control across feedstock processing to finished resin are able to optimise carbon intensity and security of supply and therefore occupy premium positions for demanding end markets.
-
Mass‑balance and bio‑attributed incumbents: polymer majors are extending product portfolios via biogenic credits and ISCC‑certified mass‑balance offerings to serve existing customers seeking lower‑carbon alternatives without major processing shifts.
-
Specialist biotech and monomer innovators: agents producing odd‑carbon chain diamines or alternative routes (e.g., cadaverine routes, sebacic acid substitutes) are targeting textile fibers and niche engineering applications where property differentials create value.
Notable recent developments underscore these dynamics: a major specialty producer commissioned a transparent bio‑based polyamide unit in Southeast Asia to materially increase supply of mid‑bio‑content grades for eyewear, electronics and medical uses; a leading chemical group launched extended mass‑balanced biocircular PA6 resins with certification credentials suitable for decarbonisation programs; and integrated producers report production carbon footprints for certain PA11 chains that are a fraction of fossil equivalents thanks to renewable electricity and process efficiency gains. These moves change the commercial calculus for buyers and suppliers alike.
Risk matrix and headwinds to monitor in 2026
-
Raw material price swings: upstream feedstock markets have shown significant month‑to‑month variability, which can compress margins and complicate long‑term procurement unless hedged or contractually managed.
-
Certification and greenwashing scrutiny: inconsistent accounting and labelling could trigger buyer scepticism; robust, auditable chain‑of‑custody practices are essential.
-
Application qualification timelines: heavily regulated segments (automotive safety, medical devices) have long validation cycles. Companies must plan multi‑year qualification programs to synchronise material readiness with product roadmaps.
-
Technology and substitution risk: advances in recycling, alternative polymers or biosynthetic monomers could alter cost curves and performance benchmarks; continuous technology monitoring is required.
How PW Consulting helps your 2026 playbook
Our report is designed as an executable commercial and technical playbook for senior executives, procurement leads and innovation teams. It combines a scenario‑driven financial model, supplier and technology diagnostics, and pragmatic contracting templates to guide investment, sourcing and product development decisions through 2026 and beyond. The study also quantifies market concentration dynamics and highlights which supplier archetypes are most likely to scale in our central and downside scenarios.
Call to action — where to find the full intelligence
This briefing deliberately highlights strategic conclusions while withholding detailed regional, product and application breakouts to preserve the integrated intelligence contained in the full study. For access to the complete dataset, editable forecasting model, supplier scorecards, and our detailed end‑use segmentation (including downloadable charts and procurement playbooks), visit the PW Consulting report landing page or contact our research desk to arrange a briefing. The next 12–18 months will determine who secures scale economics in a market projected to more than double from the 2025 base under our central forecast — acting with data, contracts and validated technology roadmaps will be decisive.
For detailed analysis of this topic, please visit the official page: General Bio Based Polyamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com