

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Recovered Carbon Black Market Poised to Reach USD 1,539.4 Million by 2032 at 11.5% CAGR, Led by Tire Manufacturing and Europe

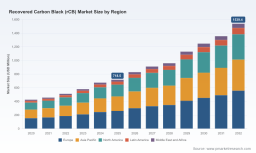
Recovered Carbon Black (rCB) Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest Recovered Carbon Black (rCB) Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) crystallizes why rCB will move from niche sustainability story to a commercially material input for rubber, plastics and specialty applications. Our modeling shows the rCB market continuing a robust compound annual growth rate (CAGR) of 11.5% through the 2026–2032 forecast window, with the global market already exceeding the three‑quarter billion mark in the 2025 base year and projected to more than double by the early 2030s in USD terms. For executives preparing 2026 budgets and three‑to‑five year strategic plans, the report converts macro momentum into practical next steps: where to secure feedstock, how to structure offtake and certification clauses, and which technology and partnership choices most directly de‑risk commercialization.
Recovered Carbon Black Rcb Market
Why this report matters for 2026 strategic planning
-
Actionable timing: 2026 is a pivot year. The industry has moved past pilot plants and demonstration runs; several commercial facilities have come online and will materially affect available supply and pricing dynamics in short order. Our forecast and scenario modules translate these capacity shifts into implications for procurement, pricing and margin capture.
Recovered Carbon Black Rcb Market -
Policy-commercial convergence: regulatory classifications and voluntary sustainability standards are converging to create credible commercial pathways for circular carbon products. Companies that wait for perfect clarity risk losing access to the best feedstock, premium customers, and collaborative incentives.
Recovered Carbon Black Rcb Market -
Investment readiness: whether you are an OEM, tire maker, compounder, or investor, the report provides the financial and operational templates needed to size and stress-test rCB projects under realistic price, feedstock and quality constraints.
Key market dynamics shaping 2026 decisions
-
Growth trajectory and scale: The rCB market has expanded rapidly in the last half‑decade and our base‑to‑forecast modeling shows sustained high‑teens to low‑double‑digit growth rates across the medium term. This is driven by feedstock availability, policy support in major markets, and industrial adoption curves — particularly in tire reinforcement and non‑tire rubber compounds.
-
Feedstock and price signals: Scrap tire availability is abundant but not costless. Recent data points show upward pressure on scrap tire pricing in major markets as recycling demand increases. Procurement strategies that lock in secure supply and integrate logistics will have a distinct advantage.
-
Regulatory enablers: In key jurisdictions, classification of tire pyrolysis outputs as recovery rather than waste allows rCB to enter commercial supply chains – enabling resale, traceability and the application of sustainability credentials. Parallel to regulation, voluntary certification frameworks (such as ISCC PLUS) are rapidly becoming a prerequisite for premium placements.
-
Certification and product differentiation: ISCC PLUS and similar mass‑balance approaches are establishing pathways for traceability and sustainability claims. Early adopters who align production process, mass balance accounting and third‑party certification can command better access to sustainability‑conscious offtakers.
-
Quality ceiling: Technical limitations remain. rCB typically exhibits a lower carbon purity range than the highest‑grade virgin carbon black; this constrains immediate substitution in the most performance‑sensitive applications (for example, some high‑end tire treads). The report’s technical appendix examines the current purity band and practical blending strategies to maximize market penetration without compromising product integrity.
-
Market concentration and competitive posture: The rCB market is neither highly fragmented nor tightly consolidated. A handful of technology‑led producers account for a meaningful share of capacity and influence pricing and technical benchmarks. This creates both opportunities for strategic partners and a rationale for scale investments by incumbents.
Competitive landscape — who to watch (and why it matters)
-
Pyrolyx AG (Germany) — An early mover with commercial pyrolysis capability. Pyrolyx’s transition from pilot to commercial scale means more predictable supply for European offtakers and provides a reference for industrial‑scale quality equivalence with traditional carbon black grades. Recent capacity expansion signals that the company is positioning to be a long‑term supplier to both tire and industrial rubber markets.
-
Black Bear Carbon B.V. (Netherlands) — Backed by a major OEM, Black Bear’s industrialization efforts reflect the strategic interest of large manufacturers in securing circular inputs. Its developments indicate how OEM partnership and sponsorship can accelerate technology de‑risking, create preferential offtake arrangements, and shift bargaining power toward certified, high‑purity rCB producers.
-
Enviro AB (Sweden) — Certification achievements highlight the premium associated with independently verified sustainability claims. Enviro’s ISCC PLUS certification is an operative example of how traceability credentials can unlock certain customer segments and justify price differentials for certified material.
-
Hi‑Green Carbon Limited (India) — Represents the drive to scale pyrolysis-driven rCB production in high‑demand, cost‑sensitive markets. Domestic policy levers (taxes, import duties) create unique trade flows that regional players must navigate; Indian producers will have a cost‑competitiveness angle, tempered by local taxation and logistics nuances.
Recent development signals and strategic implications
-
Commercial plant openings and capacity ramps are no longer hypothetical. When commercial plants reach industrial throughput, buyers will need to move from purchasing spot shipments to negotiating multi‑year offtake and quality‑assurance contracts.
-
Certifications are becoming a market entry fee for higher‑value channels. Producers that cannot demonstrate traceability and sustainability accounting will find themselves restricted to lower‑value, price‑sensitive segments.
-
Supply influx from new plants will create transient price volatility. Buyers with flexible procurement strategies and blending capabilities can capture value during supply gluts; producers without offtake agreements face margin compression.
What the PW Consulting report delivers — practical, executable content
-
Market sizing with scenario analysis: Base, upside and downside demand curves across the 2026–2032 window, with clear levers that materially impact outcomes (feedstock cost, certification uptake, substitution rates).
-
Commercial playbooks: Negotiation templates for multi‑year offtake, recommended contract provisions (quality tolerances, certification clauses, feedstock traceability, penalty and make‑good terms), and pricing indexation options to hedge feedstock volatility.
-
Technical and application guidance: Grade benchmarking, blending strategies to extend rCB use into higher‑performance applications, and material testing roadmaps for OEM qualification.
-
CapEx/Opex modelling: Unit economics for greenfield and brownfield rCB projects, sensitivity analyses and payback timelines under multiple feedstock and sales price scenarios.
-
Supply‑chain and logistics playbook: Sourcing maps, collection network design, inventory strategies and recommended partner archetypes (aggregators, toll processors, logistics integrators).
-
M&A and partnership frameworks: Value creation pathways for investors, strategic buyers and technology licensors — including earn‑out structures and JV models that align incentives across the value chain.
-
Risk matrix and mitigation strategies: Regulatory, technical, market and reputational risks with prioritized actions and contingency triggers for 2026 planning cycles.
How to use the research in your 2026 planning cycle
-
Procurement: Implement a staged sourcing strategy that secures feedstock and offtake for the near term while retaining optionality to scale into higher volumes as product qualifications complete.
-
R&D & Quality: Invest in blending and compound testing to maximize substitution without compromising performance. Prioritize ISCC or equivalent certification if targeting premium channels.
-
Manufacturing & CapEx: Stage capacity expansion decisions to coincide with verified demand commitments from OEMs and compounders. Early movers should prioritize modular designs to manage technological uncertainty.
-
Corporate strategy: Consider strategic partnerships with technology providers and certified producers to accelerate market entry and reduce time‑to‑qualification.
FAQ — key constraints and how to address them
-
Is rCB a full substitute for virgin carbon black? Not yet. rCB purity typically falls below the top performance range of virgin carbon black, which restricts immediate one‑for‑one substitution in the highest‑stress tire treads. The practical remedy is strategic blending and route‑to‑qualification programs targeting non‑tread and secondary rubber markets first.
-
How material are trade and tax barriers? They matter. Regional tax regimes (for example, import duties or GST treatments in some markets) will meaningfully affect cross‑border flows and should be baked into trade and sourcing scenarios.
-
Do certifications matter commercially? Yes. ISCC PLUS and equivalent certifications are increasingly a commercial prerequisite for premium contracts and OEM sustainability claims.
Closing and next steps
PW Consulting’s rCB Market report converts a clear macro growth story into a practical, executable intelligence product for 2026 decision‑making. We combine market sizing, competitive benchmarking, technical guidance and commercial playbooks so that procurement leads, product engineers, and corporate development teams have a common, actionable view of risk and opportunity.
In keeping with our “trailer” approach, we have showcased the strategic contours and practical uses of the intelligence in this briefing while withholding the granular regional and application splits and company‑level capacity tables that are central to transaction execution. For the full dataset, interactive models, and downloadable negotiation templates, please visit the PW Consulting report page to access the complete Recovered Carbon Black Market report and supporting annexes.
For detailed analysis of this topic, please visit the official page: Recovered Carbon Black Rcb Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com