

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Targeted Drugs for Multiple Myeloma Market Reaches USD 25,850 Million in 2025, Forecasted to Grow at a 6.45% CAGR Through 2032

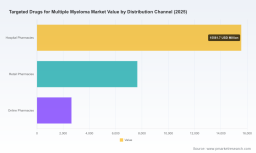
Targeted Drugs for Multiple Myeloma: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
PW Consulting’s forthcoming market research on targeted drugs for multiple myeloma synthesizes clinical progress, regulatory inflection points, reimbursement trends, and competitive positioning into a single decision-grade resource for life-science executives, investors, and payers planning activity in 2026. The global market, measured in USD million, has demonstrated resilient expansion through the mid-2020s and — under our base forecast assumptions — is set to continue growing at a mid-single-digit compound annual growth rate (CAGR) across the 2026–2032 horizon. This preview highlights the strategic value of the full report without disclosing the proprietary, transaction-sensitive segment detail readers will find in the paid study.
Targeted Drugs For Multiple Myeloma Market
Market trajectory and what it means for 2026
Multiple myeloma has shifted from a disease treated primarily with broad cytotoxic and backbone agents toward one increasingly dominated by targeted modalities: monoclonal antibodies, bispecific antibodies, CAR-T therapies, antibody–drug conjugates (ADCs), proteasome inhibitors, and novel oral targeted agents. By 2025 the total market reached a mature scale that supports differentiated specialty launches and novel combination strategies. Our modeling — using a 2026–2032 forecast window — anticipates steady, structurally supported growth driven by continued label expansions, uptake of off-the-shelf bispecifics, expanded CAR-T access, and shifting reimbursement approaches that increasingly tie approval and payment to surrogate endpoints such as minimal residual disease (MRD) negativity.
Targeted Drugs For Multiple Myeloma Market
For corporate strategists, the near-term takeaway is clear: 2026 decisions will center on sequencing, combination economics, and access pathways rather than pure volume expansion alone. Companies that can align clinical positioning with payer-validated endpoints and that optimize route-to-market costs for cellular and bispecific platforms will capture disproportionate commercial share.
Targeted Drugs For Multiple Myeloma Market
Competitive dynamics — who is moving the market and why it matters
-
Large biopharma incumbents remain dominant, with a concentrated top tier that continues to shape prescribing patterns and standards of care. Market concentration metrics show that the leading three and five firms hold the majority of realized revenue, creating both a barrier and an opportunity for newer entrants that offer clear differentiation.
-
Strategic product portfolios span mature monoclonal antibodies and proteasome inhibitors to next-generation oral CELMoDs, bispecific T-cell engagers, CAR-T constructs, and ADCs. Recent regulatory events have further rebalanced competitive dynamics: a leading company secured approvals for a bispecific in combination with an established CD38 monoclonal antibody, while other players announced positive Phase 3 results for next‑generation oral agents. These milestones accelerate the shift toward earlier use of novel targeted combinations and increase the clinical importance of tolerability and real-world manageability.
-
Fast-moving modality convergence — where companies combine or bundle CAR-T, bispecifics, antibodies, and oral agents into clinically rational sequences — will determine mid-decade winners. Firms able to protect margin through manufacturing scale, service differentiation (e.g., patient monitoring, REMS simplification adoption), and compelling combination data will command premium pricing and preferential formulary placement.
Regulatory and reimbursement inflection points shaping 2026 strategies
Regulatory authorities have tightened the link between surrogate endpoints and accelerated pathways while simultaneously offering clearer guidance on acceptable endpoints. In particular, acceptance of MRD negativity in the context of accelerated approvals changes both clinical development strategy and commercial expectations; companies can pursue shorter paths to market for certain regimens but must be prepared to demonstrate long-term benefit in pooled or confirmatory analyses.
Concurrently, safety- and monitoring-related regulatory simplifications for some cellular therapies (including reduced REMS obligations based on real-world safety evidence) materially lower the operational friction and cost of CAR-T deployment. These shifts create a more favorable reimbursement backdrop for complex therapies, but payers remain exacting — demanding health-economic justification for durable responses and real-world survivorship gains.
Patent cliffs, pricing pressure, and the response playbook
Generic entry for older backbone drugs will continue to exert pressure on combination economics and profit pools. Where a legacy agent becomes less costly, manufacturers of novel targeted therapies must re-evaluate price-setting, rebate strategies, and bundle offers that include diagnostics or services. Our full report models a range of pricing and access scenarios, showing how generic erosion catalyzes both downside risk for incumbents and opportunity for novel agents that demonstrably improve depth of response or time-to-next-therapy.
Modality-specific considerations for corporate planning
-
Bispecific antibodies: Rapid approvals and commercial uptake put a premium on outpatient logistics, dosing schedules, and demonstrable real-world safety. Market entrants should prioritize simplified delivery and strong safety management programs to gain rapid formulary traction.
-
CAR-T therapies: Reduced monitoring requirements and streamlined REMS increase scalability, but manufacturing capacity, cost-per-treatment, and center accreditation remain gating factors. Strategic partnerships with contract manufacturers and hub-and-spoke delivery models are critical near-term priorities.
-
Oral next-generation targeted agents (CELMoDs and others): Positive Phase 3 data for oral agents expands late-line options and creates pressure for head-to-head positioning versus biologics in certain niches. Companies should invest in biomarker strategies and adherence programs to safeguard real-world effectiveness.
-
ADCs and other targeted therapies: Regional approvals and combination approvals are creating niche pockets of opportunity — particularly where tolerability profiles support long-term dosing in maintenance settings.
What PW Consulting’s report contains — practical assets for 2026 decision-makers
Our full market study is designed as an operational playbook with the following deliverables:
-
Robust market-sizing and forecasting model (2020–2032) with scenario functionality to stress-test outcomes under different clinical, regulatory, and pricing assumptions. Users can run custom scenarios for launch timing, uptake, and price elasticity.
-
Competitor intelligence modules that synthesize clinical trial readouts, recent approvals, pipeline timing, and strategic intent for leading firms. These modules include SWOT-style implications for commercialization and M&A.
-
Commercial playbooks for each modality (bispecifics, CAR‑T, monoclonal antibodies, CELMoDs, proteasome inhibitors, ADCs), covering access strategies, stakeholder engagement maps, and payer negotiation scripts tailored to current MRD-focused reimbursement frameworks.
-
Deal origination and valuation matrices prioritizing licensing, bolt-on acquisition targets, and manufacturing partners; our valuation sensitivities capture the impact of generic entry, label expansions, and accelerated approval conversion requirements.
-
Health‑economic models and country-level reimbursement pathways (coverage decision timelines, HTA submission templates, and price/volume levers) — with clear recommendations on evidence generation required to secure favorable coverage in 2026.
-
Go-to-market readiness checklists for commercial and medical teams, including patient support design for high-touch therapies and digital health options to optimize adherence and outcomes.
How 2026 decisions should change based on our analysis
-
Prioritize combination strategies that align with MRD-driven endpoints. Given regulatory emphasis on MRD, companies should design pivotal combinations and confirmatory plans that address both accelerated approval criteria and payer evidence requirements.
-
De-risk launches through service-led differentiation. For high-cost modalities, the path to formulary acceptance runs through demonstrated reductions in total cost of care, predictable safety profiles, and scalable patient support that lowers real-world complication rates.
-
Pursue manufacturing and commercial partnerships proactively. Capacity constraints for cell therapies and the need for geographic reach favor strategic alliances or M&A focused on fill/finish and cold-chain logistics.
-
Use flexible valuation frameworks. The interplay of generic backbone erosion, accelerated approvals, and real-world evidence conversion creates valuation upside — and downside — that must be modeled dynamically for 2026 M&A decisions.
Why this preview — and why now
We publish this preview to surface the strategic contours that will matter for 2026 while withholding granular, commercially sensitive segment breakouts that are included in the full report. The combination of ongoing approvals, regulatory guidance around MRD, simplification of monitoring for selected cellular therapies, and the timing of generic entry for legacy agents creates a compressed decision window: execute now on evidence generation, manufacturing scale, and payer alignment or accept materially higher barriers to entry after key approvals and formularies harden.
Next steps
For pharmaceutical and biotech executives planning near-term launches, investors evaluating M&A targets, or payer organizations preparing coverage frameworks, PW Consulting’s complete report provides the actionable forecasts, competitor playbooks, and reimbursement strategies required to convert clinical innovation into commercial success in 2026 and beyond. Visit our publication page to access the full study and the executable models that underpin our forecasts.
For detailed analysis of this topic, please visit the official page: Targeted Drugs For Multiple Myeloma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com