

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: New Biomass Power Equipment Market Insight Forecasts 6.99% CAGR

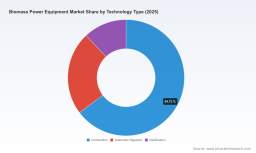
Biomass Power Equipment Market: Strategic Intelligence for 2026 Decision-Making
As energy transition priorities harden and decarbonization policies proliferate, biomass power remains one of the most actionable routes for utilities, project developers, and industrial energy consumers seeking dispatchable renewable baseload or combined heat-and-power (CHP) solutions. PW Consulting’s latest market study on the Biomass Power Equipment Market synthesizes macro trends, competitive positioning, technology pathways and investment-grade decision tools designed to inform capital allocation and go-to-market choices in 2026 and beyond.
Biomass Power Equipment Market
Market snapshot: scale, trajectory, and what it means for 2026
Our modelling traces the market’s trajectory from an estimated industry base of roughly $89.5 billion in 2020 to about $125.5 billion in 2025, driven by a blend of retrofit activity, new-build CHP projects and rising feedstock commercialization. The market is projected to expand further through the 2026–2032 forecast window at a compound annual growth rate of approximately 7%, reaching the low‑to‑mid hundreds of billions by the end of the period.
Biomass Power Equipment Market
For executives and investment committees eyeing 2026 as a pivotal planning horizon, three implications emerge immediately: (1) deployment windows remain open for large-scale equipment providers and modular gasifier suppliers as demand scales, (2) policy tailwinds create near-term subsidy and financing opportunities that can materially alter project economics, and (3) operational readiness — in the form of flexible fuel handling, grid integration and O&M competence — will differentiate winners from the pack.
Biomass Power Equipment Market
Why this report matters to corporate strategy in 2026
- Actionable sizing for capital planning. The report provides a consolidated market-size view and scenario-level revenue trajectories to calibrate capacity additions and supply-chain commitments for the next five to seven years.
- Policy and incentive modelling tied to project NPV. We translate major policy levers — from regional renewable targets to investment tax credits — into scenario outcomes that materially affect payback and IRR assumptions for projects initiated in 2026.
- Technology and feedstock risk assessment. Rather than high-level commentary, the study offers a hierarchical risk framework to quantify feedstock price exposure, combustion versus gasification pathway risks, and lifecycle carbon accounting sensitivities that are critical for financing decisions.
- Procurement and vendor selection playbooks. The report includes procurement checklists, contractual levers for lead‑time management, and vendor evaluation matrices that counsel on negotiated warranties, spare-parts pooling and performance guarantees.
Core growth drivers and headwinds (what to prioritize in 2026)
- Policy acceleration. Binding renewable targets and carbon pricing continue to tilt economics toward biomass in several jurisdictions. Where incentives (investment tax credits, feed-in premiums) are available, they compress payback timelines for projects started in the 2026 window.
- Carbon economics. Elevated carbon allowance prices increase the delta in operating cost between coal and biomass-fired assets; this drives conversion projects and coal-to-biomass retrofits where infrastructure permits.
- Feedstock and logistics risk. Feedstock availability and pricing volatility — for example, industry monitoring showed wood pellet benchmarks around the low hundreds of dollars per metric ton in late 2024 — remain a primary source of operating uncertainty and must be hedged via long-term contracts, diversified feedstock strategies or vertical integration.
- Capex and component constraints. Equipment and balance-of-plant components continue to command significant capital intensity; grate stoker systems and related plant modules exhibited multi‑million-dollar per-MW cost ranges in recent projects, affecting project sizing and financing structures.
Competitive landscape: what leading suppliers are doing
The supply side of biomass power equipment reflects a mix of large engineering groups delivering turnkey plants and specialist manufacturers catering to small-to-medium deployments. While the market retains a degree of fragmentation with meaningful opportunities for new entrants, incumbent capabilities around turnkey delivery, flue gas treatment, and turbine integration are decisive in large projects.
- Valmet (Espoo, Finland). Strengths: end-to-end CHP offerings and deep experience in fluidized bed and grate technologies. Strategic implication: its turnkey orientation makes it a candidate for utility-scale tenders and partner of choice where single-vendor responsibility is prioritized. Recent commissioning activity in Asia underscores its execution strength in export markets.
- ANDRITZ (Graz, Austria). Strengths: fluidized bed combustion expertise and project EPC capability. Strategic implication: attractive for projects that prioritize fuel flexibility and modular scalability; its order pipeline in Europe signals continued demand for medium-scale installations.
- Babcock & Wilcox (Akron, USA). Strengths: vibrating grate and hybrid stoker systems optimized for co-firing. Strategic implication: well positioned for operators seeking retrofit solutions where co-firing with coal or biomass blends is the transition path. Recent grid-connection milestones in the UK demonstrate commercial readiness.
- Mitsubishi Power (Yokohama, Japan). Strengths: integration of high-efficiency steam cycles and advanced combustion controls. Strategic implication: technology leader for projects targeting operational efficiency gains and emissions optimization; recent efficiency milestones indicate near-term tech maturation.
- Siemens Energy and GE Vernova. Strengths: turbine and generator technologies adapted to biomass plant specifics, plus control systems for variable fuel inputs. Strategic implication: preferred partners when integrating biomass generators into broader utility fleets or hybrid renewable portfolios.
- Regional specialists (e.g., Kraftwerke Mannheim, Zibo Zichai). Strengths: localized operational experience and small-to-medium scale gasifier manufacturing. Strategic implication: competitive choices for regionally specific projects where local supply chains and service networks matter.
Recent vendor activity — from Valmet’s 2024 commissioning in Japan to ANDRITZ’s orders and Babcock & Wilcox’s commercial grid connections — confirms active procurement windows and an appetite for proven, modular solutions. These vendor moves should influence procurement timetables for 2026 project pipelines.
What the report contains — practical, decision-ready outputs
- Executive dashboard and investment heatmaps. Quick-read views that rank markets and subsegments by near-term investability, policy support intensity and feedstock risk.
- Scenario economics and sensitivity models. Spreadsheet models that allow buyers to toggle carbon price, feedstock cost, capex and subsidy assumptions to produce project-level NPVs and IRRs.
- Vendor benchmarking and procurement templates. Scored matrices, RFP templates and contract clauses tailored to delivery and performance risk mitigation for boilers, turbines and gasifiers.
- Technology deep dives. Comparative analysis of combustion, anaerobic digestion and gasification pathways, with operational trade-offs, scaling vectors and maintenance profiles.
- Feedstock strategy playbook. Practical guidance on long-term offtake, co-processing options, pelletization economics and logistics optimization.
- Regulatory and carbon-policy tracker. A living annex summarizing major policy instruments and how they translate to cashflow impacts for projects initiated in 2026.
How to use this intelligence in 2026
- For corporate strategy teams: Use the scenario models to stress-test capital allocation choices under different subsidy and carbon-price regimes. Prioritize projects with flexible fuel capability if regulatory uncertainty is high.
- For project developers: Align procurement calendars with vendor lead times highlighted in the report; consider staged procurement to manage parts supply and commissioning risk.
- For investors and lenders: Apply the report’s standardized due-diligence checklist to evaluate off-take security, feedstock contracts and technology performance guarantees before term-sheet commitments.
- For equipment manufacturers: Use the competitive benchmarking to refine product roadmaps — efficiency improvements, lower O&M footprints and fuel-flexibility features deliver measurable differentiation.
Final perspective: a 2026 playbook
Biomass power equipment is entering a phase where policy tailwinds, carbon economics and technology maturation combine to create discrete windows of commercial opportunity. Projects that secure feedstock, lock-in favorable incentive structures, and partner with vendors that can guarantee delivery and performance will enjoy superior economics. Conversely, projects that neglect feedstock diversification or underestimate component lead times face the dual risk of cost overruns and missed revenue windows.
PW Consulting’s Biomass Power Equipment Market report is designed as a practical, transaction‑oriented toolkit for 2026 decision-makers — combining market sizing, scenario economics, vendor intelligence and procurement instruments. The public summary conveys the directional growth case and strategic implications; the full report includes the granular segmentation, downloadable financial models and vendor scoring that underpin defensible capital decisions.
Next steps
Stakeholders ready to convert strategic insight into action are invited to review the full research package for complete segmentation data, the detailed vendor scorecards and the ready-to-use financial models. Access to these materials will enable CFOs, strategy leads and project developers to move from directional conviction into executable project timelines for 2026.
For detailed analysis of this topic, please visit the official page: Biomass Power Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com