

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Millimeter-Wave Radar for Unmanned Driving Market to Expand at 19.7% CAGR — From USD 16.43B in 2025 to USD 48.73B by 2032

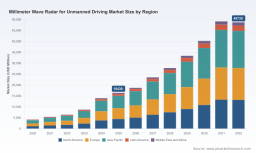
Millimeter Wave Radar For Unmanned Driving Market — Strategic Briefing for 2026
PW Consulting presents a high-conviction executive briefing derived from our forthcoming Millimeter Wave Radar For Unmanned Driving Market report. Built for boardrooms, corporate strategy teams, and senior product leaders weighing investment or partnership choices in 2026, this note synthesizes the macro trajectory, competitive dynamics, and the practical decision levers that will shape winners and losers in the next phase of automotive autonomy.
Millimeter Wave Radar For Unmanned Driving Market
Market Trajectory: A rapid, but non-linear, growth story
The mmWave radar market for unmanned driving has moved from niche sensing to a core enabler of automated mobility. Our base-year assessment (2025) places the global market at USD 16,430.0 Million, following a compound annual growth rate (CAGR) of 19.7% over the historical 2020–2025 period. The market expands further under our central forecast through 2030, reflecting accelerating adoption across ADAS tiers and early unmanned platforms, with a projected peak in the broader forecast window before near-term normalization as technology maturates and price erosion takes hold.
Millimeter Wave Radar For Unmanned Driving Market
For 2026 decision-making, the headline is simple: volume and value expansion continue, but the path is conditioned heavily by supply-side capacity, regulatory timing, and the competitive moves of a concentrated supplier base. In short, the opportunity is large; the window to shape platform-level requirements and supplier economics is short.
Millimeter Wave Radar For Unmanned Driving Market
Why the report matters to executives in 2026
- Timing of procurement and integration decisions: With production milestones and giga-scale series orders emerging, procurement teams must align multi-year sourcing to avoid costly rework or single-source exposure.
- Technology differentiation: Advances in SoC-level processing, 4D imaging radar, and digital-on-chip approaches are reshuffling which suppliers can convert trials into mass production.
- Regulatory and spectrum risk: Mandates on active safety features and heterogenous regional spectrum allocations require scenario-driven product roadmaps and geo-specific deployment plans.
- Supply chain resilience: Semiconductor availability and RF manufacturing capacity remain primary bottlenecks; strategic inventory and supplier development will materially impact time-to-market.
What PW Consulting’s report delivers (practical contents)
The published study is engineered for operations and strategy execution, not only market commentary. Key actionable modules include:
- Transparent market sizing and a reproducible forecast model (2026–2032) with scenario toggles for supply disruption, regulation shifts, and pricing pressure.
- Supply chain map and sourcing heatmap highlighting chokepoints across RF MMIC, front-end assemblies, and test & calibration capacity.
- Technology deep-dives — performance trade-offs between legacy frequency bands and emerging high-resolution 4D imaging approaches, with integration guidance for sensor-fusion stacks.
- Competitive playbooks with capability matrices, OEM win themes, and supplier readiness checklists for pilot-to-production scale-up.
- Commercial models — pricing elasticity, expected ASP trends, and tender negotiation frameworks tuned for 2026 procurement cycles.
- M&A and partnership targeting framework mapping strategic targets to capability gaps (radar SoC IP, production tooling, perception software).
- Regulatory and spectrum impact scenarios that translate policy timelines into revenue and launch-risk metrics.
Competitive landscape — concentrated but dynamic
The mmWave radar ecosystem is meaningfully concentrated: our concentration metrics indicate that the top three suppliers account for nearly half of market share (CR3 ~48.5%), and the top five approach two-thirds of the market (CR5 ~62.8%). That structure produces a dual dynamic—large incumbents move supply curves and set industrial standards, while aggressive specialists drive disruptive technology adoption.
Profiles and strategic takeaways for leading players:
- Robert Bosch GmbH (Gerlingen, Germany): Strong in SoC-level solutions, Bosch’s SX600/SX601 family demonstrates an integrated approach—combining radar signal processing with AI inference on-chip. Strategic implication: incumbents with SoC IP are positioned to capture higher-value system content if integration paths with perception software are secured early.
- Continental AG (Hanover, Germany): Continental’s 6th-generation ARS620 program has reached large-scale production milestones and has secured multi-year series orders. Strategic implication: suppliers controlling production scale and tiered pricing can squeeze smaller entrants unless differentiation on resolution or cost is compelling.
- Denso Corporation (Kariya, Japan): Focused on long-range detection and robust sensor fusion. Strategic implication: OEMs targeting highway automation and urban robotaxi corridors will prioritize suppliers with proven long-range performance and integration support.
- Valeo, HELLA, Aptiv, ZF: These tier-one integrators offer modular radar modules and system-level integration, making them natural partners for vehicle manufacturers seeking turnkey sensing stacks.
- Arbe Robotics & Uhnder: Newer entrants specializing in 4D imaging and digital radar-on-chip are proving disruptive in perception stacks, showcased at industry events and early partnerships. Strategic implication: platform owners should pilot imaging radar for edge-case detection while validating mass-production economics.
- Texas Instruments & Infineon: As core semiconductor suppliers, they remain critical for roadmap certainty. Strategic implication: locking long-lead agreements with chip-level suppliers is a material hedging instrument against supply volatility.
Recent signals that should shape 2026 strategy
- Major production milestones and series orders from top suppliers are compressing time-to-market expectations for OEMs and Tier-1s; alignment on standards and interface definitions is urgent.
- New SoC launches and co-development partnerships (notably between leading semiconductor vendors and traditional automotive suppliers) are accelerating feature parity across supplier classes.
- Regulatory mandates for active safety and regional spectrum licensing timelines will create heterogenous deployment windows—requiring geographically differentiated commercialization plans.
- Persistent semiconductor supply and skilled RF labor shortages increase the value of localized manufacturing and supplier diversification strategies.
Strategic recommendations for 2026 decision-makers
- Adopt a phased supplier engagement model: secure capacity with incumbents for baseline volumes while contracting pilot slots with specialist imaging-radar firms to validate edge-case performance.
- Negotiate chip and module agreements with explicit escalation and penalty clauses tied to spectrum/regulatory delays; prioritize suppliers with multi-node fabrication or alternative silicon pathways.
- Invest in sensor-fusion middleware and perception validation frameworks now—hardware differentials narrow quickly; software-defined advantages persist longer.
- Prioritize talent and automation investments in RF test and calibration; these are the operational enablers of quality at scale and a hedge against labor scarcity.
- Embed regulatory scenario planning into product launch gates—spectrum allocation or mandate timing can shift go-to-market by quarters, not weeks.
- Use an M&A playbook to acquire niche capabilities (4D imaging IP, radar SoC design houses, or specialized test equipment suppliers) rather than attempting in-house greenfield builds under time pressure.
Risks to monitor and leading indicators
Key risks that should be tracked continuously include semiconductor availability, spectrum allocation outcomes in priority markets, and the cadence of OEM series adoption announcements. Leading indicators we monitor weekly are supplier-volume commitments, fab utilization rates for high-frequency processes, regulatory docket movements on radar spectrum, and integration wins announced by OEMs and robotaxi platforms.
Conclusion — why engage with the full study
This briefing highlights the strategic inflection points executives must act on in 2026: the market’s growth trajectory is substantial, consolidation and technology races are accelerating, and the margin for execution error is shrinking. PW Consulting’s full report supplies the operational-level analyses, procurement templates, modeled scenarios, and supplier scorecards required to convert strategic intent into measurable outcomes.
For deployment-ready insights — including granular regional and application segmentation, supplier-level commercial benchmarks, and our interactive forecasting model — access the complete Millimeter Wave Radar For Unmanned Driving Market report at PW Consulting. The publicly released briefing intentionally omits detailed subsegment tables and contract-level intelligence to preserve client differentiation; the full dataset and playbooks are available to licensed subscribers and corporate clients.
For detailed analysis of this topic, please visit the official page: Millimeter Wave Radar For Unmanned Driving Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com