

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti‑Fog Polycarbonate Film & Sheet Market Poised for 5.45% CAGR in 2026–2032 Forecast

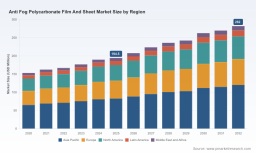
Anti-Fog Polycarbonate Film and Sheet Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive snapshot
PW Consulting’s latest market study on Anti-Fog Polycarbonate Film and Sheet delivers an evidence-based line of sight for executives planning through 2026 and beyond. Using 2025 as the base year, our top-line forecast shows the market expanding from an estimated USD 194.5 Million in 2025 to approximately USD 282.0 Million by 2032, representing a compound annual growth rate (CAGR) of 5.45% over the 2026–2032 forecast window. These headline numbers capture both steady underlying demand across safety, architectural and display end-markets and a wave of structural change on the supply side that will determine winners and losers in the next 18–36 months.
Anti Fog Polycarbonate Film And Sheet Market
Why 2026 is a strategic inflection point
-
Decision cadence is accelerating. Capital allocation, contracting and product roadmaps locked in during 2026 will crystallize players’ competitive positions for the remainder of the decade. Manufacturers that act early on capacity alignment, formulation innovation and regulatory compliance will capture disproportionate share of the moderate but persistent growth trajectory outlined above.
Anti Fog Polycarbonate Film And Sheet Market -
Cost and regulatory shocks are amplifying execution risk. Recent feedstock price volatility and the emergence of new regulatory constraints are raising both input cost uncertainty and compliance costs—pressures that require tactical changes in procurement, pricing and product formulation.
Anti Fog Polycarbonate Film And Sheet Market -
Product differentiation is becoming table stakes. With market concentration moderately elevated (CR3 and CR5 metrics indicate top-tier incumbents control a meaningful share), specialized coatings (e.g., long-duration hydrophilic anti-fog, PFAS-free chemistries) and service capabilities (custom fabrication, certified supply chains) are decisive competitive levers.
Market dynamics shaping strategic choices
-
End-market mix and technology convergence: Growth in medical and safety visors, architectural glazing, refrigerated displays and select automotive applications continues to underpin demand for anti-fog polycarbonate substrates. At the same time, display and optical performance requirements are encouraging suppliers to combine anti-fog functionality with anti-scratch, UV-stability and optical-grade clarity.
-
Supply chain and cost pressures: Feedstock dynamics have tightened supplier margins and prompted near-term cost pass-through conversations across the value chain. Procurement teams should anticipate continued volatility and adopt hedging and supplier diversification strategies rather than relying on historical spot-price patterns.
-
Regulatory and sustainability drivers: Tighter chemical regulatory controls and growing buyer demand for sustainable solutions are accelerating R&D toward low-impact, durable anti-fog treatments. At least one major coating supplier has launched PFAS-free alternatives, signaling a technology pivot that will influence product acceptance in environmentally regulated markets.
-
Capacity and geography: Strategic capacity expansions announced in late 2025 and early 2026 are set to reshape regional supply balances. New multiwall and sheet production facilities and increased coating capacity will ease supply in targeted end-markets but will also raise competitive intensity in commodity-grade segments.
Competitive landscape — practical reading
The market exhibits a moderate level of concentration: the three- and five-firm concentration ratios indicate that top suppliers hold substantial influence but do not form an impenetrable oligopoly. This structure creates space for specialized and regional players to thrive alongside global raw-material and coating specialists.
-
Global integrated suppliers: Firms with upstream polymer capabilities and proprietary coating systems retain advantages in scale, product consistency and certified supply chains. Their strategic playbooks center on deep technical partnerships with OEMs, multi-year supply agreements, and platform-based product families that bundle anti-fog, anti-scratch and UV resistance.
-
Regional manufacturers and fabricators: A cohort of agile manufacturers—particularly in Asia—competes on fast lead times, custom fabrication and cost competitiveness. These players are attractive partners for regional OEMs and distributors seeking tailored sheet dimensions and rapid prototyping services.
-
Coating specialists and licensors: Independent coating technology companies differentiate through formulation IP (including environmentally preferable chemistries) and application know-how. Their success depends on licensing deals, turnkey coating services and co-development agreements with sheet manufacturers and OEMs.
Notable vendor developments in the last 18 months illustrate these dynamics: a capacity expansion partnership creating a large North American multiwall sheet facility scheduled for 2026; the commercial introduction of PFAS-free anti-fog coatings; and public guidance from a regional manufacturer on extended durability formulations for high-humidity environments. Individually these moves matter; aggregated, they signal a market pivot toward higher-value, compliance-forward offerings.
Implications for corporate decision-makers in 2026
PW Consulting’s research translates to six concrete imperatives firms should prioritize this year.
-
Recalibrate procurement and pricing strategies: Move from reactive spot purchasing to structured supplier agreements with embedded cost-remediation triggers. Incorporate index-linked clauses, multi-supplier panels and strategic safety stocks to mitigate feedstock shocks.
-
Differentiate through formulation and certification: Invest selectively in coating partnerships or licensing arrangements that deliver PFAS-free and long-duration anti-fog performance. For OEMs in regulated sectors, prioritize suppliers with transparent supply-chain certifications and compliance roadmaps.
-
Optimize capacity and footprint decisions: Evaluate incremental capacity versus contract manufacturing. Use scenario models to stress-test capacity investments against demand shifts from key end-markets (medical PPE, architectural glazing, refrigerated display sectors).
-
Embed sustainability in product roadmaps: Develop a staged substitution plan for legacy chemistries and align product introductions with emerging regulatory timetables. Marketing messaging tied to demonstrable lifecycle benefits can unlock premium pricing in some segments.
-
Pursue targeted M&A and alliance plays: Look to acquire capabilities (coatings, surface treatments, fabrication tech) that accelerate time-to-market for value-added products. Strategic alliances with coating specialists or regional fabricators can be a lower-capex route to capability acquisition.
-
Strengthen commercial go-to-market and warranty frameworks: As product complexity grows, customers will demand clearer warranties, performance metrics and replacement policies. Standardized test protocols and third-party validation will reduce buyer friction.
What the full PW Consulting report delivers (select highlights)
This preview intentionally avoids disclosing segment-level allocations and company revenue breakdowns to preserve the competitive value of our proprietary analysis. The complete report, however, equips decision-makers with operational tools and diagnostics they can act on in 2026:
-
Actionable scenario forecasts and demand-sensitivity models designed for supply-planning and investment appraisal across a seven-year horizon.
-
Supplier scorecards and an RFP playbook to accelerate qualification of coated sheet and film providers, including technical KPIs, environmental compliance checklists and cost-to-serve templates.
-
Coating technology matrix mapping durability, environmental footprint and cost implications—plus a short-list of proven formulation partners for rapid pilot programs.
-
Regulatory impact map with timelines and compliance pathways tailored to major markets; a decision tree to prioritize reformulation, relabelling or market exit options.
-
Commercial negotiation frameworks for long-term supply agreements, including model contractual clauses for cost pass-through, quality disputes and technology migration.
-
Deal tracker and capacity atlas summarizing recent plant openings, announced expansions and strategic partnerships—presented with confidence intervals to help planners assess availability risk.
How to use this intelligence in Q1–Q2 2026
-
Procurement leaders: Use the scenario models to rebalance supplier exposure before mid-year contract renewals; prioritize suppliers offering validated low-emission coatings and multi-year price hedges.
-
R&D and product managers: Launch two parallel pilots—one focused on environmentally preferable anti-fog chemistries and another on hybrid anti-fog/anti-scratch solutions—to de-risk product transitions while protecting legacy volumes.
-
Strategy and corporate development teams: Screen acquisition targets among coating specialists and regional fabricators to accelerate vertical capability acquisition without committing to brownfield expansions outright.
-
Regulatory and quality teams: Build cross-functional compliance playbooks that convert regulatory requirements into internal product acceptance thresholds and supplier audit protocols.
Final note — a preview, not the whole story
This commentary is crafted as a strategic preview: it outlines the major trends, competitive dynamics and pragmatic decisions that will determine market positions through 2026. In keeping with the “preview” purpose, this piece omits our full segmentation tables and company-level revenue and market-share data—analytics that are available in the complete PW Consulting study and its accompanying datasets.
Next steps
For procurement teams, product leaders and corporate development teams seeking the full suite of analytics—including downloadable models, supplier scorecards and regulatory roadmaps—contact PW Consulting to access the full Anti-Fog Polycarbonate Film and Sheet Market report and workbook. Our analysts can also deliver a tailored briefing and a 90-minute workshop to translate the report’s scenarios into an actionable 2026 playbook for your organization.
For detailed analysis of this topic, please visit the official page: Anti Fog Polycarbonate Film And Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com