

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Logistics and Cold Chain Market to Expand at 8.5% CAGR, Fueling a Global Cold Storage Boom
By pmarketresearch, 2026-07-13
PW Consulting Releases Strategic Insight Brief: Logistics and Cold Chain Market — A Decision-Maker’s Playbook for 2026
PW Consulting today publishes a strategic industry brief drawn from our new Logistics And Cold Chain Market report (base year: 2025). Built on a five‑year historical analysis (2020–2025) and forward projections for 2026–2032, this release is designed to equip executive teams, investors, and supply‑chain leaders with the analytical framework they need to make confident, high‑stakes decisions in 2026. The global market is forecast to expand at a compound annual growth rate (CAGR) of 8.5% across the forecast window; total market size has risen materially since 2020 and is projected to more than double by the end of the outlook period. This brief articulates why those topline dynamics matter operationally—and what to do about them—while reserving the full breakdown of proprietary segment-level datasets for report subscribers and our website.
Logistics And Cold Chain Market
Why this report matters for 2026 decisions
- Momentum and scale: The cold chain market moved from a post‑pandemic recovery phase into sustained expansion through 2025; our forecasting shows this acceleration persisting into the late 2020s. That creates a window for capacity investments, differentiated service models, and cross‑border offerings that capture outsized returns.
- Fragmentation creates opportunity: Measured concentration tells a clear story: the market remains fragmented (CR3 and CR5 levels indicate low to moderate concentration), so there is room for targeted M&A, regional roll‑ups, and platform plays that meaningfully alter competitive position.
- Risk is operational and geopolitical, not only commercial: Energy and labor cost pressures, evolving GDP‑grade regulation, and shipping disruptions are now first‑order determinants of service reliability and margin. The right 2026 strategy balances growth with resilience.
- Technology separates winners from also‑rans: Real‑time visibility, autonomous storage, and predictive maintenance are no longer ‘nice‑to‑have’. Firms that can operationalize IoT telemetry and data‑driven exception management will capture share and reduce recall risk.
Key market dynamics shaping choices in 2026
- Energy intensity and sustainability mandates: Refrigeration drives a disproportionate share of cold storage energy consumption—addressing this is essential to protect margins and meet corporate decarbonization goals. Our report models energy intensity scenarios and provides an investment prioritization sequence for refrigeration retrofits and hybrid energy integration.
- Regulatory tightening around pharma cold chain: GDP and comparable national guidelines mandate continuous monitoring, validated processes, and auditable cold chain paths. Compliance is table stakes; our compliance risk register highlights process gaps most likely to trigger costly product recalls.
- Labor and automation tradeoffs: Specialized cold chain labor carries a measurable premium due to training and safety requirements. We quantify the break‑even horizons for automation investments across different warehouse archetypes so leaders can make capital allocation decisions with confidence.
- Supply route fragility: Recent maritime disruptions have lengthened critical routes, increasing inventory exposure to temperature excursion and spoilage risk. The brief outlines contingency routing strategies and contractual language to transfer or mitigate transit risk.
- Recall and quality risk: Temperature excursions remain a material source of drug recalls and product loss. Our scenario analysis links visibility investments to reductions in expected recall frequency and severity—information crucial when evaluating technology vendors.
What the full report contains: practical tools and executable frameworks
PW Consulting’s Logistics And Cold Chain Market report was developed as an operational playbook for the executive who must act in 2026. Rather than a purely descriptive study, the report contains hands‑on modules designed to be used in active decision cycles:
Logistics And Cold Chain Market
- Market sizing and topline forecasts (2020–2032) with scenario toggles for energy price shocks and trade disruptions.
- Decision matrices for network design (greenfield vs. brownfield), including TCO models that align CAPEX, OPEX, and service level targets.
- Vendor and technology scorecards that evaluate IoT platforms, temperature‑controlled transport providers, and warehouse automation vendors against real‑world KPI targets.
- Contract negotiation playbook and sample SLAs that translate quality and visibility requirements into enforceable commercial terms.
- Risk register and mitigation templates for product integrity, regulatory compliance, and transit contingency planning.
- M&A diligence checklist for acquirers: integration pitfalls, capex backlog assessment, and synergies quantified across multiple operational archetypes.
Competitive landscape: who to watch—and why
The sector is populated by global integrators, specialized cold chain operators, and logistics incumbents who have invested heavily in visibility and temperature control. Our competitive analysis synthesizes public disclosures, recent strategic moves, and capability mapping to identify where incumbents are investing and where white‑space remains.
Logistics And Cold Chain Market
- DHL Supply Chain (Bonn): A global leader in temperature‑controlled logistics with end‑to‑end solutions and IoT‑enabled monitoring. Recent investments in regional GDP hubs signal an emphasis on pharma corridor dominance.
- Kuehne + Nagel (Schindellegi): Known for its PharmaChain platform and multi‑modal cold chain capabilities—strengths lie in air and sea lanes combined with enhanced visibility tools.
- DB Schenker (Essen): Offers GDP‑compliant healthcare logistics and automated temperature‑controlled warehousing—positioned to serve regulated life sciences segments.
- UPS Healthcare (Atlanta): Delivers comprehensive temperature regimes including ultra‑low solutions and specialized handling protocols, making it a go‑to for complex pharma shipments.
- FedEx Logistics (Memphis): Visibility platforms and Priority Alert facilities underpin a capability set tailored to time‑critical biologics and high‑value shipments.
- A.P. Moller‑Maersk (Copenhagen): Leveraging reefer container expertise and global lanes, Maersk is integrating standards and tracking to strengthen long‑haul cold chain reliability.
- Americold & Lineage Logistics (U.S. bases): Large temperature‑controlled warehousing footprints with growing automation and consolidation activity—recent acquisitions and facility expansions illustrate an aggressive capacity strategy.
- Regional specialists (e.g., Nichirei, Swire Cold Storage, U.S. Cold Storage, Cencora World Courier): These players offer deep regional expertise—critical partners or acquisition targets for firms seeking local scale and regulatory know‑how.
Notable recent moves—facility expansions, strategic acquisitions, platform upgrades, and standards partnerships—underscore the arms race between scale, digital visibility, and regulatory compliance. We map these actions to tactical implications for competitors and potential partners in the full report.
How PW Consulting frames strategic choices for 2026
- Invest selectively in visibility: Prioritize sensor networks and analytics where recall risk or regulatory exposure is highest. Our ROI ladders show which visibility investments shorten decision cycles and reduce expected product loss.
- Hedge transit risk with diversified routing and contractual levers: Alternate routing, multi‑carrier sourcing, and dynamic inventory positioning reduce exposure to maritime chokepoints and trade volatility.
- Use M&A to buy digital and geographic capabilities, not just capacity: Targets that bring automation, validated pharma handling, or platform telemetry accelerate capability build faster than greenfield alone.
- Optimize energy strategy as a margin lever: Integrate energy consumption modelling into site selection and retrofit decisions; tie sustainability projects to tangible OPEX reductions and compliance timelines.
- Operationalize regulatory readiness: Embed GDP requirements into SOPs, vendor contracts, and audit trails to reduce the probability and cost of regulatory interventions.
Executive takeaway
For leaders making strategic bets in 2026, the logic is clear: scale and growth are present, but value will accrue to firms that combine capacity expansion with superior operational resilience and technology‑enabled visibility. Market fragmentation creates acquisition and partnership pathways for disciplined capital—while regulatory, energy, and geopolitical forces demand that growth decisions be paired with robust risk mitigation. PW Consulting’s Logistics And Cold Chain Market report supplies the models, playbooks, and checklists necessary to convert market momentum into sustainable competitive advantage.
Next steps
This briefing highlights the strategic contours and operational levers contained in our full report. To access the detailed data tables, proprietary segment models, regional overlays, and vendor benchmarking tools that underpin these conclusions, please visit PW Consulting’s report page or contact our industry team for a tailored briefing. Our consultants are available to run bespoke scenario workshops that apply the report’s frameworks directly to your 2026 planning process.
For detailed analysis of this topic, please visit the official page: Logistics And Cold Chain Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Heavy Industry Hydraulic Systems Market to Surge to USD 56,826.97 Million by 2032
By pmarketresearch, 2026-07-13
Heavy Industry Hydraulic System Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
As heavy industries accelerate modernization in 2026, hydraulic systems remain a critical backbone of construction, mining, material handling, and heavy manufacturing fleets. PW Consulting's latest market research — anchored on a 2025 base year and projecting through 2032 — finds a market that is recovering and recalibrating for a new technology and regulatory era. The global market is estimated at USD 40,792.05 Million in 2025 and is projected to grow to USD 56,826.97 Million by 2032, representing a compound annual growth rate (CAGR) of 4.85% over the 2026–2032 forecast period. This brief synthesizes the study’s strategic takeaways for leaders planning capital allocation, product roadmaps, and partner ecosystems in 2026, while intentionally preserving detailed segment-level figures to encourage direct access to the full report for operational planning.
Heavy Industry Hydraulic System Market
Why this report matters for 2026 decision-makers
- Timing of investment: With steady mid-single-digit growth ahead, 2026 is a tactical window for firms to accelerate investments in energy-efficient and electrified hydraulic solutions before competitive consolidation intensifies.
- Regulatory alignment: New design standards and energy-efficiency mandates are converging on heavy machinery—organisations that embed compliance and efficiency into procurement and R&D cycles will realize lower lifecycle costs and faster market acceptance.
- Supplier selection and resilience: Raw material volatility (steel pricing) and supply-chain concentration demands that procurement teams adopt dynamic sourcing and inventory hedging strategies; the report provides decision frameworks to do this without disrupting operations.
- Technology transition: Electrification and smart-hydraulics are moving from proof-of-concept to production-readiness. 2026 is the year to pilot integrated electric hydraulic power units (eHPUs), advanced control electronics, and predictive filtration strategies at scale.
Market snapshot (macro view)
Our historical analysis (2020–2025) and forecast (2026–2032) quantify a resilient market trajectory: after cyclical variability in the early 2020s, the sector returned to growth through 2024–2025 and is projected to expand at a 4.85% CAGR over the forecast. The trajectory reflects a mix of sustained demand from heavy equipment OEMs, replacement cycles prompted by emissions and efficiency regulations, and increasing adoption of electrified and digitally connected hydraulic subsystems. Importantly, market concentration is moderate — the top three firms collectively capture roughly one third of market revenues, while the top five account for approximately 44% — a structure that favors both incumbent strength and meaningful opportunities for niche players and system integrators.
Heavy Industry Hydraulic System Market
What the full report delivers — practical, transaction-ready content
PW Consulting’s Heavy Industry Hydraulic System Market report is tailored for boardrooms and operating teams that require prescriptive guidance, not just descriptive analytics. Key operational deliverables include:
Heavy Industry Hydraulic System Market
- Go-to-market playbooks for OEMs and aftermarket suppliers to accelerate adoption of energy-efficient hydraulic architectures.
- Vendor selection matrix that scores suppliers across technical capability, durability, digital readiness, global footprint, and total cost of ownership.
- CapEx prioritisation model for choosing between refurbishment, hybrid retrofits (electrified assist systems), and full-system replacements under multiple commodity-price scenarios.
- Supply-chain stress-test toolkit that models steel-price and logistics shocks, and prescribes inventory, sourcing, and contractual mitigations.
- M&A and partnership decision framework identifying where bolt-on acquisitions, strategic JV’s, or licensing agreements create asymmetrical value given market concentration dynamics.
- Scenario-based roadmaps for technology adoption (e.g., eHPUs, smart valves, integrated controls), including pilot designs, KPI templates, and expected payback windows under four adoption curves.
Competitive landscape: what leaders and challengers are doing
The market remains anchored by established hydraulics and systems integrators that blend component engineering with scale manufacturing and global service networks. PW Consulting’s competitive analysis profiles major players — including Bosch Rexroth, Parker Hannifin, Danfoss Power Solutions, Eaton, HYDAC, Kawasaki Heavy Industries, KYB, Bucher Hydraulics, HAWE, Linde Hydraulics, and machinery OEMs such as Caterpillar — and evaluates them on technology orientation, channel strategies, and strategic intent.
- Bosch Rexroth: Strong in connected, energy-optimized industrial hydraulics and system-level integration for high-duty applications; a reference point for digitalization-led offerings.
- Parker Hannifin: Broad portfolio strength and engineered solutions capability, with an emphasis on sustainability and smart hydraulics for off-highway and industrial fleets.
- Danfoss Power Solutions: Focused on energy-efficient components and the integration path to electrification — a key partner for OEM electrification efforts.
- Eaton and HAWE: Emphasise robustness and high-pressure solutions suited to demanding heavy-industry cycles and long service lives.
- Regional OEM and suppliers (Kawasaki, KYB, HYDAC, Bucher, Linde, and others): Complement global leaders with market-specific offerings and local service density.
- Caterpillar and other OEM-integrators: Continue to internalize hydraulic solutions as strategic differentiators for whole-machine performance and lifecycle service revenues.
Across this competitive set, PW Consulting identifies three winning moves for 2026: (1) cement system-level partnerships to lead electrified hydraulics pilots, (2) accelerate software and controls capabilities to monetize uptime and efficiency, and (3) deploy modular service propositions that shift customers from capex to recurring revenue models.
Technology, standards, and near-term catalysts
Several industry forces are shaping procure-and-build choices in 2026. ISO 18464:2025 introduces a design methodology that prioritizes lowest feasible energy consumption while preserving system functionality. This standard effectively raises the bar for design reviews, procurement specifications, and compliance testing, and is already influencing RFPs from large fleet owners.
On the technology front, electrified hydraulic power units and advanced valve-control architectures demonstrated at recent trade events (notably multiple showings at CONEXPO-CON/AGG 2026) signal that eHPUs and hybrid architectures are moving toward maturity. Early adopters who combine eHPU pilots with predictive filtration and digital twin-based performance validation will capture measurable fuel and emissions reductions — advantages that translate into procurement competitiveness and extended service revenue potential.
Risk factors and mitigation priorities
- Raw material volatility: Steel price swings materially impact component margins. The report provides procurement hedging strategies and low-cost design alternatives to mitigate margin erosion.
- Regulatory execution risk: Differing regional implementations of energy mandates require adaptable product architectures and flexible certification roadmaps. The report maps the compliance sequences that minimize time-to-market risk.
- Integration complexity: Electrified and software-enabled hydraulics introduce multi-disciplinary integration risk (mechatronics, thermal management, and cybersecurity). PW Consulting’s systems-integration checklist reduces pilot failure rates by aligning OEMs, Tier-1 suppliers, and test houses early in development.
How to use this research in 2026 planning cycles
Executives and product leaders can extract immediate value from the report in several ways:
- Strategic budgeting: Convert the report’s market-growth scenarios into prioritized investment lanes — R&D for eHPUs, expanded service networks, or bolt-on manufacturing capacity.
- Procurement re-design: Use the vendor-selection and supply-chain toolkits to renegotiate long-term supplier contracts with energy-efficiency and lifecycle KPIs embedded.
- Pilot-to-scale playbooks: Move beyond lab pilots by applying our stage-gated approach for eHPU and smart-valve validation across representative fleets.
- M&A screening: Apply the M&A scoring model to triage acquisition targets that accelerate electrification or regional service penetration without overpaying for commoditized component lines.
What we intentionally withhold here — and why
Consistent with the “trailer” principle for this market brief, we present the strategic context and actionable frameworks while intentionally omitting granular revenue splits by region, application, and component that are crucial for operational execution. The full report contains those detailed matrices, historical series, and customer-adoption curves required for transaction diligence and factory-level planning. Publishing those segment-level numbers in this release would blunt the report’s commercial utility and deprive clients of the proprietary modelling that underpins PW Consulting’s recommendations.
Recent market signals validating our outlook
- Trade shows and product awards in early 2026 showcased the sector’s momentum: multiple suppliers demonstrated next-generation mobile hydraulic and electrified solutions at CONEXPO-CON/AGG 2026, and an electrified hydraulic power unit (eHPU) earned recognition at World Ag Expo 2026, underscoring commercialization velocity.
- Standards and regulation developments (ISO 18464:2025 and tightening energy-efficiency mandates) are driving upstream design changes and downstream procurement specifications.
- Publicly visible supplier activity — from system integrators to OEMs — points to a pattern of strategic partnerships and pilot programs aimed at validating efficiency and electrification benefits at fleet scale.
Next steps — how PW Consulting supports 2026 implementation
For organisations ready to act in 2026, PW Consulting offers tailored engagements ranging from a rapid strategic diagnostic (6–8 weeks) to full-scale implementation support covering supplier selection, pilot management, and M&A due diligence. Clients receive the complete dataset, segment-level revenue matrices, and executable roadmaps needed to convert the report’s insights into measurable improvements in cost, emissions, and uptime.
Call to action
For executives preparing 2026 capex plans, supply-chain contracts, or product roadmaps, PW Consulting’s Heavy Industry Hydraulic System Market report provides the practical, data-driven guidance required to make defensible choices. Access to the full report (including granular segmentation, model assumptions, and vendor benchmarking) is available through our research portal. Request a briefing to walk through the scenarios most relevant to your portfolio and to obtain the bespoke modules that translate strategy into implementable projects.
For detailed analysis of this topic, please visit the official page: Heavy Industry Hydraulic System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Corn Flour Market to Reach USD 8.63 Billion by 2032, Growing at a 4.25% CAGR
By pmarketresearch, 2026-07-13
Corn Flour Market 2026 Strategic Outlook — PW Consulting Advisory Brief
PW Consulting today publishes an executive advisory based on our full Corn Flour Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). This brief highlights the strategic intelligence that will be most relevant to commercial, procurement, and corporate development leaders planning their 2026 agendas. The market is on a steady expansion path: our model projects a compound annual growth rate (CAGR) of 4.25% across the 2026–2032 forecast window, with global revenue expanding from an estimated USD 6.45 Billion in 2025 to roughly USD 8.63 Billion by 2032. The analysis that follows shows where that growth is being generated, which commercial levers matter most, and how leading players are positioning themselves — while preserving the granular segment tables and vendor-level metrics for clients who access the full report.
Corn Flour Market
Why this report matters for 2026 decision cycles
- Timing and investment prioritization: With predictable mid-single-digit CAGR, CFOs and strategy teams can substitute conjecture with scenario-backed ROI timelines to stage capacity investments, reformulation projects, or M&A outreach during 2026–2027.
- Procurement and price risk: Volatility in corn input markets and shifting trade policy mean procurement teams must refine hedging, contract tenors, and supplier scorecards now — not later — to capture margin opportunity as demand grows.
- Product and channel innovation: Demand patterns in bakery, snacks, and convenience foods are changing ingredient specifications and tolerance for sustainability premiums. R&D and commercial teams should align roadmaps to capture value in premium and differentiated flours.
- Regulatory and market access: Standards of identity and tariff dynamics are reshaping route-to-market decisions; food safety and labeling compliance must be integrated into any go-to-market or export strategy planned for 2026.
Report contents — operational modules that drive decisions
PW Consulting designed the full Corn Flour Market report as an action-oriented toolkit rather than a static market narrative. Key modules include:
Corn Flour Market
- Market-sizing methodology and reconciled demand-supply model (historical 2020–2025, base year 2025, and detailed forecasts to 2032).
- Scenario analyses: price-shock, crop-yield stress, tariff reversals, and a low-carbon transition pathway — each with quantified P&L and working-capital outcomes for typical processor and ingredient-user archetypes.
- Input-cost and margin sensitivity dashboards that let commercial teams test pricing levers across contract types and customer segments.
- Supplier and plant-level heat maps, including capability matrices (wet vs. dry milling, nixtamalization, organic/non-GMO, gluten-free, precooked masa), plus a shortlist of acquisition and partnership targets for strategic buyers.
- Regulatory impact checklist tied to FDA standards of identity and international labeling regimes, with a compliance roadmap for export-led growth.
- Practical go-to-market playbooks for ingredient companies and CPGs: launch templates, sample commercial KPIs, and channel segmentation exercises to accelerate uptake in retail, foodservice, and industrial applications.
Market dynamics and near-term signals
The market’s steady baseline growth masks several near-term inflection points that should inform 2026 strategy:
Corn Flour Market
- Raw material context: USDA’s 2025/26 season-average forecast and forward corn futures provide a narrower band of price expectations compared with prior cycles. That offers an opportunity to reset long-term contracts and to use layered hedging rather than one-off swaps.
- Trade policy tailwinds and headwinds: Recent legal developments and tariff reversals in major markets have reopened certain sourcing options. Conversely, the previous year’s tariff actions altered flows and supplier relationships; both effects are still playing out in logistics and inventory strategies.
- Regulatory clarity: Existing standards of identity (e.g., U.S. FDA Title 21) continue to set formulation boundaries; however, enforcement focus and international acceptance of equivalents vary by market. Timely regulatory reviews reduce market-access friction for novel formulations.
- Sustainability as a differentiator: Regenerative-sourcing pilots and carbon-conscious milling (including operations powered by renewable electricity) are moving from pilot to commercial stage among large processors. Sustainability capabilities are now a procurement criterion rather than a marketing afterthought.
Competitive landscape — what incumbent and challenger moves mean for 2026
The corn flour value chain combines global-scale millers, ingredient specialists, and regional niche players. Market concentration is moderate: the top three and top five players control meaningful but not overwhelming shares — a structure that preserves opportunities for both scale-driven and niche strategies.
Strategic read on key player types:
- Global integrated processors (scale-driven play): Firms with wet and dry milling capabilities and integrated supply chains are prioritizing decarbonization, backward integration, and broadened ingredient portfolios to serve food, beverage, and industrial customers. Their scale supports longer contract tenors and captive off-take agreements.
- Specialty ingredients and formulators (margin-driven play): Companies offering texturizing solutions, gluten-free, or clean-label corn-derived ingredients compete on formulation expertise, technical service, and speed-to-launch for new product adjacencies.
- Nixtamal/masa specialists and regional champions (regional relevance play): Producers focused on traditional process knowledge and regional cuisine sustain higher value-per-ton demand in specific channels. Their domain expertise is defensible but can be challenged by scale players through capability investments or bolt-on acquisitions.
- Independent millers and co-packers (cost and specialty mix play): These providers act as critical capacity and innovation partners for CPGs and private-label brands seeking flexibility and targeted ingredient claims.
Notable company developments underscore strategic themes. Large processors have accelerated sustainability and capacity investments: for example, a leading processor introduced regeneratively sourced flours milled on renewable electricity, signaling commercialization of sustainability premiums. Another major agribusiness recently announced new downstream capacity in a Latin American production hub — a move that reshapes regional supply balances and raises potential for feedstock diversification. These shifts should inform competitor benchmarking, supplier selection, and capital allocation in 2026 planning cycles.
Implications for commercial, procurement, and M&A strategies
Translate the market trajectory and competitive moves into practical 2026 actions:
- Procurement playbook: Shift to multi-scenario contracting: tier suppliers by sustainability credentials and supply reliability, extend contract tenors where price visibility is high, and use shorter-term indexed contracts where volatility risks remain.
- Product portfolio and R&D: Prioritize formulations that reduce reliance on margin-vulnerable inputs, while capturing premium demand for clean-label, gluten-free, or nixtamalized offerings. Use ingredient substitution pilots with commercial A/B testing to accelerate adoption.
- Manufacturing and CAPEX: Stage capacity upgrades with modular investments, and evaluate brownfield vs. greenfield through our NPV templates that factor in feedstock price cycles and potential tariff scenarios.
- M&A and partnerships: Target acquisitions that fill capability gaps (e.g., specialty milling, nixtamalization, organic certifications) and consider JV models in regions where trade policy remains uncertain. Our report’s shortlist and valuation heuristics will simplify target screening.
- Pricing and commercial contracting: Adopt dynamic pricing playbooks that reconcile list-price discipline with account-level value capture, factoring in sustainability premiums and variable supply costs.
How to use this advisory during 2026 planning
Across 2026, treat the full PW Consulting Corn Flour Market report as a decision engine rather than a reference document. Recommended uses:
- Quarterly strategy reviews: run the report’s scenario stress-tests during Q1 and Q3 planning to align procurement and marketing budgets with actual market signals.
- Business case development: use our CAPEX and ROI templates to accelerate board approvals for capacity or technology investments.
- M&A diligences: leverage the supplier capability maps and our vendor shortlists to reduce screening time by weeks.
- Commercial playbook implementation: adopt the go-to-market templates to reduce launch cycle time for new ingredient SKUs by months.
Accessing the underlying datapacks
This press advisory intentionally highlights the strategic insights while withholding the full segmentation tables, regional allocations, and vendor-level data that drive transactional decisions. PW Consulting’s full report contains the complete datapacks, source methodologies, and downloadable model files that enable replication and bespoke scenario building. Client access also includes a one-hour analyst briefing to translate the findings into an operational plan tailored to your organization.
To arrange access or to commission a bespoke deep-dive for targeted markets, capacity projects, or an M&A screen aligned with your risk/return criteria, contact the PW Consulting advisory team. The full report and the downloadable datasets provide the granular intelligence required to convert the 2026 market outlook into executable advantage.
— PW Consulting, Strategic Advisory & Industry Analytics
For detailed analysis of this topic, please visit the official page: Corn Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Fender Flare Trim Market Set for 5.45% CAGR Through 2032
By pmarketresearch, 2026-07-13
Fender Flare Trim Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases an executive preview of its forthcoming Fender Flare Trim Market report (base year 2025; historical analysis 2020–2025; forecast 2026–2032). The market for fender flare trims has evolved from roughly USD 1.03 billion in 2020 to approximately USD 1.39 billion in 2025 and is projected to expand to just over USD 2.01 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.45% over the forecast period. For automotive suppliers, OEMs, private equity investors and aftermarket distributors planning 2026 budgets and strategic initiatives, the report crystallizes which moves will most likely preserve margin, accelerate share and de-risk supply chains amid rising material and regulatory pressures.
Fender Flare Trim Market
Why this report matters for 2026 decision-making
-
Actionable foresight: Our modelling translates macro demand drivers into addressable-serviceable market scenarios that map directly to portfolio decisions — from material selection and adhesive systems to channel prioritisation (OEM accessories vs aftermarket fitment).
Fender Flare Trim Market -
Timing and prioritisation: With the market set on a multi-year growth trajectory, 2026 is a pivot year for capital allocation. The preview identifies high-conviction plays versus opportunistic experiments so executives can sequence investments and avoid costly late pivots.
Fender Flare Trim Market -
Risk-adjusted roadmaps: The report contains supply-chain stress-testing and contingency playbooks keyed to raw-material volatility and regulatory shocks that are already reshaping procurement strategies for fender-related elastomers and plastics.
Market dynamics and material economics
The fender flare trim market is influenced by three converging dynamics: vehicle parc growth and personalization trends, shifting OEM accessory strategies, and raw-material cost cycles. Demand is being supported by aftermarket customization, increasing SUV and truck ownership in key markets, and OEMs’ willingness to monetize accessory bundles. At the same time, parent-material economics — especially for EPDM and other synthetic rubbers — have a direct and outsized impact on product cost, cross-supplier margin compression and inventory policy.
Notably, EPDM rubber remains a dominant material choice for edge trims because of its ozone resistance and proven durability in automotive environments; it is backed by global manufacturing footprints that provide continuity of supply for major tier suppliers. Industry-wide projections for synthetic rubber (an adjacent indicator) — moving from a multi‑billion-dollar base in 2025 toward materially higher valuations by 2032 — underscore the likely upward pressure on input costs and the imperative to incorporate material-indexed pricing clauses and forward-coverage contracts into supplier agreements.
Compliance and safety standards are another continuous constraint. Automotive-grade rubber trims are commonly required to meet flammability and performance standards (for example, flammability compliance under standards akin to FMVSS 302), and any supplier or OEM that shortcuts this dimension risks costly recalls and reputational damage. Our regulatory checklist and audit protocols in the full report are designed to make compliance a profit-preserving exercise rather than a cost center.
Competitive landscape: who’s shaping the market
The Fender Flare Trim market exhibits moderate concentration. Our market-concentration metrics indicate that the top three suppliers account for a meaningful share of revenue, and the top five consolidate more than half the market — a dynamic that creates both defensive moats for incumbents and windows of opportunity for nimble challengers.
-
Trim‑Lok, Inc. — A market leader noted for EPDM rubber trims and peel-and-stick systems using automotive-grade tapes (including 3M). Recent commercial activity highlights a renewed product catalog and expanded design guidance, alongside targeted product launches that broaden its sealing and trim portfolio for RV and automotive OEM channels. Trim‑Lok’s strength is in specification assurance and globalized documentation for OEM procurement teams.
-
Trimco — Focused on flexible plastic trims that rely on high-performance acrylic foam tapes. Trimco’s value proposition centers on ozone resistance and geometry-conforming profiles, making it a go-to for aftermarket installers seeking consistency across curved fender interfaces.
-
Johnson Bros. Roll Forming Co. — A specialist custom roll-former serving tailored OEM and LCV/HCV applications. Their lower-volume, higher-customization model is attractive to OEMs requiring application-specific cross-sections and fast iterations.
-
Bushwacker & Air Design — Both play in the accessory and OEM-channel space, offering OE-style and low-profile flares. Their presence underscores an important market axis: the migration of accessory sales into official OEM channels for higher-margin, packaged solutions.
-
Steel Rubber & Putco — Represent divergent value propositions: the former emphasizes EPDM rubber edge-trim durability and simple peel-and-stick installation; the latter delivers premium stainless-steel aesthetic solutions for higher-end buyers prioritizing finish and longevity.
Recent product and catalog activity — including Trim‑Lok’s 2025 catalog refresh and subsequent cut-to-length product introductions — indicates incumbent suppliers are doubling down on design support and configurator utilities to shorten OEM approval cycles and reduce aftermarket fitment failures. These investments create higher switching costs for OEMs and increase the commercial value of supplier tooling and validation data.
What’s in the full PW Consulting report (practical highlights)
-
Market sizing & scenario modelling: detailed base‑case and downside/upside scenarios for 2026–2032 (segmented by type, application and region — full splits available in the paid report).
-
Pricing and margin benchmarking: bill-of-materials (BOM) sensitivities, adhesive system costs, and target margin bands for OEM-supplied vs. aftermarket SKUs.
-
Supply-chain resilience playbook: supplier mapping, lead-time analytics, material-sourcing matrices and hedging strategies for EPDM and alternative polymers.
-
Competitive profiles & capabilities matrix: deep dives on 20+ suppliers, innovation scorings, channel footprint assessments and partnership-readiness indicators.
-
Go-to-market frameworks: OEM spec-approval playbooks, distributor partnership models, kit-based aftermarket packaging, and e-commerce readiness checklists.
-
M&A & partnership thesis: target screening for bolt-on acquisitions (e.g., niche roll formers, adhesive formulators, design-tool providers) and earn-out structures tuned to ramp risk.
-
Regulatory & sustainability roadmap: compliance testing sequences, flame-retardant strategies, and material-recycling pathways that meet evolving OEM sustainability scorecards.
Strategic recommendations for 2026
-
Prioritise adhesive systems and installation economics: Peel-and-stick solutions are rapidly becoming the de‑facto expectation for speed-to-fit in both aftermarket and OEM accessory lanes. Supplier partners with validated 3M-grade or equivalent adhesive solutions consistently close faster with tier‑1 procurement teams.
-
Hedge raw-material exposure through mix and contract design: Incorporate a two-pronged approach — diversify polymers (EPDM alternatives where fit-for-purpose) and adopt indexed long-term contracts with collar mechanisms to stabilize input-cost pass-throughs.
-
Invest in configurator and validation assets: Tooling a digital configurator and producing OEM-ready validation packs reduces time-to-contract and increases switching costs for buyers. Small capex here yields outsized commercial returns.
-
Segment offerings by route-to-market economics: Create clear product families for OE accessories, premium stainless trim, and high-volume aftermarket kits. Each has distinct margin, warranty and service obligations — treat them as separate P&L streams.
-
Prepare M&A pipeline for bolt-ons that add adhesive/formulation capability or niche roll-forming to secure differentiated IP and shorten delivery times.
How to use this preview
This preview is intended as a strategic compass for 2026 planning. It outlines the market architecture, competitive dynamics and the levers that will drive return on invested capital. For procurement directors, the report provides negotiation playbooks and supplier scorecards. For product and R&D leaders it offers material pathways and validation sequences. For corporate development teams it lays out acquisition screening criteria and valuation sensitivities tied to catalogue breadth and channel depth.
Next steps
PW Consulting’s full Fender Flare Trim Market report contains the exhaustive data tables, regional and application split analytics, and executable templates needed to convert insight into action. The preview intentionally omits detailed segment-level figures to preserve the commercial value of the primary research; subscribers and licensed report purchasers will receive the granular breakdowns, downloadable models and supplier contact maps that enable immediate deployment of the recommended strategies.
To obtain the full report, detailed datasets, and a complementary executive briefing, visit the PW Consulting intelligence portal or contact your PW Consulting account representative. Our analysts are available for bespoke workshops to translate report findings into a tailored 2026 execution plan.
For detailed analysis of this topic, please visit the official page: Fender Flare Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Large Power Transformers Market Poised for 4.85% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-07-13
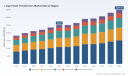
Large Power Transformers Market: Strategic Imperatives for 2026 — PW Consulting Executive Preview
As energy systems accelerate toward decarbonization, digitalization and electrification, the Large Power Transformers (LPT) market is evolving from a component procurement challenge into a strategic bottleneck for utilities, independent power producers, data center operators and national infrastructure programs. PW Consulting’s latest market study — anchored on a 2025 base year and a seven-year forecast horizon (2026–2032) — quantifies that transition: after steady growth through 2020–2025, the global market remains on an upward trajectory through 2032 with a compound annual growth rate (CAGR) of approximately 4.85%. The 2025 market baseline and the 2026–2032 scenarios in this report are designed to inform procurement timelines, capex allocation, M&A strategy and supply‑chain resilience planning for decisions made in 2026.
Large Power Transformers Market
Why 2026 is an inflection point
-
Competing demand vectors — rapid renewables integration, extensive grid modernization, expansion of high-capacity data centers and electrification of industry and transport — are creating sustained, long‑lead demand for LPTs.
Large Power Transformers Market -
Supply-side frictions — raw material tightness, limited domestic GOES production, and manufacturing capacity constraints — are lengthening lead times and elevating price volatility. These dynamics convert what was once routine procurement into strategic risk that can materially shift project economics and timelines.
Large Power Transformers Market -
Policy and industrial initiatives in major markets are incentivizing onshore production and domestic content. Several major OEMs are responding with factory investments that will change competitive dynamics and supplier selection criteria beginning in mid‑to‑late 2026.
What the PW Consulting report delivers (practical, actionable content)
-
Robust market sizing and verified growth scenarios: segmented forecasts covering 2026–2032, stress-tested against commodity price shocks, lead‑time extensions and accelerated demand cases.
-
Buy-side playbooks for 2026 procurement cycles: RFx templates, standardization roadmaps, lead‑time hedging strategies and contracting clauses (including service and spare-parts frameworks) to reduce schedule risk and cost escalation.
-
Supplier capability maps and factory-by-factory risk ratings: manufacturing readiness, technology footprints (EHV, HVDC, GSU specialization), and workforce availability assessments to inform sourcing decisions and potential JV targets.
-
Supply-chain analytics and cost build-ups: GOES/copper/steel exposure models, pass-through scenarios and inventory optimization guidance calibrated to your balance sheet and project timelines.
-
Scenario-based investment and M&A playbook: valuation sensitivities, integration checklists and a prioritization matrix for capacity acquisitions, strategic partnerships and outsourcing options.
-
Operational resilience tools: contingency planning templates, spare‑unit pools, refurbishment strategies and aftermarket service models aimed at maximizing in‑service availability and total lifecycle returns.
Data-driven market dynamics every executive must internalize
-
Pricing pressure: Since 2019 the market has seen major input-driven price increases — independent industry assessments report transformer unit prices rising materially (e.g., sharp increases documented across power transformers and generator step‑up units). These shifts force procurement teams to model inflation into lifecycle costs rather than treating it as a one‑off adjustment.
-
Lead-time escalation: Median delivery lead times have extended into multiple years in many cases. Publicly available studies indicate average LPT lead times well beyond traditional windows, with notable instances exceeding 200 weeks for certain specifications. This is a structural change — treating lead time as a critical path item is now standard practice.
-
Raw-material and component concentration: Domestic production of key inputs remains constrained in several markets. For example, certain specialized electrical steels are produced by a very small number of domestic suppliers in North America — historically, a large share has been imported — creating single‑source exposure that must be actively mitigated.
-
Industry concentration: The LPT sector is moderately concentrated at the top end of the market. Market leaders maintain scale advantages in EHV and large‑MVA units, but mid‑sized and niche suppliers retain pockets of competitive differentiation (custom designs, rapid service response, mobile substations).
Competitive landscape: players, positioning and what recent moves imply
The competitive set continues to reorganize around regional manufacturing footprints, technological differentiation (e.g., HVDC integration, ultra‑low-loss cores, eco‑friendly dielectric designs) and aftermarket service platforms. Key manufacturers that shape near‑term dynamics include established global OEMs and strong regional players with domestic production capabilities.
-
Hitachi Energy — With a global technology portfolio spanning HVDC and high‑capacity units, Hitachi Energy’s recent multi‑hundred‑million dollar investments and announced new U.S. facility signal a strategic bet on higher onshore capacity and shortened delivery cycles for North American projects. For buyers, this shifts some negotiating leverage back toward domestic supply options over a multi‑year horizon.
-
Siemens Energy — Mobilizing new LPT production capacity in the U.S. and scaling hiring for planned facilities reflects a broader industry trend: OEMs aiming to convert long lead times into competitive differentiation by localizing critical production. Timelines for such facilities — and their ramp rates — should be factored into 2026 sourcing strategies.
-
GE Vernova — GE’s LPT capabilities, including through joint ventures, remain focused on utility-scale modernization projects and grid‑scale integrations. For asset owners, GE’s combination of manufacturing scale and project execution experience continues to be attractive where lifecycle service and global engineering resources are prioritized.
-
Hyundai Electric — Emphasizing EHV capabilities with U.S. manufacturing presence, Hyundai brings competitive pricing and proven high‑voltage designs, particularly for markets balancing cost and performance.
-
U.S.-based specialists (Virginia Transformer, Delta Star, Pennsylvania Transformer Technology, SPX Transformer Solutions, Eaton, and others) — These firms offer differentiated propositions around custom design, rapid service, refurbishment and mobile substations. For many North American buyers, integrating a U.S. specialist into a mixed‑supply strategy will be essential to manage outages and mitigate long delivery tails from global vendors.
-
Global diversified players (WEG and others) — Players with cross‑regional manufacturing and service footprints provide flexible sourcing alternatives and are likely to win business where multi‑country project portfolios require a single, coordinated supplier.
Practical 2026 playbook — five priority actions for executives
-
Reclassify LPT procurement as strategic capital: Move decisions onto the executive risk register. Treat lead time, domestic content requirements and price inflation as multi-year strategic constraints, not transactional line items.
-
Lock long‑lead items early and diversify sources: Initiate long‑lead purchase orders, structured contracts with price and delivery collars, and parallel qualification of both global OEMs and domestic specialists.
-
Hedge raw‑material exposure and index appropriately: Insist on transparent cost build-ups and consider shared‑risk constructs or commodity‑linked indexation to limit one‑sided price shocks.
-
Invest in service and life‑extension capability: Augment capital expenditure programs with strategic investments in refurbishment, retrofits and aftermarket partnerships to reduce dependency on new‑build lead times.
-
Evaluate capacity M&A and strategic partnerships: For owners with significant programmatic demand — utilities with large transmission upgrade plans, sovereign funds, or major data center platforms — acquiring or partnering with local manufacturers can be a faster way to secure supply than waiting for new greenfield factories to fully ramp.
How PW Consulting supports 2026 decision cycles
Our LPT market report is intentionally practical. It includes downloadable financial models, supplier scorecards, procurement clauses, scenario analysis outputs and an executive dashboard that translates market signals into prioritized actions tied to client objectives (e.g., reliability, cost of energy, project on‑time delivery). For clients pursuing aggressive 2026 programs, we offer expedited advisory sprints: supplier due diligence, site assessments, negotiation support and bespoke valuation work for capacity investments.
Concluding observation — the strategic payoff
Decisions taken in 2026 will reverberate through utility asset lives and national infrastructure programs for decades. The combination of steady market growth, prolonged lead times, material concentration and active reshoring investments means that organizations that translate market intelligence into proactive procurement, diversification and service strategies will materially outpace peers in cost, schedule and reliability outcomes. PW Consulting’s LPT study is designed as the decision support bridge: authoritative in its methodology and pragmatic in its tools, yet deliberately reserved on proprietary sub‑segment tables to preserve the full-value intelligence contained in the complete report.
For executives preparing capital programs, procurement rounds or strategic investments in 2026, PW Consulting’s LPT insights provide the situational awareness and tactical instruments to move from risk to advantage. Access to the full analytical models, supplier ranking matrices and step‑by‑step playbooks is available in the comprehensive report and through our advisory engagements.
For detailed analysis of this topic, please visit the official page: Large Power Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Synthetic Diamond Grit Market to Expand at a 5.2% CAGR During 2026-2032
By pmarketresearch, 2026-07-13
Synthetic Diamond Grit Market: Strategic Imperatives for 2026
PW Consulting’s latest market study on Synthetic Diamond Grit synthesizes five years of historical intelligence (2020–2025, base year 2025) and a seven‑year forecast horizon (2026–2032) to equip leaders with decision-grade insights ahead of the pivotal 2026 planning cycle. Our forecast model shows the global market expanding at a compound annual growth rate (CAGR) of 5.2% through 2032, with the market size moving from USD 2,150.5 Million in 2025 toward roughly USD 3,065.1 Million by 2032. This release functions as a strategic preview: we reveal directional market sizing, concentration dynamics and scenario-based strategic pathways while preserving full subsegment matrices and proprietary micro‑level tables for subscribers who access the source dossier.
Synthetic Diamond Grit Market
Why 2026 Matters: Inflection Points and Strategic Windows
-
Investment cadence: With multi-year capacity projects and product launches already underway among industry leaders, 2026 is the year many firms will either realize scale benefits or find themselves squeezed by input cost inflation and regulatory exposure.
Synthetic Diamond Grit Market -
Technology convergence: Advancements in CVD and HPHT processes are enabling finer, higher‑purity grits optimized for semiconductor and optics polishing—markets that demand both performance and traceable supply chains.
Synthetic Diamond Grit Market -
Policy and carbon regimes: Regional trade measures, chemical registration frameworks and carbon border mechanisms are creating a new cost matrix that must be modeled into capital allocation decisions for 2026 and beyond.
What the Report Contains — Practical, Actionable, and Executable
-
Proprietary market sizing and trajectory: comprehensive headline sizing by year (historical and forecast), base‑case and two alternative scenarios, and sensitivity testing against key input variables.
-
Go‑to‑market playbooks: product positioning frameworks for industrial grinding, high‑precision semiconductor polishing, and heavy‑duty cutting segments including pricing buckets and channel strategies.
-
Supply chain stress maps: feedstock dependency matrices, freight and logistics scenarios, and contingency playbooks for rapid disruption response.
-
Regulatory compliance and carbon accounting templates: practical checklists for REACH, tariff exposure, and Carbon Border Adjustment Mechanism (CBAM) implications.
-
Competitive intelligence dossiers: benchmarked capabilities and strategic positioning for the sector’s key participants, including technology profiles, recent investments, and M&A-ready assets.
-
Transaction playbook: valuation frameworks tailored to synthetic diamond grit (including multiples guidance, earnings adjustments and synergy capture hypotheses) for buyers and sellers.
Market Structure, Concentration and Competitive Dynamics
The market remains moderately consolidated: the top three firms account for a meaningful share of supply and the top five capture a majority of organized industry revenue. This concentration creates both opportunities and risks—scale advantages for incumbents and room for specialized new entrants targeting high‑value niches.
Key industry participants profiled in the report include Element Six (UK), ILJIN Diamond (South Korea), several major Chinese manufacturers with broad production footprints, Sumitomo Electric Hardmetal (Japan), and other specialized suppliers focused on mining/oil & gas and semiconductor applications. Our dossiers combine corporate strategy scans, capacity and capability maps, and links to public intelligence (for example, Element Six’s product developments; ILJIN’s announced capacity expansion). Recent notable moves captured in our timeline include product launches tailored to semiconductor polishing, capacity scale‑ups to service stone processing demand, and new high‑stability grades for high‑speed sawing.
Key External Forces Shaping 2026 Decisions
-
Raw material volatility — Graphite and feedstock: Graphite, a key HPHT feedstock, averaged approximately USD 650/metric ton in late 2024. Price and availability shifts materially affect unit economics across producers; our model shows feedstock swings explain a substantial portion of cost variance across scenarios.
-
Trade and tariffs: Targeted tariffs and trade remedies are reshaping near‑term sourcing strategies. For firms exposed to cross‑border flows, tariff thresholds materially change landed costs and influence decisions about near‑shoring or contractual hedges.
-
Logistics inflation: Ocean freight rates for chemical shipments rose materially in early 2025. Elevated container costs compress margins for long supply chains and increase the attractiveness of localized or regional distribution hubs.
-
Regulatory and chemical governance: Registration and labeling rules for nanomaterials under regional regimes require early compliance planning for formulations and product mixtures used in abrasives and slurries.
-
Energy and carbon constraints: HPHT production is energy‑intensive. With regulatory regimes starting to treat such processes as carbon‑sensitive, firms must evaluate energy mix, site selection, and low‑carbon investments as part of NPV calculations for expansion projects.
Strategic Playbook — Recommendations for 2026 Planning
-
Prioritize scenario planning that ties directly to feedstock and freight: embed run‑rate stress tests for graphite and shipping spikes in 2026 budgets and capex approvals.
-
Accelerate product differentiation where premium margins exist: develop or acquire capabilities for ultra‑high purity grits for semiconductor/optics polishing and PCD tooling used in precision industries.
-
Mitigate regulatory and tariff risk via supply‑chain architecture: evaluate regional production nodes, bonded warehousing and contractual hedges to limit exposure to punitive import measures.
-
Invest in energy efficiency and low‑carbon proof points: retrofits or next‑gen reactors may have longer payback horizons but materially reduce CBAM exposure and open procurement channels with climate‑sensitive buyers.
-
Leverage M&A selectively to fill capability gaps: focus on bolt‑on producers with differentiated grades or geographic advantages rather than pursuing undifferentiated volume growth.
-
Strengthen commercial intelligence: adopt rolling 12–18 month pricing and inventory telemetry to convert market signals into rapid commercial moves (price adjustments, targeted promotions, or inventory hedges).
Risk Matrix and Early‑Warning Indicators
-
Cost shock indicators: monitor graphite spot price, ocean freight indices, and regional energy tariffs as primary triggers for re‑pricing or margin compression.
-
Regulatory watchpoints: track chemical registration milestones and tariff rule changes in major demand centers; these are often announced months before enforcement and provide a narrow window for mitigation.
-
Competitive jockeying: new capacity announcements or rapid grade introductions by incumbents can compress niche premiums—watch patent filings, plant permits and trade show technical demonstrations.
How PW Consulting’s Deliverables Support Action
-
Decision packs for 2026: executive summaries, board‑level scenario decks, and detailed appendices with vendor scorecards to accelerate C‑suite approvals.
-
Commercial negotiation toolkits: calibrated pricing ladders and margin levers tied to raw material indices and freight contracts.
-
M&A screening templates: pre‑validated target profiles and synergy calculators tuned to the synthetic diamond grit economics.
Our analysis is intentionally directional in this public note. While we disclose headline market sizing, growth rate and concentration metrics to inform executive deliberation, the full intelligence set — including granular segmentation tables, regional and application breakdowns, and company‑level market share models — is gated and available on the report landing page.
Next Steps for Executives
-
Download the full report to access the enclosed subsegment matrices and supplier profiles that will materially influence 2026 procurement, R&D and M&A decisions.
-
Commission a tailored impact assessment: PW Consulting can run a focused 6–8 week engagement modeling your specific exposure to feedstock, tariff and carbon scenarios and produce an actionable implementation roadmap for 2026.
For leaders preparing 2026 budgets and strategic initiatives, understanding the interplay of market growth (CAGR 5.2% through 2032), concentration dynamics and external cost drivers is no longer optional — it is a competitive necessity. Our full report delivers the missing micro‑level intelligence that turns this strategic preview into executable plans.
For detailed analysis of this topic, please visit the official page: Synthetic Diamond Grit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Suppository Base Market to Climb from USD 650 Million in 2025 to USD 945.54 Million by 2032 at a 5.5% CAGR
By pmarketresearch, 2026-07-13
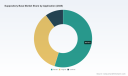
Suppository Base Market — 2026 Strategic Briefing
PW Consulting’s latest Suppository Base Market report is designed as an operationally focused intelligence product for executives making strategic sourcing, R&D, and M&A decisions in 2026. The global market for suppository bases has entered a steady, mid-single-digit growth phase: after expanding from roughly USD 498 million in 2020 to USD 650 million in our 2025 base year, our demand model shows a continuation of that momentum through the 2026–2032 forecast window — translating to a 5.5% compound annual growth rate and a projected market approaching USD 946 million by 2032. This briefing highlights the report’s strategic value, the competitive dynamics shaping supplier choice, and the practical implications for corporate decision-makers. (For full regional, type, and application breakdowns, the complete dataset and downloadable models are hosted with the full report.)
Suppository Base Market
Why this matters for 2026 decision cycles
-
Procurement: Suppository bases remain a specialty excipient category where supplier GMP status, product traceability, and grade consistency materially affect formulation stability and regulatory approvals. With a clear growth trajectory, 2026 is the inflection point for many organizations to move from tactical spot-buying to strategic supplier partnerships and long-term contracts.
Suppository Base Market -
R&D & Formulation Strategy: Choice of base (fatty/oleaginous hard fats, water-soluble PEG blends, or advanced synthetic systems) affects API release, mucosal tolerance, and patient acceptability. The report synthesizes lab-to-commercial transition risks so R&D teams can prioritize platform investments that accelerate time-to-market.
Suppository Base Market -
M&A & Corporate Development: The industry exhibits moderate concentration among established specialty suppliers — our concentration metrics indicate that the top three players account for approximately one-third of market revenue, and the top five approach just over 40% — a profile that favors roll-up plays and targeted vertical integration for mid-sized pharmaceutical and specialty chemical firms.
What the PW Consulting report delivers (practical, transaction‑grade content)
-
Granular market model (2020–2032): revenue history, base-case and alternative scenarios, and sensitivity analysis to raw material shocks and regulatory events — delivered in an editable spreadsheet to support valuation and procurement simulations.
-
Supplier scorecards: quality (GMP/cGMP history), capacity, geographic footprint, and business continuity risk matrices covering primary manufacturers and compounding distributors.
-
Formulation playbook: decision matrix for base selection by therapeutic objective, stability challenges, and patient administration route, including trade-offs between oleaginous hard fats and PEG-based systems.
-
Regulatory & compliance matrix: mapping Ph. Eur., USP, and common national requirements; inspection histories and practical guidance for dossier preparation and excipient change control.
-
Commercial go-to-market templates: sample long-form supply agreements, key performance indicators for CMO partnerships, RFP templates, and pricing frameworks that reflect raw material pass-throughs and quality premiums.
-
M&A diligence kit: target screening criteria, expected multiples range by business model (manufacturer vs. compounding distributor), and an integration checklist focused on quality systems and regulatory harmonization.
Market dynamics and operational risks
Three dynamics are driving near-term commercial decisions: (1) steady demand growth across core therapeutic segments, (2) raw material and sustainability pressures associated with vegetable-sourced hard fats, and (3) regulatory expectations around excipient provenance and GMP compliance. Hard fat bases commonly derive from saturated fatty acids sourced from coconut and palm kernel oils; this creates exposure to agricultural supply cycles, traceability requirements, and ESG scrutiny. Meanwhile, standards bodies list an array of commonly used bases (cocoa-butter substitutes, hydrogenated vegetable oils, PEG mixtures), which means formulation teams must balance clinical performance with supply security.
Regulatory alignment is non-negotiable. Some leading hard-fat manufacturers operate under EU GMP and maintain histories of US FDA cGMP inspections, and many bases are referenced in pharmacopeial compendia. For manufacturers and branded generics alike, the ability to demonstrate pharmacopeial compliance and documented supply chains will determine market access in the next regulatory sweep.
Competitive landscape — who matters and why
Our competitive analysis focuses on specialty excipient manufacturers and distribution/compounding players who control formulation access to hospital and pharmacy channels. Key firms profiled in the report include:
-
IOI Oleo GmbH (Hamburg, Germany) — A global name in hard‑fat (WITEPSOL®) bases with multiple registered grades and GMP-certified production. Their strength is in scale, regulatory pedigree, and a long track record supplying rectal and vaginal bases optimized for industrial manufacturing. Recent catalogue updates underscore continued investment in grade development and technical support for formulators.
-
Medisca (Montreal, Canada) — A major supplier to compounding pharmacies with a broad portfolio that includes vegetable‑based and PEG systems. Their commercial model is distribution-led, emphasizing availability to compounding networks; their recent promotion of natural base grades signals a push to capture pharmacist and outpatient demand.
-
PCCA (Houston, Texas, USA) — Positioned around proprietary bases for compounding and practitioner networks, PCCA combines product breadth with service support aimed at customized preparations. Their proposition targets the clinical compounding space where rapid formulation support is valued.
-
SpecializedRx (USA) — Focused on compounding markets with a portfolio that includes established hard fats and blended bases; their niche is rapid supply to independent pharmacies and small hospital systems.
-
Gattefossé (France) — Adds formulation science to the supply equation, offering hard fat bases tailored for controlled dispersion, stability, and mucosal tolerance — appealing to pharma customers seeking technical co-development.
-
Croda Pharma (UK) — A broader excipient house whose capabilities in excipient innovation and regulatory support make them an attractive partner for branded product teams seeking differentiated functional excipients.
Recent vendor moves — for example IOI’s WITEPSOL® brochure refresh and Medisca’s active promotion of natural and Witepsol‑equivalent grades — indicate two concurrent strategies in the market: (1) incumbent manufacturers focusing on technical differentiation and regulatory validation, and (2) distributors/compounding suppliers emphasizing availability and service to downstream pharmacy networks.
Strategic implications and recommended actions for 2026
-
Embed excipient strategy into product development roadmaps. Formulation strategy should be a board-level input: early decisions on base families materially affect stability, packaging, and expiration dating. Run design-of-experiments (DOE) to de-risk transitions between base types before committing to commercial batches.
-
Diversify upstream exposure where material. For manufacturers reliant on vegetable‑derived fats, implement a multi-supplier policy and consider contracted volumes or hedging to mitigate agricultural volatility. Include sustainability and traceability clauses in supplier contracts to anticipate procurement disruptions driven by ESG scrutiny.
-
Prioritize GMP and pharmacopeial alignment in supplier selection. Regulatory inspections and pharmacopeial references remain decisive in hospital and export markets. Select suppliers with transparent inspection histories and documented change-control procedures.
-
Leverage compounding channels tactically. If market entry speed is a priority, partnering with compounding-focused distributors and networks can accelerate access to B2B and outpatient demand while a longer-term manufacturing strategy is developed.
-
Evaluate M&A to achieve scale or technical capability. Given the market’s moderate concentration, acquisitive moves can secure capacity, broaden grade portfolios, or add formulation expertise — especially compelling for players seeking integrated supply chains or enhanced technical services.
PW Consulting’s unique analytical edge
Our report combines market-sizing rigor with transactional insights: the model is backed by bottom-up production and consumption estimates, validated against manufacturer disclosures and compounding distribution activity. The supplier scorecards and risk matrices are built from primary interviews, inspection histories, and product disclosures, while the commercial toolset provides immediate operational utility for procurement, quality, and corporate development teams.
We intentionally limit the level of segmentation detail in this public briefing to preserve the “trailer” effect: the full report contains the regional, type, and application splits (historical and forecast), price curves by base grade, and scenario-run workbooks that clients use directly in board-level decision-making and deal diligence.
Next steps — how to use this intelligence in 2026
-
Download the full dataset and editable models to run your own scenarios on procurement contracts and acquisition targets.
-
Use our supplier scorecards in RFP shortlists and pre-acquisition due diligence to quantify regulatory and supply continuity risk.
-
Engage our consulting team for accelerated diligence or to co-develop formulation testing plans aligned to your product pipeline milestones.
PW Consulting’s Suppository Base Market report is built for the practical needs of 2026 planners: it converts a complex, technically-driven supply market into action-oriented strategy, procurement playbooks, and transaction-ready diligence. Access to the full report and underlying models is available via our client portal — contact your PW representative to obtain the full dataset, supplier annexes, and the editable forecast workbook.
For detailed analysis of this topic, please visit the official page: Suppository Base Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium‑Ion Consumer Battery Electrolyte Market Poised for 5.2% CAGR During 2026–2032
By pmarketresearch, 2026-07-13
PW Consulting: Strategic Outlook — Lithium Ion Consumer Battery Electrolyte Market (2026 Planning Brief)
Executive summary
As consumer electronics continue to demand higher energy density, faster charging and stricter safety profiles, the lithium ion consumer battery electrolyte market is entering a period of disciplined growth and structural change. PW Consulting’s latest market study — anchored on a 2025 base year and forecasting through 2032 — finds the global market expanding at a 5.2% CAGR into the next decade, with total market value rising materially from the 2025 baseline toward our 2032 projection. For executives planning resource allocation, supply-chain moves, or M&A activity in 2026, the report converts macro momentum into practical decision levers while preserving the granular intelligence available only in the full deliverable.
Lithium Ion Consumer Battery Electrolyte Market
Why 2026 is a strategic inflection point
-
Regulatory and trade shifts enacted in late 2025 and early 2026 materially alter sourcing economics and compliance risk. New chemical restrictions and national content rules mean procurement and product teams must re-evaluate supplier footprints now to avoid downstream disruption.
Lithium Ion Consumer Battery Electrolyte Market -
Raw-material tightness and price volatility observed in the past 12–18 months are evolving into structural supply constraints for certain carbonate solvents and fluorinated salts. These dynamics will influence not just cost curves in 2026 but also product formulation choices and partnership timelines.
Lithium Ion Consumer Battery Electrolyte Market -
Competitive moves — capacity additions, product launches and certifications among leading electrolyte suppliers — are concentrating supply-side capabilities. That concentration amplifies the importance of strategic supplier engagement and contingency planning for OEMs, EMS providers and battery pack integrators.
What the report delivers (practical, action-oriented content)
PW Consulting designed this report as a practitioner’s tool for 2026 decision cycles. Highlights include:
-
Robust market sizing and high‑confidence forecasts at the global level (base year 2025; forecast 2026–2032), including sensitivity scenarios tied to raw-material price trajectories and regulatory regimes.
-
Supply-chain maps and a supplier capability matrix that score manufacturers on quality certifications, regional footprint, production modalities (solvent vs. salt vs. formulation) and scale-readiness for consumer applications.
-
Commercial playbooks: procurement negotiation levers, hedging approaches for volatile feedstocks, and contracting templates to mitigate tariff and compliance risk.
-
Technology and product roadmaps that contrast incumbent liquid and gel polymer chemistries against emerging solid-state and hybrid electrolytes, with time-to-market and risk-adjusted adoption curves.
-
Regulatory impact assessment with timelines, compliance costs and scenario-driven mitigation strategies for REACH-style restrictions, national content mandates and trade measures.
-
M&A and partnership screening: prioritized target archetypes for bolt-on vertical integration, regional capacity plays, and strategic JV structures for localized production.
-
Operational checklists for ramping manufacturing, including quality gating, contamination controls and downstream validation protocols aligned with consumer electronics OEM requirements.
Market outlook — headline metrics
At a high level, the market demonstrates steady expansion from the 2025 baseline into 2032 under our central scenario. The 5.2% CAGR reflects a balance between volume growth driven by next‑generation devices and episodic price and supply pressure driven by raw-material constraints. Historical trends through 2025 show resilient demand recovery following pandemic-era disruptions; our model incorporates demand substitution effects (e.g., higher energy density designs reducing per-unit volume) and offsetting increases in unit production for new device classes.
Competitive landscape — tactics and implications
The electrolyte supplier set is characterized by a mix of specialty chemicals houses, regional formulators and vertically integrated suppliers. Market concentration is meaningful — the top three suppliers command a large portion of available market share and the top five an even larger share — creating both stability at scale and sourcing risk for buyers who rely on a narrow pool of vendors.
-
Ube Corporation (Japan): long-standing strengths in carbonate solvent production and continued innovation (notably recent low-viscosity solvent introductions) make it a leading source of high-rate electrolytes for consumer applications. Their product development trajectory rewards OEMs seeking improved fast‑charge performance.
-
Stella Chemifa Corporation (Japan): a specialist in lithium salts, their certified manufacturing footprint and recent ISO recertification reinforce reliability for high-performance formulations — a critical attribute for partners with tight qualification cycles.
-
Capchem (China): active capacity expansion and integrated formulation capabilities position it as a go‑to supplier for large consumer OEMs; their regional investments reduce lead times for Asian supply chains but warrant tariff and regulatory scenario planning.
-
Guotai Huarong, Shengli (China): carbonate solvents, additives and salt production at scale make these firms important tactical partners for regional supply — yet exposure to trade actions and feedstock constraints necessitates contingency sourcing.
-
Solvay (Belgium), Mitsui Chemicals, TonenGeneral Sekiyu (Japan): global specialty chemistries players and additive developers that are likely partners for differentiated electrolyte platforms emphasizing stability and safety.
-
Panax Starlyte and Dongwha Electrolyte (Korea): niche-to-broad formulators focused on high-energy-density applications and custom solutions, valuable for co-development arrangements with device OEMs.
Recent announced moves — capacity expansions, new solvent launches, salt-production increases and quality certifications — underline an industry investing to secure the 2026–2028 demand window. Together, these developments tighten supplier options for buyers who delay strategic sourcing decisions.
Key market dynamics for 2026 decisions
-
Regulation: New chemical restrictions and product standards in major markets re-frame acceptable formulations and speed-to-market. Product teams must start 2026 qualification cycles with compliant chemistry options to avoid launch delays or re-engineering costs.
-
Trade & tariffs: Rising protection measures on certain trade lanes change landed-cost comparisons and favor regional manufacturing or partnership models that secure local content requirements.
-
Raw-material volatility: Spot tightness on specific carbonate solvents and fluorinated salts has compressed lead times and raised procurement risk premiums. Buyers should employ forward-buying, multi‑sourcing and supplier-backed hedges as defensive tactics.
-
Concentration risk: High market share among leading suppliers means that single‑source dependence creates outsized exposure to operational disruption or policy shifts.
Actionable strategic recommendations for 2026
-
Rebalance supplier portfolios: Move from transactional sourcing to strategic partnerships with dual-sourcing clauses, capacity reservation mechanisms and co-investment options in regional assets.
-
Accelerate chemistry qualification pipelines: Prioritize candidate formulations that meet imminent regulatory constraints and maintain performance trade-offs. Shorten qualification by pre-validating test protocols and leveraging supplier co-development resources.
-
Model tariff and content scenarios: Build a decision tree for manufacturing footprint choices that quantifies margin, lead-time and compliance impacts under different trade-regulation outcomes.
-
Pursue targeted M&A or JVs: Consider acquiring specialty additive suppliers or forming regional JVs to secure domestic content requirements and reduce tariff exposure to key markets.
-
Embed materials risk into product roadmaps: Align product development timelines with supplier capacity availability and feedstock outlooks to avoid late-stage redesigns.
-
Operational readiness: Invest in contamination control, personnel training and analytics to shorten ramp times for new electrolyte grades in pilot and full-scale manufacturing.
How clients should use this report for 2026 planning
-
Procurement leaders: Use the supplier scorecards and risk heatmaps to re-shape sourcing strategies and contract terms before annual purchasing cycles lock in spend.
-
R&D and product management: Leverage the technology roadmaps and formulation comparisons to prioritize safe, compliant chemistry stacks that meet device performance targets.
-
Corporate development: Apply the M&A screening and scenario modeling to identify acquisition targets that accelerate domestic manufacturing or add strategic capabilities.
-
Regulatory and compliance teams: Implement the report’s compliance timelines and cost scenarios to budget remediation actions and preempt market access barriers.
Closing and next steps
PW Consulting’s study offers a clear, executable view of the lithium ion consumer battery electrolyte market at a moment when regulatory shifts, material constraints and supplier consolidation will shape commercial outcomes. The analysis is intentionally prescriptive: it converts macro forecasts and industry movements into negotiated procurement levers, technology choices and M&A priorities for 2026.
For access to the full dataset, supplier scorecards and proprietary scenario models that underpin these findings, please visit our report page or contact PW Consulting’s industry practice. The detailed segmentation tables and company-level analytics are available in the full report for subscribers and client engagements — designed to support precise sourcing decisions, capex plans and product qualification roadmaps for the year ahead.
For detailed analysis of this topic, please visit the official page: Lithium Ion Consumer Battery Electrolyte Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com