

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Elastic Sealing Gate Valve Market to Grow from USD 1,450.0 Million in 2025 to USD 2,374.46 Million by 2032 at a 7.3% CAGR — Asia Pacific Leads with USD 648.6M
By pmarketresearch, 2026-07-13
Elastic Sealing Gate Valve Market — Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Elastic Sealing Gate Valve Market report — an actionable industry roadmap designed to inform board-level decisions in 2026 and beyond. Built on a disciplined historical base (2020–2025) and a robust forecast horizon (2026–2032), the study quantifies market momentum, lays out supplier dynamics, and translates regulatory and raw-material pressures into practical plays for manufacturers, utilities, EPCs, and investors. This preview highlights the report’s core strategic value while intentionally withholding detailed segmented tables and proprietary model outputs to encourage direct engagement with the full report.
Elastic Sealing Gate Valve Market
Market at a Glance: Macro Trajectory and What It Means
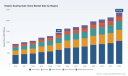
The elastic sealing (resilient seated) gate valve market has shifted from a mature, infrastructure-oriented niche into a growth corridor driven by municipal upgrades, industrial cooling demand, and water-conservancy investments. On a macro level, our model — with 2025 as the base year — shows global market revenues expanding from USD 920.45 Million in 2020 to USD 1,450.00 Million in 2025. Looking forward through the forecast window (2026–2032), the market is projected to grow at a compound annual growth rate (CAGR) of 7.3%, reaching approximately USD 2,374.46 Million by 2032.
Elastic Sealing Gate Valve Market
Why that trajectory matters for 2026 decisions:
Elastic Sealing Gate Valve Market
- Scale and runway: A multi-year expansion at a mid-single-digit to high-single-digit CAGR signals durable demand — sufficient to justify targeted capacity investments, product line extensions, and selective M&A.
- Timing: 2026 is an inflection year in our scenarios where capital allocation toward resilient seating technologies and elastomer innovation begins to translate into measurable share shifts among agile suppliers.
- Margin pressure and pricing: Growth is accompanied by material cost volatility and heightened procurement sophistication among utilities, squeezing suppliers that fail to demonstrate lifecycle cost benefits.
Key Dynamics Shaping Supply, Demand, and Risk
The report synthesizes several converging dynamics that will dominate boardroom conversations in 2026:
- Standards and compliance: Regulatory frameworks such as AWWA C509/C515 in North America and EN 1074‑2 / BS 5163 in Europe are increasingly prescriptive on ductile iron construction and zero-leakage performance. Compliance is no longer a market-entry checkbox — it is an operational differentiator for bidders on large municipal projects.
- Raw-materials and input cost profile: Elastomers are a critical cost and performance driver. For context, EPDM rubber — a common resilient-seat compound — averaged about USD 3.08/kg in Northeast Asia as of April 2026. Suppliers with integrated purchasing, long-term contracts, or alternative compound roadmaps have a measurable advantage in margin resilience.
- Customer purchasing sophistication: Utilities and large EPCs are shifting to total-cost-of-ownership procurement models, emphasizing lifecycle maintenance, leak prevention, and asset digitalization. That changes contract structures in favor of suppliers offering performance guarantees, retrofit services, and data-enabled condition monitoring.
- Technology and material evolution: Advances in elastomer formulations (enhanced UV/chemical resistance) and seat-retention designs are reducing field-failure rates and enabling longer warranty terms — but they require R&D investment and validation cycles.
- Concentration and competitive posture: Market concentration is moderate; the top-three players capture an estimated ~38.5% of market value, with the top-five accounting for roughly ~52.7%. This environment fosters regional champions, manufacturing specialization, and recurring contracting patterns with large infrastructure players.
What the Full Report Delivers — Practical and Executable
PW Consulting’s full report is built as a decision-support toolkit rather than a descriptive dossier. Key practical deliverables include:
- Proprietary market-sizing model (USD Million, 2020–2032) with scenario toggles for material-cost shocks, regulatory tightening, and municipal CAPEX cycles.
- Segmented demand matrices and supplier revenue breakdowns by region, product type, and application — presented as interactive worksheets (note: these detailed tables are withheld in this preview).
- Supply-chain heatmaps that identify single points of failure — from elastomer compounding to ductile iron casting capacity — and recommended mitigation steps for manufacturers and buyers.
- Competitive scorecards and sourcing playbooks: side-by-side supplier capabilities, warranty frameworks, production footprints, and procurement negotiation levers.
- M&A and partnership shortlist: validated acquisition targets, strategic fit analysis, and integration risk checklists for 2026 deal teams.
- Implementation roadmaps for product commercialization, including R&D staging, certification timelines (AWWA/EN/BS), and pilot deployment plans for utilities.
Competitive Landscape — Players to Watch and Strategic Moves
The market is composed of well-established European specialists and increasingly capable Asian manufacturers competing on scale, certification, and performance track records. Below are high-level profiles of core players covered in the study:
- AVK Valves (Denmark): Known for resilient seated gate valve series designed to meet BS5163 and EN standards, AVK emphasizes certified solutions for water and wastewater systems and tends to lead on specification-driven municipal tenders.
- VAG GmbH (Germany): A technical specialist focusing on advanced sealing systems for municipal and industrial applications; their product development centers on longevity and serviceability in potable water networks.
- EJ Industrial Group (China): Large-scale manufacturer of ductile iron resilient seated gate valves offering both metal-to-metal and elastomer seat options; their scale supports competitive pricing on international projects.
- Union Valve (China): Producer of cast and ductile iron resilient seated valves, including non-rising stem configurations commonly specified in distribution networks; active in cross-border shipments for water infrastructure projects.
- Dervos Valve (China): Offers elastic seat sealed gates with emphasis on zero-leakage performance — a strong choice for projects prioritizing long-term reliability.
- Weidouli Valves (China): Supplies soft-seal and resilient seated gate valves with EPDM/PTFE compound options designed for higher-pressure environments.
- BELGICAST (Spain): European manufacturer supplying higher-performance resilient seated valves for critical infrastructure and large-scale waterworks.
Recent industry signals we track: Weldon Valves’ March 2025 product update highlighted improved elastomers and sustainability features, while Union Valve reported shipments of non-rising stem resilient seated valves for international water projects in late 2024. These events underscore a bifurcation in supplier strategies: technical differentiation versus scale-driven volume plays.
Strategic Implications — Action Areas for 2026
For decision-makers preparing for 2026, our analysis crystallizes into five pragmatic plays:
- For manufacturers: Prioritize elastomer supply security and certification roadmaps. Invest in validated, higher-performance compounds and secure multi-year supply agreements for EPDM or alternative polymers to avoid margin erosion.
- For utilities and EPCs: Shift procurement beyond unit prices to TCO contracts that include field performance metrics and extended warranties. Pilot data-enabled condition monitoring to reduce lifecycle costs and inform capital planning.
- For investors and M&A teams: Target assets that combine regional market access with certification depth or proprietary elastomer know-how. Valuation premiums will accrue to businesses that can demonstrate lower field-failure rates and predictable aftermarket revenue.
- For OEMs considering capacity expansion: Stage investments against demand scenarios in our forecast model. A staged-capex approach — initial debottlenecking followed by modular capacity additions — balances responsiveness with capital discipline.
- For product strategists: Bundle product upgrades with service offerings (retrofit kits, condition assessment) and explore certification partnerships to accelerate acceptance in regulated markets.
How to Use This Preview — Next Steps
This briefing is a strategic “trailer”: it demonstrates the depth of our analysis and provides concrete decision levers, while selective data — notably the full segmented revenue tables by region, product type, and application and the detailed supplier financial profiles — are reserved for the full report. Executives seeking to operationalize these insights should request the PW Consulting Elastic Sealing Gate Valve Market report for the complete model files, supplier scorecards, and a custom briefing tailored to your organization’s role in the ecosystem.
Our team is available for executive briefings, custom model adjustments, and M&A diligence support. Equip your 2026 strategy with the empirical backbone required to convert market growth into captureable, profitable share.
For detailed analysis of this topic, please visit the official page: Elastic Sealing Gate Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HFO Cooling Fluids for Data Centers to Surge from USD 610.5 Million in 2025 to USD 1,947.03 Million by 2032 at an 18.02% CAGR
By pmarketresearch, 2026-07-13
HFO Cooling Fluids for Data Centers: Strategic Insights for 2026 Decision-Making
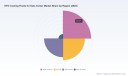
PW Consulting’s new market study on HFO (hydrofluoroolefin) cooling fluids for data centers reframes how infrastructure leaders should think about thermal strategy over the next investment cycle. The market has moved beyond experimental pilots into commercially credible deployments: our 2025 base-year analysis pegs the market at approximately USD 610.5 million, with a compound annual growth rate of 18.02% through the 2026–2032 forecast window. By 2026 the market is projected to clear the mid‑hundreds of millions and, under current trajectories, approach just under USD 2.0 billion by 2032. Those headline dynamics matter for procurement, product roadmaps, compliance planning, and risk management in 2026.
Hfo Cooling Fluids For Data Center Market
Why this market matters for your 2026 strategy
-
Regulatory timing is compressing vendor and user decisions. Policy shifts—most notably recent EPA Technology Transitions rules and ongoing implementation of Kigali and F‑gas frameworks—create hard compliance milestones that will shape which cooling options are permissible, economic, or practical across major operating geographies beginning in 2027 and beyond.
Hfo Cooling Fluids For Data Center Market -
Transition economics are moving from lab to balance sheet. The combination of accelerating market adoption and a rapid capacity build-out among key suppliers means that thermal design choices made in 2026 will influence total cost of ownership over a multi‑year lifespan, not just immediate capital outlay.
Hfo Cooling Fluids For Data Center Market -
Supplier concentration is material. The market exhibits high concentration: the top three suppliers account for a clear majority share, and the top five capture almost nine in ten dollars of market value. That concentration translates into negotiation dynamics, technology lock‑in risk, and strategic leverage for a small set of global chemical and HVAC incumbents.
-
Supply‑chain and raw‑material volatility is an operational lever. HFO production depends on specific fluorinated intermediates and olefins; periodic raw material price shocks and capacity shifts (already visible through supplier price actions in 2025) affect margins, contract terms, and supplier selection.
What the PW Consulting report delivers (practical, execution‑oriented)
-
Actionable market sizing and scenario models calibrated to 2025 base data and our 2026–2032 forecasts—designed for integration into capital planning and vendor selection processes.
-
Commercial due‑diligence templates that translate chemical supplier claims into procurement KPIs, including compatibility, lifecycle emissions, and cost drivers you can use in RFIs and RFPs.
-
Technology readiness assessments mapping product types to typical deployment archetypes (immersion, direct‑to‑chip, chiller architectures) with decision trees for when to pilot versus when to scale.
-
Regulatory scenario analysis that quantifies the impact of near‑term GWP limits and phasedown timetables on acceptable refrigerant/coolant choices and retrofitting windows.
-
Supplier scorecards and concentration risk maps, with playbooks for contracting, dual sourcing, and long‑lead procurement to mitigate supplier power and feedstock exposure.
-
Compatibility and qualification checklist for hardware vendors and hyperscalers—covering materials compatibility, electronic component validation, and operational reliability benchmarks from pilot to production.
-
Financial models for total cost of ownership and carbon‑adjusted ROI that fold in energy efficiency gains, water savings potential from liquid approaches, and disposal/recapture options for end‑of‑life fluids.
-
A curated appendix of vendor dossiers, recent commercial milestones, and anonymized case studies from pilot and full‑scale trials. Note: to preserve commercial confidentiality we summarize outcomes and implications rather than disclosing counterparty commercial terms or granular trial metrics.
Competitive landscape — what matters for vendor selection in 2026
-
The marketplace is anchored by a small set of industrial incumbents that combine chemical synthesis capability with global manufacturing footprints and channel relationships into data center OEMs and integrators. These players bring differentiated propositions: proprietary dielectric two‑phase fluids, low‑GWP blends optimized for chillers and centrifugal machines, and product lines tailored to single‑ and two‑phase immersion.
-
One global chemical player has advanced its two‑phase dielectric offering into commercial qualification with at least one major SSD manufacturer and is executing strategic manufacturing and integration agreements to secure supply and accelerate system demonstrations. These moves de‑risk adoption for hyperscalers and large colo operators planning fleet rollouts.
-
Another incumbent has recently increased upstream production capacity for low‑GWP HFO formulations to meet growing demand for chiller and immersion applications—an important signal that supply constraints are being addressed, but also that customers should validate long‑term offtake and logistics terms.
-
Specialist entrants and spin‑outs from larger diversified materials businesses are pushing performance claims—very low GWP, low flammability, dielectric stability for two‑phase immersion—and have been visible in trials and niche deployments. Their agility can translate into rapid innovation, but buyers must weigh scale, qualification history, and backward‑compatibility risk.
-
Regional and subsystem OEMs (HVAC and refrigerant specialists) are leveraging decades of refrigeration know‑how to package HFO solutions for direct‑to‑chip and chilled‑loop systems, reducing integration friction for operators that prefer incremental transitions over wholesale architectural overhaul.
Regulatory and raw‑material dynamics to watch in 2026
-
Expect regulatory levers to shift the relative attractiveness of solutions. Recent rules in major jurisdictions introduce next‑generation GWP thresholds and phase‑in schedules that make ultra‑low‑GWP HFOs strategically preferable for new equipment. These timelines create windows for factory‑charged systems, grandfathering rules, and incentives that savvy buyers can exploit in procurement cycles.
-
Feedstock risk remains a live issue. Price adjustments from producers in 2025 reflected upstream cost pressure; procurement teams should bake in sensitivity to feedstock price shocks and include contractual protections or price‑adjustment mechanisms in multi‑year supply agreements.
-
Compliance goes beyond refrigerant selection. End‑to‑end lifecycle accounting—covering leak rates, end‑of‑life recovery, and equivalent CO2 accounting—will increasingly be a procurement requirement in tenders and sustainability reporting frameworks.
Practical 100‑day plan for CIOs, CTOs, and Procurement Heads
-
Day 0–30: Inventory and risk triage. Map installed thermal architectures, inventory compatible materials, and identify high‑heat, high‑value racks where economics justify immediate pilots.
-
Day 30–60: Supplier engagement and qualification. Issue targeted RFIs to a short list of qualified suppliers, request third‑party compatibility data, and negotiate pilot‑scale supply agreements with explicit qualification gates and price‑adjustment clauses.
-
Day 60–90: Pilot and measurement. Execute instrumentation‑rich pilots that capture energy, water, reliability, and operational maintenance metrics. Use a standard template (provided in our report) to ensure cross‑vendor comparability.
-
Day 90–100: Go/no‑go and contracting. Based on pilot performance and regulatory horizon, finalize procurement strategy—pilot extension, cascade deployment, or strategic partnership—and lock in long‑lead components and service packages aligned with compliance windows.
How PW Consulting supports your 2026 roadmap
-
We provide rapid‑turn advisory packages that combine our market forecast models, supplier diligence, and technical validation protocols so teams can accelerate pilot-to-scale decisions without assuming undue technical or supply risk.
-
Our vendor negotiation workstreams help buyers structure multi‑year supply frameworks that hedge feedstock volatility, secure qualification milestones, and preserve flexibility across cooling architectures.
-
For investors and M&A teams, we offer concentration and competitive stress testing that quantify the implications of market concentration on pricing power, margin compression, and strategic entry points.
Data center operators, OEMs, and investors entering procurement or investment deliberations in 2026 will find the next 12–18 months decisive. The market’s rapid growth trajectory and the interplay of supplier consolidation, regulatory push, and raw‑material dynamics make disciplined, data‑driven strategy essential. PW Consulting’s HFO Cooling Fluids for Data Center Market report synthesizes those forces into practical, executable guidance—balancing speed to market with long‑term resilience. For the complete dataset, segment level detail, and vendor scorecards that underpin these conclusions, download the full report from PW Consulting’s insights portal.
For detailed analysis of this topic, please visit the official page: Hfo Cooling Fluids For Data Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Cloud Backup System Market to Expand from USD 7.15 Billion (2025) to USD 15.08 Billion by 2032 at an 11.25% CAGR
By pmarketresearch, 2026-07-13
Cloud Backup System Market 2026: Strategic Imperatives from PW Consulting’s Latest Market Report
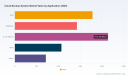
As enterprises reset priorities for 2026, PW Consulting’s new Cloud Backup System Market report delivers the high‑fidelity, decision‑ready intelligence leaders need to allocate capital, redesign operations, and negotiate supplier engagements. Anchored on a 2025 base year and projecting through 2032, our analysis synthesizes market sizing, competitive dynamics, regulatory pressure, and infrastructure cost drivers to illuminate where backup investments will generate the greatest risk‑adjusted returns. The market’s trajectory — from a USD 7,150 Million base in 2025 toward an expected USD 15,083 Million by 2032 at a compound annual growth rate of 11.25% — underpins the urgency and scale of decisions IT and security executives must make in 2026.
Cloud Backup System Market
Why this report matters for 2026 decision cycles
-
Accelerated adoption and operational complexity: Public cloud adoption, hybrid architectures, and SaaS proliferation have amplified backup surface area and recovery expectations. Our report translates macro growth into executable roadmaps for storage architects and resilience leaders.
Cloud Backup System Market -
Capital and operating tradeoffs: With rising data center construction and energy costs, capital planning now intersects with TCO of backup strategies. We provide models that map backup architecture choices to multi‑year cost outcomes and carbon/energy footprints.
Cloud Backup System Market -
Regulatory and sovereignty constraints: Data sovereignty, evolving energy reporting requirements, and sectoral privacy rules are reshaping where and how backups can be stored. The report frames compliance‑first backup architectures to prevent costly retrofits.
-
Cyber resilience as a boardroom priority: Ransomware and supply‑chain risk make recovery time objectives (RTOs) and immutable/air‑gapped designs procurement imperatives. Our frameworks prioritize resilience investments by business‑impact and recovery criticality.
What the report contains — practical assets for immediate use
PW Consulting built this report to be prescriptive, not just descriptive. Clients receive a layered suite of tools and analyses that translate market insight into execution plans:
-
Market sizing and trend narrative (2020–2025 history; 2026–2032 forecast) with scenario variants that stress‑test slower vs. faster cloud adoption paths.
-
Strategic vendor scorecards and procurement playbooks — comparative matrices that evaluate solution fit across resilience posture, integration with major cloud providers, operational automation, and cost per TB at various recovery SLAs.
-
Deployment and migration roadmaps for three archetypal enterprise profiles (cloud‑native, hybrid‑first, and regulated‑data), including phased milestones, KPIs, and risk checkpoints.
-
TCO and ROI modeling toolkit (spreadsheet‑based) that incorporates energy, facility, and labor cost assumptions to compare on‑prem, cloud, and hybrid backup scenarios over 5–7 year horizons.
-
Compliance and sovereignty decision trees that align backup locality, encryption, and access controls to major regulatory frameworks and sectoral mandates.
-
Operational playbooks for ransomware‑ready backups: retention policies, immutable storage patterns, air‑gap options, and validation cadences designed for rapid recovery and forensic readiness.
-
Vendor negotiation templates and SOW guardrails to secure resilience guarantees, clarify SLAs for point‑in‑time restore, and codify responsibilities across cloud and managed service partners.
Key market dynamics shaping vendor and customer strategies
Several structural forces are converging on the cloud backup market in 2026, raising the strategic stakes for buyers and vendors alike:
-
Energy and infrastructure cost pressures: Data center construction and operational costs are rising, and industry benchmarking indicates material increases in cost per megawatt. This drives interest in cloud‑native offload and in strategies that reduce long‑term on‑prem footprint.
-
Regulatory tightening on energy metrics and data locality: Regional directives now require reporting on power and water efficiency in data facilities, and data sovereignty rules continue to incentivize localized or edge deployments for critical backups.
-
Moderate market concentration: Market concentration metrics show a landscape where leading suppliers command a meaningful share but do not create a closed oligopoly — a pattern that favors differentiated vendors and solution specialization.
-
Security and resilience innovation: Vendors are embedding cybersecurity features — from immutable vaults to integrated scanning and recovery orchestration — responding to buyer demand for integrated protection stacks.
Competitive landscape — who to watch and why
The report includes an in‑depth competitive assessment of incumbent cloud providers and specialist backup vendors. Our analysis highlights capabilities, strategic positioning, and where each provider is likely to win or struggle as buyer needs evolve.
-
Amazon Web Services (AWS): AWS Backup continues to centralize policy‑based protection across AWS services and hybrid endpoints, emphasizing automation and ransomware recovery capabilities. Their scale and integration remain core advantages for cloud‑centric enterprises.
-
Microsoft Corporation: Azure Backup’s tight integration within Microsoft’s ecosystem makes it a default choice for enterprises with heavy Microsoft footprints, particularly where unified identity and compliance controls matter.
-
Google LLC: Google’s Backup and DR offerings have advanced multi‑region vaults and increased backup frequency options, reinforcing its appeal to cloud‑native workloads with strict recovery windows.
-
Veeam Software: Veeam’s platform focus on hybrid protection and expanded security features positions it as a leader for organizations seeking cross‑platform recovery and ransomware scanning across cloud and on‑prem assets.
-
Commvault Systems: Emphasizing unified data protection and cyber resilience, Commvault’s partnerships and air‑gap features cater to enterprises that prioritize defensibility and regulatory alignment.
-
Rubrik, Druva, Cohesity: These specialists continue to push automation and cloud‑native management models, often offering faster time‑to‑value for hybrid and SaaS backup use cases.
-
Acronis, Veritas, Backblaze, Barracuda: Each brings niche strengths — from cyber‑integrated backup to cost‑effective cloud storage options and focused SaaS/email protection — enabling targeted procurement strategies.
Recent vendor developments further validate trends we track. For example, product updates and releases in early‑to‑mid 2026 expanded scanning and cross‑platform coverage, while strategic partnerships have deepened integration between backup specialists and major cloud platforms. These moves accelerate buyer expectations for interoperability, automated recovery testing, and partner‑mediated managed services.
Strategic playbook for enterprise leaders in 2026
For CIOs, CISOs, and procurement leaders planning budgets and vendor selections this year, PW Consulting recommends a three‑track approach:
-
Stabilize: Harden critical backups with immutable storage, validated air‑gaps, and defined recovery exercises for top business processes. Make these non‑negotiables in contracts and SLAs.
-
Optimize: Use a phased TCO migration plan to rebalance on‑prem and cloud backups, factoring in projected energy and construction cost inflation. Apply lifecycle policies and deduplication to rein in storage growth.
-
Differentiate: Invest in automation, metadata‑driven recovery, and integrated cyber‑forensics to reduce mean time to recovery and lower operational overhead. Prioritize vendors that demonstrate cross‑cloud orchestration and transparent cost models.
How PW Consulting’s report accelerates procurement and architecture choices
We designed the report to shorten vendor selection cycles and de‑risk architectural pivots. Practical outputs include weighted vendor scorecards, sample RFP language, and validated TCO scenarios that executives can present to finance and audit committees. Our scenario planning also helps boards understand the funding and operational commitments required under differing growth and regulatory outcomes.
Accessing the full intelligence
This release is intentionally a strategic “preview.” To preserve actionable value for subscribers and to support confidential procurement workflows, we have withheld granular regional and application segmentation figures from this public summary. The full report contains detailed sub‑segment data, downloadable financial models, and complete vendor benchmarking tables that are essential for procurement negotiation and technical specification workshops.
For organizations evaluating backup strategy in 2026, the full PW Consulting Cloud Backup System Market report is the operational playbook needed to convert market momentum into durable resilience. Visit our report page to unlock the complete dataset, download the TCO toolkit, and schedule a briefing with our analysts.
For detailed analysis of this topic, please visit the official page: Cloud Backup System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Micro System Analyzer Market to Expand at an 8.36% CAGR — New Report Reveals Growth Drivers and Regional Leaders
By pmarketresearch, 2026-07-13
PW Consulting Releases Micro System Analyzer Market Report: Strategic Imperatives for 2026 Decision-Makers
As organizations across semiconductor test, MEMS design, medical-device R&D and precision manufacturing set priorities for 2026, PW Consulting's new Micro System Analyzer (MSA) Market report equips executives with a compact, decision-ready intelligence package. Our analysis shows the global MSA market expanded steadily through 2020–2025, reaching USD 245.8 Million in 2025 and is forecast to accelerate at a compounded annual growth rate (CAGR) of 8.36% over the 2026–2032 horizon, driving the market toward the USD 431.2 Million range by 2032. This release synthesizes historical performance, disruptive technology vectors, competitive positioning, and actionable playbooks — while preserving the proprietary granular tables and scenario datasets behind our web portal to support transaction-level engagements and procurement decisions.
Micro System Analyzer Market
Why this report matters for 2026 strategic planning
-
Capital allocation precision: With MSAs now integral to device characterization, wafer-level testing, and reliability validation, procurement and CAPEX choices made in 2026 will lock in capability sets across multi-year product cycles. Our report translates macro growth trajectories into stress-tested investment scenarios for the coming planning cycle.
Micro System Analyzer Market -
Product and roadmap alignment: MSA capabilities — from non-contact optical vibrometry to high-resolution topography — materially influence MEMS and microsystem product design windows. The report identifies which instrument capabilities are becoming table-stakes versus differentiators, enabling R&D leaders to calibrate roadmaps and partner strategies.
Micro System Analyzer Market -
Regulatory and clinical pathways: For medical and bio-MEMS in particular, non-contact characterization mitigates measurement-induced artifacts, strengthening regulatory submissions and reliability claims. We map where test evidence derived from MSAs directly supports compliance, clinical validation, and risk management decisions.
-
M&A and partnership timing: Given the market’s defined concentration profile and steady growth, 2026 is a pivotal year for bolt-on acquisitions, strategic partnerships with OEM test providers, and establishment of service labs. The report provides executable M&A playbooks and partner scorecards.
High-level takeaways (executive summary)
-
Sustained, above-market growth: The MSA market has transitioned from a niche R&D toolset to an essential element of commercial MEMS manufacturing and medical-device validation. The projected mid-single-digit to high-single-digit CAGR reflects broadening application contexts and greater adoption of optical, non-contact methods in production and test environments.
-
Technology-driven differentiation: Optical techniques that enable high-bandwidth dynamic measurements and sub-micron topography are converging with software and automation to create vertically integrated test solutions. Suppliers succeeding in 2026 will be those that combine instrument hardware with robust signal processing, test automation and data workflows.
-
Moderate market concentration: The market displays a measurable degree of concentration — our analysis shows that the top three providers command a significant share of the addressable market, and the top five control a clear majority. This creates an attractive window for specialist entrants offering complementary services, software, or regionally focused manufacturing-test partnerships.
-
Service and aftermarket uplift: As instruments move from lab to shop floor, recurring revenue from calibration, turnkey test services, and software subscriptions will be a primary margin lever for vendors and a source of value for buyers seeking total-cost-of-ownership predictability.
What’s inside the report — actionable deliverables
-
Market sizing and scenario models: Base-year 2025 calibration, historical 2020–2025 dynamics, and three forecast scenarios through 2032 (conservative, base, accelerated), each with sensitivity analyses you can drop into corporate financial models.
-
Technology deep dives: Comparative assessments of core measurement approaches, instrumentation trade-offs, and signal-to-noise implications for high-bandwidth dynamic testing and surface topography measurement.
-
Application use cases: End-user workflows mapped to instrument capabilities for automotive sensing, consumer electronics, healthcare/bio-MEMS and aerospace applications — including suggested test benches and acceptance criteria.
-
Vendor benchmarking: Profiles and technical scorecards for leading suppliers (including instrument families, service ecosystems, and IP positions), alongside procurement and evaluation templates for RFPs.
-
Go-to-market and commercialization playbook: Channel strategies, pricing models, service offering templates, and a buyer’s checklist for capital procurement, in-field validation, and lifecycle management.
-
Regulatory map and evidence matrix: Where non-contact MSA-derived measurements support regulatory filings, quality systems and reliability testing — including a crosswalk to common regulatory submission needs.
-
M&A and partnership toolkit: Valuation drivers, integration risk checklist, and a short-listing framework for strategic targets and service partners to accelerate scale and geographic reach.
Competitive landscape: profile and implications
Our vendor workstream highlights a small set of specialist equipment manufacturers that dominate the active supply of integrated Micro System Analyzers. One primary active manufacturer in this space offers a broad MSA product family — from compact benchtop systems to high-end modular workstations — designed for static and dynamic 3D characterization of MEMS and microsystems. Their platforms are optical, non-contact, and engineered to capture surface topography alongside in-plane and out-of-plane vibrations across very wide bandwidths. Because these instruments are explicitly qualified for biomedical samples and medical-device workflows, they are frequently selected for R&D, wafer-level testing, quality control, and reliability assessments where non-intrusive measurement is essential.
Implications for buyers and investors:
-
Vendor selection must consider lifecycle support and domain expertise: Long-term value accrues to suppliers who pair instrumentation with application know-how, traceable calibration, and validated test methods for regulated industries.
-
Partnership ecosystems matter: Instrument vendors that embed their tools within broader test-service networks or integrate with semiconductor fabs and clinical labs enjoy preferential adoption curves.
-
Barriers and opportunities: Building an MSA capability requires optical engineering, precision mechanics, and sophisticated signal-processing software. This raises the bar to entry but creates fertile opportunities for adjacent players — software providers, calibration labs, and systems integrators — to capture aftermarket and data-analytics value.
Recommended strategic actions for 2026 (prioritized)
-
Immediate (0–12 months): Conduct a measurement-readiness audit. Map existing test insufficiencies to specific MSA capabilities, then run a supplier pre-qualification process using the report’s RFP template. For medical-device programs, prioritize instruments and workflows that generate regulatory-grade evidence without mass-loading artifacts.
-
Near-term (12–24 months): Pilot integrated instrument-plus-software deployments on representative product lines. Negotiate service-level agreements linking uptime, calibration cadence, and data quality metrics to price. Explore channel or lab partnerships to mitigate CAPEX and accelerate time-to-market.
-
Medium-term (24–60 months): Build recurring revenue lines around test-as-a-service if you are an instrument vendor, or secure supply through exclusive channel agreements if you are a device OEM. For strategic investors, evaluate bolt-on acquisitions that expand service footprint or add proprietary software analytics.
How corporate strategy teams should use this report
-
Board-level briefings: Use our distilled scenario models to quantify downside and upside cases for CAPEX proposals and to stress-test procurement timelines against product development milestones.
-
Procurement and supplier governance: Adopt the report’s vendor-scorecard framework to rationalize instrument selection across sites and product lines, and to define standardized acceptance tests that reduce vendor lock-in risk.
-
Product and regulatory planning: Integrate the report’s evidence matrix into clinical and regulatory plans where MEMS-enabled medical devices are concerned; early alignment of measurement approach and regulatory expectation reduces approval risk.
Conclusion — the 2026 decision window
The Micro System Analyzer market is moving from specialized laboratory instrumentation toward integrated elements of production-test and regulatory-evidence ecosystems. With a solid historical footing through 2025 and a robust projected growth path out to 2032, 2026 represents a tactical inflection point: decisions on instrument procurement, service partnerships, and software integration made this year will materially affect time-to-market, product reliability narratives, and operating margins. PW Consulting’s report gives you the analytical foundation, vendor comparison tools, and executable playbooks to convert market growth into competitive advantage — while full tables, primary interview transcripts, and the detailed segmentation dataset remain available on our website for teams preparing transaction-level or procurement-compliant actions.
To access the full dataset, vendor scorecards, and scenario models that underpin this executive briefing, visit the PW Consulting Micro System Analyzer Market report landing page and request the complete package for procurement, M&A, or product strategy workstreams.
For detailed analysis of this topic, please visit the official page: Micro System Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Cloud Logistics Software Boom — 14.5% CAGR Projected for 2026–2032
By pmarketresearch, 2026-07-13
Cloud Logistics Software Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Study
As global supply chains pivot from recovery to strategic transformation, cloud logistics software is no longer a cost-saving experiment — it is a core enabler of resiliency, agility and new revenue models. PW Consulting’s new market research, prepared as a decision-grade tool for executives planning investments in 2026, synthesizes a multi-year quantitative forecast with practical, executable guidance. Our analysis captures the market’s evolution through 2025 and projects forward across 2026–2032 with a 14.5% compound annual growth rate, delivering an evidence-based foundation for board-level conversations about platform selection, deployment architectures, compliance posture and supplier strategy.
Cloud Logistics Software Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 is a hinge year. Businesses are moving from pilots to large-scale rollouts of cloud-native logistics capabilities (transportation, warehousing, freight forwarding and visibility systems). The market has reached a new scale and is forecast to expand materially over the next six years, reshaping buying patterns and partnership models.
Cloud Logistics Software Market -
Risk-reward clarity: Our study quantifies market momentum and couples it with scenario testing — so procurement, IT and supply chain leaders can assess both upside and downside of platform choices given near-term cost pressures and regulatory shifts.
Cloud Logistics Software Market -
Actionable playbooks: Beyond a topline forecast, the report delivers implementation-ready assets — including vendor scorecards, integration blueprints, TCO models and contractual risk checklists — designed to shorten procurement cycles and reduce deployment risk.
Market trajectory and structure (what the numbers tell you)
PW Consulting’s modeling shows a market that accelerated through 2020–2025 and is entering a robust growth phase. The market scale in 2025 provides the baseline for our 2026–2032 forecast, with the model driven by adoption trends across transportation management, warehouse management, freight forwarding platforms and adjacent cloud logistics services. At the same time, our concentration analysis indicates a market with significant vendor activity: the top three firms account for a material share of market revenue while the top five collectively nearly half the market — a profile that favors both large-suite incumbents and specialized challengers.
For executives, the implication is straightforward: strategic sourcing must balance the functional depth and ecosystem reach of large cloud incumbents with the innovation velocity and niche specialization of focused providers. Our report provides the quantitative foundation — and the decision frameworks — to weigh those trade-offs.
Competitive landscape: positioning, playbooks and strategic moves
We profile leading vendors to help clients align procurement strategy with business objectives. Key themes that emerge across vendor assessments include platform openness, cloud-native architecture, AI/ML capability, partner ecosystems and vertical depth.
-
Large enterprise suites (SAP SE, Oracle Corporation, Microsoft Corporation): These providers compete on integrated execution and broad functional coverage. They appeal to customers prioritizing ERP-driven end-to-end workflows, deep analytics and global support. Their strategic strengths include large install bases and embedded commercial relationships; their challenges often center on integration complexity and time-to-value for logistics-focused users.
-
Cloud-native supply chain specialists (Blue Yonder, Manhattan Associates, E2open): These vendors emphasize rapid deployment, AI-enabled planning and logistics orchestration. They are increasingly attractive where speed and continuous optimization are paramount, and where organizations prefer a best-of-breed approach to logistics execution.
-
Freight-forwarding and forwarding-centric platforms (WiseTech Global, Magaya, Descartes): These providers bring deep functional fit for freight forwarding, customs and cross-border operations. Their domain expertise shortens implementation cycles for logistics-centric enterprises and freight intermediaries.
-
Fleet and routing specialists (Trimble, Dispatch Science): Focused on executional excellence in transportation routing and last-mile logistics, these vendors are critical partners for companies prioritizing delivery quality and cost control.
Our vendor scorecards evaluate product depth, cloud maturity, integration APIs, data model standardization, go-to-market motion and post-sale services. They highlight which providers are moving from single-module success to platform plays and which are carving stable niches — insight intended to guide vendor shortlists and RFP design.
Recent developments shaping 2026 strategies
-
Product innovation: Market entrants and incumbents alike continue to layer AI and automation into execution and planning. Notably, new unified AI-driven last-mile platforms introduced in early 2026 demonstrate how execution, analytics and automation are converging into single cloud-native stacks — a development that accelerates consolidation of execution data and reduces fragmentation.
-
Recognition and momentum: Industry awards and reviews (e.g., leading software rankings in 2026) are certifying the readiness of several cloud logistics platforms for broader enterprise adoption, influencing procurement shortlists and investment decisions.
Regulatory and cost dynamics that require new sourcing rules
Two concurrent pressures are reshaping strategy and supplier negotiations in 2026:
-
Rising cloud hosting costs: Cloud providers have signaled price increases in 2026 tied to higher server hardware costs, which affects SaaS economics for logistics platforms. Our TCO modules allow procurement teams to run sensitivity analyses for a 5–10% lift in cloud service charges and to quantify pass-through risk embedded in subscription agreements.
-
Regulatory intensification: Continued enforcement of GDPR cross-border transfer rules, the operationalization of EU AI Act requirements and heightened expectations for zero-trust architectures mean that vendors and adopters must demonstrate robust documentation, risk assessments and continuous monitoring. The report includes a compliance playbook mapping required controls to RFP clauses and implementation milestones.
Practical deliverables inside the report
PW Consulting’s study is built for action. Key deliverables include:
-
Quantitative market model covering historical performance (2020–2025) and forecasts (2026–2032) with driver-level sensitivities and scenario variants for slower/faster cloud price growth and regulatory friction.
-
Vendor assessment framework and scorecards that synthesize product capability, cloud maturity, integration posture and commercial architecture.
-
Implementation playbooks for six common buyer archetypes (global retailer, third-party logistics provider, regional carrier, manufacturing network, e-commerce-first merchant, freight forwarder), each with migration paths, typical timelines and risk mitigations.
-
TCO and ROI tools calibrated to real-world contract constructs, enabling CFOs to stress-test spend under different cloud price and adoption scenarios.
-
Compliance and data governance checklist tailored to cloud logistics operations — covering SCCs, Transfer Impact Assessments, AI risk documentation, zero-trust requirements and vendor due diligence.
-
M&A and partnership heatmap: where strategic buyers should look for tuck-in capabilities versus where partnering is a faster path to capability.
How to use the report in 90, 180 and 365 day roadmaps
-
90 days: Use our vendor scorecards and TCO sensitivity runs to finalize a two- to three-vendor shortlist and to build a proof-of-value charter with measurable KPIs.
-
180 days: Execute integration pilots with pre-defined data models, security baselines and contract clauses informed by our compliance playbook; renegotiate cloud cost pass-through terms if indicated by sensitivity testing.
-
365 days: Scale to production, implement continuous monitoring and begin capability extension (AI-driven optimization, dynamic routing, predictive warehousing) while tracking ROI against the report’s scenario benchmarks.
What we deliberately withheld (and why)
Consistent with the “trailer” principle of this release, we present high-confidence macro trendlines, concentration metrics and actionable frameworks while reserving full segmentation tables, detailed regional/application splits and supplier-specific revenue breakdowns for the full report. That detailed material includes granular market shares, region-by-region adoption maps, and module-level revenue estimates that are essential for procurement negotiations and M&A diligence — and are available directly through our full product page.
Conclusion: strategic choices for 2026
Leaders face three interdependent decisions in 2026: which suppliers to trust for multi-year execution; how to structure contracts to share cloud cost risk; and how to bake compliance and AI governance into procurement and implementation. PW Consulting’s Cloud Logistics Software Market report gives boards and executive teams a clear, implementable playbook for those choices — coupling a robust quantitative forecast (anchored in 2025 baseline data and a 14.5% CAGR outlook) with the tactical tools needed to move from strategy to execution.
For supply chain executives, CIOs and investment teams preparing 2026 budgets and roadmaps, the full report provides the detailed segmentation, vendor revenue data, and plug-and-play artifacts required for procurement, legal and IT to act decisively. To access the complete intelligence package — including the full market segmentation and vendor-level detail — please consult the PW Consulting report page.
PW Consulting — Senior Strategic Advisory and Industry Analysis for Cloud Logistics Transformation.
For detailed analysis of this topic, please visit the official page: Cloud Logistics Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fish Nets Market to Expand at a 6.45% CAGR — A Net Gain for Industry Players
By pmarketresearch, 2026-07-13
Fish Nets Market 2026 Strategic Brief: Navigating Growth, Resilience, and Sustainability
PW Consulting is pleased to present an executive briefing of our forthcoming Fish Nets Market research report. As global supply chains, regulatory regimes, and materials science converge to reshape the fishing and aquaculture value chains, senior leaders must convert market signals into concrete 2026 decisions. This briefing highlights the macro picture, strategic inflection points, and the practical playbook included in the full report—while deliberately withholding detailed segment tables and fine-grained regional splits to motivate direct access to the source intelligence.
Fish Nets Market
Market at a Glance: Growth Trajectory and What It Means for 2026
The Fish Nets Market has moved from recovery to steady expansion. On a consolidated basis (USD, revenue unit: Million), the market expanded from the early-2020 baseline through 2025 to reach a declared 2025 base-year total and is projected to continue on a multi-year growth path. Our model indicates a compound annual growth rate (CAGR) of 6.45% for the forecast window beginning 2026, with the market progressing materially across the forecast horizon to 2032.
Fish Nets Market
Two high-level takeaways from the macro math that will drive boardroom decisions in 2026:
Fish Nets Market
- Momentum and optionality: The combination of steady CAGR and continued investment in aquaculture and commercial fishing infrastructure creates optionality for mid-sized manufacturers and buyers to scale selectively.
- Timing matters: Our near-term projection shows a significant step-up in total market value in 2026 versus the base year—a window where capital allocation (capex), long-term supplier contracts, and product portfolio pivots will deliver outsized impact.
Why This Report Matters for 2026 Decision-Making
Business leaders face three overlapping pressures entering 2026: tightening sustainability mandates, raw material volatility, and concentrated buyer power. The report synthesizes primary research, supplier interviews, material-technology assessments, and scenario modeling to transform these pressures into tactical options. Specifically, the research supports:
- Procurement strategy design: When to lock multi-year supply contracts versus adopt spot buying—and how to structure clauses for biodegradability or recycled content.
- R&D and product roadmaps: Prioritizing investments in alternative polymers, knotless vs. knotted product lines, and low-drag designs that reduce vessel fuel consumption.
- M&A and partnership scouting: Identifying attractive acquisition targets and joint-venture archetypes that accelerate entry into premium aquaculture net systems or circular-material value chains.
Report Contents — Practical, Actionable Deliverables
The full report is built for application, not only comprehension. Key deliverables include:
- Granular market model (macro totals across 2020–2032, validated by supplier shipment data and trade flows), with scenario variants for commodity shocks and accelerated regulatory uptake.
- Supply chain heat map identifying single points of failure, lead-time baselines, and nearshore vs. offshore sourcing trade-offs.
- Commercial playbook—procurement templates, risk-adjusted supplier scorecards, and contract language for sustainability clauses.
- Technology assessment of polymer alternatives (HDPE, UHMWPE, regenerated nylon, new marine-biodegradable polymers), comparing lifecycle durability, weight, and cost per functional year.
- Strategic M&A screen with target profiles and valuation multiples tailored to niche manufacturing (e.g., high-tenacity monofilament producers, custom-weave operations).
- Regulatory & ESG compendium summarizing jurisdictional trends that affect product compliance, end-of-life management, and reporting obligations.
- Competitive benchmarking and deep-dive company dossiers (lead manufacturers, specialized fabricators, and vertically integrated suppliers) with commercial positioning and capability maps.
Competitive Landscape: Who Matters and Why
The market structure exhibits moderate concentration—enough to create pricing influence among leading incumbents while leaving room for niche specialization. Our concentration metrics confirm that the top three players together account for a meaningful share of the worldwide market, and the top five control over half of global sales—conditions that make strategic partnerships and differentiation central to mid-market success.
Highlighted players profiled in the report include:
- Nitto Seimo Co., Ltd. (Tokyo, Japan) — a comprehensive player across knotted and knotless systems and diverse net types; recent visible investments include a refreshed customer-facing platform emphasizing product technology.
- King Chou Marine Technology Co., Ltd. (Kaohsiung, Taiwan) — long-standing purse seine and aquaculture net specialist with customizable cage systems suitable for regionally scaled farming operations.
- Garware Technical Fibres Limited (Pune, India) — focused on high-performance HDPE solutions and ropes, well positioned to serve growing aquaculture cage demand.
- Miller Net Company Inc. and Memphis Net & Twine Company Inc. (Memphis, TN, USA) — US-based manufacturers and supply specialists offering customization and strong service footprints for commercial fleets.
- AKVA group (Egersund Net, Norway) and Badinotti Group (Milan, Italy/Peru operations) — European suppliers catering to premium aquaculture and pelagic fisheries with engineering-led net systems.
- Momoi Fishing Net Mfg. Co., Ltd. (Japan) — integrated producer with control over synthetic fibre upstream processes, enabling quality and supply reliability advantages.
Our competitive analysis evaluates manufacturing breadth, material expertise, service networks, and strategic intent—allowing clients to choose partners based on operational KPIs (lead times, warranty terms, end-of-life support) rather than brand alone.
Materials & Sustainability: The New Axis of Competition
Material innovation is not incremental—it's a strategic pivot. Several industry signals underscore this:
- Biodegradable polymer pilots have moved from lab to commercial field tests in multiple African markets, demonstrating practical viability under specific use cases.
- Recycled and regenerated nylons are entering circular product launches, enabling closed-loop narratives that matter to downstream buyers in premium seafood chains.
- Adoption of HDPE and UHMWPE fiber blends is already lifting the durability-to-weight ratio for a meaningful share of newly manufactured nets, changing lifetime cost calculations.
- Life-cycle assessments show significant CO2-equivalent savings when fishing nets are recycled into new polymers—an important lever for corporate sustainability accounting and for meeting consumer-facing environmental commitments.
For 2026 planning, the strategic implication is clear: buyers and manufacturers must develop a materials roadmap that aligns procurement, engineering, and end-of-life channels. Early adopters of validated circular solutions will capture ESG premiums and reduce regulatory compliance risk.
Scenario Planning: Stress Tests to Inform CapEx and Inventory
Our scenario module models three plausible 2026-2028 pathways—base case (steady growth and moderate raw material inflation), sustainability-accelerated (rapid regulatory adoption and premium for circular products), and supply-shock (disruption in polymer supply). Each scenario outputs decision rules for:
- Inventory buffers and safety-stock triggers tied to lead-time elasticity.
- CapEx thresholds for automation or nearshoring manufacturing capacity.
- Pricing strategy levers to protect margins under each stress pattern.
Practical Recommendations for 2026 Executives
- Prioritize supplier diversification focused on material capability, not only geography—identify one strategic partner for sustainable yarns and a second for cost-flexible commodity supply.
- Commit a staged R&D budget to at least one alternative polymer proof-of-concept that aligns with your sustainability commitments and customer willingness-to-pay data.
- Include circularity clauses in procurement contracts—recovery and recycling commitments can reduce total cost of ownership when quantified across lifecycle models.
- Use market concentration signals to negotiate favorable contract terms with leading suppliers while scouting vertical integration or alliance possibilities for mid-stream capabilities.
- Implement scenario-driven inventory rules to hedge for both material and logistics volatility without eroding working capital efficiency.
What Is Intentionally Omitted from This Brief
In keeping with the “trailer” purpose of this release, we have showcased the analytical framework, strategic implications, and headline macro figures (including the base year and CAGR). We have intentionally withheld the granular segment tables and regional/application value splits that underpin our models. These detailed breakdowns—essential for contract negotiations, localized go-to-market plans, and precise ROI calculations—are available only in the full report and accompanying dataset.
Next Steps & How PW Consulting Can Help
For procurement directors, product leaders, and corporate strategy teams preparing 2026 plans, the full Fish Nets Market report provides the calibrated inputs and executable templates needed to act with confidence. PW Consulting offers tailored briefings, custom scenario modeling for your supplier base, and implementation support—including supplier scorecard rollouts and pilot designs for material transition projects.
To obtain the complete dataset, segmentation tables, and company dossiers referenced here, please request the full report through PW Consulting. Our team will prioritize clients facing imminent 2026 decisions and can deliver a condensed advisory sprint to translate findings into an actionable 90-day plan.
PW Consulting — Strategic clarity for complex markets.
For detailed analysis of this topic, please visit the official page: Fish Nets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luciferase Assay Market Poised to Rise from USD 620.0 Million in 2025 to USD 992.33 Million by 2032 at a 6.95% CAGR
By pmarketresearch, 2026-07-13
Luciferase Assay Market 2026: Strategic Briefing — Where to Play and How to Win
PW Consulting’s latest Luciferase Assay Market report delivers a pragmatic, decision-grade blueprint for executives preparing strategic moves in 2026. Drawing on a validated historical dataset (2020–2025) and a detailed forecast to 2032, the research synthesizes commercial dynamics, technology inflection points, competitive positioning, and executional playbooks. The market’s macro trajectory — rising from a mid‑2020s base to a near‑billion dollar opportunity by the end of the decade, and expanding at a compound annual growth rate of approximately 6.95% through the forecast horizon — creates actionable windows for suppliers, service providers, and strategic investors. This briefing outlines the report’s strategic value, the high‑level market picture, competitive implications, and the practical tools included for 2026 corporate decision‑making.
Luciferase Assay Market
Why this report matters for 2026 decisions
-
Timing precision: 2026 is a hinge year. The market has moved beyond early‑adopter product cycles and now rewards scale, multiplexing capability, and integration with high‑throughput workflows. Our analysis isolates the operational changes that convert R&D traction into commercial traction within the next 12–24 months.
Luciferase Assay Market -
Risk‑calibrated opportunity assessment: With clear macro growth (CAGR ~6.95%) and measurable concentration among the market leaders (top‑three and top‑five firms representing meaningful shares of market revenue), the landscape favors focused investments in platform differentiation and channel depth rather than scattershot expansion.
Luciferase Assay Market -
Decision frameworks, not just data: The report translates market movement into executable choices — where to deploy R&D spend, when to pursue pricing premium vs. volume play, what partnerships accelerate access to end‑users, and how to structure M&A screening to capture synergistic capability.
Market trajectory — the high‑level picture
Our consolidated dataset shows the luciferase assay market expanding steadily from a base of roughly USD 450 million in 2020 to approximately USD 620 million in 2025, with further acceleration expected through the 2026–2032 forecast period. By 2032 the market is projected to approach a nine‑figure territory nearing USD 1.0 billion. This growth is driven by three structural forces: continued demand from drug discovery and basic research; adoption of higher‑sensitivity luciferase technologies enabling new assay formats; and the scaling of high‑throughput screening operations in biopharma and CROs.
Importantly, market concentration metrics indicate moderate consolidation: the combined share of the three largest vendors and the five largest vendors points to a market where established players retain structural advantages, but where specialist entrants with differentiated assay chemistries or integrated services can capture meaningful niche share. These dynamics shape realistic thresholds for profitable entry and scale.
Strategic implications for corporate leaders in 2026
-
Product strategy — prioritize sensitivity, multiplexing, and workflow integration. Customers increasingly value assays that reduce hands‑on time, enable multiplexed readouts, and integrate with automated liquid handlers and LIMS. Products that demonstrate compatibility with multi‑mode detection and two‑color bioluminescence techniques are positioned to command premium pricing.
-
Commercial model — hybridize sales motions. Purely transactional distribution is being outcompeted by bundled architectures that combine reagent kits, validated protocols, and consumable subscriptions. Firms that layer technical services (assay validation, protocol transfer, automation integration) onto reagent sales report higher retention and margin stability.
-
M&A and partnership focus — target capability gaps rather than scale alone. Bolt‑on acquisitions that add proprietary luciferase variants, substrate chemistries, or software‑enabled analytics accelerate market penetration more effectively than generalist consolidation. Similarly, collaborations with instrument OEMs and contract research organizations expand addressable demand through co‑validated workflows.
-
Geographic and channel entry — be selective. While global demand grows, the most attractive near‑term opportunities favor jurisdictions with dense biopharma clusters and mature translational research ecologies. Channel strategies should optimize for laboratory preference and regulatory nuance rather than broad distribution rollouts.
-
Regulatory posture — standardize RUO clarity and clinical limitations. Luciferase assay kits remain predominantly designated for Research Use Only (RUO) and are not intended as diagnostic or therapeutic devices in clinical settings. Firms must standardize labeling, customer communications, and quality systems to avoid regulatory ambiguity while supporting translational research needs.
Report contents — what you get
Our report was designed as a strategic toolset for executives, commercialization leads, and investors. It synthesizes primary interviews, supplier and buyer surveys, and secondary literature into a compact set of actionable deliverables:
-
Market sizing and validated 2020–2025 history, with robust scenario forecasts through 2032 built from bottom‑up and top‑down reconciliations.
-
Segment playbooks that prioritize addressable segments (by product type, application area, and channel motion) and map the most defensible routes to share gains — presented as go‑to‑market blueprints rather than raw sub‑segment tables.
-
Technology and innovation radar summarizing emergent luciferase chemistries, imaging modalities, and multiplexing strategies — including an assessment of where incremental R&D produces step‑changes vs. incremental improvements.
-
Commercial execution toolkit: pricing elasticity models, distributor vs. direct sales decision frameworks, and templates for subscription/consumable economics with margin sensitivity analysis.
-
Supply chain and operational risk matrix covering reagent sourcing, Cold‑chain implications, and supplier diversification strategies to maintain production continuity and cost control.
-
Vendor scorecards and M&A screening: qualitative assessments of capability, scale, and strategic fit for the sector’s active corporate players (profiles included), and a prioritized list of candidate M&A targets by value creation theme.
-
Case studies and protocol playbooks illustrating successful product launches, academic partnerships, and CRO collaboration models that lifted commercial adoption.
Competitive landscape — what the leader moves tell us
The market is anchored by a handful of well‑resourced firms that combine reagent platforms, catalog breadth, and channel reach with ongoing product innovation. Their competitive actions — from platform upgrades to conference‑led product signals — set technical and commercial reference points for the broader market.
-
Promega Corporation: Continues to drive innovation in small, high‑intensity luciferase systems. Recent demonstrations of red‑shifted luciferase chemistry and paired two‑color analyses (presented at an industry conference in 2026) underscore a roadmap toward multiplexed, high‑sensitivity assays that reduce cross‑talk and increase dynamic range. For challengers, the strategic response is focused R&D on assay orthogonality and sample compatibility.
-
Thermo Fisher Scientific: Leverages global commercial scale and a wide instrument/reagent portfolio to embed luciferase assays in end‑to‑end workflows. Their strength lies in cross‑selling and validated protocols. Competitors should assess partnership or integrator models to access the same customer touchpoints.
-
Revvity Inc. (formerly PerkinElmer): Positions its luciferase offerings for high‑throughput screening in large pharma environments. Their history of automation compatibility signals that assay performance at scale — reproducibility, stability of reagents, and instrument interfacing — is a differentiator.
-
Biotium and Abcam: These players offer value‑focused kits with strong application notes and community adoption. Their agility in reagent development and niche customer engagement is a reminder that targeted innovation plus strong technical support remains a viable commercial model.
-
Merck KGaA (MilliporeSigma): Maintains a broad reagent portfolio that creates stickiness within research labs. Their advantage is breadth and global logistics; newer entrants can compete by offering superior protocol transfer and co‑validation services.
Operational and regulatory caveats
-
RUO designation: Ensure product claims and sales channels align with the RUO classification; stepping toward clinical claims introduces a separate, resource‑intensive regulatory pathway.
-
Quality and reproducibility: As assays move into high‑throughput and translational contexts, buyers are less tolerant of lot‑to‑lot variability. Investment in QC, lot verification, and transparent performance datasheets is non‑negotiable.
-
Intellectual property and freedom‑to‑operate: Differentiated luciferase chemistries and substrate formulations can be protected, but patent landscapes vary by jurisdiction. Licensing risk assessment should be part of any new product launch checklist.
How to use this report in 2026 — recommended playbook
-
For product leaders: Use the technology radar and validation playbooks to prioritize a one‑to‑two year development sprint that targets multiplexing and automation compatibility.
-
For commercial leaders: Implement the pricing and channel sensitivity models to pilot a hybrid sales motion (direct + strategic distribution) in two priority geographies before scaling.
-
For corporate development: Apply the vendor scorecards and M&A screens to shortlist targets that close capability gaps (e.g., unique substrates, imaging IP, or automation‑validated assays) rather than merely adding catalogue breadth.
-
For investors and PE: Leverage the scenario forecasts and concentration metrics to model exit multiples under consolidation and to size bolt‑on investments that accelerate margin improvement through cross‑sell and manufacturing optimization.
Next steps
PW Consulting’s full Luciferase Assay Market report delivers the underlying datasets, the segment playbooks, and the executable templates referenced in this briefing. The document deliberately emphasizes strategic synthesis over raw sub‑segment disclosures to preserve client advisory value while providing the precise tools needed to make high‑confidence go/no‑go decisions in 2026. For access to the full dataset, vendor scorecards, and the downloadable execution templates, please request the comprehensive report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Luciferase Assay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Closeouts Market to Grow from USD 285.5 Billion in 2025 to USD 454.0 Billion by 2032 at 6.85% CAGR; Online Liquidation Platforms Command USD 165.4 Billion
By pmarketresearch, 2026-07-13
Closeouts Market 2026: Strategic Playbook and Market Intelligence — PW Consulting Preview
Executive summary
The closeouts market — the industrial ecosystem that converts overstock, customer returns, and surplus consumer goods into recoverable value — is entering a decisive phase. Our new Closeouts Market report (base year 2025) synthesizes five years of historical trends (2020–2025) and delivers an operationally-focused forecast for 2026–2032. At the macro level, the market expanded meaningfully in recent years (from roughly USD 250 billion in 2023 to USD 285.5 billion in 2025) and is projected to continue growing: our model anticipates the market crossing the USD 300 billion threshold in 2026 and reaching approximately USD 454 billion by 2032, at a compound annual growth rate of 6.85% over the forecast period.
Closeouts Market
This release functions as a strategic “trailer”: it demonstrates the analytical depth and actionable orientation of the full report while deliberately withholding granular segmentation tables and proprietary modeling outputs — content that is available on the report landing page for decision-makers conducting vendor selection, investment due diligence, or channel redesign in 2026.
Closeouts Market
Why this matters for enterprise decisions in 2026
- Capital allocation: The projected mid-single-digit CAGR underscores continued opportunity for scale players and niche specialists alike. Boards and CFOs evaluating investments in liquidation platforms, warehousing, or returns processing need model-ready forecasts and scenario stress tests to size capex and working capital.
- Channel strategy: Retailers and brands seeking to optimize recoveries must decide where to direct inventory (direct secondary retail, auction, online liquidation marketplaces) — a choice that materially affects margin, brand control, and speed-to-cash.
- Risk management: Macro headwinds — from tariff pass-through on imported consumer goods to retailer insolvencies increasing inventory inflows — are forcing a reappraisal of sourcing, pricing, and compliance frameworks.
What the PW Consulting Closeouts Market report delivers
We designed the study for operators, corporate strategists, private equity sponsors, and logistics partners who require practical, transaction-ready intelligence. Highlights include:
Closeouts Market
- Market architecture and dynamics: concise maps of value pools and liquidity channels, with scenario-based forecasts for 2026–2032 calibrated to macroeconomic and trade-policy inputs.
- Operational playbooks: step-by-step guides for warehouse-to-consumer workflows (inspection, grading, listing, fulfillment), plus performance benchmarks for return-to-revenue timelines.
- Channel optimization toolkit: decision matrices to choose between auction, marketplace, pallet sale, and direct-secondary retailing given inventory quality, velocity targets, and brand exposure constraints.
- Technology adoption blueprints: ROI frameworks for investments in AI-driven grading, automated sorting, dynamic pricing engines, and integrations that reduce disposition cycle time and shrinkage.
- M&A and partnership framework: diligence checklists, valuation multipliers calibrations for platform consolidations, and a playbook for integrating distinct operating models (auction vs. pallet vs. retail outlet).
- Regulatory & tariff impact module: practical guidance on hedging, pricing pass-through, and compliance considerations as trade policy evolves.
- Data products & dashboards: curated datasets and KPIs (transaction velocity, recovery rate, lot yield curves) designed for CFOs and heads of liquidation — note: detailed segmentation tables and raw datasets are available exclusively in the full report.
Competitive landscape — strategic profiles and implications
The closeouts ecosystem is characterized by numerous specialized operators and a modest level of concentration. Top-three firms collectively control under one-fifth of industry throughput, and the top-five remain below one-quarter of total capacity — a structure that favors both scale-driven consolidation and continued niche innovation.
- Direct Liquidation (United States — directliquidation.com)
Position: Market-facing leader with deep retailer/manufacturer partnerships and an auction/wholesale playbook. Strategic implication: its direct relationships with brands give it preferential access to name-brand inventory and data — a model that other platforms emulate through partnerships or white-label arrangements.
- B-Stock (United States — bstock.com)
Position: Large online wholesale marketplace connecting buyers to returned and overstocked goods from major retailers. Strategic implication: B-Stock’s value comes from marketplace liquidity and buyer network effects. For enterprises, marketplace presence accelerates velocity but requires disciplined grading and seller-side governance to protect brand equity.
- Liquidation.com (United States — liquidation.com)
Position: Auction-based platform focused on surplus consumer goods. Strategic implication: auction mechanics can maximize recoveries for heterogeneous lots but demand robust logistics and buyer screening to reduce transaction costs.
- Overstock Trader (United States — overstocktrader.com)
Position: Facilitates direct relationships between brands and off-price retailers/wholesalers. Strategic implication: direct B2B matching is increasingly attractive to sellers prioritizing speed and margin retention over market-wide discovery.
- BULQ (United States — bulq.com)
Position: Pallet and truckload wholesale supplier with emphasis on standardized SKUs and frequent lot cycles. Strategic implication: BULQ’s standardized units reduce buyer friction and enable consistent pricing — a model attractive to resellers scaling online.
- Kole Imports (United States — koleimports.com) & Similar Import/Distributor Players
Position: Direct importer and large-scale distributor supplying general merchandise and closeouts to off-price channels. Strategic implication: control of import/distribution pathways remains a differentiator where tariff exposure and freight cadence materially influence landed cost.
- Smaller B2B Specialists (e.g., Total Surplus Solutions, Countryside Closeouts, Global Distributors, UpLiquidation)
Position: Regional and category-focused players that provide micro-market access to resellers. Strategic implication: these firms are fertile targets for roll-up strategies and for acquirers seeking last-mile market coverage and specialized sourcing.
Recent industry dynamics shaping 2026 strategies
- Trade-policy and tariff pressure:
U.S. tariffs on imported consumer goods remain a salient driver of landed-cost volatility. Recent analyses indicate substantial pass-through to consumers in many categories. For liquidation stakeholders, tariffs alter the calculus of resale pricing, import arbitrage plays, and cross-border flows — all factors we model in the report’s scenario set.
- Inventory influx from retailer distress and conservative consumer spend:
A wave of higher overstock levels, amplified by retailer restructurings and more cautious households, is feeding supply into liquidation channels. This raises both opportunity (higher available volumes) and risk (downward pressure on realized prices and longer holding periods).
- Event-driven sourcing and network effects:
Industry gatherings such as ASD Market Week (March 2026), which showcased 250+ closeout suppliers, continue to accelerate deal flow, cross-border introductions, and product sourcing partnerships. Trade events, when combined with digital marketplaces, are proving instrumental in matching supply surges to buyer appetite.
Strategic imperatives for 2026 — what leaders should do now
Based on our modeling and field interviews, PW Consulting recommends a prioritized set of actions for executives planning capital and operational moves in 2026:
- Invest in grading and pricing automation:
Accuracy and speed in SKU condition assessment directly increase recovery rates. Pilots of AI-assisted grading and dynamic pricing should be deployed in Q1–Q2 2026, with 6–12 month ROI targets tied to reduced hold time and improved lot yields.
- Adopt a portfolio approach to disposition channels:
Rather than exclusive reliance on a single channel, build rules-based routing that matches inventory quality and velocity targets to auction, marketplace, pallet, or direct B2B sales to maximize blended recovery.
- Hedge tariff and logistics exposure:
Implement layered pricing clauses, revisit sourcing geographies, and contract freight capacity to moderate landed cost swings. Consider nearshoring or bonded-warehousing strategies for categories with high tariff sensitivity.
- Prepare for consolidation and M&A-enabled scale:
Fragmentation creates roll-up opportunity. Build an M&A playbook focused on integrating logistics, standardizing grading, and consolidating buyer databases to capture network effects at scale.
- Elevate compliance and reputation controls:
Stronger brand owners are increasingly selective about disposition channels. Implement traceability, quality gates, and brand-protection SLAs to maintain long-term access to high-value supply.
Concluding perspective and next steps
The closeouts market’s trajectory to 2032 presents a mix of durable growth and intensifying operational complexity. Our forecast and playbooks are designed to help executives convert that complexity into defensible advantage — whether through technology-led operations, selective M&A, or smarter channel engineering.
PW Consulting’s full Closeouts Market report includes the granular segmentation, proprietary recovery-rate matrices, downloadable datasets, and step-by-step integration templates that enterprise teams and investors demand. This preview highlights the strategic contours; the full report supplies the tactical depth required to make high-confidence decisions in 2026.
To access the full dataset, scenario models, and the operational toolkits referenced here, please visit the report landing page for purchase and instant access to supplementary materials and executive briefings.
For detailed analysis of this topic, please visit the official page: Closeouts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com