

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Luciferase Assay Market Poised to Rise from USD 620.0 Million in 2025 to USD 992.33 Million by 2032 at a 6.95% CAGR

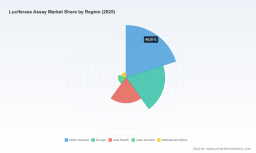
Luciferase Assay Market 2026: Strategic Briefing — Where to Play and How to Win
PW Consulting’s latest Luciferase Assay Market report delivers a pragmatic, decision-grade blueprint for executives preparing strategic moves in 2026. Drawing on a validated historical dataset (2020–2025) and a detailed forecast to 2032, the research synthesizes commercial dynamics, technology inflection points, competitive positioning, and executional playbooks. The market’s macro trajectory — rising from a mid‑2020s base to a near‑billion dollar opportunity by the end of the decade, and expanding at a compound annual growth rate of approximately 6.95% through the forecast horizon — creates actionable windows for suppliers, service providers, and strategic investors. This briefing outlines the report’s strategic value, the high‑level market picture, competitive implications, and the practical tools included for 2026 corporate decision‑making.
Luciferase Assay Market
Why this report matters for 2026 decisions
-
Timing precision: 2026 is a hinge year. The market has moved beyond early‑adopter product cycles and now rewards scale, multiplexing capability, and integration with high‑throughput workflows. Our analysis isolates the operational changes that convert R&D traction into commercial traction within the next 12–24 months.
Luciferase Assay Market -
Risk‑calibrated opportunity assessment: With clear macro growth (CAGR ~6.95%) and measurable concentration among the market leaders (top‑three and top‑five firms representing meaningful shares of market revenue), the landscape favors focused investments in platform differentiation and channel depth rather than scattershot expansion.
Luciferase Assay Market -
Decision frameworks, not just data: The report translates market movement into executable choices — where to deploy R&D spend, when to pursue pricing premium vs. volume play, what partnerships accelerate access to end‑users, and how to structure M&A screening to capture synergistic capability.
Market trajectory — the high‑level picture
Our consolidated dataset shows the luciferase assay market expanding steadily from a base of roughly USD 450 million in 2020 to approximately USD 620 million in 2025, with further acceleration expected through the 2026–2032 forecast period. By 2032 the market is projected to approach a nine‑figure territory nearing USD 1.0 billion. This growth is driven by three structural forces: continued demand from drug discovery and basic research; adoption of higher‑sensitivity luciferase technologies enabling new assay formats; and the scaling of high‑throughput screening operations in biopharma and CROs.
Importantly, market concentration metrics indicate moderate consolidation: the combined share of the three largest vendors and the five largest vendors points to a market where established players retain structural advantages, but where specialist entrants with differentiated assay chemistries or integrated services can capture meaningful niche share. These dynamics shape realistic thresholds for profitable entry and scale.
Strategic implications for corporate leaders in 2026
-
Product strategy — prioritize sensitivity, multiplexing, and workflow integration. Customers increasingly value assays that reduce hands‑on time, enable multiplexed readouts, and integrate with automated liquid handlers and LIMS. Products that demonstrate compatibility with multi‑mode detection and two‑color bioluminescence techniques are positioned to command premium pricing.
-
Commercial model — hybridize sales motions. Purely transactional distribution is being outcompeted by bundled architectures that combine reagent kits, validated protocols, and consumable subscriptions. Firms that layer technical services (assay validation, protocol transfer, automation integration) onto reagent sales report higher retention and margin stability.
-
M&A and partnership focus — target capability gaps rather than scale alone. Bolt‑on acquisitions that add proprietary luciferase variants, substrate chemistries, or software‑enabled analytics accelerate market penetration more effectively than generalist consolidation. Similarly, collaborations with instrument OEMs and contract research organizations expand addressable demand through co‑validated workflows.
-
Geographic and channel entry — be selective. While global demand grows, the most attractive near‑term opportunities favor jurisdictions with dense biopharma clusters and mature translational research ecologies. Channel strategies should optimize for laboratory preference and regulatory nuance rather than broad distribution rollouts.
-
Regulatory posture — standardize RUO clarity and clinical limitations. Luciferase assay kits remain predominantly designated for Research Use Only (RUO) and are not intended as diagnostic or therapeutic devices in clinical settings. Firms must standardize labeling, customer communications, and quality systems to avoid regulatory ambiguity while supporting translational research needs.
Report contents — what you get
Our report was designed as a strategic toolset for executives, commercialization leads, and investors. It synthesizes primary interviews, supplier and buyer surveys, and secondary literature into a compact set of actionable deliverables:
-
Market sizing and validated 2020–2025 history, with robust scenario forecasts through 2032 built from bottom‑up and top‑down reconciliations.
-
Segment playbooks that prioritize addressable segments (by product type, application area, and channel motion) and map the most defensible routes to share gains — presented as go‑to‑market blueprints rather than raw sub‑segment tables.
-
Technology and innovation radar summarizing emergent luciferase chemistries, imaging modalities, and multiplexing strategies — including an assessment of where incremental R&D produces step‑changes vs. incremental improvements.
-
Commercial execution toolkit: pricing elasticity models, distributor vs. direct sales decision frameworks, and templates for subscription/consumable economics with margin sensitivity analysis.
-
Supply chain and operational risk matrix covering reagent sourcing, Cold‑chain implications, and supplier diversification strategies to maintain production continuity and cost control.
-
Vendor scorecards and M&A screening: qualitative assessments of capability, scale, and strategic fit for the sector’s active corporate players (profiles included), and a prioritized list of candidate M&A targets by value creation theme.
-
Case studies and protocol playbooks illustrating successful product launches, academic partnerships, and CRO collaboration models that lifted commercial adoption.
Competitive landscape — what the leader moves tell us
The market is anchored by a handful of well‑resourced firms that combine reagent platforms, catalog breadth, and channel reach with ongoing product innovation. Their competitive actions — from platform upgrades to conference‑led product signals — set technical and commercial reference points for the broader market.
-
Promega Corporation: Continues to drive innovation in small, high‑intensity luciferase systems. Recent demonstrations of red‑shifted luciferase chemistry and paired two‑color analyses (presented at an industry conference in 2026) underscore a roadmap toward multiplexed, high‑sensitivity assays that reduce cross‑talk and increase dynamic range. For challengers, the strategic response is focused R&D on assay orthogonality and sample compatibility.
-
Thermo Fisher Scientific: Leverages global commercial scale and a wide instrument/reagent portfolio to embed luciferase assays in end‑to‑end workflows. Their strength lies in cross‑selling and validated protocols. Competitors should assess partnership or integrator models to access the same customer touchpoints.
-
Revvity Inc. (formerly PerkinElmer): Positions its luciferase offerings for high‑throughput screening in large pharma environments. Their history of automation compatibility signals that assay performance at scale — reproducibility, stability of reagents, and instrument interfacing — is a differentiator.
-
Biotium and Abcam: These players offer value‑focused kits with strong application notes and community adoption. Their agility in reagent development and niche customer engagement is a reminder that targeted innovation plus strong technical support remains a viable commercial model.
-
Merck KGaA (MilliporeSigma): Maintains a broad reagent portfolio that creates stickiness within research labs. Their advantage is breadth and global logistics; newer entrants can compete by offering superior protocol transfer and co‑validation services.
Operational and regulatory caveats
-
RUO designation: Ensure product claims and sales channels align with the RUO classification; stepping toward clinical claims introduces a separate, resource‑intensive regulatory pathway.
-
Quality and reproducibility: As assays move into high‑throughput and translational contexts, buyers are less tolerant of lot‑to‑lot variability. Investment in QC, lot verification, and transparent performance datasheets is non‑negotiable.
-
Intellectual property and freedom‑to‑operate: Differentiated luciferase chemistries and substrate formulations can be protected, but patent landscapes vary by jurisdiction. Licensing risk assessment should be part of any new product launch checklist.
How to use this report in 2026 — recommended playbook
-
For product leaders: Use the technology radar and validation playbooks to prioritize a one‑to‑two year development sprint that targets multiplexing and automation compatibility.
-
For commercial leaders: Implement the pricing and channel sensitivity models to pilot a hybrid sales motion (direct + strategic distribution) in two priority geographies before scaling.
-
For corporate development: Apply the vendor scorecards and M&A screens to shortlist targets that close capability gaps (e.g., unique substrates, imaging IP, or automation‑validated assays) rather than merely adding catalogue breadth.
-
For investors and PE: Leverage the scenario forecasts and concentration metrics to model exit multiples under consolidation and to size bolt‑on investments that accelerate margin improvement through cross‑sell and manufacturing optimization.
Next steps
PW Consulting’s full Luciferase Assay Market report delivers the underlying datasets, the segment playbooks, and the executable templates referenced in this briefing. The document deliberately emphasizes strategic synthesis over raw sub‑segment disclosures to preserve client advisory value while providing the precise tools needed to make high‑confidence go/no‑go decisions in 2026. For access to the full dataset, vendor scorecards, and the downloadable execution templates, please request the comprehensive report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Luciferase Assay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com