

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Elastic Sealing Gate Valve Market to Grow from USD 1,450.0 Million in 2025 to USD 2,374.46 Million by 2032 at a 7.3% CAGR — Asia Pacific Leads with USD 648.6M

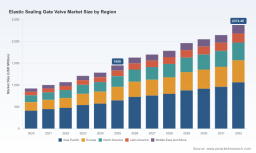
Elastic Sealing Gate Valve Market — Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Elastic Sealing Gate Valve Market report — an actionable industry roadmap designed to inform board-level decisions in 2026 and beyond. Built on a disciplined historical base (2020–2025) and a robust forecast horizon (2026–2032), the study quantifies market momentum, lays out supplier dynamics, and translates regulatory and raw-material pressures into practical plays for manufacturers, utilities, EPCs, and investors. This preview highlights the report’s core strategic value while intentionally withholding detailed segmented tables and proprietary model outputs to encourage direct engagement with the full report.
Elastic Sealing Gate Valve Market
Market at a Glance: Macro Trajectory and What It Means
The elastic sealing (resilient seated) gate valve market has shifted from a mature, infrastructure-oriented niche into a growth corridor driven by municipal upgrades, industrial cooling demand, and water-conservancy investments. On a macro level, our model — with 2025 as the base year — shows global market revenues expanding from USD 920.45 Million in 2020 to USD 1,450.00 Million in 2025. Looking forward through the forecast window (2026–2032), the market is projected to grow at a compound annual growth rate (CAGR) of 7.3%, reaching approximately USD 2,374.46 Million by 2032.
Elastic Sealing Gate Valve Market
Why that trajectory matters for 2026 decisions:
Elastic Sealing Gate Valve Market
- Scale and runway: A multi-year expansion at a mid-single-digit to high-single-digit CAGR signals durable demand — sufficient to justify targeted capacity investments, product line extensions, and selective M&A.
- Timing: 2026 is an inflection year in our scenarios where capital allocation toward resilient seating technologies and elastomer innovation begins to translate into measurable share shifts among agile suppliers.
- Margin pressure and pricing: Growth is accompanied by material cost volatility and heightened procurement sophistication among utilities, squeezing suppliers that fail to demonstrate lifecycle cost benefits.
Key Dynamics Shaping Supply, Demand, and Risk
The report synthesizes several converging dynamics that will dominate boardroom conversations in 2026:
- Standards and compliance: Regulatory frameworks such as AWWA C509/C515 in North America and EN 1074‑2 / BS 5163 in Europe are increasingly prescriptive on ductile iron construction and zero-leakage performance. Compliance is no longer a market-entry checkbox — it is an operational differentiator for bidders on large municipal projects.
- Raw-materials and input cost profile: Elastomers are a critical cost and performance driver. For context, EPDM rubber — a common resilient-seat compound — averaged about USD 3.08/kg in Northeast Asia as of April 2026. Suppliers with integrated purchasing, long-term contracts, or alternative compound roadmaps have a measurable advantage in margin resilience.
- Customer purchasing sophistication: Utilities and large EPCs are shifting to total-cost-of-ownership procurement models, emphasizing lifecycle maintenance, leak prevention, and asset digitalization. That changes contract structures in favor of suppliers offering performance guarantees, retrofit services, and data-enabled condition monitoring.
- Technology and material evolution: Advances in elastomer formulations (enhanced UV/chemical resistance) and seat-retention designs are reducing field-failure rates and enabling longer warranty terms — but they require R&D investment and validation cycles.
- Concentration and competitive posture: Market concentration is moderate; the top-three players capture an estimated ~38.5% of market value, with the top-five accounting for roughly ~52.7%. This environment fosters regional champions, manufacturing specialization, and recurring contracting patterns with large infrastructure players.
What the Full Report Delivers — Practical and Executable
PW Consulting’s full report is built as a decision-support toolkit rather than a descriptive dossier. Key practical deliverables include:
- Proprietary market-sizing model (USD Million, 2020–2032) with scenario toggles for material-cost shocks, regulatory tightening, and municipal CAPEX cycles.
- Segmented demand matrices and supplier revenue breakdowns by region, product type, and application — presented as interactive worksheets (note: these detailed tables are withheld in this preview).
- Supply-chain heatmaps that identify single points of failure — from elastomer compounding to ductile iron casting capacity — and recommended mitigation steps for manufacturers and buyers.
- Competitive scorecards and sourcing playbooks: side-by-side supplier capabilities, warranty frameworks, production footprints, and procurement negotiation levers.
- M&A and partnership shortlist: validated acquisition targets, strategic fit analysis, and integration risk checklists for 2026 deal teams.
- Implementation roadmaps for product commercialization, including R&D staging, certification timelines (AWWA/EN/BS), and pilot deployment plans for utilities.
Competitive Landscape — Players to Watch and Strategic Moves
The market is composed of well-established European specialists and increasingly capable Asian manufacturers competing on scale, certification, and performance track records. Below are high-level profiles of core players covered in the study:
- AVK Valves (Denmark): Known for resilient seated gate valve series designed to meet BS5163 and EN standards, AVK emphasizes certified solutions for water and wastewater systems and tends to lead on specification-driven municipal tenders.
- VAG GmbH (Germany): A technical specialist focusing on advanced sealing systems for municipal and industrial applications; their product development centers on longevity and serviceability in potable water networks.
- EJ Industrial Group (China): Large-scale manufacturer of ductile iron resilient seated gate valves offering both metal-to-metal and elastomer seat options; their scale supports competitive pricing on international projects.
- Union Valve (China): Producer of cast and ductile iron resilient seated valves, including non-rising stem configurations commonly specified in distribution networks; active in cross-border shipments for water infrastructure projects.
- Dervos Valve (China): Offers elastic seat sealed gates with emphasis on zero-leakage performance — a strong choice for projects prioritizing long-term reliability.
- Weidouli Valves (China): Supplies soft-seal and resilient seated gate valves with EPDM/PTFE compound options designed for higher-pressure environments.
- BELGICAST (Spain): European manufacturer supplying higher-performance resilient seated valves for critical infrastructure and large-scale waterworks.
Recent industry signals we track: Weldon Valves’ March 2025 product update highlighted improved elastomers and sustainability features, while Union Valve reported shipments of non-rising stem resilient seated valves for international water projects in late 2024. These events underscore a bifurcation in supplier strategies: technical differentiation versus scale-driven volume plays.
Strategic Implications — Action Areas for 2026
For decision-makers preparing for 2026, our analysis crystallizes into five pragmatic plays:
- For manufacturers: Prioritize elastomer supply security and certification roadmaps. Invest in validated, higher-performance compounds and secure multi-year supply agreements for EPDM or alternative polymers to avoid margin erosion.
- For utilities and EPCs: Shift procurement beyond unit prices to TCO contracts that include field performance metrics and extended warranties. Pilot data-enabled condition monitoring to reduce lifecycle costs and inform capital planning.
- For investors and M&A teams: Target assets that combine regional market access with certification depth or proprietary elastomer know-how. Valuation premiums will accrue to businesses that can demonstrate lower field-failure rates and predictable aftermarket revenue.
- For OEMs considering capacity expansion: Stage investments against demand scenarios in our forecast model. A staged-capex approach — initial debottlenecking followed by modular capacity additions — balances responsiveness with capital discipline.
- For product strategists: Bundle product upgrades with service offerings (retrofit kits, condition assessment) and explore certification partnerships to accelerate acceptance in regulated markets.
How to Use This Preview — Next Steps
This briefing is a strategic “trailer”: it demonstrates the depth of our analysis and provides concrete decision levers, while selective data — notably the full segmented revenue tables by region, product type, and application and the detailed supplier financial profiles — are reserved for the full report. Executives seeking to operationalize these insights should request the PW Consulting Elastic Sealing Gate Valve Market report for the complete model files, supplier scorecards, and a custom briefing tailored to your organization’s role in the ecosystem.
Our team is available for executive briefings, custom model adjustments, and M&A diligence support. Equip your 2026 strategy with the empirical backbone required to convert market growth into captureable, profitable share.
For detailed analysis of this topic, please visit the official page: Elastic Sealing Gate Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com