

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Heavy Industry Hydraulic Systems Market to Surge to USD 56,826.97 Million by 2032

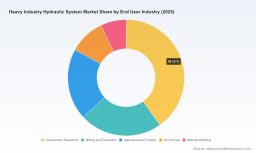
Heavy Industry Hydraulic System Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
As heavy industries accelerate modernization in 2026, hydraulic systems remain a critical backbone of construction, mining, material handling, and heavy manufacturing fleets. PW Consulting's latest market research — anchored on a 2025 base year and projecting through 2032 — finds a market that is recovering and recalibrating for a new technology and regulatory era. The global market is estimated at USD 40,792.05 Million in 2025 and is projected to grow to USD 56,826.97 Million by 2032, representing a compound annual growth rate (CAGR) of 4.85% over the 2026–2032 forecast period. This brief synthesizes the study’s strategic takeaways for leaders planning capital allocation, product roadmaps, and partner ecosystems in 2026, while intentionally preserving detailed segment-level figures to encourage direct access to the full report for operational planning.
Heavy Industry Hydraulic System Market
Why this report matters for 2026 decision-makers
- Timing of investment: With steady mid-single-digit growth ahead, 2026 is a tactical window for firms to accelerate investments in energy-efficient and electrified hydraulic solutions before competitive consolidation intensifies.
- Regulatory alignment: New design standards and energy-efficiency mandates are converging on heavy machinery—organisations that embed compliance and efficiency into procurement and R&D cycles will realize lower lifecycle costs and faster market acceptance.
- Supplier selection and resilience: Raw material volatility (steel pricing) and supply-chain concentration demands that procurement teams adopt dynamic sourcing and inventory hedging strategies; the report provides decision frameworks to do this without disrupting operations.
- Technology transition: Electrification and smart-hydraulics are moving from proof-of-concept to production-readiness. 2026 is the year to pilot integrated electric hydraulic power units (eHPUs), advanced control electronics, and predictive filtration strategies at scale.
Market snapshot (macro view)
Our historical analysis (2020–2025) and forecast (2026–2032) quantify a resilient market trajectory: after cyclical variability in the early 2020s, the sector returned to growth through 2024–2025 and is projected to expand at a 4.85% CAGR over the forecast. The trajectory reflects a mix of sustained demand from heavy equipment OEMs, replacement cycles prompted by emissions and efficiency regulations, and increasing adoption of electrified and digitally connected hydraulic subsystems. Importantly, market concentration is moderate — the top three firms collectively capture roughly one third of market revenues, while the top five account for approximately 44% — a structure that favors both incumbent strength and meaningful opportunities for niche players and system integrators.
Heavy Industry Hydraulic System Market
What the full report delivers — practical, transaction-ready content
PW Consulting’s Heavy Industry Hydraulic System Market report is tailored for boardrooms and operating teams that require prescriptive guidance, not just descriptive analytics. Key operational deliverables include:
Heavy Industry Hydraulic System Market
- Go-to-market playbooks for OEMs and aftermarket suppliers to accelerate adoption of energy-efficient hydraulic architectures.
- Vendor selection matrix that scores suppliers across technical capability, durability, digital readiness, global footprint, and total cost of ownership.
- CapEx prioritisation model for choosing between refurbishment, hybrid retrofits (electrified assist systems), and full-system replacements under multiple commodity-price scenarios.
- Supply-chain stress-test toolkit that models steel-price and logistics shocks, and prescribes inventory, sourcing, and contractual mitigations.
- M&A and partnership decision framework identifying where bolt-on acquisitions, strategic JV’s, or licensing agreements create asymmetrical value given market concentration dynamics.
- Scenario-based roadmaps for technology adoption (e.g., eHPUs, smart valves, integrated controls), including pilot designs, KPI templates, and expected payback windows under four adoption curves.
Competitive landscape: what leaders and challengers are doing
The market remains anchored by established hydraulics and systems integrators that blend component engineering with scale manufacturing and global service networks. PW Consulting’s competitive analysis profiles major players — including Bosch Rexroth, Parker Hannifin, Danfoss Power Solutions, Eaton, HYDAC, Kawasaki Heavy Industries, KYB, Bucher Hydraulics, HAWE, Linde Hydraulics, and machinery OEMs such as Caterpillar — and evaluates them on technology orientation, channel strategies, and strategic intent.
- Bosch Rexroth: Strong in connected, energy-optimized industrial hydraulics and system-level integration for high-duty applications; a reference point for digitalization-led offerings.
- Parker Hannifin: Broad portfolio strength and engineered solutions capability, with an emphasis on sustainability and smart hydraulics for off-highway and industrial fleets.
- Danfoss Power Solutions: Focused on energy-efficient components and the integration path to electrification — a key partner for OEM electrification efforts.
- Eaton and HAWE: Emphasise robustness and high-pressure solutions suited to demanding heavy-industry cycles and long service lives.
- Regional OEM and suppliers (Kawasaki, KYB, HYDAC, Bucher, Linde, and others): Complement global leaders with market-specific offerings and local service density.
- Caterpillar and other OEM-integrators: Continue to internalize hydraulic solutions as strategic differentiators for whole-machine performance and lifecycle service revenues.
Across this competitive set, PW Consulting identifies three winning moves for 2026: (1) cement system-level partnerships to lead electrified hydraulics pilots, (2) accelerate software and controls capabilities to monetize uptime and efficiency, and (3) deploy modular service propositions that shift customers from capex to recurring revenue models.
Technology, standards, and near-term catalysts
Several industry forces are shaping procure-and-build choices in 2026. ISO 18464:2025 introduces a design methodology that prioritizes lowest feasible energy consumption while preserving system functionality. This standard effectively raises the bar for design reviews, procurement specifications, and compliance testing, and is already influencing RFPs from large fleet owners.
On the technology front, electrified hydraulic power units and advanced valve-control architectures demonstrated at recent trade events (notably multiple showings at CONEXPO-CON/AGG 2026) signal that eHPUs and hybrid architectures are moving toward maturity. Early adopters who combine eHPU pilots with predictive filtration and digital twin-based performance validation will capture measurable fuel and emissions reductions — advantages that translate into procurement competitiveness and extended service revenue potential.
Risk factors and mitigation priorities
- Raw material volatility: Steel price swings materially impact component margins. The report provides procurement hedging strategies and low-cost design alternatives to mitigate margin erosion.
- Regulatory execution risk: Differing regional implementations of energy mandates require adaptable product architectures and flexible certification roadmaps. The report maps the compliance sequences that minimize time-to-market risk.
- Integration complexity: Electrified and software-enabled hydraulics introduce multi-disciplinary integration risk (mechatronics, thermal management, and cybersecurity). PW Consulting’s systems-integration checklist reduces pilot failure rates by aligning OEMs, Tier-1 suppliers, and test houses early in development.
How to use this research in 2026 planning cycles
Executives and product leaders can extract immediate value from the report in several ways:
- Strategic budgeting: Convert the report’s market-growth scenarios into prioritized investment lanes — R&D for eHPUs, expanded service networks, or bolt-on manufacturing capacity.
- Procurement re-design: Use the vendor-selection and supply-chain toolkits to renegotiate long-term supplier contracts with energy-efficiency and lifecycle KPIs embedded.
- Pilot-to-scale playbooks: Move beyond lab pilots by applying our stage-gated approach for eHPU and smart-valve validation across representative fleets.
- M&A screening: Apply the M&A scoring model to triage acquisition targets that accelerate electrification or regional service penetration without overpaying for commoditized component lines.
What we intentionally withhold here — and why
Consistent with the “trailer” principle for this market brief, we present the strategic context and actionable frameworks while intentionally omitting granular revenue splits by region, application, and component that are crucial for operational execution. The full report contains those detailed matrices, historical series, and customer-adoption curves required for transaction diligence and factory-level planning. Publishing those segment-level numbers in this release would blunt the report’s commercial utility and deprive clients of the proprietary modelling that underpins PW Consulting’s recommendations.
Recent market signals validating our outlook
- Trade shows and product awards in early 2026 showcased the sector’s momentum: multiple suppliers demonstrated next-generation mobile hydraulic and electrified solutions at CONEXPO-CON/AGG 2026, and an electrified hydraulic power unit (eHPU) earned recognition at World Ag Expo 2026, underscoring commercialization velocity.
- Standards and regulation developments (ISO 18464:2025 and tightening energy-efficiency mandates) are driving upstream design changes and downstream procurement specifications.
- Publicly visible supplier activity — from system integrators to OEMs — points to a pattern of strategic partnerships and pilot programs aimed at validating efficiency and electrification benefits at fleet scale.
Next steps — how PW Consulting supports 2026 implementation
For organisations ready to act in 2026, PW Consulting offers tailored engagements ranging from a rapid strategic diagnostic (6–8 weeks) to full-scale implementation support covering supplier selection, pilot management, and M&A due diligence. Clients receive the complete dataset, segment-level revenue matrices, and executable roadmaps needed to convert the report’s insights into measurable improvements in cost, emissions, and uptime.
Call to action
For executives preparing 2026 capex plans, supply-chain contracts, or product roadmaps, PW Consulting’s Heavy Industry Hydraulic System Market report provides the practical, data-driven guidance required to make defensible choices. Access to the full report (including granular segmentation, model assumptions, and vendor benchmarking) is available through our research portal. Request a briefing to walk through the scenarios most relevant to your portfolio and to obtain the bespoke modules that translate strategy into implementable projects.
For detailed analysis of this topic, please visit the official page: Heavy Industry Hydraulic System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com