

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Large Power Transformers Market Poised for 4.85% CAGR in 2026–2032 Forecast

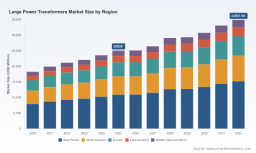
Large Power Transformers Market: Strategic Imperatives for 2026 — PW Consulting Executive Preview
As energy systems accelerate toward decarbonization, digitalization and electrification, the Large Power Transformers (LPT) market is evolving from a component procurement challenge into a strategic bottleneck for utilities, independent power producers, data center operators and national infrastructure programs. PW Consulting’s latest market study — anchored on a 2025 base year and a seven-year forecast horizon (2026–2032) — quantifies that transition: after steady growth through 2020–2025, the global market remains on an upward trajectory through 2032 with a compound annual growth rate (CAGR) of approximately 4.85%. The 2025 market baseline and the 2026–2032 scenarios in this report are designed to inform procurement timelines, capex allocation, M&A strategy and supply‑chain resilience planning for decisions made in 2026.
Large Power Transformers Market
Why 2026 is an inflection point
-
Competing demand vectors — rapid renewables integration, extensive grid modernization, expansion of high-capacity data centers and electrification of industry and transport — are creating sustained, long‑lead demand for LPTs.
Large Power Transformers Market -
Supply-side frictions — raw material tightness, limited domestic GOES production, and manufacturing capacity constraints — are lengthening lead times and elevating price volatility. These dynamics convert what was once routine procurement into strategic risk that can materially shift project economics and timelines.
Large Power Transformers Market -
Policy and industrial initiatives in major markets are incentivizing onshore production and domestic content. Several major OEMs are responding with factory investments that will change competitive dynamics and supplier selection criteria beginning in mid‑to‑late 2026.
What the PW Consulting report delivers (practical, actionable content)
-
Robust market sizing and verified growth scenarios: segmented forecasts covering 2026–2032, stress-tested against commodity price shocks, lead‑time extensions and accelerated demand cases.
-
Buy-side playbooks for 2026 procurement cycles: RFx templates, standardization roadmaps, lead‑time hedging strategies and contracting clauses (including service and spare-parts frameworks) to reduce schedule risk and cost escalation.
-
Supplier capability maps and factory-by-factory risk ratings: manufacturing readiness, technology footprints (EHV, HVDC, GSU specialization), and workforce availability assessments to inform sourcing decisions and potential JV targets.
-
Supply-chain analytics and cost build-ups: GOES/copper/steel exposure models, pass-through scenarios and inventory optimization guidance calibrated to your balance sheet and project timelines.
-
Scenario-based investment and M&A playbook: valuation sensitivities, integration checklists and a prioritization matrix for capacity acquisitions, strategic partnerships and outsourcing options.
-
Operational resilience tools: contingency planning templates, spare‑unit pools, refurbishment strategies and aftermarket service models aimed at maximizing in‑service availability and total lifecycle returns.
Data-driven market dynamics every executive must internalize
-
Pricing pressure: Since 2019 the market has seen major input-driven price increases — independent industry assessments report transformer unit prices rising materially (e.g., sharp increases documented across power transformers and generator step‑up units). These shifts force procurement teams to model inflation into lifecycle costs rather than treating it as a one‑off adjustment.
-
Lead-time escalation: Median delivery lead times have extended into multiple years in many cases. Publicly available studies indicate average LPT lead times well beyond traditional windows, with notable instances exceeding 200 weeks for certain specifications. This is a structural change — treating lead time as a critical path item is now standard practice.
-
Raw-material and component concentration: Domestic production of key inputs remains constrained in several markets. For example, certain specialized electrical steels are produced by a very small number of domestic suppliers in North America — historically, a large share has been imported — creating single‑source exposure that must be actively mitigated.
-
Industry concentration: The LPT sector is moderately concentrated at the top end of the market. Market leaders maintain scale advantages in EHV and large‑MVA units, but mid‑sized and niche suppliers retain pockets of competitive differentiation (custom designs, rapid service response, mobile substations).
Competitive landscape: players, positioning and what recent moves imply
The competitive set continues to reorganize around regional manufacturing footprints, technological differentiation (e.g., HVDC integration, ultra‑low-loss cores, eco‑friendly dielectric designs) and aftermarket service platforms. Key manufacturers that shape near‑term dynamics include established global OEMs and strong regional players with domestic production capabilities.
-
Hitachi Energy — With a global technology portfolio spanning HVDC and high‑capacity units, Hitachi Energy’s recent multi‑hundred‑million dollar investments and announced new U.S. facility signal a strategic bet on higher onshore capacity and shortened delivery cycles for North American projects. For buyers, this shifts some negotiating leverage back toward domestic supply options over a multi‑year horizon.
-
Siemens Energy — Mobilizing new LPT production capacity in the U.S. and scaling hiring for planned facilities reflects a broader industry trend: OEMs aiming to convert long lead times into competitive differentiation by localizing critical production. Timelines for such facilities — and their ramp rates — should be factored into 2026 sourcing strategies.
-
GE Vernova — GE’s LPT capabilities, including through joint ventures, remain focused on utility-scale modernization projects and grid‑scale integrations. For asset owners, GE’s combination of manufacturing scale and project execution experience continues to be attractive where lifecycle service and global engineering resources are prioritized.
-
Hyundai Electric — Emphasizing EHV capabilities with U.S. manufacturing presence, Hyundai brings competitive pricing and proven high‑voltage designs, particularly for markets balancing cost and performance.
-
U.S.-based specialists (Virginia Transformer, Delta Star, Pennsylvania Transformer Technology, SPX Transformer Solutions, Eaton, and others) — These firms offer differentiated propositions around custom design, rapid service, refurbishment and mobile substations. For many North American buyers, integrating a U.S. specialist into a mixed‑supply strategy will be essential to manage outages and mitigate long delivery tails from global vendors.
-
Global diversified players (WEG and others) — Players with cross‑regional manufacturing and service footprints provide flexible sourcing alternatives and are likely to win business where multi‑country project portfolios require a single, coordinated supplier.
Practical 2026 playbook — five priority actions for executives
-
Reclassify LPT procurement as strategic capital: Move decisions onto the executive risk register. Treat lead time, domestic content requirements and price inflation as multi-year strategic constraints, not transactional line items.
-
Lock long‑lead items early and diversify sources: Initiate long‑lead purchase orders, structured contracts with price and delivery collars, and parallel qualification of both global OEMs and domestic specialists.
-
Hedge raw‑material exposure and index appropriately: Insist on transparent cost build-ups and consider shared‑risk constructs or commodity‑linked indexation to limit one‑sided price shocks.
-
Invest in service and life‑extension capability: Augment capital expenditure programs with strategic investments in refurbishment, retrofits and aftermarket partnerships to reduce dependency on new‑build lead times.
-
Evaluate capacity M&A and strategic partnerships: For owners with significant programmatic demand — utilities with large transmission upgrade plans, sovereign funds, or major data center platforms — acquiring or partnering with local manufacturers can be a faster way to secure supply than waiting for new greenfield factories to fully ramp.
How PW Consulting supports 2026 decision cycles
Our LPT market report is intentionally practical. It includes downloadable financial models, supplier scorecards, procurement clauses, scenario analysis outputs and an executive dashboard that translates market signals into prioritized actions tied to client objectives (e.g., reliability, cost of energy, project on‑time delivery). For clients pursuing aggressive 2026 programs, we offer expedited advisory sprints: supplier due diligence, site assessments, negotiation support and bespoke valuation work for capacity investments.
Concluding observation — the strategic payoff
Decisions taken in 2026 will reverberate through utility asset lives and national infrastructure programs for decades. The combination of steady market growth, prolonged lead times, material concentration and active reshoring investments means that organizations that translate market intelligence into proactive procurement, diversification and service strategies will materially outpace peers in cost, schedule and reliability outcomes. PW Consulting’s LPT study is designed as the decision support bridge: authoritative in its methodology and pragmatic in its tools, yet deliberately reserved on proprietary sub‑segment tables to preserve the full-value intelligence contained in the complete report.
For executives preparing capital programs, procurement rounds or strategic investments in 2026, PW Consulting’s LPT insights provide the situational awareness and tactical instruments to move from risk to advantage. Access to the full analytical models, supplier ranking matrices and step‑by‑step playbooks is available in the comprehensive report and through our advisory engagements.
For detailed analysis of this topic, please visit the official page: Large Power Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com