

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Fender Flare Trim Market Set for 5.45% CAGR Through 2032

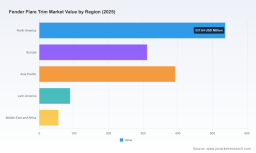
Fender Flare Trim Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases an executive preview of its forthcoming Fender Flare Trim Market report (base year 2025; historical analysis 2020–2025; forecast 2026–2032). The market for fender flare trims has evolved from roughly USD 1.03 billion in 2020 to approximately USD 1.39 billion in 2025 and is projected to expand to just over USD 2.01 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.45% over the forecast period. For automotive suppliers, OEMs, private equity investors and aftermarket distributors planning 2026 budgets and strategic initiatives, the report crystallizes which moves will most likely preserve margin, accelerate share and de-risk supply chains amid rising material and regulatory pressures.
Fender Flare Trim Market
Why this report matters for 2026 decision-making
-
Actionable foresight: Our modelling translates macro demand drivers into addressable-serviceable market scenarios that map directly to portfolio decisions — from material selection and adhesive systems to channel prioritisation (OEM accessories vs aftermarket fitment).
Fender Flare Trim Market -
Timing and prioritisation: With the market set on a multi-year growth trajectory, 2026 is a pivot year for capital allocation. The preview identifies high-conviction plays versus opportunistic experiments so executives can sequence investments and avoid costly late pivots.
Fender Flare Trim Market -
Risk-adjusted roadmaps: The report contains supply-chain stress-testing and contingency playbooks keyed to raw-material volatility and regulatory shocks that are already reshaping procurement strategies for fender-related elastomers and plastics.
Market dynamics and material economics
The fender flare trim market is influenced by three converging dynamics: vehicle parc growth and personalization trends, shifting OEM accessory strategies, and raw-material cost cycles. Demand is being supported by aftermarket customization, increasing SUV and truck ownership in key markets, and OEMs’ willingness to monetize accessory bundles. At the same time, parent-material economics — especially for EPDM and other synthetic rubbers — have a direct and outsized impact on product cost, cross-supplier margin compression and inventory policy.
Notably, EPDM rubber remains a dominant material choice for edge trims because of its ozone resistance and proven durability in automotive environments; it is backed by global manufacturing footprints that provide continuity of supply for major tier suppliers. Industry-wide projections for synthetic rubber (an adjacent indicator) — moving from a multi‑billion-dollar base in 2025 toward materially higher valuations by 2032 — underscore the likely upward pressure on input costs and the imperative to incorporate material-indexed pricing clauses and forward-coverage contracts into supplier agreements.
Compliance and safety standards are another continuous constraint. Automotive-grade rubber trims are commonly required to meet flammability and performance standards (for example, flammability compliance under standards akin to FMVSS 302), and any supplier or OEM that shortcuts this dimension risks costly recalls and reputational damage. Our regulatory checklist and audit protocols in the full report are designed to make compliance a profit-preserving exercise rather than a cost center.
Competitive landscape: who’s shaping the market
The Fender Flare Trim market exhibits moderate concentration. Our market-concentration metrics indicate that the top three suppliers account for a meaningful share of revenue, and the top five consolidate more than half the market — a dynamic that creates both defensive moats for incumbents and windows of opportunity for nimble challengers.
-
Trim‑Lok, Inc. — A market leader noted for EPDM rubber trims and peel-and-stick systems using automotive-grade tapes (including 3M). Recent commercial activity highlights a renewed product catalog and expanded design guidance, alongside targeted product launches that broaden its sealing and trim portfolio for RV and automotive OEM channels. Trim‑Lok’s strength is in specification assurance and globalized documentation for OEM procurement teams.
-
Trimco — Focused on flexible plastic trims that rely on high-performance acrylic foam tapes. Trimco’s value proposition centers on ozone resistance and geometry-conforming profiles, making it a go-to for aftermarket installers seeking consistency across curved fender interfaces.
-
Johnson Bros. Roll Forming Co. — A specialist custom roll-former serving tailored OEM and LCV/HCV applications. Their lower-volume, higher-customization model is attractive to OEMs requiring application-specific cross-sections and fast iterations.
-
Bushwacker & Air Design — Both play in the accessory and OEM-channel space, offering OE-style and low-profile flares. Their presence underscores an important market axis: the migration of accessory sales into official OEM channels for higher-margin, packaged solutions.
-
Steel Rubber & Putco — Represent divergent value propositions: the former emphasizes EPDM rubber edge-trim durability and simple peel-and-stick installation; the latter delivers premium stainless-steel aesthetic solutions for higher-end buyers prioritizing finish and longevity.
Recent product and catalog activity — including Trim‑Lok’s 2025 catalog refresh and subsequent cut-to-length product introductions — indicates incumbent suppliers are doubling down on design support and configurator utilities to shorten OEM approval cycles and reduce aftermarket fitment failures. These investments create higher switching costs for OEMs and increase the commercial value of supplier tooling and validation data.
What’s in the full PW Consulting report (practical highlights)
-
Market sizing & scenario modelling: detailed base‑case and downside/upside scenarios for 2026–2032 (segmented by type, application and region — full splits available in the paid report).
-
Pricing and margin benchmarking: bill-of-materials (BOM) sensitivities, adhesive system costs, and target margin bands for OEM-supplied vs. aftermarket SKUs.
-
Supply-chain resilience playbook: supplier mapping, lead-time analytics, material-sourcing matrices and hedging strategies for EPDM and alternative polymers.
-
Competitive profiles & capabilities matrix: deep dives on 20+ suppliers, innovation scorings, channel footprint assessments and partnership-readiness indicators.
-
Go-to-market frameworks: OEM spec-approval playbooks, distributor partnership models, kit-based aftermarket packaging, and e-commerce readiness checklists.
-
M&A & partnership thesis: target screening for bolt-on acquisitions (e.g., niche roll formers, adhesive formulators, design-tool providers) and earn-out structures tuned to ramp risk.
-
Regulatory & sustainability roadmap: compliance testing sequences, flame-retardant strategies, and material-recycling pathways that meet evolving OEM sustainability scorecards.
Strategic recommendations for 2026
-
Prioritise adhesive systems and installation economics: Peel-and-stick solutions are rapidly becoming the de‑facto expectation for speed-to-fit in both aftermarket and OEM accessory lanes. Supplier partners with validated 3M-grade or equivalent adhesive solutions consistently close faster with tier‑1 procurement teams.
-
Hedge raw-material exposure through mix and contract design: Incorporate a two-pronged approach — diversify polymers (EPDM alternatives where fit-for-purpose) and adopt indexed long-term contracts with collar mechanisms to stabilize input-cost pass-throughs.
-
Invest in configurator and validation assets: Tooling a digital configurator and producing OEM-ready validation packs reduces time-to-contract and increases switching costs for buyers. Small capex here yields outsized commercial returns.
-
Segment offerings by route-to-market economics: Create clear product families for OE accessories, premium stainless trim, and high-volume aftermarket kits. Each has distinct margin, warranty and service obligations — treat them as separate P&L streams.
-
Prepare M&A pipeline for bolt-ons that add adhesive/formulation capability or niche roll-forming to secure differentiated IP and shorten delivery times.
How to use this preview
This preview is intended as a strategic compass for 2026 planning. It outlines the market architecture, competitive dynamics and the levers that will drive return on invested capital. For procurement directors, the report provides negotiation playbooks and supplier scorecards. For product and R&D leaders it offers material pathways and validation sequences. For corporate development teams it lays out acquisition screening criteria and valuation sensitivities tied to catalogue breadth and channel depth.
Next steps
PW Consulting’s full Fender Flare Trim Market report contains the exhaustive data tables, regional and application split analytics, and executable templates needed to convert insight into action. The preview intentionally omits detailed segment-level figures to preserve the commercial value of the primary research; subscribers and licensed report purchasers will receive the granular breakdowns, downloadable models and supplier contact maps that enable immediate deployment of the recommended strategies.
To obtain the full report, detailed datasets, and a complementary executive briefing, visit the PW Consulting intelligence portal or contact your PW Consulting account representative. Our analysts are available for bespoke workshops to translate report findings into a tailored 2026 execution plan.
For detailed analysis of this topic, please visit the official page: Fender Flare Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com