

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Suppository Base Market to Climb from USD 650 Million in 2025 to USD 945.54 Million by 2032 at a 5.5% CAGR

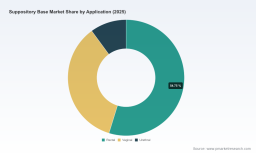
Suppository Base Market — 2026 Strategic Briefing
PW Consulting’s latest Suppository Base Market report is designed as an operationally focused intelligence product for executives making strategic sourcing, R&D, and M&A decisions in 2026. The global market for suppository bases has entered a steady, mid-single-digit growth phase: after expanding from roughly USD 498 million in 2020 to USD 650 million in our 2025 base year, our demand model shows a continuation of that momentum through the 2026–2032 forecast window — translating to a 5.5% compound annual growth rate and a projected market approaching USD 946 million by 2032. This briefing highlights the report’s strategic value, the competitive dynamics shaping supplier choice, and the practical implications for corporate decision-makers. (For full regional, type, and application breakdowns, the complete dataset and downloadable models are hosted with the full report.)
Suppository Base Market
Why this matters for 2026 decision cycles
-
Procurement: Suppository bases remain a specialty excipient category where supplier GMP status, product traceability, and grade consistency materially affect formulation stability and regulatory approvals. With a clear growth trajectory, 2026 is the inflection point for many organizations to move from tactical spot-buying to strategic supplier partnerships and long-term contracts.
Suppository Base Market -
R&D & Formulation Strategy: Choice of base (fatty/oleaginous hard fats, water-soluble PEG blends, or advanced synthetic systems) affects API release, mucosal tolerance, and patient acceptability. The report synthesizes lab-to-commercial transition risks so R&D teams can prioritize platform investments that accelerate time-to-market.
Suppository Base Market -
M&A & Corporate Development: The industry exhibits moderate concentration among established specialty suppliers — our concentration metrics indicate that the top three players account for approximately one-third of market revenue, and the top five approach just over 40% — a profile that favors roll-up plays and targeted vertical integration for mid-sized pharmaceutical and specialty chemical firms.
What the PW Consulting report delivers (practical, transaction‑grade content)
-
Granular market model (2020–2032): revenue history, base-case and alternative scenarios, and sensitivity analysis to raw material shocks and regulatory events — delivered in an editable spreadsheet to support valuation and procurement simulations.
-
Supplier scorecards: quality (GMP/cGMP history), capacity, geographic footprint, and business continuity risk matrices covering primary manufacturers and compounding distributors.
-
Formulation playbook: decision matrix for base selection by therapeutic objective, stability challenges, and patient administration route, including trade-offs between oleaginous hard fats and PEG-based systems.
-
Regulatory & compliance matrix: mapping Ph. Eur., USP, and common national requirements; inspection histories and practical guidance for dossier preparation and excipient change control.
-
Commercial go-to-market templates: sample long-form supply agreements, key performance indicators for CMO partnerships, RFP templates, and pricing frameworks that reflect raw material pass-throughs and quality premiums.
-
M&A diligence kit: target screening criteria, expected multiples range by business model (manufacturer vs. compounding distributor), and an integration checklist focused on quality systems and regulatory harmonization.
Market dynamics and operational risks
Three dynamics are driving near-term commercial decisions: (1) steady demand growth across core therapeutic segments, (2) raw material and sustainability pressures associated with vegetable-sourced hard fats, and (3) regulatory expectations around excipient provenance and GMP compliance. Hard fat bases commonly derive from saturated fatty acids sourced from coconut and palm kernel oils; this creates exposure to agricultural supply cycles, traceability requirements, and ESG scrutiny. Meanwhile, standards bodies list an array of commonly used bases (cocoa-butter substitutes, hydrogenated vegetable oils, PEG mixtures), which means formulation teams must balance clinical performance with supply security.
Regulatory alignment is non-negotiable. Some leading hard-fat manufacturers operate under EU GMP and maintain histories of US FDA cGMP inspections, and many bases are referenced in pharmacopeial compendia. For manufacturers and branded generics alike, the ability to demonstrate pharmacopeial compliance and documented supply chains will determine market access in the next regulatory sweep.
Competitive landscape — who matters and why
Our competitive analysis focuses on specialty excipient manufacturers and distribution/compounding players who control formulation access to hospital and pharmacy channels. Key firms profiled in the report include:
-
IOI Oleo GmbH (Hamburg, Germany) — A global name in hard‑fat (WITEPSOL®) bases with multiple registered grades and GMP-certified production. Their strength is in scale, regulatory pedigree, and a long track record supplying rectal and vaginal bases optimized for industrial manufacturing. Recent catalogue updates underscore continued investment in grade development and technical support for formulators.
-
Medisca (Montreal, Canada) — A major supplier to compounding pharmacies with a broad portfolio that includes vegetable‑based and PEG systems. Their commercial model is distribution-led, emphasizing availability to compounding networks; their recent promotion of natural base grades signals a push to capture pharmacist and outpatient demand.
-
PCCA (Houston, Texas, USA) — Positioned around proprietary bases for compounding and practitioner networks, PCCA combines product breadth with service support aimed at customized preparations. Their proposition targets the clinical compounding space where rapid formulation support is valued.
-
SpecializedRx (USA) — Focused on compounding markets with a portfolio that includes established hard fats and blended bases; their niche is rapid supply to independent pharmacies and small hospital systems.
-
Gattefossé (France) — Adds formulation science to the supply equation, offering hard fat bases tailored for controlled dispersion, stability, and mucosal tolerance — appealing to pharma customers seeking technical co-development.
-
Croda Pharma (UK) — A broader excipient house whose capabilities in excipient innovation and regulatory support make them an attractive partner for branded product teams seeking differentiated functional excipients.
Recent vendor moves — for example IOI’s WITEPSOL® brochure refresh and Medisca’s active promotion of natural and Witepsol‑equivalent grades — indicate two concurrent strategies in the market: (1) incumbent manufacturers focusing on technical differentiation and regulatory validation, and (2) distributors/compounding suppliers emphasizing availability and service to downstream pharmacy networks.
Strategic implications and recommended actions for 2026
-
Embed excipient strategy into product development roadmaps. Formulation strategy should be a board-level input: early decisions on base families materially affect stability, packaging, and expiration dating. Run design-of-experiments (DOE) to de-risk transitions between base types before committing to commercial batches.
-
Diversify upstream exposure where material. For manufacturers reliant on vegetable‑derived fats, implement a multi-supplier policy and consider contracted volumes or hedging to mitigate agricultural volatility. Include sustainability and traceability clauses in supplier contracts to anticipate procurement disruptions driven by ESG scrutiny.
-
Prioritize GMP and pharmacopeial alignment in supplier selection. Regulatory inspections and pharmacopeial references remain decisive in hospital and export markets. Select suppliers with transparent inspection histories and documented change-control procedures.
-
Leverage compounding channels tactically. If market entry speed is a priority, partnering with compounding-focused distributors and networks can accelerate access to B2B and outpatient demand while a longer-term manufacturing strategy is developed.
-
Evaluate M&A to achieve scale or technical capability. Given the market’s moderate concentration, acquisitive moves can secure capacity, broaden grade portfolios, or add formulation expertise — especially compelling for players seeking integrated supply chains or enhanced technical services.
PW Consulting’s unique analytical edge
Our report combines market-sizing rigor with transactional insights: the model is backed by bottom-up production and consumption estimates, validated against manufacturer disclosures and compounding distribution activity. The supplier scorecards and risk matrices are built from primary interviews, inspection histories, and product disclosures, while the commercial toolset provides immediate operational utility for procurement, quality, and corporate development teams.
We intentionally limit the level of segmentation detail in this public briefing to preserve the “trailer” effect: the full report contains the regional, type, and application splits (historical and forecast), price curves by base grade, and scenario-run workbooks that clients use directly in board-level decision-making and deal diligence.
Next steps — how to use this intelligence in 2026
-
Download the full dataset and editable models to run your own scenarios on procurement contracts and acquisition targets.
-
Use our supplier scorecards in RFP shortlists and pre-acquisition due diligence to quantify regulatory and supply continuity risk.
-
Engage our consulting team for accelerated diligence or to co-develop formulation testing plans aligned to your product pipeline milestones.
PW Consulting’s Suppository Base Market report is built for the practical needs of 2026 planners: it converts a complex, technically-driven supply market into action-oriented strategy, procurement playbooks, and transaction-ready diligence. Access to the full report and underlying models is available via our client portal — contact your PW representative to obtain the full dataset, supplier annexes, and the editable forecast workbook.
For detailed analysis of this topic, please visit the official page: Suppository Base Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com