

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 6.5% CAGR for High‑Purity Tungsten Market Through 2032

High Purity Tungsten Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting today publishes a forward-looking market study on High Purity Tungsten that translates raw market dynamics into executable strategy for corporate leaders preparing for 2026. Built on a six‑year historical base (2020–2025) and a seven‑year forecast horizon (2026–2032), the report synthesizes supply, demand, pricing and regulatory inflection points into a single actionable playbook. Our objective is simple: give executives the clarity they need to make high‑stakes choices this year—capacity investments, supply‑chain design, M&A and commercial negotiation—while preserving proprietary granularity for subscribers.
High Purity Tungsten Market
Why 2026 is a Decision Year
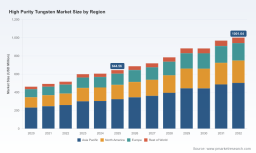
High purity tungsten is at the intersection of geopolitics, upstream raw‑material volatility and technology‑driven demand. PW Consulting’s topline market model shows the global industry expanding from the mid‑hundreds of millions (USD, revenue basis) in 2020 to roughly USD 645 million in 2025, before proceeding to just over USD 1.0 billion by 2032—implying a compound annual growth rate of approximately 6.5% through the forecast period. That steady, above‑trend growth masks episodic shocks (pricing spikes, export controls, tariff actions) that materially affect commercial outcomes in 12–18 month windows. Our report isolates those shocks and translates them into practical decision options for 2026.
High Purity Tungsten Market
What the Report Delivers (Operationally Focused)
- Supply‑chain diagnostics: A layered map of feedstock flows (APT and oxides), reduction and downstream finishing, highlighting bottlenecks and points of leverage for buyers and producers alike.
- Scenario modelling: Three plausible market paths (baseline, constrained‑supply, demand‑surge) with trigger points and contingency playbooks that quantify margin and working capital sensitivity.
- Price and inventory playbooks: Tactical hedging approaches and inventory ladders calibrated to current APT and oxide volatility, including break‑even analyses for forward buying versus just‑in‑time procurement.
- Project and capacity prioritization: A framework for evaluating greenfield and brownfield expansions—including cash‑flow modeling, payback bands and priority gating for 2026 CAPEX.
- Competitive and M&A playbook: Screening criteria for targets and partners, valuation heuristics for tungsten assets, and integration checklists tailored to high‑purity production.
- Regulatory and geopolitical watchlist: Country‑level policy scenarios, tariff and export control matrices, and recommended advocacy strategies for producers and industrial users.
- Supplier scorecards and technical benchmarks: Comparative assessments of commercial producers across technical purity, vertical integration, geographic resilience and customer service metrics.
Market Dynamics—Key Themes Every Executive Must Track
- Supply tightness and input cost pressure. Raw feedstock volatility has re‑emerged as a central value driver. Market indicators show significant price appreciation in key intermediates across 2025–early 2026, and Rotterdam and domestic benchmarks both reflected material upward movements during the period. For procurement teams, this shifts the calculus on forward purchase commitments and justifies new tender structures.
- Trade policy as a supply management lever. Recent trade actions—including higher tariffs and export controls enacted by major consuming and producing countries—are no longer hypothetical. These instruments have already begun to reshape arbitrage flows and increase the value of near‑sourced capacity for sensitive end markets.
- Geographic rebalancing of primary supply. New mine starts and advanced exploration projects in multiple jurisdictions are changing long‑term mine supply expectations, but lead times and permitting timelines mean near‑term relief is limited. Policymakers’ industrial strategies (including strategic funding) are shortening development cycles for certain projects, a dynamic that buyers and investors must anticipate.
- Consolidation and concentration. The high purity tungsten market exhibits moderate concentration: top tier manufacturers capture a meaningful share of global revenue, and an expanded cohort of mid‑tier specialists serve niche purity, form and supply‑security needs. This structure creates windows for strategic partnerships while also reinforcing pricing power for well‑integrated incumbents.
Competitive Landscape — Who Matters and Why
Our competitive mapping profiles global manufacturers with differentiated strategic positions: fully integrated producers with upstream reduction capability; specialist powder makers focused on ultra‑high‑purity grades; and multinational refractory‑metals groups that combine materials depth with global distribution channels. Key players analyzed in the report include long‑standing manufactures in North America, Europe and East Asia, as well as major conglomerates and regional champions. Each profile includes operational footprints, technology strengths, and a calibrated view on partner or acquisition fit for different buyer archetypes.
High Purity Tungsten Market
- Profiles of major integrated manufacturers: Our assessment details how integration from APT/oxide reduction to finished mill products creates margin resiliency and supply security, and identifies which asset archetypes are most attractive for mid‑market consolidators.
- Independent specialists and niche suppliers: We examine the technical differentiation that enables suppliers to capture premium pricing—purity control, particle engineering, and form factor expertise (targets, sputtering materials, wires and rods).
- Concentration metrics: The market exhibits mid‑range concentration among the largest vendors—enough to affect negotiation dynamics but not so concentrated as to prevent new entrants with the right technical or geographic play.
Note: The report contains company‑level scorecards and anonymized supplier benchmarking that reveal negotiating levers and supplier risk profiles—intentionally withheld here to preserve the premium value of the full dataset.
Regulatory & Geopolitical Drivers to Watch in 2026
- Export controls and tariffs. Recent policy shifts have already disrupted traditional routing and increased landed costs for some buyers. The interplay between export licensing and trade remedy tools is now a core input to sourcing strategies.
- Strategic industrial funding. Several jurisdictions are deploying funding mechanisms to accelerate domestic tungsten project development; these interventions shorten development lead times for a subset of projects and change the timing of future supply additions.
- Environmental permitting and community interface. Local permitting outcomes remain a gating risk for greenfield projects; developers with robust stakeholder strategies materially de‑risk schedules and value.
Recent Market Signals (What Our Watchlist Flagged)
- Project advancement and resource activity in multiple jurisdictions signaled stronger developer confidence and a re‑rating of medium‑term mine output.
- Notable policy actions on trade and export licensing have already compressed arbitrage and pushed buyers to formalize resilient sourcing strategies.
- Raw material benchmarks recorded sharp moves in 2025–early 2026, reinforcing the premium for secure offtake and integrated conversion capacity.
Our research team maintains a living timeline of these events and their modeled impact on mid‑term pricing and availability—an asset included with the full report subscription.
Actionable Recommendations for 2026
- For producers: prioritize staged capacity expansion with offtake‑backed financing. Focus first on modular units that reduce technical execution risk and allow rapid scale‑up should demand accelerate.
- For industrial buyers: develop a layered sourcing strategy that blends strategic long‑term contracts, secured offtake with creditworthy upstream partners, and a calibrated inventory cushion tied to demand‑sensitivity thresholds.
- For investors and private equity: screen targets for both technical differentiation (high‑purity process IP) and vertical integration potential; value accretion comes fastest where integration reduces feedstock exposure or creates proprietary customer solutions.
- For governments and policymakers: design permitting timelines and funding mechanisms that shorten but do not preempt rigorous environmental and community engagement—successful projects will be those that secure social license as well as capital.
How This Report Helps You Make Better Choices in 2026
PW Consulting’s High Purity Tungsten report converts complex, often noisy signals into discrete strategic moves. It does so by combining a transparent quantitative model (historical calibration 2020–2025; forecast 2026–2032) with qualitative intelligence—company diagnostics, policy mapping and scenario playbooks. The product is not a collection of static numbers: it is an executable plan for decisions that materially affect margin, supply continuity and strategic optionality in 2026.
To preserve the commercial integrity of our analysis and encourage executive engagement, this release intentionally omits granular regional and application split tables and company‑level proprietary metrics. These data are included in the full report and the interactive dashboard, which provide drill‑downs to support negotiation, M&A diligence and procurement optimization.
Next Steps & Access
Executives preparing 2026 budgets, procurement cycles or capital allocation plans should consider the report a decision‑support system rather than background reading. Subscribers gain access to the full dataset, downloadable scenario models, supplier scorecards and a confidential advisory session with PW Consulting’s metals & materials team to translate findings into an implementation timeline.
For more information on the report contents, licensing options and subscription access to the interactive model, please visit our website or contact PW Consulting’s industry practice. Our team can provide bespoke briefings tailored to executive, commercial and technical audiences.
For detailed analysis of this topic, please visit the official page: High Purity Tungsten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com