

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Emergency Rescue Drone Market to More Than Double from USD 312.5 Million in 2025 to USD 710.12 Million by 2032, Fueled by a 12.45% CAGR

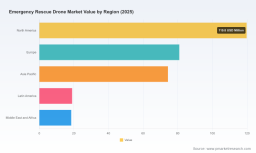
Emergency Rescue Drone Market: Strategic Playbook for 2026 — PW Consulting Industry Brief
Executive snapshot
The emergency rescue drone market is no longer a niche adjunct to traditional first-responder capabilities — it is a core operational capability reshaping how agencies, NGOs, and private emergency services prepare for and react to crises. Our latest PW Consulting market study — anchored on a base year of 2025 with a historical window covering 2020–2025 and a forward-looking forecast through 2032 — synthesizes commercial adoption, technology maturation, regulatory inflection points, and procurement realities into an actionable intelligence package for 2026 decision-makers.
Emergency Rescue Drone Market
Key macro context: measured in USD (Million), the market expanded from USD 142.35 Million in 2020 to USD 312.50 Million in 2025. Under current assumptions, PW Consulting forecasts growth to USD 710.12 Million by 2032, reflecting a compounded annual growth rate (CAGR) of 12.45% across the 2026–2032 forecast window. Market structure remains moderately concentrated, with the three largest players accounting for a material share of industry revenues and the top five capturing a clear majority — dynamics that materially affect competitive strategy, supplier selection, and M&A calculus.
Emergency Rescue Drone Market
Why 2026 is a strategic inflection point
-
Regulatory alignment is unlocking scale. Government and public-safety adoption has moved from experimental to programmatic. Recent policy developments — including streamlined processes for Drone as First Responder (DFR) deployments and heightened supply-chain security requirements — materially reduce barriers to fielding prepositioned and rapidly deployable systems at municipal and state levels.
Emergency Rescue Drone Market -
Technology is transitioning from capability parity to differentiated mission outcomes. Advances in autonomy, sensor fusion (especially thermal and low-light imaging), secure communications, and VTOL endurance architectures are enabling drones to conduct real search-and-rescue and disaster-relief missions independently and as integrated elements of multi-capability response teams.
-
Procurement and supply-chain resilience are now procurement criteria. As defense and public-safety customers formalize acquisition frameworks, compliance requirements (notably national security-oriented sourcing standards) and the availability of certified components — for example, NDAA-compliant batteries and parts — have become gating factors in award decisions.
Strategic implications for 2026 decisions
-
Operators (public safety, NGOs, utilities): Prioritize readiness investments that create operational uptime, not only unit counts. This means investments in prepositioned stations, trained DFR workflows, and sustainment contracts rather than one-off platform purchases. Scenario-based procurement that ties capability to response times and operational metrics will outperform simple platform buy cycles.
-
OEMs and system integrators: Adopt a modular product and services model. Buyers will favor vendors who can demonstrate certified supply chains, predictable lifecycle support, and systems that integrate into existing incident command and communications architectures. Long-lead material sourcing (batteries, secure comms) and compliance certification are critical competitively differentiating investments.
-
Investors and corporate development teams: Seek opportunities where technology leadership combines with defensible distribution to public-sector accounts. Given market concentration among a limited set of incumbents, bolt-on acquisitions that add NDAA-compliant manufacturing, recurring service revenue, or geographic access to public-safety contracts can accelerate scale with lower execution risk.
-
Policy and procurement offices: Recast RFPs to reward mission outcomes and sustainment rather than purely unit cost. Incorporate compliance checklists and interoperability tests into award criteria and consider performance-based contracts that align vendor incentives to operational availability.
Competitive landscape — players to watch
The market presents a juxtaposition of specialized public-safety innovators and established tactical UAS suppliers. PW Consulting’s competitive analysis focuses on capabilities and strategic posture rather than headline market shares, identifying where each firm is positioned to capture the next wave of adoption.
-
BRINC Drones (Seattle, WA) : A focused public-safety playbook built around indoor and tactical response. BRINC’s product suite targets Drone-as-First-Responder programs and constrained-environment missions where two-way communications, glass-penetration tools, and ruggedized designs matter. Notably, BRINC announced a production and capability expansion in March 2026 — a doubled manufacturing footprint and the next-generation Guardian platform — signaling an intent to scale 24/7 operational deployments.
-
Skydio (San Mateo, CA) : Autonomy as a competitive moat. Skydio’s systems emphasize AI-driven navigation and obstacle avoidance in complex environments, with payload capabilities (including thermal sensors) tailored to search-and-rescue and public-safety operators. The firm’s strength lies in ease-of-use and reduced training overhead, important attributes for agencies with constrained aircrew resources.
-
AeroVironment (Arlington, VA) : Tactical and defense-fluent systems with a track record in rapid-deployment ISR. AeroVironment’s portfolio is compelling where interoperability with defense and multi-domain command structures is required, and where proven endurance and VTOL/Fixed-Wing hybrid solutions support extended missions.
-
Draganfly (USA/Canada) : North American manufacturing emphasis and specialization in mission payloads. Draganfly’s strategic positioning benefits buyers prioritizing regional production and tailored sensor configurations for complex emergency scenarios.
-
ZenaDrone (USA) : Focused long-range search-and-rescue capability with real-time telemetry. The company’s emphasis on range and persistent data links is attractive for jurisdictions that need to cover extensive geographies with fewer launch points.
-
Ascent Aerosystems (USA) : Compact, robust coaxial designs optimized for space-constrained and tactical operations. Ascent’s engineering focus supports integrations into vehicles and rapid-deployment kits for first responders.
Market structure and competitive dynamics
The emergency rescue drone market is neither a pure fragmentation nor a duopoly: concentration metrics show a meaningful presence of leading players, yet sufficient space for specialized innovators and systems integrators. This environment favors partnerships — OEMs aligning with certified manufacturing partners, sensor firms integrating with autonomy stacks, and service providers bundling training and sustainment into subscription offerings. For buyers, the implication is clear: you can achieve both capability and vendor diversification, but procurement frameworks must account for interoperability and lifecycle assurance.
Operational playbooks and what our report delivers
PW Consulting’s report is designed as an operational playbook for leaders making procurement, investment, and programmatic decisions in 2026. It combines strategic analysis with step-by-step tools to accelerate deployment while managing program risk. Highlights include:
-
Scenario-driven capability matrices linking mission profiles (urban SAR, disaster relief, medical delivery) to recommended architectures (multi-rotor, fixed-wing, hybrid), endurance profiles, and sensor suites.
-
Procurement checklists and RFP language templates that operationalize compliance (including national security-related sourcing), lifecycle support, and interoperability tests.
-
Supplier due-diligence frameworks — assessing manufacturing footprint, certification status, component traceability (with emphasis on battery and communications supply chains), and sustainment economics.
-
Operational readiness scorecards for DFR programs: measures for stationing, crew training, mission rehearsal cadence, and maintenance turnaround times required to deliver mandated response SLAs.
-
Investment and M&A playbooks for strategic buyers: valuation sensibilities for recurring service revenue, integration risk assessments, and scenarios for rapid scale via acquisitions.
Risk vectors and mitigation priorities
-
Supply-chain and compliance risk: NDAA and similar sourcing standards are non-negotiable for many government programs. Buyers should require component-level certification and conduct supplier audits early in the procurement process.
-
Operational integration risk: Drones are seldom a standalone capability. They must be interoperable with incident command systems, comms networks, and medical dispatch workflows. Prioritize vendors with proven integrations and open APIs.
-
Technology obsolescence: Rapid advances in autonomy and sensors can render platforms suboptimal within procurement cycles. Structure contracts to allow payload upgrades and modular avionics refreshes without full platform replacement.
-
Regulatory change: The same regulatory developments that unlock deployment can also shift compliance requirements. Maintain a regulatory-monitoring function and build contractual clauses that address changing certification regimes.
Actionable recommendations for 2026
-
Reframe procurement around operational outcome metrics (response time, area coverage per launch, mission success rates) and tie payments to availability and sustainment KPIs.
-
Invest in a hybrid sourcing strategy: partner with proven incumbents for baseline platforms while selectively piloting fast-moving innovators for specialized mission sets.
-
Prioritize NDAA-compliant supply chain visibility and battery certification as gating criteria for any program intended for public-safety or defense alignment.
-
Establish a centralized integration lab or framework to validate vendor claims across sensors, autonomy stacks, and RF comms before awarding long-term contracts.
Next step — why the full report matters
This briefing articulates the strategic contours decision-makers need in 2026. The full PW Consulting Emergency Rescue Drone Market report contains the actionable datasets, vendor scorecards, procurement templates, and scenario-modeled forecasts required to move from strategy to execution. While this summary highlights market scale and structural forces, detailed segmentation, vendor-level financials, regional program analyses, and downloadable procurement templates are available exclusively in the complete report.
For organizations planning capital allocations, R&D roadmaps, or program launches in 2026, the PW Consulting study is intended to compress months of bespoke advisory work into a single, repeatable playbook — enabling faster, lower-risk decisions where lives and public trust depend on performance.
For detailed analysis of this topic, please visit the official page: Emergency Rescue Drone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com