

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Automotive DSP Amplifier Market to Grow at a Robust 8.75% CAGR Through 2032

Automotive DSP Amplifier Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
As OEMs, Tier‑1s, semiconductor suppliers and aftermarket specialists position themselves for the next phase of vehicle electrification and premium cabin experiences, PW Consulting’s latest Automotive DSP Amplifier Market study provides the prescriptive intelligence required to convert uncertainty into decisive action in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes market sizing, technology evolution, supply‑chain stress tests and competitive playbooks — enabling stakeholders to prioritize investments, partnerships and product roadmaps with confidence.
Automotive Dsp Amplifier Market
Macro trajectory: growth that demands strategic response
The DSP amplifier sector has transitioned from a niche premium segment into a mainstream enabler of immersive in‑vehicle audio and active cockpit experiences. Our topline model shows the global market expanding from approximately USD 1.85 billion in 2020 to roughly USD 2.98 billion in 2025, and continuing to grow through the forecast horizon to exceed USD 5.3 billion by 2032, at a compound annual growth rate (CAGR) of 8.75% across 2026–2032. This scale and momentum create both opportunity and structural challenges: margins will be sustained for differentiated players, while commoditization pressures will intensify for purely hardware-centric offerings.
Automotive Dsp Amplifier Market
Why this report matters for 2026 decisions
- Decision timing: Suppliers deciding on capacity expansion, semiconductor sourcing contracts, or strategic hires need a 12–18 month lead time. Our scenario‑based demand curves and supply‑constraint overlays convert market growth into concrete capacity and procurement timelines.
- Technology roadmap alignment: Whether to prioritize high‑efficiency Class‑D power stages, integrated DSP platforms, or multi‑channel modularity is a make‑or‑break choice. We map technology adoption vectors to vehicle segments and two implementation horizons (near‑term: 2026–2028; medium term: 2029–2032).
- Commercial strategy: The premiumization of in‑car audio creates recurring software and integration revenue opportunities. The report quantifies value pools for hardware, software licensing, calibration services and aftermarket upgrades — so commercial teams can design margin-accretive offerings rather than competing on price alone.
- M&A and partnerships: With a moderately concentrated supply base (CR3 ~42.5%, CR5 ~58.3%), the market favors bolt‑on acquisitions and strategic alliances. Our vendor heatmaps identify which segments are ripe for consolidation and which capabilities should be acquired versus developed in‑house.
What the report contains — actionable, executable intelligence
PW Consulting’s study was developed to be operator‑useful, not just academic. Highlights of the analytical toolkit provided include:
Automotive Dsp Amplifier Market
- Top‑down and bottom‑up market sizing with sensitivity analysis across three adoption scenarios (base, accelerated EV premium, and constrained supply).
- Multi‑dimensional forecast (2026–2032) that connects market value to vehicle production, trim penetration rates and per‑vehicle average selling price (ASP) trajectories.
- Vendor benchmarking: product portfolio mapping, go‑to‑market positioning, and technology capability scoring for leading players across OEM and aftermarket channels.
- Technology deep dives: Class‑D amplifier efficiency curves, digital input architectures, software stack requirements for real‑time DSP, and integration best practices for multi‑channel and active noise applications.
- Supply‑chain risk matrix: semiconductor node dependencies, raw material exposure (including rare earth risks), and mitigation pathways such as multi‑sourcing and buffer inventory strategies.
- Regulatory and qualification playbook: practical steps to meet AEC‑Q100 and functional safety expectations, plus recommended test and validation regimes for automotive‑grade audio components.
- Commercial playbook: pricing strategies for OEM bids, aftermarket warranty models, feature‑based monetization (e.g., sound signature packs, OTA DSP updates), and channel mix optimization.
- M&A screening framework: prioritized capability targets, valuation multipliers observed in the sector, and integration checklists for technology and go‑to‑market assimilation.
Competition and capability map: who matters and why
The competitive landscape is populated by a mix of specialized audio houses, established automotive electronics brands and semiconductor incumbents. Notable participants include Audiotec Fischer (Germany), Audison and Mosconi (Italy), Alpine Electronics (Japan), AudioControl and ARC Audio (USA), and semiconductor leaders such as STMicroelectronics, Texas Instruments, Analog Devices and NXP. Each brings a distinct strategic posture:
- Audiotec Fischer: recognized for high‑end DSP amplification and award‑winning products and software tools that cater to audiophile aftermarket customers and boutique OEM integrations.
- Audison and Mosconi: focused product roadmaps for compact, high‑performance DSP amplifiers that bridge aftermarket and OEM supplier demands.
- Alpine Electronics: leveraging Hi‑Res and Status‑level DSP platforms to support OEM differentiated audio packages and integrated cockpit initiatives.
- AudioControl and ARC Audio: strong in signal processing and pro‑audio feature sets attractive to premium OEM and aftermarket installers.
- Semiconductor suppliers (ST, TI, Analog Devices, NXP): driving foundational performance envelopes through integrated Class‑D drivers, DSP cores, and domain‑specific accelerators — increasingly blurring lines between software and silicon in audio subsystems.
Recent industry events underscore the pace and direction of innovation: Audiotec Fischer’s HELIX V EIGHT DSP ULTIMATE and associated PC software received independent recognition in 2025, signaling product and toolchain maturity in premium segments. Semiconductor vendors continue to launch automotive‑grade, high‑frequency Class‑D parts and advanced audio processors, reflecting OEM demand for higher efficiency, lower EMI and greater digital integration.
Market dynamics to watch in 2026
- Electrification as an accelerant: EVs change the acoustic baseline and enable new features (active sound design, bass compensation). Suppliers must align DSP roadmaps to exploit EV‑specific value pools.
- Supply constraints and rare earth exposure: Semiconductor volatility and material shortages persist through 2026; procurement strategies will determine who can reliably meet OEM serial timelines.
- Regulatory and qualification gatekeepers: Compliance with AEC‑Q100 and automotive functional safety is a non‑negotiable cost of entry. Early investments in qualification shorten time‑to‑production and reduce warranty risk.
- Software monetization and OTA lifecycles: The product is increasingly defined by software calibration and user experience. Companies that can deliver seamless OTA updates, tuning services and curated sound profiles command higher lifetime value.
- Consolidation pressure: With a CR3 of about 42.5% and CR5 near 58.3%, strategic consolidation is likely where mid‑tier manufacturers seek scale to compete on OEM contracts and global distribution.
Strategic imperatives for 2026 — an executive checklist
- Harden supply chains now: secure multi‑sourced contracts for key power ICs and DSP cores; incorporate rare‑earth substitution plans where feasible.
- Prioritize modular platforms: design architectures that allow feature‑additive upgrades (software‑defined DSP modules, channel expansion kits) to capture aftermarket upsell.
- Form semiconductor partnerships: co‑develop reference platforms with Tier‑1 or chip vendors to reduce integration risk and accelerate validation cycles.
- Embed software monetization: create licensing and OTA pipelines for sound profiles, adaptive tuning and premium audio subscriptions.
- Invest in qualification and test automation: reduce time‑to‑production for AEC‑Q100 and functional safety sign‑offs through in‑house or partner test rigs.
- Screen M&A targets tactically: focus on capabilities that close gaps (calibration software, cloud services, installation networks) rather than bolt‑on product SKUs alone.
What we don’t disclose here — and why you’ll want the full report
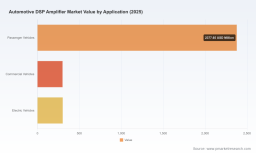
To preserve the trailer nature of this briefing, we are intentionally omitting granular regional, application and model‑level revenue splits that are essential for deal underwriting, production planning and pricing strategy. The full PW Consulting report includes these high‑resolution tables, vendor‑level revenue breakdowns, ASP trajectories by vehicle class, and downloadable data models that support bespoke scenario simulations — resources that many executives will find indispensable when finalizing 2026 budgets and capital allocations.
Concluding perspective
By 2026, the Automotive DSP Amplifier market will no longer be just an audio add‑on; it will be a differentiated pillar of the in‑vehicle experience stack, tightly integrated with infotainment, active noise management and even brand identity. Companies that treat this segment as a cross‑functional strategic initiative — combining resilient supply chains, modular hardware, monetizable software and disciplined compliance — will capture the most value as the market doubles in scale through the forecast horizon. PW Consulting’s report translates that strategic horizon into tactical steps, keyed to the timing and risk profile that matter to executives making 2026 commitments.
For access to the complete dataset, vendor scorecards, and executable playbooks referenced in this summary, visit the PW Consulting Automotive Research page or contact our client services team to schedule a briefing and data license. The detailed intelligence will accelerate decision certainty in a market where timing and integration expertise determine winners.
For detailed analysis of this topic, please visit the official page: Automotive Dsp Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com