

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Global Liquid Termiticides Market Hits $2.85B in 2025, Projected 5.12% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence in Global Pest Management: Decoding the Worldwide Liquid Termiticides Market Outlook 2026–2032
Urbanization, climate-induced pest migration, and tightening regulatory frameworks are reshaping the structural pest control landscape. At the center of this transformation lies the liquid termiticide segment, a critical tier within the broader crop protection and professional pest management ecosystem. As property development expands across emerging regions and older infrastructures demand rigorous post-construction interventions, stakeholders require more than aggregate industry rhetoric. They need a disciplined, data-grounded view of market mechanics, competitive positioning, and the evolving cost structure that defines profitability. PW Consulting’s latest research initiative, the Worldwide Liquid Termiticides Market study, delivers precisely that calibrated intelligence for executive teams, procurement leaders, R&D strategists, and investment analysts preparing for the 2026 decision cycle.
This market intelligence briefing is designed to function as a strategic compass. It translates multi-year historical performance, forward-looking growth trajectories, and structural market forces into actionable frameworks. Rather than offering superficial category summaries, the study dissects the operational realities that determine market share, margin resilience, and regulatory compliance readiness. The following sections outline the analytical architecture of the report, highlight the core dynamics shaping the sector, and illustrate how decision-makers can convert these insights into defensible market positioning over the next seven years.
Market Architecture and Growth Trajectory
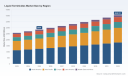
The worldwide liquid termiticides market has demonstrated consistent expansion over the historical analysis window, driven by sustained demand for soil-applied structural protection and professional pest management services. The market reached an estimated valuation of 2850.0 million in the 2025 base year, reflecting a steady upward arc from the 2023 baseline of 2579.14 million and the 2024 reading of 2711.19 million. This trajectory underscores a segment that has matured beyond cyclical dormancy and now operates with predictable resilience, even as input costs and regulatory pressures fluctuate.
Looking ahead, the forecast horizon extending through 2032 positions the market for continued expansion, with the projected figure reaching 4042.31 million by the end of the period. This escalation is anchored by a forecast compound annual growth rate of 5.12 percent across the 2026–2032 interval. For strategic planners, this growth rate is not merely a statistical marker; it signals a market in which incremental share gains, formulation optimization, and channel efficiency will increasingly separate high-performing operators from those reliant on legacy pricing models. The transition from 2995.92 million in 2026 to 3149.31 million in 2027, and onward through successive annual milestones, reflects a compounding environment where product differentiation, application methodology, and regulatory agility become decisive competitive levers.
Within this landscape, the study systematically maps how market value is distributed across operational and geographical dimensions, providing a structural reference for capacity planning and regional go-to-market design. The segmentation architecture reveals that non-repellent liquid termiticides command the larger share of market activity at 1824.0 million, while repellent liquid termiticides account for 1026.0 million. This bifurcation is highly instructive for product portfolio strategy. Non-repellent chemistries tend to benefit from transfer-effect dynamics and soil penetration characteristics that appeal to integrated pest management protocols, whereas repellent formulations maintain relevance in specific barrier-use scenarios where immediate avoidance behavior is operationally desirable. Understanding the strategic implications of these two technology streams—and how their relative positioning shifts in response to active ingredient availability, resistance management concerns, and applicator preference—is central to formulation roadmapping and commercial messaging.
The application dimension further sharpens the market lens. Post-construction treatment remains the dominant deployment context at 1653.0 million, reflecting the ongoing need to retrofit existing structures against subterranean termite pressure. Pre-construction treatment contributes 1197.0 million, highlighting the embedded role of soil preparation and barrier establishment during new building cycles. These two application pathways are not interchangeable from an execution standpoint. Post-construction work involves access constraints, treatment precision, and customer communication challenges, while pre-construction interventions are tightly coupled with construction timelines, contractor coordination, and formulation application standards. The report provides decision-makers with the operational context needed to align product offerings, sales force specialization, and service-delivery models with the distinct economics of each use case.
Geographically, the market exhibits a pronounced concentration of activity in North America at 1254.0 million, followed by Asia Pacific at 855.0 million, Europe at 342.0 million, Latin America at 285.0 million, and the Middle East and Africa at 114.0 million. This distribution is not a simple function of property stock; it integrates regulatory maturity, professional pest control penetration, housing and infrastructure investment cycles, and the localization of distribution networks. For multinational manufacturers and regional formulators alike, these geographic gradients inform where to prioritize formulation registration, where to invest in technical sales coverage, and where to anticipate shifts in competitive intensity as local players expand their registered portfolios.
Competitive Positioning and the Shape of the Industry Landscape
The liquid termiticide sector is characterized by a moderately consolidated competitive structure. The study quantifies this concentration through a CR3 of 42.5 percent and a CR5 of 58.8 percent, indicating that a small group of leading enterprises holds a substantial portion of market value, while a broader field of specialty manufacturers, regional suppliers, and generic formulation houses competes for the remainder. In practical terms, this means that scale, registration portfolios, technical service capability, and supply continuity are decisive elements of competitive advantage. It also means that market entry and share expansion strategies must be carefully calibrated, particularly where incumbents have deep-rooted relationships with professional applicators and established placement in procurement specifications.
BASF SE, headquartered in Ludwigshafen, Germany, is positioned around a well-recognized termiticide portfolio that includes Termidor SC, Termidor HE High-Efficiency, and Termidor HP II liquid termiticides for both pre- and post-construction soil treatments against subterranean termites. Its product architecture illustrates the strategic importance of tiered offerings that address varying application efficiencies, soil conditions, and customer throughput requirements. Syngenta AG, based in Basel, Switzerland, brings a reduced-risk, chlorantraniliprole-based approach through its Altriset termiticide, a liquid soil-applied product designed for indoor and outdoor structural protection with low mammalian toxicity. This positioning reflects a broader industry pivot toward active ingredients and formulations that align with evolving stewardship expectations and customer sensitivity to handler safety.
FMC Corporation, with headquarters in Philadelphia, USA, supplies bifenthrin and other pyrethroid-based liquid termiticides for professional pest management, anchoring its relevance in well-established active ingredient families that are widely understood by applicators and integrated into standard treatment protocols. Bayer AG, located in Leverkusen, Germany, offers imidacloprid-based liquid termiticides such as Premise for soil barrier treatments in residential and commercial structures, reinforcing the importance of chemistry breadth and multi-market applicability. Nufarm Limited, from Melbourne, Australia, produces and supplies a range of insecticide formulations including liquid termiticides for professional pest control markets, representing the strategic role of agile manufacturing and international distribution in serving varied regional demand profiles. Sumitomo Chemical Co., Ltd., in Tokyo, Japan, develops and markets synthetic pyrethroid and other active ingredient-based liquid termiticides for global structural pest control, highlighting the relevance of Asian innovation capacity and export-oriented formulation strategy.
The competitive field also includes specialized players with focused operational models. Control Solutions Inc., based in Pasadena, USA, manufactures and distributes liquid termiticide products including generic formulations of fipronil and bifenthrin for professional use, demonstrating how cost-structured alternatives can gain traction where applicators prioritize economic efficiency and compatible performance characteristics. Ensystex Inc., located in Fayetteville, USA, provides liquid termiticide options alongside bait systems for comprehensive termite management, underscoring the growing importance of integrated solution design rather than single-product competition. Across these profiles, a consistent strategic theme emerges: competitive advantage is increasingly defined not only by chemistry, but by the ability to bundle technical support, regulatory readiness, application guidance, and supply reliability into a coherent value proposition for professional channels.
Regulatory Flux, Input Economics, and Structural Market Dynamics
Market performance in the liquid termiticide segment does not evolve in a vacuum. It is shaped by regulatory developments, active ingredient economics, and supply chain conditions that collectively influence cost structures, product viability, and time-to-market for new formulations. One of the most consequential recent regulatory updates occurred in November 2025, when the U.S. Environmental Protection Agency established a time-limited tolerance for residues of chlorantraniliprole in or on rice grain at 15 ppm, expiring December 31, 2028. While this action is framed around agricultural residue tolerances, its strategic relevance for the termiticide market lies in the broader signal it sends regarding chlorantraniliprole’s regulatory treatment and the continuing scrutiny applied to active ingredients with dual-use implications. For product managers and regulatory affairs teams, such developments require continuous monitoring because tolerance frameworks, use patterns, and species-protection measures can affect formulation strategy, labeling flexibility, and customer confidence.
In April 2025, the U.S. EPA released the final Insecticide Strategy intended to reduce exposure of federally listed endangered species from conventional agricultural insecticides, including mitigation measures applicable to termiticide use patterns. This policy direction reinforces a regulatory environment in which environmental stewardship, non-target organism protection, and application-method accountability are increasingly embedded in operational decision-making. At the same time, the broader active ingredient landscape is being shaped by restrictions on certain chemistries. Fipronil and imidacloprid use in agriculture is severely restricted in the US and EU due to acute toxicity to non-target arthropods, particularly pollinators. These limitations do not merely affect crop protection markets; they reverberate into structural pest control by influencing active ingredient availability, registration momentum, substitution dynamics, and perceived chemical risk among applicators and end customers.
On the input side, the sector has absorbed meaningful cost pressure. The price of fipronil and bifenthrin, common active ingredients in liquid termiticides, increased by 16 percent between 2022 and 2024. This movement matters because active ingredient cost is a primary driver of formulation economics, margin design, and pricing strategy. In a market where product performance, regulatory status, and applicator acceptance all hinge on chemistry choice, ingredient cost inflation can compress profitability unless manufacturers and distributors actively manage sourcing strategy, product mix, and value-based pricing. Compounding these pressures, supply chain disruptions for specialty chemicals due to geopolitical tensions and transportation bottlenecks have affected production capacities of liquid termiticide manufacturers. The practical consequence is that supply continuity has become a strategic asset. Companies that can maintain stable production pathways, diversify sourcing where feasible, and provide reliable fulfillment timelines are better positioned to retain professional channel trust, especially during periods when competitor shortages or lead-time variability create procurement uncertainty.
What the Study Delivers: Analytical Depth, Practical Utility, and Decision-Ready Structure
The Worldwide Liquid Termiticides Market research is engineered to translate complex industry signals into clear operational guidance. It does so through a layered analytical design that links macro market behavior to the tactical decisions made by commercial, supply chain, and regulatory teams. The study maps historical performance and projected growth in a way that helps leadership test assumptions about demand durability and investment timing. It situates product categories and application contexts within the broader ecosystem so that portfolio decisions reflect real-world deployment conditions rather than abstract category definitions. It also contextualizes competitive activity by examining how established players and specialized manufacturers structure their offerings, where they derive differentiation, and how concentration dynamics influence pricing and channel access.
Beyond top-line market sizing, the research emphasizes the operational drivers that determine commercial outcomes. This includes the interplay between non-repellent and repellent technology streams, the economics of pre-construction versus post-construction deployment, and the geographic nuances that shape registration priorities, distribution strategies, and technical service intensity. The report also integrates market dynamics that are directly relevant to cost planning and risk management, including regulatory trajectory, active ingredient price behavior, and the operational implications of specialty chemical supply constraints. By linking these forces to competitive strategy, the study helps organizations anticipate where margin pressure may intensify, where product substitution could accelerate, and where market access may become more demanding due to compliance or stewardship requirements.
Liquid Copper Fungicide Market
This is not a static snapshot. The study is structured to support scenario thinking, allowing decision-makers to evaluate how changes in construction activity, professional pest control adoption, regulatory interpretation, and input cost trends could affect strategic priorities across the forecast period. It provides a coherent framework for assessing whether to expand into new formulations, deepen presence in priority geographies, refine channel partnerships, or strengthen supply-side resilience. In doing so, it converts raw market intelligence into a usable strategic asset.
Strategic Use Cases for the 2026 Decision Cycle
For R&D and formulation teams, the report offers a structured basis for prioritizing active ingredient and delivery-system development. By clarifying how product categories perform across applications and regions, it helps identify where technical differentiation is most likely to yield commercial returns and where competing on cost or convenience may be more appropriate. For procurement and supply chain leaders, the study frames the market in terms of concentration, input cost volatility, and supply continuity risk, supporting more informed sourcing strategies and inventory planning in an environment where specialty chemical availability can shift quickly.
For commercial and sales leadership, the segmentation and geographic context provides a foundation for territory planning, channel specialization, and value proposition design. Understanding the distinct operational characteristics of post-construction and pre-construction deployments, as well as the relative scale of non-repellent and repellent formulations, enables more precise alignment between product messaging, applicator training, and customer engagement models. For corporate strategy and investment teams, the competitive concentration data, company profiles, and regulatory developments create a practical basis for evaluating market entry opportunities, partnership potential, and long-term positioning in a segment where incumbency advantages and registration assets carry substantial weight.
Conclusion
The worldwide liquid termiticides market is entering a phase in which durable growth must be paired with disciplined strategic execution. The 2025 baseline of 2850.0 million and the forward path toward 4042.31 million by 2032, supported by a CAGR of 5.12 percent, defines a market with meaningful scale and continued expansion potential. Yet the real strategic challenge lies in navigating the forces that shape competitive advantage within that growth: technology preference across non-repellent and repellent categories, the economics of post-construction and pre-construction applications, geographic demand distribution, regulatory evolution, input cost inflation, and the supply chain vulnerabilities that affect production continuity. PW Consulting’s Worldwide Liquid Termiticides Market research is built to address these complexities with analytical rigor and practical relevance. It equips organizations with the evidence base needed to make informed decisions in 2026 and beyond, while preserving the deeper segmentation detail, competitive intelligence, and scenario-level analysis that executive teams require to act with confidence.
Worldwide Liquid Termiticides Market
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Termiticides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tasigna Market to Hit 1,550M in 2025, -11.45% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Contraction: Strategic Insights into the Global Tasigna Market Through 2032
The global oncology pharmaceutical landscape is undergoing a profound transformation, driven by patent expirations, the influx of biosimilars and generics, and shifting reimbursement models. Within this complex ecosystem, the market for Tasigna (nilotinib capsules) represents a critical case study in brand lifecycle management and competitive displacement. As we move into 2026, enterprise decision-makers in the pharmaceutical sector, investment firms, and healthcare strategists require granular intelligence to navigate the diminishing revenue trajectories and evolving competitive dynamics of this therapeutic area.
This introduction serves as a precursor to the comprehensive Worldwide Tasigna Market research report recently published by PW Consulting. Our analysis is designed to equip stakeholders with the actionable intelligence necessary to formulate robust strategies amidst a contracting market environment. Below, we outline the strategic value of this study, the key market dynamics shaping the landscape, and the depth of competitive intelligence contained within the full document.
The Macro Trajectory: A Landscape in Decline
Understanding the overarching revenue trends is the first step in strategic planning. Our research provides a detailed historical reconstruction and forward-looking forecast spanning from 2020 through 2032. The data reveals a consistent downward trajectory in global market revenue, reflecting the significant impact of patent expirations and the subsequent entry of generic competitors.
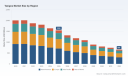
In the base year of 2025, the global market revenue for Tasigna is recorded at approximately $1,550.0 million USD. Looking back, the market stood at roughly $2,008.15 million in 2020, indicating a measurable erosion of branded market share over the past half-decade. This contraction is projected to accelerate through the forecast period. Our models estimate that by 2026, market revenue will decline to approximately $1,319.11 million, further decreasing to $1,186.37 million in 2027 and reaching $1,094.43 million by 2028.
The long-term outlook suggests a continued compression of the addressable market for the branded product. By 2032, the revenue is forecasted to settle around $660.0 million. This represents a significant reduction from peak historical levels. The Compounded Annual Growth Rate (CAGR) for the forecast period from 2026 to 2032 is calculated at -11.45 percent. This negative growth rate underscores the urgency for stakeholders to understand the underlying drivers of this decline, rather than relying on historical performance metrics that no longer apply.
It is crucial for strategists to recognize that these aggregate figures mask complex regional and therapeutic shifts. While the top-line numbers indicate contraction, the distribution of remaining value across geographies and indications is shifting in nuanced ways that require detailed examination. Our full report dissects these nuances without exposing the specific pricing sensitivities that could impact proprietary strategy, but the headline trend is clear: the era of high-margin branded dominance for this specific molecule is transitioning rapidly toward a volume-driven generic landscape.
Competitive Dynamics and the Generic Inflection Point
The primary driver of the market contraction observed in our data is the alteration of the competitive landscape following key regulatory milestones. The expiration of the compound patent US 7,169,791 on March 17, 2023, marked a definitive turning point. This event, documented in the FDA Orange Book, triggered the approval and launch of generic alternatives, fundamentally altering the supply-demand equilibrium.
Novartis AG, headquartered in Basel, Switzerland, has historically been the manufacturer and worldwide marketer of branded Tasigna. They maintain approval for nilotinib capsules for both adult and pediatric patients with newly diagnosed or imatinib-resistant Philadelphia chromosome-positive chronic myeloid leukemia (Ph+ CML). However, their financial disclosures reflect the market reality. In their full-year 2023 financial report, released in February 2024, Novartis noted that Tasigna net sales stood at $1,182 million, representing a 19 percent decline in USD terms compared to the prior year, directly attributed to generic competition.
Conversely, generic manufacturers have moved swiftly to capture market share. Teva Pharmaceuticals, for instance, received FDA approval and launched the first generic version of Tasigna (nilotinib capsules, 150 mg and 200 mg) in the US in December 2022. This launch preceded the patent expiration, signaling aggressive lifecycle management strategies from generic entrants. The entry of Teva and potentially other competitors creates a price-competitive environment that squeezes branded margins while expanding access through lower-cost options.
Market concentration remains high despite the influx of generics. Our analysis indicates that the top three companies control approximately 92.4 percent of the market revenue, while the top five firms hold around 96.15 percent. This high concentration suggests that while fragmentation is theoretically possible, the market is still heavily influenced by major players managing the transition from branded to generic portfolios. For stakeholders, understanding the specific market share holdings of these key entities is vital for assessing partnership opportunities, competitive threats, and supply chain vulnerabilities.
Therapeutic Indications and Dosage Segmentation
Beyond the macro revenue trends, the utility of Tasigna is segmented by specific clinical indications and dosage strengths. These segments behave differently under pricing pressure and generic substitution. The market is primarily driven by two key patient populations: those with Newly Diagnosed Ph+ CML-CP and those who are Resistant or Intolerant to prior therapies (Ph+ CML-CP).
Worldwide Tasigna Market
Our research quantifies the revenue contribution of each indication segment, revealing which patient populations remain most reliant on the branded formulation versus those where generic substitution is most prevalent. Similarly, the market is divided by dosage strength, specifically 200mg Capsules and 150mg Capsules. The uptake of generics may vary between these strengths due to manufacturing complexities, prescribing habits, and insurance formulary placements.
For pharmaceutical strategists, knowing which indication or dosage strength retains higher brand loyalty is essential for lifecycle extension strategies. For generic entrants, identifying the segments with the highest volume potential dictates production planning. Our full report provides a granular breakdown of these segments, analyzing the volume-to-value ratios without disclosing the sensitive pricing architectures that underpin current market transactions.
Regional Nuances and Reimbursement Landscapes
Geography plays a pivotal role in the longevity of branded pharmaceuticals. The global market is distributed across North America, Europe, Asia Pacific, and the Rest of World. Each region presents unique regulatory hurdles, reimbursement pathways, and generic penetration rates.
In North America, the impact of the US patent expiration and the Medicare Part D reimbursement structure significantly influences market dynamics. Post-patent expiry, Tasigna is reimbursed under Medicare Part D with average sales price-based payments, which alters the economic incentive structure for providers and patients. This reimbursement shift often accelerates the adoption of generic versions if they are listed favorably on formularies.
Europe and Asia Pacific present different challenges and opportunities. Regulatory approval timelines for generics, local manufacturing capabilities, and national health service procurement policies vary widely. The Rest of World segment includes emerging markets where access to cancer therapies is expanding, but pricing pressures remain intense. Our report maps the revenue distribution across these regions, highlighting where the branded product maintains resilience and where generic erosion is most aggressive. However, specific regional revenue figures are reserved for the full download to protect the proprietary modeling techniques used to estimate these values in markets with limited public data transparency.
Risk Factors and Regulatory Considerations
Strategic planning in the oncology space must account for significant risk factors. Tasigna carries FDA black box warnings for QT prolongation, torsades de pointes, and sudden death. These safety profiles impact prescribing behaviors and patient adherence. While these risks are managed through clinical guidelines, they remain a constraint on market expansion and a potential liability consideration for manufacturers.
Furthermore, the regulatory environment is dynamic. Beyond the patent expiry, changes in healthcare policy, drug pricing negotiations, and international trade agreements can alter market access. Our report incorporates a regulatory outlook section that assesses potential upcoming changes that could impact the supply chain or reimbursement status of nilotinib products through 2032.
What the Full Report Delivers
This overview highlights the broad strokes of the Worldwide Tasigna Market, but the strategic depth required for high-stakes decision-making lies in the details. The complete PW Consulting report goes beyond the macro trends summarized here to provide a toolkit for execution.
Key components included in the full study include:
- Historical Data Reconstruction (2020-2025): A validated dataset allowing users to benchmark their internal performance against market averages and identify discrepancies in forecasting assumptions.
- Forecast Modeling (2026-2032): Scenario-based projections that account for variable generic penetration rates, potential new indications, and regulatory shifts, enabling stress-testing of investment hypotheses.
- Segment-Level Intelligence: Detailed analysis of the Newly Diagnosed and Resistant/Intolerant indications, as well as the 150mg and 200mg dosage strengths, to identify pockets of stability within the declining market.
- Competitive Profiling: In-depth profiles of key companies including Novartis AG and major generic entrants, covering their strategic positioning, pipeline adjacencies, and market share trajectories.
- Regional Deep Dives: Country-specific insights within the broader regional buckets, focusing on reimbursement policies, tender processes, and distribution channel dynamics.
- Strategic Recommendations: Actionable guidance for brand managers seeking to defend share, generic manufacturers planning market entry, and investors evaluating exposure to the CML therapeutic area.
The concentration of market revenue among the top three and top five players suggests that competitive intelligence is not merely about tracking sales figures but understanding the strategic moves of a few dominant entities. Our report elucidates the interplay between these players, offering clarity on who is gaining share and at what cost.
Conclusion: The Imperative for Precision Intelligence
The Worldwide Tasigna Market is at a critical juncture. With a forecasted CAGR of -11.45 percent from 2026 to 2032 and total revenue projected to drop from $1,319.11 million in 2026 to $660.0 million by 2032, the margin for error is slim. Stakeholders cannot rely on static models or outdated assumptions about branded drug longevity.
The transition from a protected branded monopoly to a competitive generic market requires a recalibration of strategy. Whether the goal is to maximize the remaining lifecycle of the branded asset, identify the optimal timing for generic launch, or assess the risk exposure of a portfolio heavily weighted toward CML treatments, precise data is non-negotiable.
Worldwide Imbruvica Market
The insights presented here serve as a validation of the market's direction but represent only the surface layer of the intelligence available. To access the full segmentation data, regional revenue breakdowns, detailed competitor analysis, and proprietary forecast models, stakeholders are encouraged to acquire the complete Worldwide Tasigna Market report. In an environment defined by rapid contraction and strategic complexity, the difference between a reactive posture and a proactive strategy lies in the depth of your intelligence.
PW Consulting remains committed to providing the highest caliber of market research to support your strategic objectives. We invite you to explore the full suite of findings to ensure your organization is equipped to navigate the future of the Tasigna market with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Tasigna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Antibody Fragments Market Hits $12B in 2025, Growing at 9.6% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Global Antibody Fragments Market (2026–2032)
The therapeutic landscape is undergoing a structural shift. As full-length monoclonal antibodies approach maturity in certain indications, antibody fragments—Fab, scFv, and single-domain VHH/nanobody formats—are emerging as precision instruments that address unmet needs in tissue penetration, pharmacokinetics, and manufacturing agility. Our newly released Worldwide Antibody Fragments Market study is designed to convert this structural transition into actionable strategy for executives operating across biopharma, diagnostics, and research supply chains.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
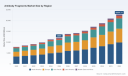
This report offers a disciplined, forward-looking view of a market that reached an estimated USD 12,001.0 million in 2025 and is projected to scale to approximately USD 22,797.7 million by 2032, reflecting a forecast-period CAGR of 9.6%. More than a revenue trajectory, these figures signal a market in which strategic positioning, platform selection, and manufacturing realism will determine which organizations capture durable share. The insights that follow are built to support 2026 decision cycles—from portfolio prioritization and partnership evaluation to capacity planning and regulatory preparedness.
Why Antibody Fragments Are Reaching an Inflection Point
Antibody fragments are not a substitute for full-length antibodies; they are a complementary toolkit. By removing the Fc region, fragments can achieve deeper tissue penetration, reduced immunogenicity in selected contexts, and alternative expression routes that alter the economics of production. At the same time, the absence of a native Fc domain introduces trade-offs that many strategy discussions still underestimate. The strategic question for 2026 is not whether fragments matter, but how to align indication selection, format choice, and process design so that technical advantages translate into commercial value.
Our market analysis situates this question within a market structure that has evolved steadily from USD 7,850.4 million in 2020 to the 2025 baseline noted above, with 2026 projected to reach approximately USD 13,829.3 million. That growth path is not uniform across formats or use cases. It is shaped by therapeutic adoption curves, diagnostic demand, research-sector activity, and regional dynamics that differ in both pace and concentration. The report unpacks these drivers without reducing them to static snapshots, allowing decision-makers to see where momentum is durable and where volatility demands a more adaptive plan.
What the Study Covers: Operational Utility for Strategy Teams
The study is built for teams that need more than a top-line number. It connects market sizing with the operational and competitive realities that determine execution risk. Topics examined include:
- Historical evolution from 2020 through the 2025 base year, with a forecast window extending to 2032 designed to inform medium-term planning rather than short-lived tactical bets.
- Segment-level perspectives on antibody fragment types and application domains, presented to illuminate demand drivers, adoption patterns, and the relative maturity of each pathway.
- Regional market perspectives that clarify where activity is concentrated and how geographic variation influences partnership, supply, and market-entry logic.
- A competitive landscape built around major global companies and specialized producers, anchored in their platform strategies, pipeline directions, and recent commercial or technical developments.
- Manufacturing and regulatory realities that shape cost structures, lead times, and go-to-market feasibility for fragment-based programs.
The intent is practical intelligence. Each section is structured so that R&D leaders can compare technology pathways, commercial leaders can weigh indication and pricing dynamics, and operations leaders can anticipate where process complexity will affect margin and timeline. Crucially, the analysis preserves the granularity needed for internal modeling while presenting a coherent narrative suitable for board-level discussion.
The Cost-and-Complexity Equation That Shapes Fragment Economics
A recurring theme in this study is that fragment economics cannot be inferred from full antibody analogies. Without the Fc domain, conventional Protein A affinity capture is not available, forcing reliance on multi-step purification approaches such as ion exchange and hydrophobic interaction chromatography. Sector analysis indicates that these added process steps can raise manufacturing costs by up to 60% relative to full monoclonal antibody production in comparable contexts. That cost penalty is not universally fatal—especially when fragments are paired with high-value indications or differentiated formats—but it changes the algebra of target product profiles and scale-up decisions.
On the other side of the equation, expression strategy can create meaningful leverage. Microbial systems such as E. coli or Pichia pastoris can enable more cost-effective production of scFv and nanobody formats compared with mammalian systems traditionally used for full antibodies, with reported yields reaching up to 150 mg/L in optimized fed-batch processes. For organizations evaluating capacity, outsourcing, or platform investments, this distinction is central. The report examines where microbial productivity offers a genuine advantage and where downstream complexity re-emerges, helping teams avoid over-optimistic assumptions about cost parity.
Half-Life Engineering, Regulation, and the Commercial Margin Story
Therapeutic fragments often require molecular engineering to address short serum half-life. PEGylation, albumin-binding tags, or Fc fusions can extend exposure and improve dosing convenience, but these modifications are not free. Sector analyses indicate that such half-life extension strategies can double or triple cost of goods sold, a dynamic that becomes especially consequential in price-sensitive indications or competitive reimbursement environments. Decision-makers must therefore view half-life engineering not simply as a scientific choice but as a commercial lever with direct implications for margin, market access, and indication prioritization.
Worldwide Antibody Fragments Market
Regulatory expectations add another layer of realism. Antibody fragments, including Fab, scFv, and VHH/nanobody formats, require rigorous preclinical, clinical, and post-market assessments comparable to other biologics seeking therapeutic approval. The regulatory path is viable and increasingly familiar, but it is not shortcuttable. The study integrates these expectations into its market outlook so that teams can align development timelines, evidence-generation plans, and market-entry assumptions with the realities of biological evaluation and approval pathways.
Competitive Landscape: Platforms, Partnerships, and Differentiated Moves
The competitive picture reflects a blend of large biopharmaceutical organizations and specialized technology providers, each pursuing distinct routes to value. The study profiles a range of leading participants, including F. Hoffmann-La Roche AG, Novartis AG, AbbVie Inc., Amgen Inc., Pfizer Inc., Johnson & Johnson (Janssen), Bristol-Myers Squibb, Sanofi (Ablynx), UCB, Eli Lilly and Company, Sino Biological, Inc., and evitria AG. Rather than presenting a simple corporate roster, the analysis focuses on how each organization's platform activity, therapeutic emphasis, and production specialization informs its strategic posture in fragment-based markets.
Several recent developments illustrate the direction of travel. In August 2025, Sanofi continued to advance and promote its NANOBODY technology platform for next-generation therapeutics, emphasizing improved tissue penetration and manufacturing advantages tied to single-domain formats. In January 2025, Adimab announced that it had entered 17 new partnerships and achieved 51 milestones in 2024, including programs involving VHH single-domain antibody formats—a signal of growing partnership velocity around fragment-compatible discovery and optimization capabilities. In February 2025, a broader industrial review summarized nanobody production, patent activity, clinical trial trends, and industrialization patterns from 2014 onward, reinforcing the idea that fragment platforms are moving from niche differentiation toward scaled commercialization conversations.
Within this landscape, market concentration remains significant. The study notes a combined share held by the top three participants of approximately 42.5% and a top five share of roughly 58.8%. These concentration levels matter because they shape both competitive intensity and opportunity distribution. They indicate where incumbency advantages are strongest, and where adjacent entrants may still create value through specialized manufacturing, novel formats, or targeted indication strategies. The report explores these dynamics in depth so that companies can gauge not just who is present, but how the arena is likely to evolve as platform and partnership activity accelerates.
Where Fragments Are Creating Distinct Value Across Applications
Antibody fragments are being evaluated and deployed across therapeutics, diagnostics, and research and development, but the strategic logic differs in each domain. In therapeutics, fragments can offer advantages in indications where tissue access, molecular size, or engineering flexibility are decisive. In diagnostics, fragments can support binding specificity, format compactness, and manufacturing flexibility for assay design. In research and development, fragments serve as enabling tools for discovery, target validation, and custom production workflows that feed earlier-stage pipeline activity.
The report examines these application pathways with attention to adoption readiness and commercial logic, rather than treating them as interchangeable categories. For example, therapeutic use cases often involve the largest revenue pool and the most demanding regulatory and reimbursement scrutiny, while research and diagnostic activities can provide earlier demand signals, specialized revenue streams, and useful proving grounds for format selection. Understanding the interplay among these domains is essential for organizations that want to sequence investments wisely and avoid over-committing to a single pathway before evidence is sufficient.
Regional Structure and the Distribution of Opportunity
Market opportunity is not uniformly distributed, and regional variation influences everything from partnership strategy to supply-chain design. The study maps regional market perspectives to clarify where current activity is concentrated and how geographic differences shape demand patterns, manufacturing footprints, and market-access considerations. This regional framing is especially important for companies evaluating where to place development resources, how to prioritize collaborations, and which markets might offer faster paths to proof of concept versus larger but more competitive revenue opportunities.
Because regional dynamics interact with format choice, application mix, and manufacturing economics, the analysis avoids simplistic rankings and instead focuses on the strategic implications of geographic structure. That approach allows executives to interpret where regional scale matters, where specialized local capabilities can create advantage, and how global players may adjust their footprints over the forecast period.
How to Use This Intelligence for 2026 Decisions
The 2026 planning cycle will reward organizations that treat antibody fragments as a strategic platform decision rather than a narrow product category. The study is structured to support that mindset in several concrete ways:
- Portfolio strategy: Evaluate where fragment formats align with indication needs, target product profiles, and differentiation goals, while accounting for half-life engineering, manufacturing complexity, and regulatory burden.
- Partnership and sourcing: Compare internal platform bets with external options, including specialized producers and technology partners, by weighing yield potential, purification requirements, and timeline implications.
- Capacity and cost planning: Model production scenarios that reflect the real cost drivers of fragment purification, expression system selection, and half-life modification strategies.
- Market-entry sequencing: Use regional and application-level insight to sequence launches, partnerships, and evidence generation in ways that balance speed, risk, and revenue potential.
- Competitive posture: Situate your organization relative to large biopharmaceutical players and focused entrants, recognizing both concentration dynamics and the partnership activity now reshaping the field.
What Remains Inside the Full Analysis
This overview establishes the framework and the stakes. The complete Worldwide Antibody Fragments Market study goes further by providing the detailed segment, regional, and competitive quantification that underpin execution-level strategy. It contains the specific breakdowns and modeled comparisons that teams need for scenario planning, investment justification, and competitive benchmarking, while preserving the broader narrative required to communicate the logic to stakeholders.
For organizations preparing 2026 decisions, the full report is where the strategic signal becomes operational. The macro trajectory—growth from a 2025 baseline of USD 12,001.0 million toward a 2032 projection of approximately USD 22,797.7 million at a 9.6% CAGR—gives the market its gravity. The segment splits, regional distributions, application dynamics, and competitive concentration data give it shape. The manufacturing, regulatory, and reimbursement realities give it discipline. Together, they form a decision-ready intelligence base for leaders who need to move from awareness to action.
The Worldwide Antibody Fragments Market study is now available through PW Consulting. Readers seeking the detailed segmentation figures, regional quantification, company-level profiles, and modeled forecast pathways are encouraged to access the full report at the source webpage, where the complete dataset and expert commentary can be reviewed in context.
For detailed analysis of this topic, please visit the official page: Worldwide Antibody Fragments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Low-VOC Coating Additives Market to Hit $11,142.59M by 2032 Amid 6.42% CAGR
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Intelligence in the Worldwide Low-VOC Coating Additives Market
Unlocking Growth Trajectories and Compliance Imperatives for 2026 and Beyond
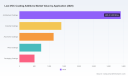
The global coatings industry stands at a critical inflection point. Throughout 2020 to 2025, the worldwide low-VOC coating additives market navigated a complex path of recovery, regulatory tightening, and technological maturation, culminating in a comprehensive market valuation of approximately 7,208.15 million USD in the 2025 base year. This trajectory, while marked by periods of contraction such as the modest dip observed in 2023, reflects the resilience of a sector fundamentally realigned toward sustainability. As we project forward through the 2026 to 2032 forecast period, the market is poised for sustained expansion, driven by an anticipated compound annual growth rate of 6.42 percent. This growth is not merely a function of volume but of value, as formulators increasingly seek high-performance additives that reconcile environmental compliance with optimal coating attributes.
Recent historical data illustrates the volatility and eventual upward trajectory of this sector. Starting from 5,280.40 million USD in 2020, the market climbed to 5,849.06 million USD in 2021, followed by 6,231.28 million USD in 2022. The slight contraction to 6,015.38 million USD in 2023 underscored supply chain and raw material challenges, but the rebound to 6,739.56 million USD in 2024 and 7,208.15 million USD in 2025 signaled robust recovery. Forecasts indicate continued momentum, with valuations expected to reach 7,776.63 million USD in 2026, progressing toward 11,142.59 million USD by 2032. These figures represent more than just revenue; they encode the strategic shifts in material science, regulatory compliance costs, and the premium attached to low-emission technologies.
For executives and R&D leaders making decisions in 2026, the challenge lies in parsing these macro indicators into actionable precision. Surface-level data cannot capture the nuanced interplay between regional regulatory divergence, feedstock innovation, and the shifting balance of power among tier-one suppliers. This is where a dedicated, granular market intelligence study becomes indispensable, translating broad trends into targeted strategic leverage.
The Regulatory and Technological Matrix Driving Demand
Compliance is no longer a defensive posture but a primary driver of product architecture and procurement strategy. The regulatory landscape for low-VOC coating additives is increasingly fragmented and stringent, requiring formulators to navigate overlapping jurisdictional mandates while maintaining performance parity with legacy high-VOC systems. In North America, the U.S. EPA amended National VOC Emission Standards for Aerosol Coatings in January 2025, introducing new reactivity factors and expanding the roster of regulated compounds. Simultaneously, California's SCAQMD Rule 1113 continues to set a de facto national benchmark by imposing VOC limits for most architectural coatings under 50 g/L, compelling manufacturers to rewrite formulation protocols and adopt advanced additive packages that deliver flow, stability, and durability without cross-threshold emissions.
In Europe, the EU Deco-Paint Directive 2004/42/EC establishes harmonized VOC limits for decorative paints and varnishes, serving as a foundational compliance framework that continues to shape additive selection across the continent. Standard test methods such as ASTM D6886, which provides the standard procedure for determination of VOC content in waterborne coatings, further operationalize compliance, ensuring that laboratory formulations translate accurately into regulatory submissions and market-ready products. These regulatory pressures are not uniform, however. They interact with regional production capacities, local raw material availability, and varying customer expectations, creating a mosaic of compliance requirements that demands localized strategic insight rather than blanket formulation approaches.
Beyond regulation, the material science foundation of low-VOC additives is undergoing a structural shift. These additives increasingly rely on bio-based or alternative feedstocks such as vegetable oil-derived polyols and biosurfactants to achieve reduced emissions while preserving critical performance characteristics like surface tension control, rheology management, and foam suppression. This transition introduces new considerations around supply chain resilience, lifecycle sustainability metrics, and cost-to-performance ratios. Companies that can secure reliable, scalable access to these advanced feedstocks while demonstrating measurable sustainability advantages will capture disproportionate value in the coming years.
Coating (Painting) Additives Market
Market Architecture: Segmentation, Concentration, and Strategic Positioning
Beneath the aggregate market valuation lies a highly differentiated landscape of additive categories, application domains, and regional performance patterns, each carrying distinct growth drivers and competitive implications. The segmentation structure reveals how demand is distributed across rheology modifiers, wetting and dispersing agents, defoamers, leveling agents, and other specialty additives, reflecting the specific technical requirements of modern low-VOC and waterborne systems. Each category serves a critical function in formulation architecture: rheology modifiers govern viscosity, sag resistance, and application behavior; wetting and dispersing agents ensure pigment stability and color consistency; defoamers and leveling agents address surface defects and finish quality. The relative demand intensity across these categories is shaped by end-use performance standards, regulatory constraints on specific chemistries, and the pace of adoption for next-generation waterborne, high-solids, and UV-curable platforms.
Similarly, application segmentation highlights where low-VOC additive demand is most concentrated and where incremental growth is emerging. Architectural coatings represent a substantial portion of market activity, driven by stringent consumer-facing environmental labels, green building certifications, and residential and commercial retrofit cycles. Industrial coatings contribute significant volume through manufacturing, maintenance, and protective applications where durability, chemical resistance, and process efficiency remain paramount. Automotive coatings, wood coatings, and packaging coatings each introduce distinct formulation challenges and regulatory considerations, from appearance and corrosion protection to substrate compatibility and recycled content integration. Understanding the cross-section of additive type, application, and geography is essential for identifying the niches where formulation innovation can translate into premium positioning and margin expansion.
Market concentration metrics further illuminate the competitive dynamics. With the top three players accounting for approximately 31.4 percent of market revenue and the top five reaching 44.8 percent, the industry exhibits moderate concentration rather than monopolistic dominance. This structure creates a dual environment: established multinationals leverage scale, R&D depth, and global technical service networks to anchor customer relationships, while specialized and regional players compete on formulation agility, niche performance claims, and localized regulatory expertise. For buyers and investors alike, this balance of concentration and fragmentation signals where consolidation risks lie, where partnership opportunities emerge, and where supplier diversification can mitigate single-source vulnerability.
Competitive Landscape and Recent Developments Shaping 2026
The roster of key participants in the worldwide low-VOC coating additives market reflects a blend of chemical conglomerates, specialty additive leaders, and sustainability-focused innovators. BASF SE, headquartered in Ludwigshafen, Germany, maintains a broad portfolio of low-VOC coating additives including defoamers, rheology modifiers, wetting agents, and surface modifiers optimized for waterborne and high-solids systems across architectural, industrial, and automotive coatings. Evonik Industries AG, based in Essen, Germany, provides high-performance low-VOC and zero-VOC additives such as TEGO series defoamers, wetting agents, and dispersants, with a clear focus on bio-based and sustainable options for waterborne coatings. Dow Inc., operating from Midland, Michigan, supplies low-VOC coating additives and acrylic emulsions tailored for eco-friendly waterborne formulations in architectural and industrial applications.
Other major contributors include Eastman Chemical Company in Kingsport, Tennessee, which develops specialty low-VOC additives including coalescents and performance enhancers for compliant coating formulations; Allnex in Frankfurt, Germany, specializing in low-VOC additives and resins for high-performance waterborne, powder, and UV-curable coating systems; and AkzoNobel N.V. in Amsterdam, Netherlands, producing low-VOC additives as part of its specialty chemicals offering for sustainable paint and coating formulations. Elementis plc, London, United Kingdom, offers rheology modifiers and other low-VOC additives for architectural and industrial coatings. Huntsman Corporation, The Woodlands, Texas, provides additives supporting low-VOC formulations in polyurethane and other coating technologies. Seqens, Ecully, France, supplies specialty chemicals including low-VOC coating additives for performance coatings. Arkema, Colombes, France, develops water-based and low-VOC additives and resins for coatings, including recent expansions in acrylic emulsions. LANXESS, Cologne, Germany, offers next-generation low-VOC coalescents and additives such as Koalex MFX for waterborne coatings. ALTANA AG, Wesel, Germany, provides specialized coating additives with low-VOC profiles through its BYK and other brands, and Nouryon, Amsterdam, Netherlands, supplies performance additives for low-VOC coating systems.
Recent corporate activity underscores the velocity of innovation and the competitive significance of timing. In April 2026, LANXESS introduced Koalex MFX, a next-generation multifunctional low-VOC coalescent for waterborne coatings, alongside low-carbon pigment technology at the American Coatings Show 2026. In February 2026, hubergroup Chemicals launched ELARA, a new brand for high-performance additives for coatings and printing inks, with global availability from March 2026 and debut at PAINT INDIA 2026. In March 2026, Dow Inc. expanded its acrylic emulsions portfolio with advanced low-VOC formulations to meet demand for eco-friendly paints and coatings. Earlier, in March 2025, Evonik Industries AG launched mass balanced products TEGO Wet 270 eCO and TEGO Foamex 812 eCO for sustainable, reduced-carbon low-VOC coatings with ISCC PLUS certification. These moves are not isolated product announcements; they are strategic signals about feedstock transition, branding differentiation, and the race to embed sustainability credentials into high-performance additive categories. A comprehensive analysis of such developments reveals the underlying priorities of each competitor, the technological pathways they are betting on, and the market segments they are attempting to redefine.
A Preview of the Intelligence Inside the Report
The full Worldwide Low-VOC Coating Additives Market study is structured to convert macroeconomic and competitive signals into decision-grade intelligence. Beyond the headline market size and growth rate, the report delivers a layered examination of segmentation performance across regions, additive types, and applications, with careful attention to the drivers, restraints, and transitional dynamics shaping each segment. Readers will encounter detailed profiles of leading companies, including headquarters locations, product portfolio orientations, strategic positioning, and recent corporate developments that indicate future market intent. This competitor mapping is paired with an assessment of market concentration and the implications for supplier selection, risk management, and partnership strategy.
The study also integrates a thorough regulatory and raw material context, mapping the key policy instruments, test methods, and feedstock trends that dictate formulation feasibility and cost structures. This background is not provided as a static list but as a dynamic framework for evaluating where compliance costs will rise, where bio-based substitution will accelerate, and which technical bottlenecks are most likely to reward early investment. In addition, the report examines market forces such as pricing elasticity, capacity expansion rationales, technology adoption cycles, and regional demand intensities, giving executives the ability to align product roadmaps, procurement strategies, and market entry decisions with realistic performance trajectories.
Crucially, the analysis is designed to support scenario planning. By connecting historical performance, forward forecasts, regulatory evolution, and competitor behavior, the report equips stakeholders to anticipate not just the direction of the market but the specific inflection points that will determine competitive advantage in 2026 and beyond. Whether the objective is to evaluate supplier reliability, identify white-space application opportunities, benchmark formulation strategies against peer behavior, or assess regional growth potential, the study is built to surface the granularity that high-stakes decisions demand.
Strategic Imperatives for 2026 Decision-Making
For organizations operating in or adjacent to the low-VOC coating additives ecosystem, the 2026 decision environment rewards precision, foresight, and disciplined interpretation of complex data. The market's projected growth trajectory, combined with its regulatory intensity and evolving feedstock base, creates both opportunity and exposure. Companies that rely on aggregate statistics alone risk misjudging segment-level momentum, underestimating compliance-driven formulation shifts, or overlooking competitor moves that redefine category expectations. Conversely, those who ground their strategies in deep segmentation insight, competitor profiling, and regulatory mapping can allocate resources more effectively, differentiate on performance and sustainability, and build supplier and customer relationships that withstand market volatility.
The strategic questions facing leaders in 2026 are pointed: How should additive portfolios be rebalanced to reflect shifting demand across architectural, industrial, automotive, wood, and packaging coatings? Which regional markets offer the most favorable combination of regulatory tailwinds, formulation readiness, and competitive openness? Where should R&D investment be concentrated to secure advantages in rheology modification, dispersion stability, defoaming efficiency, or leveling performance without compromising VOC compliance? How should procurement and supplier diversification strategies account for concentration metrics, raw material transition risks, and the pace of competitor innovation? Answering these questions requires a source of intelligence that goes beyond the headline figures and into the structural logic of the market.
Conclusion
The worldwide low-VOC coating additives market is entering a phase where sustainable compliance and high performance are no longer competing priorities but integrated requirements. The historical trajectory from 2020 through 2025 and the forecast path to 2032 signal a market that is consolidating around advanced, low-emission additive technologies, shaped by stringent regulations, bio-based feedstock adoption, and a competitive field that blends scale with specialization. For enterprises making decisions in 2026, the difference between reactive positioning and proactive advantage lies in access to detailed, current, and strategically framed market intelligence. This study provides that foundation, offering the depth, structure, and competitive context needed to navigate an industry that is being redefined as fast as it is growing.
Worldwide Low-VOC Coating Additives Market
To explore the full segmentation analysis, comprehensive competitor profiles, regulatory and raw material dynamics, and forward-looking scenario frameworks, access the complete Worldwide Low-VOC Coating Additives Market report. The detailed data, regional and application-level insights, and in-depth company evaluations contained in the full publication are designed to support precise, confident decision-making across strategy, R&D, procurement, and commercial planning.
For detailed analysis of this topic, please visit the official page: Worldwide Low-VOC Coating Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automatic Weapons Market Hits $9.25B in 2025, Poised to Reach $14B by 2032
By pmarketresearch, 2026-09-16
Navigating the Next Frontier: Strategic Insights into the Worldwide Automatic Weapons Market
The global defense procurement landscape is undergoing a decisive shift. As geopolitical tensions recalibrate force postures and emerging threats demand superior firepower, the worldwide automatic weapons market stands at a critical inflection point. For executives, government contract officers, and investment strategists alike, understanding the trajectory of this sector is no longer optional; it is a prerequisite for resilient planning. Our newly published Worldwide Automatic Weapons Market research study provides a rigorous, data-anchored foundation for navigating the 2026 decision cycle and beyond.
The automatic weapons sector is no longer defined solely by incremental upgrades to legacy platforms. It is being reshaped by rapid procurement modernization, evolving tactical requirements, and a supply chain environment that demands both agility and precision. This report distills those forces into actionable intelligence. It maps historical performance from 2020 through 2025 and projects forward through 2032, giving decision-makers a clear line of sight into the structural drivers that will shape revenue streams, competitive positioning, and program viability over the coming years.
By 2025, the overall market had reached approximately 9,250.0 million USD in revenue, reflecting a marked recovery and expansion following the fluctuations observed across 2020 to 2023. Growth momentum is projected to accelerate into the forecast window, with the market estimated at 9,971.18 million USD in 2026 and continuing toward 14,853.48 million USD by 2032. The compound annual growth rate of 7.0 percent across the 2026 to 2032 horizon underscores a sustained, structurally supported expansion rather than a temporary procurement spike. This trajectory signals durable demand and invites a more disciplined, forward-looking approach to market entry, partnership selection, and portfolio alignment.
Worldwide Automatic Weapons Market
What transforms raw figures into strategic leverage is context. This study examines how procurement cycles, platform modernization priorities, and evolving trade frameworks intersect with production capacity, component availability, and end-user requirements. Rather than presenting a static snapshot, it offers a dynamic view of the forces that executives must monitor to anticipate shifts in bidding calendars, production planning, and regional demand patterns.
Market Structure and Segmentation: Mapping the Demand Architecture
Understanding where value concentrates within the automatic weapons market requires a precise view of the segmentation architecture. The research unpacks the market across three foundational dimensions: product type, end-user category, and geographic footprint. Each slice reveals distinct demand drivers, procurement rhythms, and competitive intensity levels that materially affect market strategy.
At the product level, automatic rifles anchor a substantial share of total activity, supported by continued operational requirements and platform standardization across multiple forces. Machine guns and automatic cannons represent equally critical pillars, with each segment shaped by differing platform integration needs, sustainment profiles, and performance thresholds. Automatic shotguns and personal defense weapons round out the landscape, serving specialized operational roles where compact firepower and close-quarters effectiveness are decisive. The report provides detailed profiling for each type category, enabling stakeholders to assess where demand is structural, where it is cyclical, and where technology transitions may alter adoption curves.
End-user segmentation further clarifies the market’s operational logic. Land forces account for the largest share of demand, reflecting their central role in ground combat, security operations, and force modernization programs. Naval forces and air forces follow as significant demand centers, each governed by platform-specific integration constraints, payload considerations, and mission profiles. Law enforcement applications, while smaller in scale, represent a strategically important segment tied to domestic security requirements and specialized tactical deployments. By disaggregating demand in this way, the study equips leaders to align product roadmaps, service offerings, and partnership strategies with the end users most relevant to their organizational goals.
Geographically, the market is distributed across a diverse set of regions, each influenced by unique procurement policies, defense budgets, and alliance commitments. North America, Europe, and Asia Pacific represent major anchors of activity, with additional demand coming from the Middle East, Africa, and Latin America. These varied regional environments create distinct entry pathways and competitive conditions. The report provides region-level context to help teams evaluate market access considerations, partnership opportunities, and localization requirements without oversimplifying the complexities of cross-border defense trade.
Industry Context: The Forces Reshaping Supply, Regulation, and Demand
A market of this scale cannot be understood in isolation from the operational environment surrounding it. The study integrates several cross-cutting developments that are actively shaping sourcing strategies, compliance obligations, and demand expectations across the sector.
-
Raw material dynamics remain a critical input consideration. Hot-rolled coil steel, widely used in firearm receivers, barrels, and structural components, has been forecast around 900 USD per short ton in the second quarter of 2025, with limited recovery expected into 2026 amid global overcapacity. These cost conditions influence production economics and require manufacturers and procurement teams to plan for volatility in input pricing and capacity allocation.
-
Regulatory frameworks continue to evolve. The Wassenaar Arrangement updated its control lists in December 2025, refining entries for conventional arms and dual-use goods, including certain lasers, imaging sensors, and ceramic composite materials relevant to weapon systems. Such updates matter because they directly affect component sourcing, technology transfer pathways, and compliance planning for firms operating in multinational supply chains.
-
Export control regimes remain a defining constraint and enabler. US controls under ITAR and EAR continue to govern fully automatic firearms to .50 caliber, with ongoing revisions to licensing requirements for firearms and components designed to align with Wassenaar commitments and national security priorities. For organizations engaged in international sales, licensing strategy and documentation discipline are becoming increasingly central to deal execution and program timing.
-
Demand-side modernization is a primary growth engine. Ongoing military modernization programs, including US Next Generation Squad Weapon initiatives and allied NATO procurements, are driving demand for advanced automatic small arms capable of defeating modern body armor at extended ranges. This trend reinforces a broader shift toward performance-based procurement, where lethality, modularity, weight reduction, and integration compatibility are increasingly decisive factors.
These forces do not operate independently. Material availability, regulatory timing, and modernization priorities interact continuously, creating a landscape in which strategic foresight can differentiate market participants. The report weaves these dynamics together so that readers can evaluate not only what is happening, but how different pressures may compound across the forecast period.
Competitive Landscape: Who Is Shaping the Market
The worldwide automatic weapons market is characterized by a mix of established defense primes, specialized firearm manufacturers, and regional capability leaders. Competitive intensity varies by segment, geography, and platform class, and success increasingly depends on the ability to combine production reliability with innovation cadence and compliance readiness.
Several firms illustrate the breadth of competing approaches. FN Herstal SA, with US operations based in McLean, Virginia, remains a major producer of automatic weapons, including SCAR rifles and lightweight and medium machine guns for military and law enforcement customers worldwide. Heckler & Koch GmbH in Germany continues to specialize in automatic firearms and machine gun systems that serve military and special forces globally. SIG Sauer Inc., based in Newington, New Hampshire, produces the MCX and MPX platform families with automatic variants and has been closely associated with next-generation squad weapon systems for US and international military customers. Colt’s Manufacturing Company LLC remains an iconic producer of M4/M16 automatic rifle platforms and their variants for military forces around the world.
At the broader systems level, Rheinmetall AG in Germany develops and manufactures machine gun systems and integrated turret-mounted automatic cannons for armored platforms, while General Dynamics Corporation and Northrop Grumman Corporation contribute automatic weapon systems across aircraft, naval, and ground applications, including miniguns, cannons, and close-in weapon systems. BAE Systems plc manufactures automatic weapons and chain guns for armored vehicles and naval applications. In parallel, regional specialists play important roles in certain markets: Israel Weapon Industries offers automatic-capable platforms including rifle and light machine gun variants for military and law enforcement; Kalashnikov Concern produces AK-series rifles, light machine guns, and modernized machine guns for global military markets; Beretta manufactures automatic weapons including rifle platforms and supports military machine gun systems; Denel Land Systems develops anti-materiel rifle and automatic cannon systems; and Singapore Technologies Engineering produces light machine guns and automatic rifles for regional and international customers.
Recent industry activity underscores the tempo of innovation and program execution in this market. In January 2026, FN America introduced a next-generation FN SCAR modular rifle platform with more than two dozen upgrades, including enhanced suppressor compatibility through updated muzzle threading and dedicated FN QD suppressors for 5.56 and 7.62 variants. In May 2025, the US Army granted Type Classification to the XM7 rifle and XM250 automatic rifle under the Next Generation Squad Weapon program, enabling full production and fielding. These milestones reflect the broader push toward modular, high-performance weapon systems and the increasing importance of program milestones in shaping competitive positioning.
Market concentration data further clarifies the structure of competition. The top three firms account for 38.45 percent of market revenue, while the top five collectively represent 52.12 percent. This distribution indicates a market anchored by strong incumbents, yet one that still leaves meaningful room for differentiated offerings, niche leadership, and regional specialization. For prospective entrants and incumbent strategists alike, that balance matters: it suggests opportunities exist where technology, platform fit, or service capability can create defensible advantage even in a concentrated environment.
What the Report Delivers: Actionable Intelligence for 2026 Decisions
This study is designed for practitioners who need more than high-level estimates. It translates market size and growth into operational questions that procurement leaders, business development teams, and strategy executives face every day. The report is built around a practical framework: establish the baseline, understand the segmentation, assess the competitive and regulatory environment, and identify where to act.
Core analytical components
-
A full historical-to-forecast revenue view that situates near-term 2026 planning within a longer 2026 to 2032 trajectory, allowing leaders to pressure-test growth assumptions against both base-year performance and forward projections.
-
Segment-level analysis across product types, end-user categories, and regional markets, with enough structural detail to support product positioning, channel strategy, and demand forecasting without exposing proprietary breakdowns prematurely.
-
Competitive profiling of leading manufacturers and platform specialists, including company headquarters and operational footprints, product portfolios, and strategic roles within the market. This enables direct benchmarking and partnership evaluation.
Automatic Door Market -
Contextual analysis of recent developments, such as platform certifications, product launches, and program milestones, tied to their implications for procurement timing and competitive momentum.
-
Cross-functional market dynamics, including raw material input considerations, export control and multilateral regulatory developments, and demand-side modernization trends that influence both cost structures and market access.
-
Market concentration and structural insight to help teams gauge competitive crowding, differentiate positioning, and identify segments where specialized capabilities can command stronger strategic value.
Each component is structured to support decision-making under uncertainty. Whether the objective is identifying attractive subsegments, evaluating supply continuity risks, assessing export-related compliance exposure, or prioritizing customer conversations, the report is organized so that the intelligence can be translated directly into planning assumptions and action steps.
Why This Research Matters Now
The 2026 decision environment demands clarity. Defense budgets are being allocated against modernization priorities, procurement cycles are accelerating for next-generation platforms, and regulatory frameworks are being adjusted to reflect evolving security and technology concerns. In that environment, organizations that rely on fragmented data or lagging indicators risk misreading demand, overcommitting to weak segments, or underestimating compliance and sourcing risks.
This report offers a consolidated, analyst-vetted view of the worldwide automatic weapons market that connects market size, growth trajectory, segmentation logic, competitive dynamics, and external forces into one coherent framework. It is designed to support strategic conversations across multiple functions, including portfolio planning, business development, compliance readiness, and investor or stakeholder communication.
Most importantly, the research is built to guide action. It highlights where the market is expanding, which demand drivers are structural rather than episodic, and how leading companies are positioning themselves around product innovation and program milestones. By integrating macro trends with segmentation and competitive detail, it helps organizations move from awareness to execution with greater confidence.
Positioning Organizations for the Forecast Period
The market’s projected advance from approximately 9,971.18 million USD in 2026 toward 14,853.48 million USD in 2032 reflects a sector energized by modernization requirements, platform evolution, and sustained operational demand. Yet scale alone does not guarantee advantage. The organizations that will benefit most are those that combine disciplined market reading with differentiated execution: the right product fit for the right end user, timing aligned with program milestones, and a compliance and sourcing posture capable of absorbing regulatory and input-cost volatility.
For readers evaluating where to focus resources, the study establishes a strategic baseline and points to the most consequential questions to ask next. Which subsegments offer the strongest alignment with your capabilities? Where do certification and program milestones create near-term opportunities? How will export control updates affect your go-to-market model? What sourcing contingencies are needed given material cost conditions? These are the kinds of questions that separate reactive planning from deliberate strategy.
From Insight to Execution
This article has outlined the strategic contours of the worldwide automatic weapons market and the broader context shaping its trajectory. The full report goes further, providing the segment-level depth, competitive detail, and dynamic analysis required to support concrete business decisions in 2026 and throughout the 2032 forecast horizon. For leaders who need to move quickly from market awareness to informed action, the complete research package offers the intelligence infrastructure necessary to plan with precision.
To access the full segmentation breakdown, regional demand context, detailed competitor profiles, and forward-looking scenario framing, request the complete study through our official report channel. The full dataset and analyst commentary are intended to serve as a working resource for strategy, procurement, and market development teams preparing for the next phase of market expansion.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Weapons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Oil Hose Market to Reach $5.45 Billion by 2032 at 4.8% CAGR, Led by Asia Pacific
By pmarketresearch, 2026-09-16
Navigating the Currents: Strategic Imperatives in the Global Oil Hose Market Through 2032
The worldwide oil hose market stands at a critical juncture where operational resilience meets evolving regulatory and material pressures. For executives operating within upstream exploration, midstream transportation, and downstream industrial processing, the ability to forecast demand shifts, monitor raw material volatility, and benchmark against entrenched competitors is no longer a peripheral concern. It is a core determinant of supply chain continuity, capital allocation efficiency, and long-term profitability. Our newly published Worldwide Oil Hose Market research report provides a comprehensive, data-driven roadmap designed specifically to equip decision-makers with the analytical rigor required to navigate the 2026–2032 horizon with confidence.
A Decade of Structural Growth Underpinned by Steady Expansion
The global oil hose market has demonstrated consistent expansion over the past five years, with total revenue climbing from approximately 3.11 billion USD in 2020 to an estimated 3.93 billion USD in 2025. This historical trajectory reflects sustained investment in oilfield infrastructure, marine bunkering networks, and heavy industrial fluid transfer systems. Looking ahead, the market is projected to grow at a compound annual growth rate of 4.8 percent through 2032, with forecasted revenues expected to surpass 5.45 billion USD by the end of the period.
While macroeconomic headwinds—including fluctuating crude pricing environments, geopolitical supply chain disruptions, and shifting regulatory mandates—have periodically altered procurement cycles, the underlying demand drivers remain structurally intact. The projected growth curve is not merely a linear extension of historical performance; it encapsulates the compounding effect of emerging deepwater projects, fleet modernization programs, and the gradual replacement of aging hose assets across mature basins. Recognizing the inflection points embedded within this trajectory is essential for organizations seeking to optimize inventory positioning, align production capacity with regional demand surges, and time capital expenditures against competitive windows of opportunity.
Raw Material Volatility and Regulatory Compliance as Strategic Filters
One of the most immediate pressures facing manufacturers, distributors, and end-users is the dynamic pricing environment for core polymer inputs. Synthetic rubber benchmarks have exhibited pronounced year-over-year escalation, with China-based pricing reflecting a 34.16 percent increase as of late April 2026, even after recent monthly corrections. Concurrently, Nitrile Butadiene Rubber pricing in North American markets strengthened markedly through mid-March 2026, driven by geopolitical supply constraints and tightening logistics corridors. These material cost movements directly influence gross margins, pricing strategies, and the economic viability of specific hose formulations across different application segments.
Beyond cost structures, compliance frameworks increasingly dictate product selection and procurement protocols. Oil hoses deployed in fuel transfer, mineral oil conveyance, and marine refuelling operations are routinely manufactured to meet stringent technical standards, including EN 12115 for chemical resistance, as well as EN 1360 and EN 1761 specifications for truck and aircraft fuel delivery systems. In offshore and deepwater environments, adherence to API and OCIMF guidelines remains a non-negotiable baseline for safety, environmental protection, and operational licensing. Organizations that fail to integrate these compliance layers into their sourcing criteria risk not only regulatory exposure but also operational downtime and reputational damage.
Our research unpacks how material price trajectories intersect with engineering specifications, regional certification requirements, and sustainability mandates. Rather than treating raw material volatility as an isolated procurement concern, the report frames it as a systemic variable that influences product design choices, supplier negotiations, and long-term contract structuring.
Application-Specific Demand Drivers Across Exploration, Transport, and Industrial Ecosystems
The oil hose ecosystem serves a highly diversified set of operational contexts, each with distinct technical requirements, procurement cycles, and growth catalysts. Offshore and deepwater exploration continues to represent the largest demand center, driven by the necessity for high-performance fluid conveyance capable of withstanding extreme pressure, corrosive subsea conditions, and rigorous safety protocols. The transportation and tankers segment follows closely, supported by global crude and refined product logistics, marine bunkering expansion, and the ongoing renewal of fuel transfer infrastructure across major port networks.
Parallel demand streams emerge from refineries and industrial processing facilities, where hoses are integral to pipeline interconnects, chemical handling, and pressurized fluid distribution. Automotive and marine engine applications, while comparatively smaller in aggregate revenue contribution, remain critical for specialized OEMs and aftermarket service networks that prioritize durability, flexibility, and compliance with evolving emissions and fuel compatibility standards. The interplay between these application verticals creates a layered demand structure in which shifts in one segment can cascade into pricing dynamics, inventory strategies, and supplier prioritization across the broader market.
Worldwide Oil Hose Market
Our analysis maps these application-driven demand patterns without isolating them from their operational realities. Understanding where exploration capital is being deployed, how tanker fleet utilization cycles are evolving, and which industrial processing hubs are undergoing expansion provides decision-makers with the contextual intelligence needed to align product portfolios, sales territories, and service-level commitments with actual market pull.
Competitive Intensity and the Calculus of Market Positioning
The competitive architecture of the oil hose market is characterized by a concentrated yet globally dispersed supplier base. The cumulative share held by the top three contenders remains modest, while the top five players command a slightly larger but still fragmented portion of total revenue. This structural dispersion indicates that market leadership is not solely a function of scale but rather a combination of technical differentiation, regional distribution strength, compliance certification breadth, and the ability to serve demanding operational environments across multiple geographies.
Established industrial and hydraulic specialists anchor much of the competitive landscape. Parker Hannifin Corporation leverages its extensive portfolio of hydraulic and industrial hoses, including rubber oil hoses, fuel transfer solutions, and specialized fluid conveyance products engineered for abrasion, chemical, and weathering resistance. Eaton Corporation complements this landscape with industrial and hydraulic hose systems tailored for oil, fuel, and petroleum transfer, emphasizing high-performance configurations for demanding oilfield and marine environments. Gates Corporation maintains a strong focus on power transmission and fluid power applications, delivering hydraulic and industrial hoses that integrate seamlessly into heavy industry and oil and gas sector operations.
European and Asia-Pacific manufacturers introduce distinct competitive dynamics through material specialization, regional certification expertise, and cost-optimized manufacturing footprints. Manuli Hydraulics brings extensive experience in fuel and oil hose systems, including series engineered with NBR, SBR, and CR materials to meet EN 12115 standards for heavy-duty mineral oil applications. Trelleborg AB supplies comprehensive industrial hose portfolios for oil and gas transfer, marine deployments, and dock oil series designed for petroleum transportation. Alfagomma Group contributes hydraulic and industrial hose solutions spanning oil, fuel, and petroleum handling across multiple industrial sectors. Transfer Oil S.p.A. has established a prominent position as an independent manufacturer of reinforced thermoplastic hoses for hydraulic, industrial fluid, and oil and gas conveying applications, with a distribution footprint extending across more than 75 countries. Danfoss A/S operates one of the world's largest hose production facilities in Turkey, offering hydraulic and industrial hose products, including SEL-branded and private-label configurations, for low, mid, and high-pressure oil and fluid transfer scenarios. RYCO Hydraulics designs and manufactures premium hydraulic and industrial hoses, including fuel and oil solutions for mining, construction, marine, and oil and gas industries.
In the North American and specialized offshore segments, NRP Jones focuses on hydraulic and industrial hoses engineered specifically for harsh oil field conditions, while Cavmac produces large bore, hand-built rubber hoses with substantial internal diameters for oil, fuel, marine, offshore, and dockside applications. Continental AG, through its ContiTech division, delivers energy hoses, rig supply hoses, and marine fluid transfer solutions that align with API-standard requirements for offshore environments. Chinese manufacturers such as ZYfire Hose Corporation and Sinopulse Hose Factory further expand the competitive field by producing industrial hoses, lay-flat frac hoses, petroleum and oilfield hoses, and fuel dispensing, suction, and discharge configurations that cater to both domestic and export markets.
The competitive intensity of this landscape means that strategic advantage rarely comes from a single product launch or pricing adjustment. It emerges from a sustained ability to anticipate regional demand shifts, optimize material sourcing against volatile input costs, maintain compliance readiness across multiple certification regimes, and align distribution capabilities with the geographic concentration of end-user purchasing activity. Our report provides a structured evaluation of how these competitors position themselves across product lines, application segments, and regional markets, enabling clients to benchmark their own strategic posture and identify white-space opportunities or defensive vulnerabilities.
What the Research Delivers: Operational Intelligence for Execution
Market research that stops at high-level sizing or generic trend commentary offers limited utility for executives responsible for medium-term planning and operational execution. The Worldwide Oil Hose Market report is structured to bridge the gap between strategic overview and actionable intelligence. It integrates historical performance tracking with forward-looking forecasts, enabling organizations to test capacity expansion scenarios, evaluate pricing strategies against material cost trajectories, and assess the timing of procurement commitments relative to anticipated demand cycles.
The analysis covers segmentation dynamics across product typologies, geographic regions, and application verticals, providing the structural clarity needed to determine where growth is concentrating and where competitive saturation may be intensifying. Competitive profiling extends beyond corporate descriptions to examine positioning logic, product alignment with end-user requirements, and the strategic implications of geographic manufacturing and distribution footprints. Supply chain and raw material considerations are woven into the broader market narrative, illustrating how polymer pricing shifts, logistics constraints, and certification requirements influence margin structures and procurement decision-making.
Hydraulic Hose Market
Additionally, the report examines regulatory and standards-driven dynamics that shape product selection in fuel delivery, offshore fluid transfer, and industrial processing environments. By mapping the intersection of compliance mandates, technical performance expectations, and regional procurement practices, the research equips clients with the context required to evaluate supplier qualifications, design specification thresholds, and risk mitigation strategies. The objective is not simply to inform but to operationalize intelligence—transforming market data into executable planning parameters that support procurement, sales strategy, product development, and capital allocation decisions.
Strategic Value for 2026 Decision-Making
The 2026 operating environment demands a more granular understanding of how material cost fluctuations, compliance requirements, application-specific demand cycles, and competitive positioning interact to shape market outcomes. Organizations that approach the oil hose sector with only aggregate market awareness risk misallocating inventory, underestimating regional demand surges, or overcommitting to product lines that face intensifying competitive pressure. Conversely, firms that leverage comprehensive market intelligence can time procurement commitments more effectively, align product portfolios with the highest-value application segments, and differentiate their offerings through compliance readiness, material engineering, and geographic service coverage.
Our Worldwide Oil Hose Market report is designed to serve as a strategic reference point for these decisions. By consolidating historical performance, forward-looking forecasts, competitive analysis, and dynamic industry context into a cohesive framework, the research enables executives to move from reactive monitoring to proactive planning. The insights contained within support scenario modeling, regional prioritization, supplier evaluation, and long-term capacity strategy, providing the analytical foundation required to navigate a market defined by steady growth, material volatility, and evolving technical expectations.
For organizations seeking to deepen their strategic positioning and secure a data-driven advantage in the oil hose sector, the full research report delivers the complete segmentation detail, competitive benchmarking, and dynamic market analysis necessary to inform high-stakes decisions through 2032. The complete intelligence package is available through the source publication, where the full dataset, methodological framework, and extended competitive profiles provide the depth required for precise strategic execution.
For detailed analysis of this topic, please visit the official page: Worldwide Oil Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Areca Nut Market Hits $1,008M in 2025, Projected 3.88% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Evolving Global Areca Nut Market
As the global areca nut market enters a critical phase of restructuring and value-chain modernization, corporate strategists, supply chain architects, and regulatory compliance teams require more than headline figures to make defensible decisions in 2026. The commodity sits at the intersection of entrenched consumption patterns, tightening health-related regulations, shifting agricultural input economics, and rapidly evolving export-grade processing standards. Understanding where the market is heading, which operational levers are moving the needle, and how competitive intensity is concentrating across key geographies demands a structured, forward-looking intelligence framework. This analysis outlines the strategic architecture behind our latest Worldwide Areca Nut Market study, demonstrating why it is engineered specifically to support enterprise decision-making throughout the 2026–2032 horizon.
The Macro Trajectory and What It Signals for Planning Cycles
Across the historical window from 2020 through 2025, the global areca nut market expanded from roughly USD 840 million to surpass the USD 1,000 million threshold, reflecting sustained demand in core consumption regions alongside gradual improvements in post-harvest handling and grading consistency. The forward trajectory, modeled through 2032, points to a measured but structurally meaningful expansion, anchored by a forecast CAGR of approximately 3.88 percent. By 2026, market revenue is projected to cross the USD 1.1 billion mark, with the growth path continuing toward the mid-USD 1.3 billion range before reaching the late-forecast period.
For executives, these trajectories are not merely indicators of volume expansion. They reveal a market transitioning from raw volume growth to margin-sensitive, compliance-aware, and grade-differentiated commerce. The modest but persistent compound growth rate suggests that headline volume gains will increasingly be offset by cost pressures, regulatory friction, and quality-standard premiums. Strategic planning in 2026 must therefore account for scenarios where volume scaling is decoupled from revenue acceleration, and where competitive advantage shifts toward processing efficiency, traceability, and access to premium export channels rather than bulk commodity volume alone.
Importantly, the market’s concentration profile underscores the need for careful competitor mapping. A relatively concentrated top tier of participants commands a significant share of market value, while the remaining landscape is fragmented across regional cooperatives, processors, and export-focused mid-tier operators. This structure creates both risks and opportunities: pricing and procurement leverage can shift quickly around dominant players, while nimble regional entrants with upgraded processing capabilities can capture value in compliance-driven or certification-sensitive export segments. The full segmentation architecture, including regional distribution and application splits, is mapped in granular detail within the report, allowing leadership teams to identify where exposure, dependency, or untapped adjacency exists without relying on high-level approximations.
Areca Plates Market
Building an Operational Intelligence Base Beyond Industry Averages
A market study of this scale is most valuable when it translates structural dynamics into actionable internal planning inputs. The research is organized to support multiple enterprise functions simultaneously, from procurement and capacity planning to regulatory risk assessment and competitive benchmarking. Rather than stopping at aggregate projections, the report integrates historical baselines, forward modeling, and operational milestones that shape how value is captured along the supply chain.
At the analytical core, the study examines the market across multiple structural lenses. The type dimension differentiates between product variants that carry distinct grading premiums, end-use preferences, and processing requirements. Direct consumption remains a dominant demand stream, but the report also maps the role of pharmaceutical and industrial applications, where quality consistency, extraction specifications, and input standardization influence procurement behavior and contract structures. This layered segmentation approach helps identify where demand is most price-elastic, where quality differentiation commands margin resilience, and where downstream specifications are tightening in response to food-safety or regulatory expectations.
The regional architecture is handled with the same operational intent. Asia Pacific remains the foundational demand and production base, reflecting deeply embedded consumption and long-established cultivation and processing ecosystems. Beyond that core, the report delineates how secondary regions function within the global trade network, capturing differences in import dependency, compliance sensitivity, and trade-route dynamics. Rather than presenting regional shares as static snapshots, the analysis traces how procurement geography, export orientation, and policy environments interact to shape channel strategies over the forecast period.
To support practical usage, the report includes scenario-ready frameworks that help teams test assumptions around yield volatility, input-cost escalation, processing throughput, and export compliance readiness. It also provides decision-support materials designed for cross-functional alignment, ensuring that commercial, operations, and compliance teams can work from the same underlying market logic. The structure is intentionally built to feed directly into strategic planning calendars, quarterly risk reviews, and supplier or channel evaluations.
Competitive Landscapes, Operational Upgrades, and the 2026 Policy Pulse
Competitive positioning in the areca nut market is increasingly defined by processing capability, procurement scale, and the ability to align with export-grade quality and safety expectations. The competitive universe spans large cooperative structures, export-oriented processors, and specialized traders that serve distinct domestic and international demand channels. Several of these players are moving beyond commodity handling toward higher-value processing, optical sorting, hygienic packaging, and region-specific value-added initiatives. These operational shifts matter because they directly affect grade consistency, rejection rates, and access to buyers who require documented food-safety and traceability standards.
Worldwide Areca Nut Market
Recent operational and policy developments illustrate how quickly the competitive and regulatory environment is being reshaped. In early 2026, a major cooperative laid the foundation for a new branch and modern warehouse designed to strengthen procurement efficiency for grower members, signaling continued investment in upstream consolidation and post-harvest handling in core cultivation zones. Around the same time, a state-level government initiative expanded an agro-processing cluster program under a national horticulture mission, introducing subsidized mechanized equipment and new processing clusters aimed at reducing post-harvest losses. This type of policy support changes the operating economics for small and mid-scale processors by lowering capital friction and improving throughput consistency.
On the export-compliance side, one international-facing processor commissioned an upgraded optical sorting and hygienic packaging line to meet export quality and food-safety expectations, reflecting a broader industry trend where technological upgrades are becoming prerequisites for maintaining or expanding access to premium channels. Meanwhile, another operator inaugurated a high-capacity processing unit to support substantial local cultivation acreage, demonstrating how regional processing capacity is being aligned with localized production bases. These facility-level moves are not isolated; they are part of a reorientation toward grade control, processing speed, and standardized output that increasingly distinguishes suppliers in buyer evaluations.
Regulatory and trade-policy dynamics add another layer of strategic complexity. Over recent periods, trade protections have been reinforced in key domestic markets through minimum import pricing and elevated customs duties, aimed at shielding local producers from external supply pressures. At the same time, food-safety and import-administration frameworks in major destination markets continue to maintain heightened scrutiny for products containing areca nut, influencing detention practices and compliance expectations for exporters. These overlapping regulatory currents create a market where product readiness, documentation, and channel selection can determine commercial viability as much as volume or price. Added to this are input-cost pressures affecting cultivation economics, with fertilizer and pesticide expenses trending upward and placing strain on smallholder production systems. The report integrates these dynamics into its forward analysis so that procurement, sourcing, and market-entry strategies are evaluated against realistic cost and compliance scenarios rather than static assumptions.
Why This Research Is Built for 2026 Decision-Making
Enterprise leaders do not need another retrospective summary; they need a decision-grade intelligence asset that connects market structure to operational consequence. The Worldwide Areca Nut Market study is designed with that endpoint in mind. It combines historical validation, forward-looking modeling, competitive tracking, and regulatory-context mapping into a single coherent framework, enabling strategy, operations, and risk teams to evaluate opportunities and vulnerabilities on common terms.
The report’s value lies in its specificity and its readiness for internal application. It supports questions that emerge directly in planning discussions: where concentration and supplier dependency are most pronounced, which processing or compliance upgrades are becoming commercially meaningful, how trade policy and health-related regulatory scrutiny intersect with channel strategy, and which regional demand streams offer the most defensible growth paths under current cost and policy conditions. By integrating these elements, the research helps organizations avoid overreliance on aggregate market narratives and instead base decisions on the structural drivers that will shape pricing, throughput, access, and margin outcomes across the forecast window.
For organizations actively shaping 2026 procurement plans, export-channel strategies, capacity investments, or market-entry assessments, the complete dataset and analytical modules provide the granularity required to move from directional awareness to precise action. The full segmentation splits, company-level competitive profiles, regional demand architecture, and forward scenario structures are available within the complete study, offering a ready-made foundation for strategic review and cross-functional alignment.
Accessing the Full Intelligence Architecture
To support rigorous enterprise planning, the full report goes beyond the directional insights summarized here and provides the detailed segmentation data, competitive benchmarking, regulatory mapping, and scenario support that strategy teams require. The complete version contains the region-level distribution, type-level revenue architecture, application-level demand mapping, and the extended competitive and policy timelines needed to pressure-test internal assumptions.
If your team is preparing for 2026 sourcing decisions, market positioning reviews, or capacity and compliance investments, the full Worldwide Areca Nut Market research offers the structured intelligence necessary to convert market complexity into actionable strategy. Access the complete report to retrieve the core segmentation values, competitive profiles, and forward forecasting modules that underpin the analysis and to align your planning cycle with the most current market logic available.
For detailed analysis of this topic, please visit the official page: Worldwide Areca Nut Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Subsea Well Access and BOP Market to Reach $6.76 Billion by 2032, Growing at 5.4% CAGR
By pmarketresearch, 2026-09-16
Navigating the Depths: Strategic Intelligence for the Subsea Well Access and BOP System Market (2026-2032)
The offshore oil and gas industry is entering a decisive phase of operational recalibration. As legacy fields mature and frontier basins demand higher technical performance, the infrastructure that enables safe, efficient subsea intervention has become a strategic priority for operators and equipment suppliers alike. Subsea well access and blowout preventer (BOP) systems sit at the intersection of safety assurance, production optimization, and cost discipline. Understanding where this market is headed, who is shaping its trajectory, and what forces are reshaping procurement decisions is no longer optional. It is a prerequisite for capital allocation, vendor selection, and long-cycle project planning.
Our newly released Worldwide Subsea Well Access And BOP System Market study is designed to cut through the noise and deliver actionable intelligence for executives, procurement leaders, and corporate strategy teams. Rather than offering high-level generalizations, this report maps the operational, technological, and competitive realities that will define market behavior through 2032. Below is a structured overview of the landscape, the dynamics driving it, and the strategic frameworks embedded in our analysis.
Market Trajectory and Structural Growth Drivers
The subsea well access and BOP system market has demonstrated consistent expansion over the past half-decade, supported by a combination of deepwater project sanctioning, aging offshore asset intervention needs, and continuous upgrades in pressure control technology. Historical revenue progression from 2020 through 2025 reflects a market that has moved past post-cycle stabilization and entered a more predictable growth rhythm. The forward curve reinforces that momentum: the forecast period from 2026 to 2032 points to a compound annual growth rate of 5.4 percent, with market valuation projected to cross the 6.7 billion USD threshold by the end of the forecast window.
This trajectory is not uniform across all segments, but it is persistent. Several underlying forces explain why. First, operators are increasingly relying on subsea well access solutions to extend field life, reduce surface infrastructure exposure, and execute targeted workovers without incurring the cost and schedule burden of full surface redeployments. Second, BOP system demand remains tied to both new drilling campaigns and the ongoing modernization of installed bases, particularly where regulatory expectations, well complexity, and pressure ratings continue to rise. Third, the shift toward higher-specification equipment in challenging reservoir environments is creating a technical premium that favors suppliers capable of delivering compliant, high-integrity systems at scale.
The convergence of these drivers is producing a market in which demand visibility is improving, but competitive differentiation is becoming more nuanced. Revenue growth alone no longer signals advantage. What matters now is the ability to align system architecture, qualification pathways, service integration, and regional execution capacity with operator priorities.
Segment Architecture and Procurement Realities
The market is structurally divided across multiple dimensions that influence both pricing and sourcing strategy. On the component side, the ecosystem spans subsea blowout preventer systems and well access systems, each with distinct engineering requirements, service attachments, and deployment cycles. These two categories are complementary but not interchangeable, and procurement teams increasingly evaluate them through different lenses: one anchored in safety-critical pressure control, the other in intervention efficiency, completion flexibility, and well lifecycle management.
Water depth further shapes demand patterns. Shallow water, deepwater, and ultra-deepwater environments each impose different design constraints, installation logistics, and certification expectations. As project portfolios shift toward more technically demanding settings, the addressable market for high-pressure, high-reliability systems expands, while the cost and qualification burden for suppliers rises in parallel. This segmentation matters because it influences not just unit economics, but also lead times, inventory strategy, and the local presence required to support offshore campaigns.
On the materials and manufacturing side, the sector continues to contend with the practical realities of high-strength steel, corrosion-resistant alloys, and precision machining. Pricing dispersion across BOP stacks remains significant, reflecting variations in pressure rating, component complexity, and specification requirements. In practice, this means procurement decisions are becoming more value-driven and less commodity-based. Operators and EPCs are scrutinizing total cost of ownership, availability of life-of-field support, and the credibility of a supplier's qualification track record.
Worldwide Subsea Well Access And BOP System Market
Regulatory, Technical, and Operational Dynamics
Standards and compliance frameworks are increasingly central to commercial speed and competitive positioning. Subsea well access and BOP equipment must satisfy rigorous technical expectations, including API specifications for intervention and pressure control systems. The industry is also moving toward higher-pressure design envelopes, with 20,000 psi-class equipment development gaining relevance for frontier basins where bottom-hole pressures and reservoir conditions push conventional equipment limits. This trend is especially pronounced in areas such as the Gulf of Mexico Paleogene trend, where extreme pressure regimes require equipment that can perform reliably under demanding operational stress.
At the same time, sour-service compatibility remains a non-negotiable consideration for many projects. Material selection and component qualification under NACE MR0175 are essential for mitigating corrosion risks and ensuring long-term integrity in hostile reservoir environments. The practical implication for buyers is that procurement timelines must incorporate testing, validation, and documentation checkpoints that are tightly linked to the operating environment. For suppliers, compliance is both a cost driver and a competitive moat. Companies that can demonstrate consistent adherence to API and material standards while maintaining product robustness are better positioned to win repeat awards and integrated project roles.
Operational trends are also reshaping market expectations. Intervention strategies are evolving toward solutions that reduce rig time, minimize surface footprint, and improve well access flexibility. Riserless and open-water intervention approaches, for example, are gaining traction as operators seek more efficient ways to access subsea wells without the overhead of traditional infrastructure. These service-driven models blur the line between equipment supply and field execution, encouraging partnerships between OEMs, service companies, and operators that can de-risk complex campaigns.
Competitive Landscape and Strategic Positioning
The competitive field includes a diverse set of global players with varying strengths across equipment manufacturing, subsea production architecture, well access intervention packages, and pressure control services. Market concentration reflects a landscape where scale, technical depth, and regional execution capability matter. A core group of leading suppliers commands a substantial share of activity, while a broader tier of specialized firms competes on innovation, niche intervention technologies, and tailored project support.
Among the most prominent participants, several firms have built strong identities around subsea well access and pressure control. Baker Hughes Company continues to be recognized for its subsea well access systems, including installation and workover control systems, subsea wellhead technologies, and pressure control equipment suited to deepwater and ultra-deepwater operations. SLB maintains a broad footprint in subsea pressure control, BOP manufacturing, downhole intervention tools, and well access solutions, including advanced configurations designed for ultra-deepwater pre-salt reservoirs. Aker Solutions ASA brings depth in subsea production systems, well access intervention packages, workover systems, and integrated subsea trees, often paired with well access technologies. TechnipFMC is heavily involved in subsea production systems and integrated well access solutions, including subsea trees and associated intervention equipment for offshore projects.
National Oilwell Varco remains a key manufacturer of subsea BOP systems, drilling equipment, and well access technologies, with a notable focus on high-pressure ram BOPs for deepwater applications. Weatherford International Plc. supplies subsea well access systems, pressure control equipment, and intervention solutions for offshore operations, while Oceaneering International contributes riserless light well intervention services and deepwater intervention capabilities. Dril-Quip Inc. provides subsea wellhead systems, well access equipment, and related drilling and completion technologies. Halliburton Company offers subsea well control solutions, intervention services, and support for BOP and well access systems across drilling and completion activities.
A strong presence is also evident among specialists in well intervention and subsea control technologies. Expro has built recognition around subsea well access systems, including its Solus single shear-and-seal ball valve system designed for intervention and abandonment activities. Proserv supplies subsea well access and control systems, along with intervention and production enhancement technologies. Helix Energy Solutions Group Inc. contributes well intervention vessels and subsea well access services, including riserless and open-water intervention capabilities. Taken together, these players illustrate a market where competitive advantage depends on a blend of product engineering, service integration, and the ability to execute in challenging offshore environments.
Recent activity further signals where strategic focus is intensifying. In February 2026, Expro launched its Solus single high-debris shear-and-seal ball valve system for subsea well access. By consolidating two valves into one, the design aims to reduce complexity, failure points, and costs in intervention and abandonment work, with validation to API Std 17G and NACE MR0175. In September 2025, SLB secured a major contract from Petrobras for completions on up to 35 ultra-deepwater wells in the Atapu/Sépia fields, deploying advanced interval control valves as part of subsea well access and production systems. Earlier, in February 2025, Innovex signed a master service agreement with SLB's OneSubsea as the exclusive supplier of subsea wellhead systems, reinforcing subsea well access infrastructure supply chains.
These developments are not isolated product or contract announcements. They reflect broader shifts toward simplified hardware architectures, expanded ultra-deepwater deployment, and tighter supply-chain alignment between equipment makers and subsea technology partners. For operators and investors, the pattern suggests that suppliers with integrated capabilities, validated high-pressure designs, and credible intervention portfolios are likely to capture disproportionate value as projects become more technically complex.
Strategic Imperatives for 2026 Decision-Making
As market participants plan for 2026 and beyond, several strategic questions deserve structured attention. For operators, the priority is no longer simply securing equipment availability. It is optimizing the balance between safety assurance, intervention flexibility, and lifecycle cost. That requires clearer visibility into which suppliers can deliver high-specification systems on time, support them throughout the field life, and adapt to evolving operational models.
For equipment manufacturers and service providers, the opportunities lie in differentiation through reliability, qualification readiness, and integration. Companies that can demonstrate compliant performance in high-pressure and sour-service environments, while streamlining hardware complexity and supporting faster intervention campaigns, will be better placed to win repeat business and long-term partnerships. At the same time, firms must manage exposure to material costs, lead-time variability, and the execution demands of deepwater and ultra-deepwater projects.
For investors and corporate planners, market concentration and competitive dynamism raise important risk and opportunity considerations. A market with meaningful concentration can offer stability and scale advantages, but it also demands careful analysis of supplier dependency, innovation pace, and regional execution capacity. Understanding how key players are positioning themselves across BOP systems, well access systems, and intervention services is essential for evaluating supply continuity and pricing resilience.
Our report is built to support these decisions with a disciplined, evidence-based framework. It does not simply describe what is happening; it structures the information in ways that help teams compare options, anticipate bottlenecks, and align procurement or investment strategies with market reality.
What the Report Delivers
This study provides a comprehensive analytical foundation for executives who need more than headline figures. It combines market sizing and growth projections with detailed segmentation analysis across regions, system components, and water depth categories. It examines the competitive landscape with company-level profiles, recent contract activity, product launches, and strategic agreements that reveal how participating firms are shaping the market. It also contextualizes technical and regulatory dynamics, including API and material compliance expectations, high-pressure equipment development, and emerging intervention approaches.
Worldwide Subsea Sensors Market
Beyond macro trends, the report focuses on the operational implications of market evolution. It explores how demand is distributed across shallow water, deepwater, and ultra-deepwater settings, how component-level revenue splits inform procurement and capacity planning, and how recent industry activity reflects shifting priorities in subsea well access and pressure control. Readers will find practical context for evaluating supplier capabilities, anticipating technology trends, and aligning portfolio strategy with the realities of offshore deployment.
The value of this research lies in its ability to connect high-level market direction with the decision-level detail that strategy teams need. Market sizing establishes the scale and pace of opportunity. Segmentation reveals where demand is concentrated and how it is likely to shift. Competitive intelligence clarifies who is winning work, what technologies are gaining traction, and where partnerships are being forged. Technical and regulatory context ensures that growth narratives are grounded in the practical constraints that shape execution.
Conclusion
The Worldwide Subsea Well Access And BOP System Market is moving into a phase where strategic agility will separate participants that merely survive from those that capture durable advantage. Growth is expected to continue at a steady pace, but the real differentiators will be technical credibility, compliance reliability, service integration, and the capacity to support increasingly demanding offshore environments. For organizations making decisions in 2026, the ability to read these signals accurately will influence procurement strategy, partnership selection, and long-term positioning.
This report is designed to provide that clarity. It offers the intelligence needed to navigate a market that is expanding in value, intensifying in technical complexity, and becoming more selective in how value is awarded. The full study delivers the depth, segmentation, and competitive analysis required to turn market awareness into informed action.
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Well Access And BOP System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Military Floating Bridge Market to Hit 1,199.49M USD by 2032|5.12% CAGR
By pmarketresearch, 2026-09-16
Navigating the Waters of Defense Modernization: Strategic Intelligence on the Worldwide Military Floating Bridge Market (2026–2032)
In an era defined by heightened geopolitical friction and the strategic imperative for rapid expeditionary deployment, the ability to traverse contested waterways has never been more critical to operational success. Military floating bridges are no longer merely engineering support assets; they are force multipliers that enable armored brigades to maintain momentum across wet gaps that would otherwise stall advance maneuvers. At PW Consulting, we recognize that understanding the trajectory of this specialized defense sector is essential for stakeholders navigating procurement cycles, investment allocations, and supply chain resilience. Our latest research initiative, the Worldwide Military Floating Bridge Market study, delivers a comprehensive, forward-looking intelligence framework calibrated to support enterprise decision-making throughout the 2026–2032 horizon.
The global market for military floating bridges closed the 2025 base year at approximately USD 845.67 million, reflecting a compounding trajectory that analysts project will reach roughly USD 1.2 billion by 2032. This expansion is underpinned by a steady compound annual growth rate of 5.12 percent, signaling both sustained institutional demand and the gradual modernization of legacy bridging inventories. The historical record from 2020 through 2025 reveals a market that absorbed macroeconomic volatility, supply chain reconfiguration, and shifting procurement priorities, yet consistently returned to an upward growth path. Looking ahead, the forecast period captures the inflection point where next-generation systems, multinational framework contracts, and accelerated training cycles converge to reshape competitive positioning and downstream manufacturing requirements.
Floating Dock Market
For defense contractors, engineering prime contractors, materiel planners, and financial analysts, these aggregate figures represent far more than top-line indicators. They reflect evolving readiness postures, the reallocation of modernization budgets toward rapid-deployment infrastructure, and the strategic recalibration of allied force structures. This report translates those macro signals into actionable intelligence, equipping leadership teams with the context needed to evaluate partnership opportunities, anticipate requirement shifts, and align production or investment roadmaps with the operational tempo of modern armed forces.
Market Architecture and Structural Value Drivers
The worldwide military floating bridge market is organized around several interlocking value streams, each responding to distinct operational requirements and procurement rhythms. By platform architecture, the landscape encompasses ribbon bridge systems engineered for heavy combat vehicle passage, amphibious bridge rigs that balance deployment speed with payload capacity, and motorized floating bridges designed for mechanized wet-gap crossings under combat conditions. By end-use mission profile, demand clusters around ground combat operations that require sustained armored mobility, disaster relief and humanitarian assistance missions that depend on rapid, modular deployment in degraded environments, and military training and drills that sustain crew proficiency and system readiness between operational cycles.
Behind these functional categories lies a hardware ecosystem dominated by aluminum alloy and steel constructions, which together account for over sixty percent of material utilization across modular floating platforms. This material reliance is dictated by uncompromising engineering requirements: high strength-to-weight ratios, resistance to prolonged immersion and corrosion, and the structural integrity necessary to support military load classifications that routinely span MLC 80 through MLC 120 configurations. Compliance with STANAG 2021 standards further constrains design parameters, ensuring interoperability across allied formations and standardizing load ratings for wheeled and tracked platforms in systems such as improved ribbon bridges and motorized floating variants.
The market's structural dynamics are equally influenced by the accelerating cadence of joint procurement initiatives. Defense ministries are increasingly pooling requirements through multinational frameworks to achieve economies of scale, standardize training pipelines, and reduce single-nation logistical burdens. These collaborative acquisition models are reshaping supplier relationships, compressing development timelines, and elevating the strategic importance of manufacturers capable of delivering certified, interoperable systems at scale. The ripple effects extend to raw material sourcing, fabrication capacity, and aftermarket support networks, making supply chain visibility a critical component of competitive positioning.
Operational and Procurement Dynamics Shaping the Forecast Period
Several overlapping forces are converging to define the market's trajectory from 2026 onward. First, rising defense budgets and force modernization programs are explicitly prioritizing rapid-deployment modular floating bridges as essential enablers of expeditionary operations. Military planners recognize that wet-gap crossing capability must be integrated into brigade-level maneuver concepts rather than treated as a standalone engineer task, driving demand for lighter, faster-deploying, and more modular configurations. Second, the regulatory and standardization environment continues to reinforce the dominance of established load-classification frameworks, ensuring that new system introductions must demonstrate compatibility with existing tactical vehicles, handling protocols, and joint logistics structures.
Third, the geopolitical landscape has elevated river-crossing capability from a niche engineering concern to a core element of allied deterrence and operational readiness. Mobilization scenarios, territorial defense planning, and contingency response frameworks across multiple theaters have prompted defense institutions to treat wet-gap capability as a continuous readiness priority rather than a cyclical procurement item. This shift encourages longer-term framework agreements, multi-year delivery schedules, and sustained training investments that collectively stabilize demand signals and reduce the volatility historically associated with single-event bridge acquisitions.
Finally, the competition for procurement share is intensifying as incumbents and emerging manufacturers alike seek to differentiate through deployment speed, payload capacity, modularity, and lifecycle support. The market's competitive density is reflected in a moderately concentrated supplier base, where leading participants command substantial positioning while specialized firms continue to capture differentiated niches through regional partnerships, material innovation, and mission-specific engineering solutions. Understanding how these dynamics interact is essential for any organization seeking to negotiate favorable contract terms, anticipate competitor moves, or align internal R&D pipelines with emerging operational requirements.
What This Research Delivers for Enterprise Decision-Makers
Our Worldwide Military Floating Bridge Market study is structured to convert high-level market signals into operationally useful intelligence. Rather than offering superficial trend commentary, the report delivers a methodical, data-anchored assessment of the environment in which suppliers, procurement bodies, and investment stakeholders must operate. Key components of the analysis include:
- A multi-period historical reconstruction from 2020 through 2025 that isolates growth patterns, inflection points, and the market's response to evolving procurement and readiness priorities.
- A forward forecast extending through 2032, anchored in defensible growth assumptions and calibrated to capture the effects of modernization programs, joint procurement frameworks, and sustained training cycles.
- A functional and mission-based segmentation review that clarifies how different platform architectures and end-use profiles contribute to overall market structure, enabling buyers and suppliers to map capability portfolios against demand concentrations.
- A competitive positioning assessment that examines the strategic profiles of leading manufacturers, their product architectures, deployment track records, and the operational contexts in which their systems are fielded or under contract.
- An integration of industry context signals covering material utilization patterns, military load classification requirements, standardization frameworks, and the geopolitical procurement dynamics that shape cross-border defense acquisition.
- A structured review of recent contract awards, delivery milestones, and training activations that illustrate how market demand translates into executable procurement activity and long-term capability roadmaps.
The report is designed to support scenario planning, customer targeting, supplier evaluation, and portfolio strategy development. It provides the contextual depth necessary to interpret how individual contracts, program announcements, and capability deliveries aggregate into durable market trajectories, while deliberately preserving granular segmentation data for stakeholders who require full-spectrum intelligence for detailed strategic modeling.
Competitive Landscape and Strategic Positioning
The competitive field in military floating bridges reflects a blend of long-established defense engineering firms, specialized bridging manufacturers, and regional suppliers expanding their footprint through targeted export programs and multinational participation. Several participants stand out for their operational relevance, product maturity, and active engagement in high-value procurement initiatives. CNIM Systèmes Industriels, based in France, has positioned itself around the Motorized Floating Bridge (PFM) platform for MLC 90T and 100W class vehicles, delivering tactical wet-gap crossing capability to the French Army and extending its footprint through the Daglezja-P program for Polish forces. The company's recent inclusion in a consortium awarded a major framework contract by the French DGA underscores the strategic priority placed on restoring and modernizing armored brigade river-crossing capability, with training activations already underway for delivered sets and additional units scheduled for phased delivery into the latter part of the decade.
Worldwide Military Floating Bridge Market
General Dynamics European Land Systems, headquartered in Germany, operates as a leading provider of amphibious bridging systems and continues to shape allied capability standards through platforms such as the M3 amphibious bridge and ferry system, the Improved Ribbon Bridge for heavy combat vehicles, and the HYDRA modular pontoon system. Its equipment supports multiple NATO forces, and recent multi-hundred-million-euro award activity through OCCAR for next-generation M3 capabilities to Germany and the UK highlights the strategic weight of the Wide Wet Gap Crossing project, which aims to replace aging systems with faster-deploying, higher-capacity solutions aligned to contemporary maneuver requirements.
Across the Atlantic, Acrow supplies wet-gap prefabricated modular steel bridge solutions with floating barge configurations engineered to support line-of-communication missions and heavy vehicle crossings at elevated load classifications. In the United Kingdom, Mabey Bridge has extended the legacy of the Bailey Bridge through the Mabey Logistic Support Bridge, a configurable platform that integrates floating pontoons for both military and emergency applications and has achieved broad adoption across NATO nations. In continental Europe, Waagner-Biro Bridge Systems contributes modular prefabricated steel panel bridges suited to temporary and emergency military bridging, including configurations adapted for floating support environments.
The market also features active participation from manufacturers in Asia, where Jiangsu Bailey Steel Bridge Co., Ltd. produces Bailey and military floating/pontoon bridge systems for defense applications, and China Harzone Industry Corp., Ltd. manufactures military pontoon and modular floating bridge platforms. These suppliers illustrate the expanding globalization of bridging expertise and the increasing relevance of export-oriented production capacity in a market where allied procurement, regional modernization programs, and cost-competitive manufacturing continue to intersect.
Recent Procurement and Capability Milestones
The pace of recent contract activity and system delivery reinforces the market's transformation from episodic acquisition to sustained capability renewal. In early 2026, a consortium that includes CNIM Systèmes Industriels, alongside CEFA and Soframe, secured a substantial framework contract from the French DGA to supply new heavy and light crossing systems, a move intended to restore river-crossing capability for armored brigades and institutionalize access to modernized wet-gap platforms. Around the same period, the Polish Armed Forces' 3rd Engineer Regiment began training on newly delivered PFM Motorized Floating Bridge sets under the Daglezja-P program, following an additional implementing contract for multiple sets with deliveries extending through 2029. These milestones demonstrate how capability delivery now spans not only hardware supply but also structured crew training and sustained logistical support.
In late 2025, General Dynamics European Land Systems secured a major award exceeding €450 million through OCCAR for new-generation M3 amphibious bridging and ferry capabilities destined for Germany and the United Kingdom under the Wide Wet Gap Crossing project. The initiative reflects a deliberate effort to replace legacy systems with platforms optimized for deployment speed and load capacity, and it signals the growing preference for multinational acquisition pathways that harmonize requirements, reduce duplication, and improve interoperability across allied forces. Together, these developments illustrate a procurement environment in which framework-level commitments, multi-year delivery schedules, and cross-border collaboration are becoming defining features of market growth.
Why This Intelligence Matters for 2026 Decision-Making
For enterprises operating in or adjacent to the defense systems sector, the military floating bridge market presents both structural opportunity and strategic complexity. The convergence of modernization budgets, multinational procurement frameworks, and standardized load-classification requirements creates a demand environment that rewards suppliers capable of delivering certified interoperability, scalable production, and lifecycle support. At the same time, it raises the stakes for companies evaluating market entry, capacity expansion, partnership formation, or portfolio diversification. Decisions made in 2026 will shape competitiveness through the end of the decade, making early access to comprehensive, forward-looking intelligence a strategic necessity rather than an informational luxury.
This report is designed to support those decisions. It connects high-level market size and growth signals to the operational realities that drive procurement behavior, clarifies where competitive pressure is intensifying, and highlights the kinds of capability, certification, and supply-chain attributes that increasingly determine contract success. By embedding recent contract awards, delivery and training milestones, material and regulatory context, and geopolitical procurement dynamics into a single analytical framework, the study equips decision-makers with the situational awareness needed to move from reactive market observation to proactive strategy formulation.
Detailed segmentation breakdowns, exhaustive regional valuation splits, and mission-level revenue allocations are reserved for the full research deliverable. That level of granularity is essential for precise modeling, bid strategy development, and targeted market-entry planning, and it is precisely the depth that distinguishes a surface-level overview from an actionable intelligence asset. Organizations that require complete access to those figures, along with the supporting methodology and competitive benchmarking framework, are invited to obtain the full report through the source page, where the complete dataset and accompanying analysis are available.
The Worldwide Military Floating Bridge Market is entering a phase of sustained capability renewal, shaped by modernization imperatives, allied collaboration, and the operational demand for rapid, reliable wet-gap crossing solutions. Understanding how that phase unfolds will separate organizations that merely observe market movement from those that position themselves to capture it. This research provides the strategic foundation for that distinction.
For detailed analysis of this topic, please visit the official page: Worldwide Military Floating Bridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fish & Shrimp Feed Additive Market Hits $2,450M in 2025, 5.45% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Insights from the Worldwide Fish and Shrimp Feed Additive Market Outlook
The global aquaculture sector stands at a critical inflection point. As wild capture fisheries plateau, the industry's reliance on formulated nutrition has never been greater. Our latest Worldwide Fish and Shrimp Feed Additive Market research delivers a comprehensive blueprint for navigating the years through 2032, translating historical performance and forward-looking indicators into actionable intelligence for executive decision-making.
Worldwide Fish and Shrimp Feed Additive Market
Building upon a robust historical baseline from 2020 to 2025, our analysis captures the market's journey from approximately 1,879 million USD to a projected 2,450 million USD in 2025. This trajectory reflects a compound annual growth rate of 5.45 percent across the forecast horizon of 2026 through 2032. While these aggregate figures provide a crucial macroeconomic compass, the true strategic value of our research lies in its granular dissection of growth vectors, operational bottlenecks, and competitive maneuvers that will separate market leaders from laggards in the coming cycle.
This document serves as an executive prequel to our full report. We outline the structural forces reshaping the nutrition landscape for fish and shrimp, highlight the operational realities that procurement and R&D teams must confront, and preview the analytical frameworks our study provides. For teams seeking exact valuation thresholds, regional penetration curves, and application-specific adoption models, the complete market intelligence is engineered to be calibrated against your internal business models.
The Macro Trajectory: From Recovery to Structural Expansion
The market's expansion since 2020 has been characterized by a blend of post-pandemic supply chain recalibration and sustained demand for high-efficiency aquafeed formulations. By the close of 2025, total market revenue crossed the 2,450 million USD threshold, setting a firm footing for the projected climb toward 3,552 million USD by 2032. This growth is not merely a function of volume; it is increasingly a story of formulation sophistication. Producers are moving beyond commodity inclusion toward precision nutrition that balances growth rates, disease resistance, and environmental compliance.
Our forecast period, spanning 2026 to 2032, maps a landscape where incremental volume gains intersect with intense cost pressures. The revenue progression from 2,588 million USD in 2026 to over 3,100 million USD by 2029 underscores the acceleration of nutrition intensity in farming operations. However, these totals mask a volatile reality at the ingredient level. Structural factors such as raw material price swings for synthetic amino acids, particularly those influenced by energy costs and regulatory environments in major production regions, create persistent margin challenges. Simultaneously, elevated prices for traditional marine ingredients in 2025 have forced feed formulators to rethink substitution ratios and cost-benefit equations.
Understanding how these macroeconomic and supply-side forces interact is the first layer of insight our report provides. Executives will gain clarity on which growth segments are driven by genuine functional necessity versus those buoyed by short-term commodity cycles, allowing for more disciplined capital allocation and hedging strategies.
Competitive Architecture: Global Giants and Regional Powerhouses
The industry's competitive landscape is defined by a concentration of top players that collectively command a meaningful share of total revenue, with the top three entities accounting for approximately 28.4 percent and the top five extending to 42.15 percent. This level of concentration suggests a market where scale, formulation IP, and integration capabilities heavily influence win rates on large-volume contracts. Yet, beneath this handful of leaders lies a diverse array of specialized firms and regionally dominant producers driving distinct value propositions.
Global leaders such as Cargill Incorporated, Nutreco N.V. (operating through its Skretting brand), BioMar Group, Alltech Inc., Archer Daniels Midland Company, dsm-firmenich, Evonik Industries AG, and BASF SE represent the core of the internationalized nutrition and additive supply chain. These firms compete on the strength of comprehensive portfolios, spanning amino acid optimization, enzyme systems, organic trace minerals, carotenoids, and functional health additives. Several have leaned heavily into microbiome management, sustainable ingredient sourcing, and performance-linked certification frameworks to differentiate beyond price.
In parallel, specialized and regionally entrenched players are reshaping localized supply dynamics. Guangdong HAID Group Co., Ltd., Tongwei Co., Ltd., Charoen Pokphand Foods PCL (CP Foods), Aller Aqua Group, and Ridley Corporation Limited demonstrate how integrated aquaculture networks and regional capacity advantages can intensify competition in specific geographies and species segments. Companies such as Adisseo and Kemin Industries further enrich the landscape with targeted methionine delivery, antioxidant technologies, mold inhibition, and gut health solutions that address nuanced formulation challenges.
Recent corporate activity highlights how this competitive board is being actively reconfigured. In September 2025, BioMar Group partnered with Innovafeed and Auchan to commercialize black soldier fly insect meal for Ecuadorian shrimp feed, signaling a deliberate pivot toward alternative protein integration. Earlier that year, in March 2025, the same group secured France's first Aquaculture Stewardship Council Feed Certification for its Nersac mill, reinforcing the strategic weight of sustainability credentials. Even regulatory milestones influence competitive positioning: the November 2024 FDA approval of the first generic florfenicol formulation introduced a new cost and availability axis for controlling mortality in freshwater-reared fish. Our report dissects these moves not as isolated headlines, but as indicators of where margins, differentiation, and barriers to entry are evolving.
Worldwide Shrimp's Disease Treatment Market
Dynamics Shaping Formulation Decisions
The feed additive market does not operate in a vacuum. A confluence of regulatory, sustainability, and ingredient-cost forces dictates what formulators can realistically deploy and what producers are willing to pay. Understanding these dynamics is essential for translating market size data into durable commercial strategy.
Regulatory complexity remains a persistent operational reality. Across United States aquaculture operations, the total annual regulatory cost burden reached 196 million USD in 2023 terms, representing roughly 9 to 30 percent of total annual costs depending on farm scale and compliance profile. This heterogeneity means that additive procurement cannot be standardized across all customer segments; instead, it must align with the specific compliance architecture of each farming operation. In Europe, regulatory frameworks such as EC 1831/2003 govern the safe use of herbal additives, including oregano, rosemary, sage, thyme, and mint, establishing clear boundaries for natural and botanical inclusions within aquaculture nutrition programs.
Simultaneously, sustainability imperatives are reshaping input portfolios. The shift toward alternative proteins, notably insect meal such as black soldier fly biomass and a broader range of plant-based ingredients, is accelerating as operators seek to mitigate fishmeal dependency and reduce environmental impact. This transition is not merely aspirational; it is becoming commercially executable, as demonstrated by recent commercialization efforts linking sustainable ingredient innovation with large-scale retail and farming partnerships.
On the cost side, volatility in synthetic amino acid pricing, driven by energy inputs and regulatory conditions in China, remains a primary determinant of feed additive economics. Coupled with rising fishmeal and fish oil costs in 2025, these pressures elevate production expenses and compress margins across aquafeed formulations. Our analysis isolates the interplay between these cost drivers and additive utilization patterns, helping teams forecast where substitution, formulation efficiency, and premiumization will have the greatest financial impact.
Inside the Research Framework
Our Worldwide Fish and Shrimp Feed Additive Market study is designed as an operational toolkit, not just a high-level overview. The report integrates historical data, forward forecasts, and qualitative intelligence into a modular structure that supports pricing strategy, R&D prioritization, procurement planning, and competitive positioning.
The analytical core begins with a full historical reconstruction from 2020 through 2025, followed by a forecast architecture extending to 2032. This temporal breadth enables users to test growth assumptions against multiple scenarios and identify inflection points where volume momentum diverges from price behavior. All monetary figures are reported in USD millions, allowing direct integration with enterprise financial models.
Beyond the aggregate market curve, the report maps regional demand distributions, providing comparative context for where supply-side investments and formulation priorities are gaining traction. While exact split percentages and absolute regional revenue figures are reserved for the full intelligence package, the strategic takeaway is unmistakable: regional feed ecosystems differ substantially in cost structures, species mix, regulatory intensity, and additive adoption maturity. Our analysis equips teams with the frameworks to evaluate which geographies offer the most favorable risk-return balance for additive portfolios and partnership strategies.
The study also breaks down additive categories and application environments, covering functional classes such as amino acid solutions, vitamin and mineral premixes, enzyme systems, antibiotics and antimicrobials, probiotics and prebiotics, and mycotoxin binders. In parallel, it examines how these inputs are deployed across fish and shrimp feeding programs. The contrast between fish-focused and shrimp-focused nutrition pathways is especially important for product developers and commercial teams: each pathway carries distinct performance requirements, regulatory constraints, and buyer expectations. Instead of presenting raw subgroup allocations, the report emphasizes strategic cross-references—such as where enzyme integration intersects with gut health programs in shrimp diets, or how amino acid precision correlates with feed conversion targets in finfish operations.
To support competitive and operational decision-making, the report includes detailed company profiles spanning major global players and regional leaders. Each profile covers headquarters context, core capabilities, and strategic orientation within aquafeed and additive markets. The competitive section pairs these profiles with a review of recent developments, including partnerships, commercialization milestones, and regulatory approvals, translating them into implications for market share dynamics and innovation races. This allows executives to anticipate where formulation IP, sustainability certification, and supply chain integration will become decisive.
Procurement and supply chain teams will find particular value in the report's treatment of raw material volatility, cost driver mapping, and regulatory burden analysis. By connecting ingredient-level instability to formulation and pricing outcomes, the research helps teams design contracts, hedging postures, and supplier diversification plans that are resilient under stress. Sustainability and compliance teams, meanwhile, can leverage the synthesis of regulatory constraints and alternative ingredient trends to plan ingredient roadmaps that align with evolving certification requirements and buyer expectations.
Conclusion: Converting Intelligence into Action
The Worldwide Fish and Shrimp Feed Additive Market is expanding along a defined growth curve, yet its strategic significance lies in the choices that surround that curve. The market's movement from 2,450 million USD in 2025 toward over 3,550 million USD by 2032 reflects an industry increasingly shaped by precision nutrition, alternative ingredient integration, cost-side volatility, and a regulatory landscape that differs sharply across jurisdictions. Companies that can read these signals early will gain an advantage in formulation design, supplier selection, and market positioning.
Our full market research translates these dynamics into precise revenue trajectories, segment-level comparisons, regional demand distributions, and competitive assessments. It is built for teams that need to move from general market awareness to specific business decisions—whether that means prioritizing a new enzyme system, evaluating a regional expansion, renegotiating an amino acid supply contract, or benchmarking a sustainability claim against market reality.
For decision-makers ready to convert trend awareness into targeted strategy, the complete report provides the granular dashboards, company evaluations, and scenario frameworks needed to de-risk planning through 2032. The executive overview presented here establishes the strategic landscape; the full intelligence package delivers the figures and toolkits required to act on it.
For detailed analysis of this topic, please visit the official page: Worldwide Fish and Shrimp Feed Additive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com