

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Antibody Fragments Market Hits $12B in 2025, Growing at 9.6% CAGR Through 2032

Navigating the Next Wave: Strategic Intelligence for the Global Antibody Fragments Market (2026–2032)
The therapeutic landscape is undergoing a structural shift. As full-length monoclonal antibodies approach maturity in certain indications, antibody fragments—Fab, scFv, and single-domain VHH/nanobody formats—are emerging as precision instruments that address unmet needs in tissue penetration, pharmacokinetics, and manufacturing agility. Our newly released Worldwide Antibody Fragments Market study is designed to convert this structural transition into actionable strategy for executives operating across biopharma, diagnostics, and research supply chains.
Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
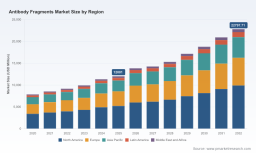
This report offers a disciplined, forward-looking view of a market that reached an estimated USD 12,001.0 million in 2025 and is projected to scale to approximately USD 22,797.7 million by 2032, reflecting a forecast-period CAGR of 9.6%. More than a revenue trajectory, these figures signal a market in which strategic positioning, platform selection, and manufacturing realism will determine which organizations capture durable share. The insights that follow are built to support 2026 decision cycles—from portfolio prioritization and partnership evaluation to capacity planning and regulatory preparedness.
Why Antibody Fragments Are Reaching an Inflection Point
Antibody fragments are not a substitute for full-length antibodies; they are a complementary toolkit. By removing the Fc region, fragments can achieve deeper tissue penetration, reduced immunogenicity in selected contexts, and alternative expression routes that alter the economics of production. At the same time, the absence of a native Fc domain introduces trade-offs that many strategy discussions still underestimate. The strategic question for 2026 is not whether fragments matter, but how to align indication selection, format choice, and process design so that technical advantages translate into commercial value.
Our market analysis situates this question within a market structure that has evolved steadily from USD 7,850.4 million in 2020 to the 2025 baseline noted above, with 2026 projected to reach approximately USD 13,829.3 million. That growth path is not uniform across formats or use cases. It is shaped by therapeutic adoption curves, diagnostic demand, research-sector activity, and regional dynamics that differ in both pace and concentration. The report unpacks these drivers without reducing them to static snapshots, allowing decision-makers to see where momentum is durable and where volatility demands a more adaptive plan.
What the Study Covers: Operational Utility for Strategy Teams
The study is built for teams that need more than a top-line number. It connects market sizing with the operational and competitive realities that determine execution risk. Topics examined include:
- Historical evolution from 2020 through the 2025 base year, with a forecast window extending to 2032 designed to inform medium-term planning rather than short-lived tactical bets.
- Segment-level perspectives on antibody fragment types and application domains, presented to illuminate demand drivers, adoption patterns, and the relative maturity of each pathway.
- Regional market perspectives that clarify where activity is concentrated and how geographic variation influences partnership, supply, and market-entry logic.
- A competitive landscape built around major global companies and specialized producers, anchored in their platform strategies, pipeline directions, and recent commercial or technical developments.
- Manufacturing and regulatory realities that shape cost structures, lead times, and go-to-market feasibility for fragment-based programs.
The intent is practical intelligence. Each section is structured so that R&D leaders can compare technology pathways, commercial leaders can weigh indication and pricing dynamics, and operations leaders can anticipate where process complexity will affect margin and timeline. Crucially, the analysis preserves the granularity needed for internal modeling while presenting a coherent narrative suitable for board-level discussion.
The Cost-and-Complexity Equation That Shapes Fragment Economics
A recurring theme in this study is that fragment economics cannot be inferred from full antibody analogies. Without the Fc domain, conventional Protein A affinity capture is not available, forcing reliance on multi-step purification approaches such as ion exchange and hydrophobic interaction chromatography. Sector analysis indicates that these added process steps can raise manufacturing costs by up to 60% relative to full monoclonal antibody production in comparable contexts. That cost penalty is not universally fatal—especially when fragments are paired with high-value indications or differentiated formats—but it changes the algebra of target product profiles and scale-up decisions.
On the other side of the equation, expression strategy can create meaningful leverage. Microbial systems such as E. coli or Pichia pastoris can enable more cost-effective production of scFv and nanobody formats compared with mammalian systems traditionally used for full antibodies, with reported yields reaching up to 150 mg/L in optimized fed-batch processes. For organizations evaluating capacity, outsourcing, or platform investments, this distinction is central. The report examines where microbial productivity offers a genuine advantage and where downstream complexity re-emerges, helping teams avoid over-optimistic assumptions about cost parity.
Half-Life Engineering, Regulation, and the Commercial Margin Story
Therapeutic fragments often require molecular engineering to address short serum half-life. PEGylation, albumin-binding tags, or Fc fusions can extend exposure and improve dosing convenience, but these modifications are not free. Sector analyses indicate that such half-life extension strategies can double or triple cost of goods sold, a dynamic that becomes especially consequential in price-sensitive indications or competitive reimbursement environments. Decision-makers must therefore view half-life engineering not simply as a scientific choice but as a commercial lever with direct implications for margin, market access, and indication prioritization.
Worldwide Antibody Fragments Market
Regulatory expectations add another layer of realism. Antibody fragments, including Fab, scFv, and VHH/nanobody formats, require rigorous preclinical, clinical, and post-market assessments comparable to other biologics seeking therapeutic approval. The regulatory path is viable and increasingly familiar, but it is not shortcuttable. The study integrates these expectations into its market outlook so that teams can align development timelines, evidence-generation plans, and market-entry assumptions with the realities of biological evaluation and approval pathways.
Competitive Landscape: Platforms, Partnerships, and Differentiated Moves
The competitive picture reflects a blend of large biopharmaceutical organizations and specialized technology providers, each pursuing distinct routes to value. The study profiles a range of leading participants, including F. Hoffmann-La Roche AG, Novartis AG, AbbVie Inc., Amgen Inc., Pfizer Inc., Johnson & Johnson (Janssen), Bristol-Myers Squibb, Sanofi (Ablynx), UCB, Eli Lilly and Company, Sino Biological, Inc., and evitria AG. Rather than presenting a simple corporate roster, the analysis focuses on how each organization's platform activity, therapeutic emphasis, and production specialization informs its strategic posture in fragment-based markets.
Several recent developments illustrate the direction of travel. In August 2025, Sanofi continued to advance and promote its NANOBODY technology platform for next-generation therapeutics, emphasizing improved tissue penetration and manufacturing advantages tied to single-domain formats. In January 2025, Adimab announced that it had entered 17 new partnerships and achieved 51 milestones in 2024, including programs involving VHH single-domain antibody formats—a signal of growing partnership velocity around fragment-compatible discovery and optimization capabilities. In February 2025, a broader industrial review summarized nanobody production, patent activity, clinical trial trends, and industrialization patterns from 2014 onward, reinforcing the idea that fragment platforms are moving from niche differentiation toward scaled commercialization conversations.
Within this landscape, market concentration remains significant. The study notes a combined share held by the top three participants of approximately 42.5% and a top five share of roughly 58.8%. These concentration levels matter because they shape both competitive intensity and opportunity distribution. They indicate where incumbency advantages are strongest, and where adjacent entrants may still create value through specialized manufacturing, novel formats, or targeted indication strategies. The report explores these dynamics in depth so that companies can gauge not just who is present, but how the arena is likely to evolve as platform and partnership activity accelerates.
Where Fragments Are Creating Distinct Value Across Applications
Antibody fragments are being evaluated and deployed across therapeutics, diagnostics, and research and development, but the strategic logic differs in each domain. In therapeutics, fragments can offer advantages in indications where tissue access, molecular size, or engineering flexibility are decisive. In diagnostics, fragments can support binding specificity, format compactness, and manufacturing flexibility for assay design. In research and development, fragments serve as enabling tools for discovery, target validation, and custom production workflows that feed earlier-stage pipeline activity.
The report examines these application pathways with attention to adoption readiness and commercial logic, rather than treating them as interchangeable categories. For example, therapeutic use cases often involve the largest revenue pool and the most demanding regulatory and reimbursement scrutiny, while research and diagnostic activities can provide earlier demand signals, specialized revenue streams, and useful proving grounds for format selection. Understanding the interplay among these domains is essential for organizations that want to sequence investments wisely and avoid over-committing to a single pathway before evidence is sufficient.
Regional Structure and the Distribution of Opportunity
Market opportunity is not uniformly distributed, and regional variation influences everything from partnership strategy to supply-chain design. The study maps regional market perspectives to clarify where current activity is concentrated and how geographic differences shape demand patterns, manufacturing footprints, and market-access considerations. This regional framing is especially important for companies evaluating where to place development resources, how to prioritize collaborations, and which markets might offer faster paths to proof of concept versus larger but more competitive revenue opportunities.
Because regional dynamics interact with format choice, application mix, and manufacturing economics, the analysis avoids simplistic rankings and instead focuses on the strategic implications of geographic structure. That approach allows executives to interpret where regional scale matters, where specialized local capabilities can create advantage, and how global players may adjust their footprints over the forecast period.
How to Use This Intelligence for 2026 Decisions
The 2026 planning cycle will reward organizations that treat antibody fragments as a strategic platform decision rather than a narrow product category. The study is structured to support that mindset in several concrete ways:
- Portfolio strategy: Evaluate where fragment formats align with indication needs, target product profiles, and differentiation goals, while accounting for half-life engineering, manufacturing complexity, and regulatory burden.
- Partnership and sourcing: Compare internal platform bets with external options, including specialized producers and technology partners, by weighing yield potential, purification requirements, and timeline implications.
- Capacity and cost planning: Model production scenarios that reflect the real cost drivers of fragment purification, expression system selection, and half-life modification strategies.
- Market-entry sequencing: Use regional and application-level insight to sequence launches, partnerships, and evidence generation in ways that balance speed, risk, and revenue potential.
- Competitive posture: Situate your organization relative to large biopharmaceutical players and focused entrants, recognizing both concentration dynamics and the partnership activity now reshaping the field.
What Remains Inside the Full Analysis
This overview establishes the framework and the stakes. The complete Worldwide Antibody Fragments Market study goes further by providing the detailed segment, regional, and competitive quantification that underpin execution-level strategy. It contains the specific breakdowns and modeled comparisons that teams need for scenario planning, investment justification, and competitive benchmarking, while preserving the broader narrative required to communicate the logic to stakeholders.
For organizations preparing 2026 decisions, the full report is where the strategic signal becomes operational. The macro trajectory—growth from a 2025 baseline of USD 12,001.0 million toward a 2032 projection of approximately USD 22,797.7 million at a 9.6% CAGR—gives the market its gravity. The segment splits, regional distributions, application dynamics, and competitive concentration data give it shape. The manufacturing, regulatory, and reimbursement realities give it discipline. Together, they form a decision-ready intelligence base for leaders who need to move from awareness to action.
The Worldwide Antibody Fragments Market study is now available through PW Consulting. Readers seeking the detailed segmentation figures, regional quantification, company-level profiles, and modeled forecast pathways are encouraged to access the full report at the source webpage, where the complete dataset and expert commentary can be reviewed in context.
For detailed analysis of this topic, please visit the official page: Worldwide Antibody Fragments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com