

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automatic Weapons Market Hits $9.25B in 2025, Poised to Reach $14B by 2032

Navigating the Next Frontier: Strategic Insights into the Worldwide Automatic Weapons Market
The global defense procurement landscape is undergoing a decisive shift. As geopolitical tensions recalibrate force postures and emerging threats demand superior firepower, the worldwide automatic weapons market stands at a critical inflection point. For executives, government contract officers, and investment strategists alike, understanding the trajectory of this sector is no longer optional; it is a prerequisite for resilient planning. Our newly published Worldwide Automatic Weapons Market research study provides a rigorous, data-anchored foundation for navigating the 2026 decision cycle and beyond.
The automatic weapons sector is no longer defined solely by incremental upgrades to legacy platforms. It is being reshaped by rapid procurement modernization, evolving tactical requirements, and a supply chain environment that demands both agility and precision. This report distills those forces into actionable intelligence. It maps historical performance from 2020 through 2025 and projects forward through 2032, giving decision-makers a clear line of sight into the structural drivers that will shape revenue streams, competitive positioning, and program viability over the coming years.
By 2025, the overall market had reached approximately 9,250.0 million USD in revenue, reflecting a marked recovery and expansion following the fluctuations observed across 2020 to 2023. Growth momentum is projected to accelerate into the forecast window, with the market estimated at 9,971.18 million USD in 2026 and continuing toward 14,853.48 million USD by 2032. The compound annual growth rate of 7.0 percent across the 2026 to 2032 horizon underscores a sustained, structurally supported expansion rather than a temporary procurement spike. This trajectory signals durable demand and invites a more disciplined, forward-looking approach to market entry, partnership selection, and portfolio alignment.
Worldwide Automatic Weapons Market
What transforms raw figures into strategic leverage is context. This study examines how procurement cycles, platform modernization priorities, and evolving trade frameworks intersect with production capacity, component availability, and end-user requirements. Rather than presenting a static snapshot, it offers a dynamic view of the forces that executives must monitor to anticipate shifts in bidding calendars, production planning, and regional demand patterns.
Market Structure and Segmentation: Mapping the Demand Architecture
Understanding where value concentrates within the automatic weapons market requires a precise view of the segmentation architecture. The research unpacks the market across three foundational dimensions: product type, end-user category, and geographic footprint. Each slice reveals distinct demand drivers, procurement rhythms, and competitive intensity levels that materially affect market strategy.
At the product level, automatic rifles anchor a substantial share of total activity, supported by continued operational requirements and platform standardization across multiple forces. Machine guns and automatic cannons represent equally critical pillars, with each segment shaped by differing platform integration needs, sustainment profiles, and performance thresholds. Automatic shotguns and personal defense weapons round out the landscape, serving specialized operational roles where compact firepower and close-quarters effectiveness are decisive. The report provides detailed profiling for each type category, enabling stakeholders to assess where demand is structural, where it is cyclical, and where technology transitions may alter adoption curves.
End-user segmentation further clarifies the market’s operational logic. Land forces account for the largest share of demand, reflecting their central role in ground combat, security operations, and force modernization programs. Naval forces and air forces follow as significant demand centers, each governed by platform-specific integration constraints, payload considerations, and mission profiles. Law enforcement applications, while smaller in scale, represent a strategically important segment tied to domestic security requirements and specialized tactical deployments. By disaggregating demand in this way, the study equips leaders to align product roadmaps, service offerings, and partnership strategies with the end users most relevant to their organizational goals.
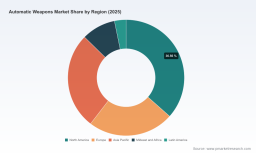
Geographically, the market is distributed across a diverse set of regions, each influenced by unique procurement policies, defense budgets, and alliance commitments. North America, Europe, and Asia Pacific represent major anchors of activity, with additional demand coming from the Middle East, Africa, and Latin America. These varied regional environments create distinct entry pathways and competitive conditions. The report provides region-level context to help teams evaluate market access considerations, partnership opportunities, and localization requirements without oversimplifying the complexities of cross-border defense trade.
Industry Context: The Forces Reshaping Supply, Regulation, and Demand
A market of this scale cannot be understood in isolation from the operational environment surrounding it. The study integrates several cross-cutting developments that are actively shaping sourcing strategies, compliance obligations, and demand expectations across the sector.
-
Raw material dynamics remain a critical input consideration. Hot-rolled coil steel, widely used in firearm receivers, barrels, and structural components, has been forecast around 900 USD per short ton in the second quarter of 2025, with limited recovery expected into 2026 amid global overcapacity. These cost conditions influence production economics and require manufacturers and procurement teams to plan for volatility in input pricing and capacity allocation.
-
Regulatory frameworks continue to evolve. The Wassenaar Arrangement updated its control lists in December 2025, refining entries for conventional arms and dual-use goods, including certain lasers, imaging sensors, and ceramic composite materials relevant to weapon systems. Such updates matter because they directly affect component sourcing, technology transfer pathways, and compliance planning for firms operating in multinational supply chains.
-
Export control regimes remain a defining constraint and enabler. US controls under ITAR and EAR continue to govern fully automatic firearms to .50 caliber, with ongoing revisions to licensing requirements for firearms and components designed to align with Wassenaar commitments and national security priorities. For organizations engaged in international sales, licensing strategy and documentation discipline are becoming increasingly central to deal execution and program timing.
-
Demand-side modernization is a primary growth engine. Ongoing military modernization programs, including US Next Generation Squad Weapon initiatives and allied NATO procurements, are driving demand for advanced automatic small arms capable of defeating modern body armor at extended ranges. This trend reinforces a broader shift toward performance-based procurement, where lethality, modularity, weight reduction, and integration compatibility are increasingly decisive factors.
These forces do not operate independently. Material availability, regulatory timing, and modernization priorities interact continuously, creating a landscape in which strategic foresight can differentiate market participants. The report weaves these dynamics together so that readers can evaluate not only what is happening, but how different pressures may compound across the forecast period.
Competitive Landscape: Who Is Shaping the Market
The worldwide automatic weapons market is characterized by a mix of established defense primes, specialized firearm manufacturers, and regional capability leaders. Competitive intensity varies by segment, geography, and platform class, and success increasingly depends on the ability to combine production reliability with innovation cadence and compliance readiness.
Several firms illustrate the breadth of competing approaches. FN Herstal SA, with US operations based in McLean, Virginia, remains a major producer of automatic weapons, including SCAR rifles and lightweight and medium machine guns for military and law enforcement customers worldwide. Heckler & Koch GmbH in Germany continues to specialize in automatic firearms and machine gun systems that serve military and special forces globally. SIG Sauer Inc., based in Newington, New Hampshire, produces the MCX and MPX platform families with automatic variants and has been closely associated with next-generation squad weapon systems for US and international military customers. Colt’s Manufacturing Company LLC remains an iconic producer of M4/M16 automatic rifle platforms and their variants for military forces around the world.
At the broader systems level, Rheinmetall AG in Germany develops and manufactures machine gun systems and integrated turret-mounted automatic cannons for armored platforms, while General Dynamics Corporation and Northrop Grumman Corporation contribute automatic weapon systems across aircraft, naval, and ground applications, including miniguns, cannons, and close-in weapon systems. BAE Systems plc manufactures automatic weapons and chain guns for armored vehicles and naval applications. In parallel, regional specialists play important roles in certain markets: Israel Weapon Industries offers automatic-capable platforms including rifle and light machine gun variants for military and law enforcement; Kalashnikov Concern produces AK-series rifles, light machine guns, and modernized machine guns for global military markets; Beretta manufactures automatic weapons including rifle platforms and supports military machine gun systems; Denel Land Systems develops anti-materiel rifle and automatic cannon systems; and Singapore Technologies Engineering produces light machine guns and automatic rifles for regional and international customers.
Recent industry activity underscores the tempo of innovation and program execution in this market. In January 2026, FN America introduced a next-generation FN SCAR modular rifle platform with more than two dozen upgrades, including enhanced suppressor compatibility through updated muzzle threading and dedicated FN QD suppressors for 5.56 and 7.62 variants. In May 2025, the US Army granted Type Classification to the XM7 rifle and XM250 automatic rifle under the Next Generation Squad Weapon program, enabling full production and fielding. These milestones reflect the broader push toward modular, high-performance weapon systems and the increasing importance of program milestones in shaping competitive positioning.
Market concentration data further clarifies the structure of competition. The top three firms account for 38.45 percent of market revenue, while the top five collectively represent 52.12 percent. This distribution indicates a market anchored by strong incumbents, yet one that still leaves meaningful room for differentiated offerings, niche leadership, and regional specialization. For prospective entrants and incumbent strategists alike, that balance matters: it suggests opportunities exist where technology, platform fit, or service capability can create defensible advantage even in a concentrated environment.
What the Report Delivers: Actionable Intelligence for 2026 Decisions
This study is designed for practitioners who need more than high-level estimates. It translates market size and growth into operational questions that procurement leaders, business development teams, and strategy executives face every day. The report is built around a practical framework: establish the baseline, understand the segmentation, assess the competitive and regulatory environment, and identify where to act.
Core analytical components
-
A full historical-to-forecast revenue view that situates near-term 2026 planning within a longer 2026 to 2032 trajectory, allowing leaders to pressure-test growth assumptions against both base-year performance and forward projections.
-
Segment-level analysis across product types, end-user categories, and regional markets, with enough structural detail to support product positioning, channel strategy, and demand forecasting without exposing proprietary breakdowns prematurely.
-
Competitive profiling of leading manufacturers and platform specialists, including company headquarters and operational footprints, product portfolios, and strategic roles within the market. This enables direct benchmarking and partnership evaluation.
Automatic Door Market -
Contextual analysis of recent developments, such as platform certifications, product launches, and program milestones, tied to their implications for procurement timing and competitive momentum.
-
Cross-functional market dynamics, including raw material input considerations, export control and multilateral regulatory developments, and demand-side modernization trends that influence both cost structures and market access.
-
Market concentration and structural insight to help teams gauge competitive crowding, differentiate positioning, and identify segments where specialized capabilities can command stronger strategic value.
Each component is structured to support decision-making under uncertainty. Whether the objective is identifying attractive subsegments, evaluating supply continuity risks, assessing export-related compliance exposure, or prioritizing customer conversations, the report is organized so that the intelligence can be translated directly into planning assumptions and action steps.
Why This Research Matters Now
The 2026 decision environment demands clarity. Defense budgets are being allocated against modernization priorities, procurement cycles are accelerating for next-generation platforms, and regulatory frameworks are being adjusted to reflect evolving security and technology concerns. In that environment, organizations that rely on fragmented data or lagging indicators risk misreading demand, overcommitting to weak segments, or underestimating compliance and sourcing risks.
This report offers a consolidated, analyst-vetted view of the worldwide automatic weapons market that connects market size, growth trajectory, segmentation logic, competitive dynamics, and external forces into one coherent framework. It is designed to support strategic conversations across multiple functions, including portfolio planning, business development, compliance readiness, and investor or stakeholder communication.
Most importantly, the research is built to guide action. It highlights where the market is expanding, which demand drivers are structural rather than episodic, and how leading companies are positioning themselves around product innovation and program milestones. By integrating macro trends with segmentation and competitive detail, it helps organizations move from awareness to execution with greater confidence.
Positioning Organizations for the Forecast Period
The market’s projected advance from approximately 9,971.18 million USD in 2026 toward 14,853.48 million USD in 2032 reflects a sector energized by modernization requirements, platform evolution, and sustained operational demand. Yet scale alone does not guarantee advantage. The organizations that will benefit most are those that combine disciplined market reading with differentiated execution: the right product fit for the right end user, timing aligned with program milestones, and a compliance and sourcing posture capable of absorbing regulatory and input-cost volatility.
For readers evaluating where to focus resources, the study establishes a strategic baseline and points to the most consequential questions to ask next. Which subsegments offer the strongest alignment with your capabilities? Where do certification and program milestones create near-term opportunities? How will export control updates affect your go-to-market model? What sourcing contingencies are needed given material cost conditions? These are the kinds of questions that separate reactive planning from deliberate strategy.
From Insight to Execution
This article has outlined the strategic contours of the worldwide automatic weapons market and the broader context shaping its trajectory. The full report goes further, providing the segment-level depth, competitive detail, and dynamic analysis required to support concrete business decisions in 2026 and throughout the 2032 forecast horizon. For leaders who need to move quickly from market awareness to informed action, the complete research package offers the intelligence infrastructure necessary to plan with precision.
To access the full segmentation breakdown, regional demand context, detailed competitor profiles, and forward-looking scenario framing, request the complete study through our official report channel. The full dataset and analyst commentary are intended to serve as a working resource for strategy, procurement, and market development teams preparing for the next phase of market expansion.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Weapons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com