

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Military Floating Bridge Market to Hit 1,199.49M USD by 2032|5.12% CAGR

Navigating the Waters of Defense Modernization: Strategic Intelligence on the Worldwide Military Floating Bridge Market (2026–2032)
In an era defined by heightened geopolitical friction and the strategic imperative for rapid expeditionary deployment, the ability to traverse contested waterways has never been more critical to operational success. Military floating bridges are no longer merely engineering support assets; they are force multipliers that enable armored brigades to maintain momentum across wet gaps that would otherwise stall advance maneuvers. At PW Consulting, we recognize that understanding the trajectory of this specialized defense sector is essential for stakeholders navigating procurement cycles, investment allocations, and supply chain resilience. Our latest research initiative, the Worldwide Military Floating Bridge Market study, delivers a comprehensive, forward-looking intelligence framework calibrated to support enterprise decision-making throughout the 2026–2032 horizon.
The global market for military floating bridges closed the 2025 base year at approximately USD 845.67 million, reflecting a compounding trajectory that analysts project will reach roughly USD 1.2 billion by 2032. This expansion is underpinned by a steady compound annual growth rate of 5.12 percent, signaling both sustained institutional demand and the gradual modernization of legacy bridging inventories. The historical record from 2020 through 2025 reveals a market that absorbed macroeconomic volatility, supply chain reconfiguration, and shifting procurement priorities, yet consistently returned to an upward growth path. Looking ahead, the forecast period captures the inflection point where next-generation systems, multinational framework contracts, and accelerated training cycles converge to reshape competitive positioning and downstream manufacturing requirements.
Floating Dock Market
For defense contractors, engineering prime contractors, materiel planners, and financial analysts, these aggregate figures represent far more than top-line indicators. They reflect evolving readiness postures, the reallocation of modernization budgets toward rapid-deployment infrastructure, and the strategic recalibration of allied force structures. This report translates those macro signals into actionable intelligence, equipping leadership teams with the context needed to evaluate partnership opportunities, anticipate requirement shifts, and align production or investment roadmaps with the operational tempo of modern armed forces.
Market Architecture and Structural Value Drivers
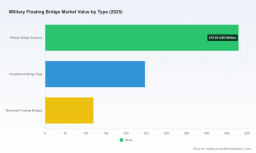
The worldwide military floating bridge market is organized around several interlocking value streams, each responding to distinct operational requirements and procurement rhythms. By platform architecture, the landscape encompasses ribbon bridge systems engineered for heavy combat vehicle passage, amphibious bridge rigs that balance deployment speed with payload capacity, and motorized floating bridges designed for mechanized wet-gap crossings under combat conditions. By end-use mission profile, demand clusters around ground combat operations that require sustained armored mobility, disaster relief and humanitarian assistance missions that depend on rapid, modular deployment in degraded environments, and military training and drills that sustain crew proficiency and system readiness between operational cycles.
Behind these functional categories lies a hardware ecosystem dominated by aluminum alloy and steel constructions, which together account for over sixty percent of material utilization across modular floating platforms. This material reliance is dictated by uncompromising engineering requirements: high strength-to-weight ratios, resistance to prolonged immersion and corrosion, and the structural integrity necessary to support military load classifications that routinely span MLC 80 through MLC 120 configurations. Compliance with STANAG 2021 standards further constrains design parameters, ensuring interoperability across allied formations and standardizing load ratings for wheeled and tracked platforms in systems such as improved ribbon bridges and motorized floating variants.
The market's structural dynamics are equally influenced by the accelerating cadence of joint procurement initiatives. Defense ministries are increasingly pooling requirements through multinational frameworks to achieve economies of scale, standardize training pipelines, and reduce single-nation logistical burdens. These collaborative acquisition models are reshaping supplier relationships, compressing development timelines, and elevating the strategic importance of manufacturers capable of delivering certified, interoperable systems at scale. The ripple effects extend to raw material sourcing, fabrication capacity, and aftermarket support networks, making supply chain visibility a critical component of competitive positioning.
Operational and Procurement Dynamics Shaping the Forecast Period
Several overlapping forces are converging to define the market's trajectory from 2026 onward. First, rising defense budgets and force modernization programs are explicitly prioritizing rapid-deployment modular floating bridges as essential enablers of expeditionary operations. Military planners recognize that wet-gap crossing capability must be integrated into brigade-level maneuver concepts rather than treated as a standalone engineer task, driving demand for lighter, faster-deploying, and more modular configurations. Second, the regulatory and standardization environment continues to reinforce the dominance of established load-classification frameworks, ensuring that new system introductions must demonstrate compatibility with existing tactical vehicles, handling protocols, and joint logistics structures.
Third, the geopolitical landscape has elevated river-crossing capability from a niche engineering concern to a core element of allied deterrence and operational readiness. Mobilization scenarios, territorial defense planning, and contingency response frameworks across multiple theaters have prompted defense institutions to treat wet-gap capability as a continuous readiness priority rather than a cyclical procurement item. This shift encourages longer-term framework agreements, multi-year delivery schedules, and sustained training investments that collectively stabilize demand signals and reduce the volatility historically associated with single-event bridge acquisitions.
Finally, the competition for procurement share is intensifying as incumbents and emerging manufacturers alike seek to differentiate through deployment speed, payload capacity, modularity, and lifecycle support. The market's competitive density is reflected in a moderately concentrated supplier base, where leading participants command substantial positioning while specialized firms continue to capture differentiated niches through regional partnerships, material innovation, and mission-specific engineering solutions. Understanding how these dynamics interact is essential for any organization seeking to negotiate favorable contract terms, anticipate competitor moves, or align internal R&D pipelines with emerging operational requirements.
What This Research Delivers for Enterprise Decision-Makers
Our Worldwide Military Floating Bridge Market study is structured to convert high-level market signals into operationally useful intelligence. Rather than offering superficial trend commentary, the report delivers a methodical, data-anchored assessment of the environment in which suppliers, procurement bodies, and investment stakeholders must operate. Key components of the analysis include:
- A multi-period historical reconstruction from 2020 through 2025 that isolates growth patterns, inflection points, and the market's response to evolving procurement and readiness priorities.
- A forward forecast extending through 2032, anchored in defensible growth assumptions and calibrated to capture the effects of modernization programs, joint procurement frameworks, and sustained training cycles.
- A functional and mission-based segmentation review that clarifies how different platform architectures and end-use profiles contribute to overall market structure, enabling buyers and suppliers to map capability portfolios against demand concentrations.
- A competitive positioning assessment that examines the strategic profiles of leading manufacturers, their product architectures, deployment track records, and the operational contexts in which their systems are fielded or under contract.
- An integration of industry context signals covering material utilization patterns, military load classification requirements, standardization frameworks, and the geopolitical procurement dynamics that shape cross-border defense acquisition.
- A structured review of recent contract awards, delivery milestones, and training activations that illustrate how market demand translates into executable procurement activity and long-term capability roadmaps.
The report is designed to support scenario planning, customer targeting, supplier evaluation, and portfolio strategy development. It provides the contextual depth necessary to interpret how individual contracts, program announcements, and capability deliveries aggregate into durable market trajectories, while deliberately preserving granular segmentation data for stakeholders who require full-spectrum intelligence for detailed strategic modeling.
Competitive Landscape and Strategic Positioning
The competitive field in military floating bridges reflects a blend of long-established defense engineering firms, specialized bridging manufacturers, and regional suppliers expanding their footprint through targeted export programs and multinational participation. Several participants stand out for their operational relevance, product maturity, and active engagement in high-value procurement initiatives. CNIM Systèmes Industriels, based in France, has positioned itself around the Motorized Floating Bridge (PFM) platform for MLC 90T and 100W class vehicles, delivering tactical wet-gap crossing capability to the French Army and extending its footprint through the Daglezja-P program for Polish forces. The company's recent inclusion in a consortium awarded a major framework contract by the French DGA underscores the strategic priority placed on restoring and modernizing armored brigade river-crossing capability, with training activations already underway for delivered sets and additional units scheduled for phased delivery into the latter part of the decade.
Worldwide Military Floating Bridge Market
General Dynamics European Land Systems, headquartered in Germany, operates as a leading provider of amphibious bridging systems and continues to shape allied capability standards through platforms such as the M3 amphibious bridge and ferry system, the Improved Ribbon Bridge for heavy combat vehicles, and the HYDRA modular pontoon system. Its equipment supports multiple NATO forces, and recent multi-hundred-million-euro award activity through OCCAR for next-generation M3 capabilities to Germany and the UK highlights the strategic weight of the Wide Wet Gap Crossing project, which aims to replace aging systems with faster-deploying, higher-capacity solutions aligned to contemporary maneuver requirements.
Across the Atlantic, Acrow supplies wet-gap prefabricated modular steel bridge solutions with floating barge configurations engineered to support line-of-communication missions and heavy vehicle crossings at elevated load classifications. In the United Kingdom, Mabey Bridge has extended the legacy of the Bailey Bridge through the Mabey Logistic Support Bridge, a configurable platform that integrates floating pontoons for both military and emergency applications and has achieved broad adoption across NATO nations. In continental Europe, Waagner-Biro Bridge Systems contributes modular prefabricated steel panel bridges suited to temporary and emergency military bridging, including configurations adapted for floating support environments.
The market also features active participation from manufacturers in Asia, where Jiangsu Bailey Steel Bridge Co., Ltd. produces Bailey and military floating/pontoon bridge systems for defense applications, and China Harzone Industry Corp., Ltd. manufactures military pontoon and modular floating bridge platforms. These suppliers illustrate the expanding globalization of bridging expertise and the increasing relevance of export-oriented production capacity in a market where allied procurement, regional modernization programs, and cost-competitive manufacturing continue to intersect.
Recent Procurement and Capability Milestones
The pace of recent contract activity and system delivery reinforces the market's transformation from episodic acquisition to sustained capability renewal. In early 2026, a consortium that includes CNIM Systèmes Industriels, alongside CEFA and Soframe, secured a substantial framework contract from the French DGA to supply new heavy and light crossing systems, a move intended to restore river-crossing capability for armored brigades and institutionalize access to modernized wet-gap platforms. Around the same period, the Polish Armed Forces' 3rd Engineer Regiment began training on newly delivered PFM Motorized Floating Bridge sets under the Daglezja-P program, following an additional implementing contract for multiple sets with deliveries extending through 2029. These milestones demonstrate how capability delivery now spans not only hardware supply but also structured crew training and sustained logistical support.
In late 2025, General Dynamics European Land Systems secured a major award exceeding €450 million through OCCAR for new-generation M3 amphibious bridging and ferry capabilities destined for Germany and the United Kingdom under the Wide Wet Gap Crossing project. The initiative reflects a deliberate effort to replace legacy systems with platforms optimized for deployment speed and load capacity, and it signals the growing preference for multinational acquisition pathways that harmonize requirements, reduce duplication, and improve interoperability across allied forces. Together, these developments illustrate a procurement environment in which framework-level commitments, multi-year delivery schedules, and cross-border collaboration are becoming defining features of market growth.
Why This Intelligence Matters for 2026 Decision-Making
For enterprises operating in or adjacent to the defense systems sector, the military floating bridge market presents both structural opportunity and strategic complexity. The convergence of modernization budgets, multinational procurement frameworks, and standardized load-classification requirements creates a demand environment that rewards suppliers capable of delivering certified interoperability, scalable production, and lifecycle support. At the same time, it raises the stakes for companies evaluating market entry, capacity expansion, partnership formation, or portfolio diversification. Decisions made in 2026 will shape competitiveness through the end of the decade, making early access to comprehensive, forward-looking intelligence a strategic necessity rather than an informational luxury.
This report is designed to support those decisions. It connects high-level market size and growth signals to the operational realities that drive procurement behavior, clarifies where competitive pressure is intensifying, and highlights the kinds of capability, certification, and supply-chain attributes that increasingly determine contract success. By embedding recent contract awards, delivery and training milestones, material and regulatory context, and geopolitical procurement dynamics into a single analytical framework, the study equips decision-makers with the situational awareness needed to move from reactive market observation to proactive strategy formulation.
Detailed segmentation breakdowns, exhaustive regional valuation splits, and mission-level revenue allocations are reserved for the full research deliverable. That level of granularity is essential for precise modeling, bid strategy development, and targeted market-entry planning, and it is precisely the depth that distinguishes a surface-level overview from an actionable intelligence asset. Organizations that require complete access to those figures, along with the supporting methodology and competitive benchmarking framework, are invited to obtain the full report through the source page, where the complete dataset and accompanying analysis are available.
The Worldwide Military Floating Bridge Market is entering a phase of sustained capability renewal, shaped by modernization imperatives, allied collaboration, and the operational demand for rapid, reliable wet-gap crossing solutions. Understanding how that phase unfolds will separate organizations that merely observe market movement from those that position themselves to capture it. This research provides the strategic foundation for that distinction.
For detailed analysis of this topic, please visit the official page: Worldwide Military Floating Bridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com