

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Oil Hose Market to Reach $5.45 Billion by 2032 at 4.8% CAGR, Led by Asia Pacific

Navigating the Currents: Strategic Imperatives in the Global Oil Hose Market Through 2032
The worldwide oil hose market stands at a critical juncture where operational resilience meets evolving regulatory and material pressures. For executives operating within upstream exploration, midstream transportation, and downstream industrial processing, the ability to forecast demand shifts, monitor raw material volatility, and benchmark against entrenched competitors is no longer a peripheral concern. It is a core determinant of supply chain continuity, capital allocation efficiency, and long-term profitability. Our newly published Worldwide Oil Hose Market research report provides a comprehensive, data-driven roadmap designed specifically to equip decision-makers with the analytical rigor required to navigate the 2026–2032 horizon with confidence.
A Decade of Structural Growth Underpinned by Steady Expansion
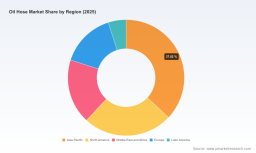
The global oil hose market has demonstrated consistent expansion over the past five years, with total revenue climbing from approximately 3.11 billion USD in 2020 to an estimated 3.93 billion USD in 2025. This historical trajectory reflects sustained investment in oilfield infrastructure, marine bunkering networks, and heavy industrial fluid transfer systems. Looking ahead, the market is projected to grow at a compound annual growth rate of 4.8 percent through 2032, with forecasted revenues expected to surpass 5.45 billion USD by the end of the period.
While macroeconomic headwinds—including fluctuating crude pricing environments, geopolitical supply chain disruptions, and shifting regulatory mandates—have periodically altered procurement cycles, the underlying demand drivers remain structurally intact. The projected growth curve is not merely a linear extension of historical performance; it encapsulates the compounding effect of emerging deepwater projects, fleet modernization programs, and the gradual replacement of aging hose assets across mature basins. Recognizing the inflection points embedded within this trajectory is essential for organizations seeking to optimize inventory positioning, align production capacity with regional demand surges, and time capital expenditures against competitive windows of opportunity.
Raw Material Volatility and Regulatory Compliance as Strategic Filters
One of the most immediate pressures facing manufacturers, distributors, and end-users is the dynamic pricing environment for core polymer inputs. Synthetic rubber benchmarks have exhibited pronounced year-over-year escalation, with China-based pricing reflecting a 34.16 percent increase as of late April 2026, even after recent monthly corrections. Concurrently, Nitrile Butadiene Rubber pricing in North American markets strengthened markedly through mid-March 2026, driven by geopolitical supply constraints and tightening logistics corridors. These material cost movements directly influence gross margins, pricing strategies, and the economic viability of specific hose formulations across different application segments.
Beyond cost structures, compliance frameworks increasingly dictate product selection and procurement protocols. Oil hoses deployed in fuel transfer, mineral oil conveyance, and marine refuelling operations are routinely manufactured to meet stringent technical standards, including EN 12115 for chemical resistance, as well as EN 1360 and EN 1761 specifications for truck and aircraft fuel delivery systems. In offshore and deepwater environments, adherence to API and OCIMF guidelines remains a non-negotiable baseline for safety, environmental protection, and operational licensing. Organizations that fail to integrate these compliance layers into their sourcing criteria risk not only regulatory exposure but also operational downtime and reputational damage.
Our research unpacks how material price trajectories intersect with engineering specifications, regional certification requirements, and sustainability mandates. Rather than treating raw material volatility as an isolated procurement concern, the report frames it as a systemic variable that influences product design choices, supplier negotiations, and long-term contract structuring.
Application-Specific Demand Drivers Across Exploration, Transport, and Industrial Ecosystems
The oil hose ecosystem serves a highly diversified set of operational contexts, each with distinct technical requirements, procurement cycles, and growth catalysts. Offshore and deepwater exploration continues to represent the largest demand center, driven by the necessity for high-performance fluid conveyance capable of withstanding extreme pressure, corrosive subsea conditions, and rigorous safety protocols. The transportation and tankers segment follows closely, supported by global crude and refined product logistics, marine bunkering expansion, and the ongoing renewal of fuel transfer infrastructure across major port networks.
Parallel demand streams emerge from refineries and industrial processing facilities, where hoses are integral to pipeline interconnects, chemical handling, and pressurized fluid distribution. Automotive and marine engine applications, while comparatively smaller in aggregate revenue contribution, remain critical for specialized OEMs and aftermarket service networks that prioritize durability, flexibility, and compliance with evolving emissions and fuel compatibility standards. The interplay between these application verticals creates a layered demand structure in which shifts in one segment can cascade into pricing dynamics, inventory strategies, and supplier prioritization across the broader market.
Worldwide Oil Hose Market
Our analysis maps these application-driven demand patterns without isolating them from their operational realities. Understanding where exploration capital is being deployed, how tanker fleet utilization cycles are evolving, and which industrial processing hubs are undergoing expansion provides decision-makers with the contextual intelligence needed to align product portfolios, sales territories, and service-level commitments with actual market pull.
Competitive Intensity and the Calculus of Market Positioning
The competitive architecture of the oil hose market is characterized by a concentrated yet globally dispersed supplier base. The cumulative share held by the top three contenders remains modest, while the top five players command a slightly larger but still fragmented portion of total revenue. This structural dispersion indicates that market leadership is not solely a function of scale but rather a combination of technical differentiation, regional distribution strength, compliance certification breadth, and the ability to serve demanding operational environments across multiple geographies.
Established industrial and hydraulic specialists anchor much of the competitive landscape. Parker Hannifin Corporation leverages its extensive portfolio of hydraulic and industrial hoses, including rubber oil hoses, fuel transfer solutions, and specialized fluid conveyance products engineered for abrasion, chemical, and weathering resistance. Eaton Corporation complements this landscape with industrial and hydraulic hose systems tailored for oil, fuel, and petroleum transfer, emphasizing high-performance configurations for demanding oilfield and marine environments. Gates Corporation maintains a strong focus on power transmission and fluid power applications, delivering hydraulic and industrial hoses that integrate seamlessly into heavy industry and oil and gas sector operations.
European and Asia-Pacific manufacturers introduce distinct competitive dynamics through material specialization, regional certification expertise, and cost-optimized manufacturing footprints. Manuli Hydraulics brings extensive experience in fuel and oil hose systems, including series engineered with NBR, SBR, and CR materials to meet EN 12115 standards for heavy-duty mineral oil applications. Trelleborg AB supplies comprehensive industrial hose portfolios for oil and gas transfer, marine deployments, and dock oil series designed for petroleum transportation. Alfagomma Group contributes hydraulic and industrial hose solutions spanning oil, fuel, and petroleum handling across multiple industrial sectors. Transfer Oil S.p.A. has established a prominent position as an independent manufacturer of reinforced thermoplastic hoses for hydraulic, industrial fluid, and oil and gas conveying applications, with a distribution footprint extending across more than 75 countries. Danfoss A/S operates one of the world's largest hose production facilities in Turkey, offering hydraulic and industrial hose products, including SEL-branded and private-label configurations, for low, mid, and high-pressure oil and fluid transfer scenarios. RYCO Hydraulics designs and manufactures premium hydraulic and industrial hoses, including fuel and oil solutions for mining, construction, marine, and oil and gas industries.
In the North American and specialized offshore segments, NRP Jones focuses on hydraulic and industrial hoses engineered specifically for harsh oil field conditions, while Cavmac produces large bore, hand-built rubber hoses with substantial internal diameters for oil, fuel, marine, offshore, and dockside applications. Continental AG, through its ContiTech division, delivers energy hoses, rig supply hoses, and marine fluid transfer solutions that align with API-standard requirements for offshore environments. Chinese manufacturers such as ZYfire Hose Corporation and Sinopulse Hose Factory further expand the competitive field by producing industrial hoses, lay-flat frac hoses, petroleum and oilfield hoses, and fuel dispensing, suction, and discharge configurations that cater to both domestic and export markets.
The competitive intensity of this landscape means that strategic advantage rarely comes from a single product launch or pricing adjustment. It emerges from a sustained ability to anticipate regional demand shifts, optimize material sourcing against volatile input costs, maintain compliance readiness across multiple certification regimes, and align distribution capabilities with the geographic concentration of end-user purchasing activity. Our report provides a structured evaluation of how these competitors position themselves across product lines, application segments, and regional markets, enabling clients to benchmark their own strategic posture and identify white-space opportunities or defensive vulnerabilities.
What the Research Delivers: Operational Intelligence for Execution
Market research that stops at high-level sizing or generic trend commentary offers limited utility for executives responsible for medium-term planning and operational execution. The Worldwide Oil Hose Market report is structured to bridge the gap between strategic overview and actionable intelligence. It integrates historical performance tracking with forward-looking forecasts, enabling organizations to test capacity expansion scenarios, evaluate pricing strategies against material cost trajectories, and assess the timing of procurement commitments relative to anticipated demand cycles.
The analysis covers segmentation dynamics across product typologies, geographic regions, and application verticals, providing the structural clarity needed to determine where growth is concentrating and where competitive saturation may be intensifying. Competitive profiling extends beyond corporate descriptions to examine positioning logic, product alignment with end-user requirements, and the strategic implications of geographic manufacturing and distribution footprints. Supply chain and raw material considerations are woven into the broader market narrative, illustrating how polymer pricing shifts, logistics constraints, and certification requirements influence margin structures and procurement decision-making.
Hydraulic Hose Market
Additionally, the report examines regulatory and standards-driven dynamics that shape product selection in fuel delivery, offshore fluid transfer, and industrial processing environments. By mapping the intersection of compliance mandates, technical performance expectations, and regional procurement practices, the research equips clients with the context required to evaluate supplier qualifications, design specification thresholds, and risk mitigation strategies. The objective is not simply to inform but to operationalize intelligence—transforming market data into executable planning parameters that support procurement, sales strategy, product development, and capital allocation decisions.
Strategic Value for 2026 Decision-Making
The 2026 operating environment demands a more granular understanding of how material cost fluctuations, compliance requirements, application-specific demand cycles, and competitive positioning interact to shape market outcomes. Organizations that approach the oil hose sector with only aggregate market awareness risk misallocating inventory, underestimating regional demand surges, or overcommitting to product lines that face intensifying competitive pressure. Conversely, firms that leverage comprehensive market intelligence can time procurement commitments more effectively, align product portfolios with the highest-value application segments, and differentiate their offerings through compliance readiness, material engineering, and geographic service coverage.
Our Worldwide Oil Hose Market report is designed to serve as a strategic reference point for these decisions. By consolidating historical performance, forward-looking forecasts, competitive analysis, and dynamic industry context into a cohesive framework, the research enables executives to move from reactive monitoring to proactive planning. The insights contained within support scenario modeling, regional prioritization, supplier evaluation, and long-term capacity strategy, providing the analytical foundation required to navigate a market defined by steady growth, material volatility, and evolving technical expectations.
For organizations seeking to deepen their strategic positioning and secure a data-driven advantage in the oil hose sector, the full research report delivers the complete segmentation detail, competitive benchmarking, and dynamic market analysis necessary to inform high-stakes decisions through 2032. The complete intelligence package is available through the source publication, where the full dataset, methodological framework, and extended competitive profiles provide the depth required for precise strategic execution.
For detailed analysis of this topic, please visit the official page: Worldwide Oil Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com