

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fish & Shrimp Feed Additive Market Hits $2,450M in 2025, 5.45% CAGR to 2032

Navigating the Next Wave: Strategic Insights from the Worldwide Fish and Shrimp Feed Additive Market Outlook
The global aquaculture sector stands at a critical inflection point. As wild capture fisheries plateau, the industry's reliance on formulated nutrition has never been greater. Our latest Worldwide Fish and Shrimp Feed Additive Market research delivers a comprehensive blueprint for navigating the years through 2032, translating historical performance and forward-looking indicators into actionable intelligence for executive decision-making.
Worldwide Fish and Shrimp Feed Additive Market
Building upon a robust historical baseline from 2020 to 2025, our analysis captures the market's journey from approximately 1,879 million USD to a projected 2,450 million USD in 2025. This trajectory reflects a compound annual growth rate of 5.45 percent across the forecast horizon of 2026 through 2032. While these aggregate figures provide a crucial macroeconomic compass, the true strategic value of our research lies in its granular dissection of growth vectors, operational bottlenecks, and competitive maneuvers that will separate market leaders from laggards in the coming cycle.
This document serves as an executive prequel to our full report. We outline the structural forces reshaping the nutrition landscape for fish and shrimp, highlight the operational realities that procurement and R&D teams must confront, and preview the analytical frameworks our study provides. For teams seeking exact valuation thresholds, regional penetration curves, and application-specific adoption models, the complete market intelligence is engineered to be calibrated against your internal business models.
The Macro Trajectory: From Recovery to Structural Expansion
The market's expansion since 2020 has been characterized by a blend of post-pandemic supply chain recalibration and sustained demand for high-efficiency aquafeed formulations. By the close of 2025, total market revenue crossed the 2,450 million USD threshold, setting a firm footing for the projected climb toward 3,552 million USD by 2032. This growth is not merely a function of volume; it is increasingly a story of formulation sophistication. Producers are moving beyond commodity inclusion toward precision nutrition that balances growth rates, disease resistance, and environmental compliance.
Our forecast period, spanning 2026 to 2032, maps a landscape where incremental volume gains intersect with intense cost pressures. The revenue progression from 2,588 million USD in 2026 to over 3,100 million USD by 2029 underscores the acceleration of nutrition intensity in farming operations. However, these totals mask a volatile reality at the ingredient level. Structural factors such as raw material price swings for synthetic amino acids, particularly those influenced by energy costs and regulatory environments in major production regions, create persistent margin challenges. Simultaneously, elevated prices for traditional marine ingredients in 2025 have forced feed formulators to rethink substitution ratios and cost-benefit equations.
Understanding how these macroeconomic and supply-side forces interact is the first layer of insight our report provides. Executives will gain clarity on which growth segments are driven by genuine functional necessity versus those buoyed by short-term commodity cycles, allowing for more disciplined capital allocation and hedging strategies.
Competitive Architecture: Global Giants and Regional Powerhouses
The industry's competitive landscape is defined by a concentration of top players that collectively command a meaningful share of total revenue, with the top three entities accounting for approximately 28.4 percent and the top five extending to 42.15 percent. This level of concentration suggests a market where scale, formulation IP, and integration capabilities heavily influence win rates on large-volume contracts. Yet, beneath this handful of leaders lies a diverse array of specialized firms and regionally dominant producers driving distinct value propositions.
Global leaders such as Cargill Incorporated, Nutreco N.V. (operating through its Skretting brand), BioMar Group, Alltech Inc., Archer Daniels Midland Company, dsm-firmenich, Evonik Industries AG, and BASF SE represent the core of the internationalized nutrition and additive supply chain. These firms compete on the strength of comprehensive portfolios, spanning amino acid optimization, enzyme systems, organic trace minerals, carotenoids, and functional health additives. Several have leaned heavily into microbiome management, sustainable ingredient sourcing, and performance-linked certification frameworks to differentiate beyond price.
In parallel, specialized and regionally entrenched players are reshaping localized supply dynamics. Guangdong HAID Group Co., Ltd., Tongwei Co., Ltd., Charoen Pokphand Foods PCL (CP Foods), Aller Aqua Group, and Ridley Corporation Limited demonstrate how integrated aquaculture networks and regional capacity advantages can intensify competition in specific geographies and species segments. Companies such as Adisseo and Kemin Industries further enrich the landscape with targeted methionine delivery, antioxidant technologies, mold inhibition, and gut health solutions that address nuanced formulation challenges.
Recent corporate activity highlights how this competitive board is being actively reconfigured. In September 2025, BioMar Group partnered with Innovafeed and Auchan to commercialize black soldier fly insect meal for Ecuadorian shrimp feed, signaling a deliberate pivot toward alternative protein integration. Earlier that year, in March 2025, the same group secured France's first Aquaculture Stewardship Council Feed Certification for its Nersac mill, reinforcing the strategic weight of sustainability credentials. Even regulatory milestones influence competitive positioning: the November 2024 FDA approval of the first generic florfenicol formulation introduced a new cost and availability axis for controlling mortality in freshwater-reared fish. Our report dissects these moves not as isolated headlines, but as indicators of where margins, differentiation, and barriers to entry are evolving.
Worldwide Shrimp's Disease Treatment Market
Dynamics Shaping Formulation Decisions
The feed additive market does not operate in a vacuum. A confluence of regulatory, sustainability, and ingredient-cost forces dictates what formulators can realistically deploy and what producers are willing to pay. Understanding these dynamics is essential for translating market size data into durable commercial strategy.
Regulatory complexity remains a persistent operational reality. Across United States aquaculture operations, the total annual regulatory cost burden reached 196 million USD in 2023 terms, representing roughly 9 to 30 percent of total annual costs depending on farm scale and compliance profile. This heterogeneity means that additive procurement cannot be standardized across all customer segments; instead, it must align with the specific compliance architecture of each farming operation. In Europe, regulatory frameworks such as EC 1831/2003 govern the safe use of herbal additives, including oregano, rosemary, sage, thyme, and mint, establishing clear boundaries for natural and botanical inclusions within aquaculture nutrition programs.
Simultaneously, sustainability imperatives are reshaping input portfolios. The shift toward alternative proteins, notably insect meal such as black soldier fly biomass and a broader range of plant-based ingredients, is accelerating as operators seek to mitigate fishmeal dependency and reduce environmental impact. This transition is not merely aspirational; it is becoming commercially executable, as demonstrated by recent commercialization efforts linking sustainable ingredient innovation with large-scale retail and farming partnerships.
On the cost side, volatility in synthetic amino acid pricing, driven by energy inputs and regulatory conditions in China, remains a primary determinant of feed additive economics. Coupled with rising fishmeal and fish oil costs in 2025, these pressures elevate production expenses and compress margins across aquafeed formulations. Our analysis isolates the interplay between these cost drivers and additive utilization patterns, helping teams forecast where substitution, formulation efficiency, and premiumization will have the greatest financial impact.
Inside the Research Framework
Our Worldwide Fish and Shrimp Feed Additive Market study is designed as an operational toolkit, not just a high-level overview. The report integrates historical data, forward forecasts, and qualitative intelligence into a modular structure that supports pricing strategy, R&D prioritization, procurement planning, and competitive positioning.
The analytical core begins with a full historical reconstruction from 2020 through 2025, followed by a forecast architecture extending to 2032. This temporal breadth enables users to test growth assumptions against multiple scenarios and identify inflection points where volume momentum diverges from price behavior. All monetary figures are reported in USD millions, allowing direct integration with enterprise financial models.
Beyond the aggregate market curve, the report maps regional demand distributions, providing comparative context for where supply-side investments and formulation priorities are gaining traction. While exact split percentages and absolute regional revenue figures are reserved for the full intelligence package, the strategic takeaway is unmistakable: regional feed ecosystems differ substantially in cost structures, species mix, regulatory intensity, and additive adoption maturity. Our analysis equips teams with the frameworks to evaluate which geographies offer the most favorable risk-return balance for additive portfolios and partnership strategies.
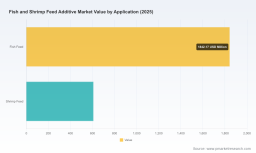
The study also breaks down additive categories and application environments, covering functional classes such as amino acid solutions, vitamin and mineral premixes, enzyme systems, antibiotics and antimicrobials, probiotics and prebiotics, and mycotoxin binders. In parallel, it examines how these inputs are deployed across fish and shrimp feeding programs. The contrast between fish-focused and shrimp-focused nutrition pathways is especially important for product developers and commercial teams: each pathway carries distinct performance requirements, regulatory constraints, and buyer expectations. Instead of presenting raw subgroup allocations, the report emphasizes strategic cross-references—such as where enzyme integration intersects with gut health programs in shrimp diets, or how amino acid precision correlates with feed conversion targets in finfish operations.
To support competitive and operational decision-making, the report includes detailed company profiles spanning major global players and regional leaders. Each profile covers headquarters context, core capabilities, and strategic orientation within aquafeed and additive markets. The competitive section pairs these profiles with a review of recent developments, including partnerships, commercialization milestones, and regulatory approvals, translating them into implications for market share dynamics and innovation races. This allows executives to anticipate where formulation IP, sustainability certification, and supply chain integration will become decisive.
Procurement and supply chain teams will find particular value in the report's treatment of raw material volatility, cost driver mapping, and regulatory burden analysis. By connecting ingredient-level instability to formulation and pricing outcomes, the research helps teams design contracts, hedging postures, and supplier diversification plans that are resilient under stress. Sustainability and compliance teams, meanwhile, can leverage the synthesis of regulatory constraints and alternative ingredient trends to plan ingredient roadmaps that align with evolving certification requirements and buyer expectations.
Conclusion: Converting Intelligence into Action
The Worldwide Fish and Shrimp Feed Additive Market is expanding along a defined growth curve, yet its strategic significance lies in the choices that surround that curve. The market's movement from 2,450 million USD in 2025 toward over 3,550 million USD by 2032 reflects an industry increasingly shaped by precision nutrition, alternative ingredient integration, cost-side volatility, and a regulatory landscape that differs sharply across jurisdictions. Companies that can read these signals early will gain an advantage in formulation design, supplier selection, and market positioning.
Our full market research translates these dynamics into precise revenue trajectories, segment-level comparisons, regional demand distributions, and competitive assessments. It is built for teams that need to move from general market awareness to specific business decisions—whether that means prioritizing a new enzyme system, evaluating a regional expansion, renegotiating an amino acid supply contract, or benchmarking a sustainability claim against market reality.
For decision-makers ready to convert trend awareness into targeted strategy, the complete report provides the granular dashboards, company evaluations, and scenario frameworks needed to de-risk planning through 2032. The executive overview presented here establishes the strategic landscape; the full intelligence package delivers the figures and toolkits required to act on it.
For detailed analysis of this topic, please visit the official page: Worldwide Fish and Shrimp Feed Additive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com