

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tasigna Market to Hit 1,550M in 2025, -11.45% CAGR Through 2032

Navigating the Contraction: Strategic Insights into the Global Tasigna Market Through 2032
The global oncology pharmaceutical landscape is undergoing a profound transformation, driven by patent expirations, the influx of biosimilars and generics, and shifting reimbursement models. Within this complex ecosystem, the market for Tasigna (nilotinib capsules) represents a critical case study in brand lifecycle management and competitive displacement. As we move into 2026, enterprise decision-makers in the pharmaceutical sector, investment firms, and healthcare strategists require granular intelligence to navigate the diminishing revenue trajectories and evolving competitive dynamics of this therapeutic area.
This introduction serves as a precursor to the comprehensive Worldwide Tasigna Market research report recently published by PW Consulting. Our analysis is designed to equip stakeholders with the actionable intelligence necessary to formulate robust strategies amidst a contracting market environment. Below, we outline the strategic value of this study, the key market dynamics shaping the landscape, and the depth of competitive intelligence contained within the full document.
The Macro Trajectory: A Landscape in Decline
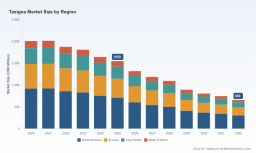
Understanding the overarching revenue trends is the first step in strategic planning. Our research provides a detailed historical reconstruction and forward-looking forecast spanning from 2020 through 2032. The data reveals a consistent downward trajectory in global market revenue, reflecting the significant impact of patent expirations and the subsequent entry of generic competitors.
In the base year of 2025, the global market revenue for Tasigna is recorded at approximately $1,550.0 million USD. Looking back, the market stood at roughly $2,008.15 million in 2020, indicating a measurable erosion of branded market share over the past half-decade. This contraction is projected to accelerate through the forecast period. Our models estimate that by 2026, market revenue will decline to approximately $1,319.11 million, further decreasing to $1,186.37 million in 2027 and reaching $1,094.43 million by 2028.
The long-term outlook suggests a continued compression of the addressable market for the branded product. By 2032, the revenue is forecasted to settle around $660.0 million. This represents a significant reduction from peak historical levels. The Compounded Annual Growth Rate (CAGR) for the forecast period from 2026 to 2032 is calculated at -11.45 percent. This negative growth rate underscores the urgency for stakeholders to understand the underlying drivers of this decline, rather than relying on historical performance metrics that no longer apply.
It is crucial for strategists to recognize that these aggregate figures mask complex regional and therapeutic shifts. While the top-line numbers indicate contraction, the distribution of remaining value across geographies and indications is shifting in nuanced ways that require detailed examination. Our full report dissects these nuances without exposing the specific pricing sensitivities that could impact proprietary strategy, but the headline trend is clear: the era of high-margin branded dominance for this specific molecule is transitioning rapidly toward a volume-driven generic landscape.
Competitive Dynamics and the Generic Inflection Point
The primary driver of the market contraction observed in our data is the alteration of the competitive landscape following key regulatory milestones. The expiration of the compound patent US 7,169,791 on March 17, 2023, marked a definitive turning point. This event, documented in the FDA Orange Book, triggered the approval and launch of generic alternatives, fundamentally altering the supply-demand equilibrium.
Novartis AG, headquartered in Basel, Switzerland, has historically been the manufacturer and worldwide marketer of branded Tasigna. They maintain approval for nilotinib capsules for both adult and pediatric patients with newly diagnosed or imatinib-resistant Philadelphia chromosome-positive chronic myeloid leukemia (Ph+ CML). However, their financial disclosures reflect the market reality. In their full-year 2023 financial report, released in February 2024, Novartis noted that Tasigna net sales stood at $1,182 million, representing a 19 percent decline in USD terms compared to the prior year, directly attributed to generic competition.
Conversely, generic manufacturers have moved swiftly to capture market share. Teva Pharmaceuticals, for instance, received FDA approval and launched the first generic version of Tasigna (nilotinib capsules, 150 mg and 200 mg) in the US in December 2022. This launch preceded the patent expiration, signaling aggressive lifecycle management strategies from generic entrants. The entry of Teva and potentially other competitors creates a price-competitive environment that squeezes branded margins while expanding access through lower-cost options.
Market concentration remains high despite the influx of generics. Our analysis indicates that the top three companies control approximately 92.4 percent of the market revenue, while the top five firms hold around 96.15 percent. This high concentration suggests that while fragmentation is theoretically possible, the market is still heavily influenced by major players managing the transition from branded to generic portfolios. For stakeholders, understanding the specific market share holdings of these key entities is vital for assessing partnership opportunities, competitive threats, and supply chain vulnerabilities.
Therapeutic Indications and Dosage Segmentation
Beyond the macro revenue trends, the utility of Tasigna is segmented by specific clinical indications and dosage strengths. These segments behave differently under pricing pressure and generic substitution. The market is primarily driven by two key patient populations: those with Newly Diagnosed Ph+ CML-CP and those who are Resistant or Intolerant to prior therapies (Ph+ CML-CP).
Worldwide Tasigna Market
Our research quantifies the revenue contribution of each indication segment, revealing which patient populations remain most reliant on the branded formulation versus those where generic substitution is most prevalent. Similarly, the market is divided by dosage strength, specifically 200mg Capsules and 150mg Capsules. The uptake of generics may vary between these strengths due to manufacturing complexities, prescribing habits, and insurance formulary placements.
For pharmaceutical strategists, knowing which indication or dosage strength retains higher brand loyalty is essential for lifecycle extension strategies. For generic entrants, identifying the segments with the highest volume potential dictates production planning. Our full report provides a granular breakdown of these segments, analyzing the volume-to-value ratios without disclosing the sensitive pricing architectures that underpin current market transactions.
Regional Nuances and Reimbursement Landscapes
Geography plays a pivotal role in the longevity of branded pharmaceuticals. The global market is distributed across North America, Europe, Asia Pacific, and the Rest of World. Each region presents unique regulatory hurdles, reimbursement pathways, and generic penetration rates.
In North America, the impact of the US patent expiration and the Medicare Part D reimbursement structure significantly influences market dynamics. Post-patent expiry, Tasigna is reimbursed under Medicare Part D with average sales price-based payments, which alters the economic incentive structure for providers and patients. This reimbursement shift often accelerates the adoption of generic versions if they are listed favorably on formularies.
Europe and Asia Pacific present different challenges and opportunities. Regulatory approval timelines for generics, local manufacturing capabilities, and national health service procurement policies vary widely. The Rest of World segment includes emerging markets where access to cancer therapies is expanding, but pricing pressures remain intense. Our report maps the revenue distribution across these regions, highlighting where the branded product maintains resilience and where generic erosion is most aggressive. However, specific regional revenue figures are reserved for the full download to protect the proprietary modeling techniques used to estimate these values in markets with limited public data transparency.
Risk Factors and Regulatory Considerations
Strategic planning in the oncology space must account for significant risk factors. Tasigna carries FDA black box warnings for QT prolongation, torsades de pointes, and sudden death. These safety profiles impact prescribing behaviors and patient adherence. While these risks are managed through clinical guidelines, they remain a constraint on market expansion and a potential liability consideration for manufacturers.
Furthermore, the regulatory environment is dynamic. Beyond the patent expiry, changes in healthcare policy, drug pricing negotiations, and international trade agreements can alter market access. Our report incorporates a regulatory outlook section that assesses potential upcoming changes that could impact the supply chain or reimbursement status of nilotinib products through 2032.
What the Full Report Delivers
This overview highlights the broad strokes of the Worldwide Tasigna Market, but the strategic depth required for high-stakes decision-making lies in the details. The complete PW Consulting report goes beyond the macro trends summarized here to provide a toolkit for execution.
Key components included in the full study include:
- Historical Data Reconstruction (2020-2025): A validated dataset allowing users to benchmark their internal performance against market averages and identify discrepancies in forecasting assumptions.
- Forecast Modeling (2026-2032): Scenario-based projections that account for variable generic penetration rates, potential new indications, and regulatory shifts, enabling stress-testing of investment hypotheses.
- Segment-Level Intelligence: Detailed analysis of the Newly Diagnosed and Resistant/Intolerant indications, as well as the 150mg and 200mg dosage strengths, to identify pockets of stability within the declining market.
- Competitive Profiling: In-depth profiles of key companies including Novartis AG and major generic entrants, covering their strategic positioning, pipeline adjacencies, and market share trajectories.
- Regional Deep Dives: Country-specific insights within the broader regional buckets, focusing on reimbursement policies, tender processes, and distribution channel dynamics.
- Strategic Recommendations: Actionable guidance for brand managers seeking to defend share, generic manufacturers planning market entry, and investors evaluating exposure to the CML therapeutic area.
The concentration of market revenue among the top three and top five players suggests that competitive intelligence is not merely about tracking sales figures but understanding the strategic moves of a few dominant entities. Our report elucidates the interplay between these players, offering clarity on who is gaining share and at what cost.
Conclusion: The Imperative for Precision Intelligence
The Worldwide Tasigna Market is at a critical juncture. With a forecasted CAGR of -11.45 percent from 2026 to 2032 and total revenue projected to drop from $1,319.11 million in 2026 to $660.0 million by 2032, the margin for error is slim. Stakeholders cannot rely on static models or outdated assumptions about branded drug longevity.
The transition from a protected branded monopoly to a competitive generic market requires a recalibration of strategy. Whether the goal is to maximize the remaining lifecycle of the branded asset, identify the optimal timing for generic launch, or assess the risk exposure of a portfolio heavily weighted toward CML treatments, precise data is non-negotiable.
Worldwide Imbruvica Market
The insights presented here serve as a validation of the market's direction but represent only the surface layer of the intelligence available. To access the full segmentation data, regional revenue breakdowns, detailed competitor analysis, and proprietary forecast models, stakeholders are encouraged to acquire the complete Worldwide Tasigna Market report. In an environment defined by rapid contraction and strategic complexity, the difference between a reactive posture and a proactive strategy lies in the depth of your intelligence.
PW Consulting remains committed to providing the highest caliber of market research to support your strategic objectives. We invite you to explore the full suite of findings to ensure your organization is equipped to navigate the future of the Tasigna market with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Tasigna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com