

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Low-VOC Coating Additives Market to Hit $11,142.59M by 2032 Amid 6.42% CAGR

Navigating the Next Wave: Strategic Intelligence in the Worldwide Low-VOC Coating Additives Market
Unlocking Growth Trajectories and Compliance Imperatives for 2026 and Beyond
The global coatings industry stands at a critical inflection point. Throughout 2020 to 2025, the worldwide low-VOC coating additives market navigated a complex path of recovery, regulatory tightening, and technological maturation, culminating in a comprehensive market valuation of approximately 7,208.15 million USD in the 2025 base year. This trajectory, while marked by periods of contraction such as the modest dip observed in 2023, reflects the resilience of a sector fundamentally realigned toward sustainability. As we project forward through the 2026 to 2032 forecast period, the market is poised for sustained expansion, driven by an anticipated compound annual growth rate of 6.42 percent. This growth is not merely a function of volume but of value, as formulators increasingly seek high-performance additives that reconcile environmental compliance with optimal coating attributes.
Recent historical data illustrates the volatility and eventual upward trajectory of this sector. Starting from 5,280.40 million USD in 2020, the market climbed to 5,849.06 million USD in 2021, followed by 6,231.28 million USD in 2022. The slight contraction to 6,015.38 million USD in 2023 underscored supply chain and raw material challenges, but the rebound to 6,739.56 million USD in 2024 and 7,208.15 million USD in 2025 signaled robust recovery. Forecasts indicate continued momentum, with valuations expected to reach 7,776.63 million USD in 2026, progressing toward 11,142.59 million USD by 2032. These figures represent more than just revenue; they encode the strategic shifts in material science, regulatory compliance costs, and the premium attached to low-emission technologies.
For executives and R&D leaders making decisions in 2026, the challenge lies in parsing these macro indicators into actionable precision. Surface-level data cannot capture the nuanced interplay between regional regulatory divergence, feedstock innovation, and the shifting balance of power among tier-one suppliers. This is where a dedicated, granular market intelligence study becomes indispensable, translating broad trends into targeted strategic leverage.
The Regulatory and Technological Matrix Driving Demand
Compliance is no longer a defensive posture but a primary driver of product architecture and procurement strategy. The regulatory landscape for low-VOC coating additives is increasingly fragmented and stringent, requiring formulators to navigate overlapping jurisdictional mandates while maintaining performance parity with legacy high-VOC systems. In North America, the U.S. EPA amended National VOC Emission Standards for Aerosol Coatings in January 2025, introducing new reactivity factors and expanding the roster of regulated compounds. Simultaneously, California's SCAQMD Rule 1113 continues to set a de facto national benchmark by imposing VOC limits for most architectural coatings under 50 g/L, compelling manufacturers to rewrite formulation protocols and adopt advanced additive packages that deliver flow, stability, and durability without cross-threshold emissions.
In Europe, the EU Deco-Paint Directive 2004/42/EC establishes harmonized VOC limits for decorative paints and varnishes, serving as a foundational compliance framework that continues to shape additive selection across the continent. Standard test methods such as ASTM D6886, which provides the standard procedure for determination of VOC content in waterborne coatings, further operationalize compliance, ensuring that laboratory formulations translate accurately into regulatory submissions and market-ready products. These regulatory pressures are not uniform, however. They interact with regional production capacities, local raw material availability, and varying customer expectations, creating a mosaic of compliance requirements that demands localized strategic insight rather than blanket formulation approaches.
Beyond regulation, the material science foundation of low-VOC additives is undergoing a structural shift. These additives increasingly rely on bio-based or alternative feedstocks such as vegetable oil-derived polyols and biosurfactants to achieve reduced emissions while preserving critical performance characteristics like surface tension control, rheology management, and foam suppression. This transition introduces new considerations around supply chain resilience, lifecycle sustainability metrics, and cost-to-performance ratios. Companies that can secure reliable, scalable access to these advanced feedstocks while demonstrating measurable sustainability advantages will capture disproportionate value in the coming years.
Coating (Painting) Additives Market
Market Architecture: Segmentation, Concentration, and Strategic Positioning
Beneath the aggregate market valuation lies a highly differentiated landscape of additive categories, application domains, and regional performance patterns, each carrying distinct growth drivers and competitive implications. The segmentation structure reveals how demand is distributed across rheology modifiers, wetting and dispersing agents, defoamers, leveling agents, and other specialty additives, reflecting the specific technical requirements of modern low-VOC and waterborne systems. Each category serves a critical function in formulation architecture: rheology modifiers govern viscosity, sag resistance, and application behavior; wetting and dispersing agents ensure pigment stability and color consistency; defoamers and leveling agents address surface defects and finish quality. The relative demand intensity across these categories is shaped by end-use performance standards, regulatory constraints on specific chemistries, and the pace of adoption for next-generation waterborne, high-solids, and UV-curable platforms.
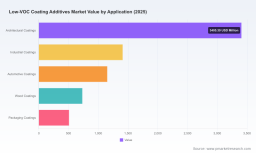
Similarly, application segmentation highlights where low-VOC additive demand is most concentrated and where incremental growth is emerging. Architectural coatings represent a substantial portion of market activity, driven by stringent consumer-facing environmental labels, green building certifications, and residential and commercial retrofit cycles. Industrial coatings contribute significant volume through manufacturing, maintenance, and protective applications where durability, chemical resistance, and process efficiency remain paramount. Automotive coatings, wood coatings, and packaging coatings each introduce distinct formulation challenges and regulatory considerations, from appearance and corrosion protection to substrate compatibility and recycled content integration. Understanding the cross-section of additive type, application, and geography is essential for identifying the niches where formulation innovation can translate into premium positioning and margin expansion.
Market concentration metrics further illuminate the competitive dynamics. With the top three players accounting for approximately 31.4 percent of market revenue and the top five reaching 44.8 percent, the industry exhibits moderate concentration rather than monopolistic dominance. This structure creates a dual environment: established multinationals leverage scale, R&D depth, and global technical service networks to anchor customer relationships, while specialized and regional players compete on formulation agility, niche performance claims, and localized regulatory expertise. For buyers and investors alike, this balance of concentration and fragmentation signals where consolidation risks lie, where partnership opportunities emerge, and where supplier diversification can mitigate single-source vulnerability.
Competitive Landscape and Recent Developments Shaping 2026
The roster of key participants in the worldwide low-VOC coating additives market reflects a blend of chemical conglomerates, specialty additive leaders, and sustainability-focused innovators. BASF SE, headquartered in Ludwigshafen, Germany, maintains a broad portfolio of low-VOC coating additives including defoamers, rheology modifiers, wetting agents, and surface modifiers optimized for waterborne and high-solids systems across architectural, industrial, and automotive coatings. Evonik Industries AG, based in Essen, Germany, provides high-performance low-VOC and zero-VOC additives such as TEGO series defoamers, wetting agents, and dispersants, with a clear focus on bio-based and sustainable options for waterborne coatings. Dow Inc., operating from Midland, Michigan, supplies low-VOC coating additives and acrylic emulsions tailored for eco-friendly waterborne formulations in architectural and industrial applications.
Other major contributors include Eastman Chemical Company in Kingsport, Tennessee, which develops specialty low-VOC additives including coalescents and performance enhancers for compliant coating formulations; Allnex in Frankfurt, Germany, specializing in low-VOC additives and resins for high-performance waterborne, powder, and UV-curable coating systems; and AkzoNobel N.V. in Amsterdam, Netherlands, producing low-VOC additives as part of its specialty chemicals offering for sustainable paint and coating formulations. Elementis plc, London, United Kingdom, offers rheology modifiers and other low-VOC additives for architectural and industrial coatings. Huntsman Corporation, The Woodlands, Texas, provides additives supporting low-VOC formulations in polyurethane and other coating technologies. Seqens, Ecully, France, supplies specialty chemicals including low-VOC coating additives for performance coatings. Arkema, Colombes, France, develops water-based and low-VOC additives and resins for coatings, including recent expansions in acrylic emulsions. LANXESS, Cologne, Germany, offers next-generation low-VOC coalescents and additives such as Koalex MFX for waterborne coatings. ALTANA AG, Wesel, Germany, provides specialized coating additives with low-VOC profiles through its BYK and other brands, and Nouryon, Amsterdam, Netherlands, supplies performance additives for low-VOC coating systems.
Recent corporate activity underscores the velocity of innovation and the competitive significance of timing. In April 2026, LANXESS introduced Koalex MFX, a next-generation multifunctional low-VOC coalescent for waterborne coatings, alongside low-carbon pigment technology at the American Coatings Show 2026. In February 2026, hubergroup Chemicals launched ELARA, a new brand for high-performance additives for coatings and printing inks, with global availability from March 2026 and debut at PAINT INDIA 2026. In March 2026, Dow Inc. expanded its acrylic emulsions portfolio with advanced low-VOC formulations to meet demand for eco-friendly paints and coatings. Earlier, in March 2025, Evonik Industries AG launched mass balanced products TEGO Wet 270 eCO and TEGO Foamex 812 eCO for sustainable, reduced-carbon low-VOC coatings with ISCC PLUS certification. These moves are not isolated product announcements; they are strategic signals about feedstock transition, branding differentiation, and the race to embed sustainability credentials into high-performance additive categories. A comprehensive analysis of such developments reveals the underlying priorities of each competitor, the technological pathways they are betting on, and the market segments they are attempting to redefine.
A Preview of the Intelligence Inside the Report
The full Worldwide Low-VOC Coating Additives Market study is structured to convert macroeconomic and competitive signals into decision-grade intelligence. Beyond the headline market size and growth rate, the report delivers a layered examination of segmentation performance across regions, additive types, and applications, with careful attention to the drivers, restraints, and transitional dynamics shaping each segment. Readers will encounter detailed profiles of leading companies, including headquarters locations, product portfolio orientations, strategic positioning, and recent corporate developments that indicate future market intent. This competitor mapping is paired with an assessment of market concentration and the implications for supplier selection, risk management, and partnership strategy.
The study also integrates a thorough regulatory and raw material context, mapping the key policy instruments, test methods, and feedstock trends that dictate formulation feasibility and cost structures. This background is not provided as a static list but as a dynamic framework for evaluating where compliance costs will rise, where bio-based substitution will accelerate, and which technical bottlenecks are most likely to reward early investment. In addition, the report examines market forces such as pricing elasticity, capacity expansion rationales, technology adoption cycles, and regional demand intensities, giving executives the ability to align product roadmaps, procurement strategies, and market entry decisions with realistic performance trajectories.
Crucially, the analysis is designed to support scenario planning. By connecting historical performance, forward forecasts, regulatory evolution, and competitor behavior, the report equips stakeholders to anticipate not just the direction of the market but the specific inflection points that will determine competitive advantage in 2026 and beyond. Whether the objective is to evaluate supplier reliability, identify white-space application opportunities, benchmark formulation strategies against peer behavior, or assess regional growth potential, the study is built to surface the granularity that high-stakes decisions demand.
Strategic Imperatives for 2026 Decision-Making
For organizations operating in or adjacent to the low-VOC coating additives ecosystem, the 2026 decision environment rewards precision, foresight, and disciplined interpretation of complex data. The market's projected growth trajectory, combined with its regulatory intensity and evolving feedstock base, creates both opportunity and exposure. Companies that rely on aggregate statistics alone risk misjudging segment-level momentum, underestimating compliance-driven formulation shifts, or overlooking competitor moves that redefine category expectations. Conversely, those who ground their strategies in deep segmentation insight, competitor profiling, and regulatory mapping can allocate resources more effectively, differentiate on performance and sustainability, and build supplier and customer relationships that withstand market volatility.
The strategic questions facing leaders in 2026 are pointed: How should additive portfolios be rebalanced to reflect shifting demand across architectural, industrial, automotive, wood, and packaging coatings? Which regional markets offer the most favorable combination of regulatory tailwinds, formulation readiness, and competitive openness? Where should R&D investment be concentrated to secure advantages in rheology modification, dispersion stability, defoaming efficiency, or leveling performance without compromising VOC compliance? How should procurement and supplier diversification strategies account for concentration metrics, raw material transition risks, and the pace of competitor innovation? Answering these questions requires a source of intelligence that goes beyond the headline figures and into the structural logic of the market.
Conclusion
The worldwide low-VOC coating additives market is entering a phase where sustainable compliance and high performance are no longer competing priorities but integrated requirements. The historical trajectory from 2020 through 2025 and the forecast path to 2032 signal a market that is consolidating around advanced, low-emission additive technologies, shaped by stringent regulations, bio-based feedstock adoption, and a competitive field that blends scale with specialization. For enterprises making decisions in 2026, the difference between reactive positioning and proactive advantage lies in access to detailed, current, and strategically framed market intelligence. This study provides that foundation, offering the depth, structure, and competitive context needed to navigate an industry that is being redefined as fast as it is growing.
Worldwide Low-VOC Coating Additives Market
To explore the full segmentation analysis, comprehensive competitor profiles, regulatory and raw material dynamics, and forward-looking scenario frameworks, access the complete Worldwide Low-VOC Coating Additives Market report. The detailed data, regional and application-level insights, and in-depth company evaluations contained in the full publication are designed to support precise, confident decision-making across strategy, R&D, procurement, and commercial planning.
For detailed analysis of this topic, please visit the official page: Worldwide Low-VOC Coating Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com