

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Subsea Well Access and BOP Market to Reach $6.76 Billion by 2032, Growing at 5.4% CAGR

Navigating the Depths: Strategic Intelligence for the Subsea Well Access and BOP System Market (2026-2032)
The offshore oil and gas industry is entering a decisive phase of operational recalibration. As legacy fields mature and frontier basins demand higher technical performance, the infrastructure that enables safe, efficient subsea intervention has become a strategic priority for operators and equipment suppliers alike. Subsea well access and blowout preventer (BOP) systems sit at the intersection of safety assurance, production optimization, and cost discipline. Understanding where this market is headed, who is shaping its trajectory, and what forces are reshaping procurement decisions is no longer optional. It is a prerequisite for capital allocation, vendor selection, and long-cycle project planning.
Our newly released Worldwide Subsea Well Access And BOP System Market study is designed to cut through the noise and deliver actionable intelligence for executives, procurement leaders, and corporate strategy teams. Rather than offering high-level generalizations, this report maps the operational, technological, and competitive realities that will define market behavior through 2032. Below is a structured overview of the landscape, the dynamics driving it, and the strategic frameworks embedded in our analysis.
Market Trajectory and Structural Growth Drivers
The subsea well access and BOP system market has demonstrated consistent expansion over the past half-decade, supported by a combination of deepwater project sanctioning, aging offshore asset intervention needs, and continuous upgrades in pressure control technology. Historical revenue progression from 2020 through 2025 reflects a market that has moved past post-cycle stabilization and entered a more predictable growth rhythm. The forward curve reinforces that momentum: the forecast period from 2026 to 2032 points to a compound annual growth rate of 5.4 percent, with market valuation projected to cross the 6.7 billion USD threshold by the end of the forecast window.
This trajectory is not uniform across all segments, but it is persistent. Several underlying forces explain why. First, operators are increasingly relying on subsea well access solutions to extend field life, reduce surface infrastructure exposure, and execute targeted workovers without incurring the cost and schedule burden of full surface redeployments. Second, BOP system demand remains tied to both new drilling campaigns and the ongoing modernization of installed bases, particularly where regulatory expectations, well complexity, and pressure ratings continue to rise. Third, the shift toward higher-specification equipment in challenging reservoir environments is creating a technical premium that favors suppliers capable of delivering compliant, high-integrity systems at scale.
The convergence of these drivers is producing a market in which demand visibility is improving, but competitive differentiation is becoming more nuanced. Revenue growth alone no longer signals advantage. What matters now is the ability to align system architecture, qualification pathways, service integration, and regional execution capacity with operator priorities.
Segment Architecture and Procurement Realities
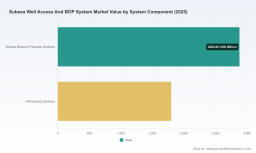
The market is structurally divided across multiple dimensions that influence both pricing and sourcing strategy. On the component side, the ecosystem spans subsea blowout preventer systems and well access systems, each with distinct engineering requirements, service attachments, and deployment cycles. These two categories are complementary but not interchangeable, and procurement teams increasingly evaluate them through different lenses: one anchored in safety-critical pressure control, the other in intervention efficiency, completion flexibility, and well lifecycle management.
Water depth further shapes demand patterns. Shallow water, deepwater, and ultra-deepwater environments each impose different design constraints, installation logistics, and certification expectations. As project portfolios shift toward more technically demanding settings, the addressable market for high-pressure, high-reliability systems expands, while the cost and qualification burden for suppliers rises in parallel. This segmentation matters because it influences not just unit economics, but also lead times, inventory strategy, and the local presence required to support offshore campaigns.
On the materials and manufacturing side, the sector continues to contend with the practical realities of high-strength steel, corrosion-resistant alloys, and precision machining. Pricing dispersion across BOP stacks remains significant, reflecting variations in pressure rating, component complexity, and specification requirements. In practice, this means procurement decisions are becoming more value-driven and less commodity-based. Operators and EPCs are scrutinizing total cost of ownership, availability of life-of-field support, and the credibility of a supplier's qualification track record.
Worldwide Subsea Well Access And BOP System Market
Regulatory, Technical, and Operational Dynamics
Standards and compliance frameworks are increasingly central to commercial speed and competitive positioning. Subsea well access and BOP equipment must satisfy rigorous technical expectations, including API specifications for intervention and pressure control systems. The industry is also moving toward higher-pressure design envelopes, with 20,000 psi-class equipment development gaining relevance for frontier basins where bottom-hole pressures and reservoir conditions push conventional equipment limits. This trend is especially pronounced in areas such as the Gulf of Mexico Paleogene trend, where extreme pressure regimes require equipment that can perform reliably under demanding operational stress.
At the same time, sour-service compatibility remains a non-negotiable consideration for many projects. Material selection and component qualification under NACE MR0175 are essential for mitigating corrosion risks and ensuring long-term integrity in hostile reservoir environments. The practical implication for buyers is that procurement timelines must incorporate testing, validation, and documentation checkpoints that are tightly linked to the operating environment. For suppliers, compliance is both a cost driver and a competitive moat. Companies that can demonstrate consistent adherence to API and material standards while maintaining product robustness are better positioned to win repeat awards and integrated project roles.
Operational trends are also reshaping market expectations. Intervention strategies are evolving toward solutions that reduce rig time, minimize surface footprint, and improve well access flexibility. Riserless and open-water intervention approaches, for example, are gaining traction as operators seek more efficient ways to access subsea wells without the overhead of traditional infrastructure. These service-driven models blur the line between equipment supply and field execution, encouraging partnerships between OEMs, service companies, and operators that can de-risk complex campaigns.
Competitive Landscape and Strategic Positioning
The competitive field includes a diverse set of global players with varying strengths across equipment manufacturing, subsea production architecture, well access intervention packages, and pressure control services. Market concentration reflects a landscape where scale, technical depth, and regional execution capability matter. A core group of leading suppliers commands a substantial share of activity, while a broader tier of specialized firms competes on innovation, niche intervention technologies, and tailored project support.
Among the most prominent participants, several firms have built strong identities around subsea well access and pressure control. Baker Hughes Company continues to be recognized for its subsea well access systems, including installation and workover control systems, subsea wellhead technologies, and pressure control equipment suited to deepwater and ultra-deepwater operations. SLB maintains a broad footprint in subsea pressure control, BOP manufacturing, downhole intervention tools, and well access solutions, including advanced configurations designed for ultra-deepwater pre-salt reservoirs. Aker Solutions ASA brings depth in subsea production systems, well access intervention packages, workover systems, and integrated subsea trees, often paired with well access technologies. TechnipFMC is heavily involved in subsea production systems and integrated well access solutions, including subsea trees and associated intervention equipment for offshore projects.
National Oilwell Varco remains a key manufacturer of subsea BOP systems, drilling equipment, and well access technologies, with a notable focus on high-pressure ram BOPs for deepwater applications. Weatherford International Plc. supplies subsea well access systems, pressure control equipment, and intervention solutions for offshore operations, while Oceaneering International contributes riserless light well intervention services and deepwater intervention capabilities. Dril-Quip Inc. provides subsea wellhead systems, well access equipment, and related drilling and completion technologies. Halliburton Company offers subsea well control solutions, intervention services, and support for BOP and well access systems across drilling and completion activities.
A strong presence is also evident among specialists in well intervention and subsea control technologies. Expro has built recognition around subsea well access systems, including its Solus single shear-and-seal ball valve system designed for intervention and abandonment activities. Proserv supplies subsea well access and control systems, along with intervention and production enhancement technologies. Helix Energy Solutions Group Inc. contributes well intervention vessels and subsea well access services, including riserless and open-water intervention capabilities. Taken together, these players illustrate a market where competitive advantage depends on a blend of product engineering, service integration, and the ability to execute in challenging offshore environments.
Recent activity further signals where strategic focus is intensifying. In February 2026, Expro launched its Solus single high-debris shear-and-seal ball valve system for subsea well access. By consolidating two valves into one, the design aims to reduce complexity, failure points, and costs in intervention and abandonment work, with validation to API Std 17G and NACE MR0175. In September 2025, SLB secured a major contract from Petrobras for completions on up to 35 ultra-deepwater wells in the Atapu/Sépia fields, deploying advanced interval control valves as part of subsea well access and production systems. Earlier, in February 2025, Innovex signed a master service agreement with SLB's OneSubsea as the exclusive supplier of subsea wellhead systems, reinforcing subsea well access infrastructure supply chains.
These developments are not isolated product or contract announcements. They reflect broader shifts toward simplified hardware architectures, expanded ultra-deepwater deployment, and tighter supply-chain alignment between equipment makers and subsea technology partners. For operators and investors, the pattern suggests that suppliers with integrated capabilities, validated high-pressure designs, and credible intervention portfolios are likely to capture disproportionate value as projects become more technically complex.
Strategic Imperatives for 2026 Decision-Making
As market participants plan for 2026 and beyond, several strategic questions deserve structured attention. For operators, the priority is no longer simply securing equipment availability. It is optimizing the balance between safety assurance, intervention flexibility, and lifecycle cost. That requires clearer visibility into which suppliers can deliver high-specification systems on time, support them throughout the field life, and adapt to evolving operational models.
For equipment manufacturers and service providers, the opportunities lie in differentiation through reliability, qualification readiness, and integration. Companies that can demonstrate compliant performance in high-pressure and sour-service environments, while streamlining hardware complexity and supporting faster intervention campaigns, will be better placed to win repeat business and long-term partnerships. At the same time, firms must manage exposure to material costs, lead-time variability, and the execution demands of deepwater and ultra-deepwater projects.
For investors and corporate planners, market concentration and competitive dynamism raise important risk and opportunity considerations. A market with meaningful concentration can offer stability and scale advantages, but it also demands careful analysis of supplier dependency, innovation pace, and regional execution capacity. Understanding how key players are positioning themselves across BOP systems, well access systems, and intervention services is essential for evaluating supply continuity and pricing resilience.
Our report is built to support these decisions with a disciplined, evidence-based framework. It does not simply describe what is happening; it structures the information in ways that help teams compare options, anticipate bottlenecks, and align procurement or investment strategies with market reality.
What the Report Delivers
This study provides a comprehensive analytical foundation for executives who need more than headline figures. It combines market sizing and growth projections with detailed segmentation analysis across regions, system components, and water depth categories. It examines the competitive landscape with company-level profiles, recent contract activity, product launches, and strategic agreements that reveal how participating firms are shaping the market. It also contextualizes technical and regulatory dynamics, including API and material compliance expectations, high-pressure equipment development, and emerging intervention approaches.
Worldwide Subsea Sensors Market
Beyond macro trends, the report focuses on the operational implications of market evolution. It explores how demand is distributed across shallow water, deepwater, and ultra-deepwater settings, how component-level revenue splits inform procurement and capacity planning, and how recent industry activity reflects shifting priorities in subsea well access and pressure control. Readers will find practical context for evaluating supplier capabilities, anticipating technology trends, and aligning portfolio strategy with the realities of offshore deployment.
The value of this research lies in its ability to connect high-level market direction with the decision-level detail that strategy teams need. Market sizing establishes the scale and pace of opportunity. Segmentation reveals where demand is concentrated and how it is likely to shift. Competitive intelligence clarifies who is winning work, what technologies are gaining traction, and where partnerships are being forged. Technical and regulatory context ensures that growth narratives are grounded in the practical constraints that shape execution.
Conclusion
The Worldwide Subsea Well Access And BOP System Market is moving into a phase where strategic agility will separate participants that merely survive from those that capture durable advantage. Growth is expected to continue at a steady pace, but the real differentiators will be technical credibility, compliance reliability, service integration, and the capacity to support increasingly demanding offshore environments. For organizations making decisions in 2026, the ability to read these signals accurately will influence procurement strategy, partnership selection, and long-term positioning.
This report is designed to provide that clarity. It offers the intelligence needed to navigate a market that is expanding in value, intensifying in technical complexity, and becoming more selective in how value is awarded. The full study delivers the depth, segmentation, and competitive analysis required to turn market awareness into informed action.
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Well Access And BOP System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com