

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Global High Purity Lignin Market to Reach $69.18M by 2032, 7.21% CAGR
By pmarketresearch, 2026-09-16
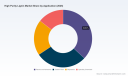
Global High Purity Lignin Market Outlook: Strategic Intelligence for the 2026 Business Cycle
The transition from fossil-based feedstocks to renewable biopolymers represents one of the most significant structural shifts in the global chemicals and materials landscape. As we move through 2026, high purity lignin has emerged as a critical enabler of this transition, offering viable pathways for decarbonization across adhesives, composites, carbon materials, and specialty chemicals. Our latest Worldwide High Purity Lignin Market research provides decision-makers with a rigorous, forward-looking intelligence framework designed to navigate capacity deployment, competitive positioning, and application commercialization over the 2026 to 2032 horizon.
For executives, investors, and strategy teams, the imperative is clear: market timing, technology selection, and partnership strategy will dictate who captures value in a rapidly maturing bio-based supply chain. This report delivers the granular market architecture, technology roadmaps, and competitive scaffolding required to make those decisions with confidence.
Market Trajectory and Growth Architecture
The global high purity lignin market has demonstrated sustained expansion over the past half-decade, driven by accelerating substitution demand, regulatory tailwinds, and scale-up activity across pulp-integrated and standalone biorefinery operations. Historical performance from 2020 through 2025 reflects a consistent upward trajectory, with total market revenue climbing from approximately 31.25 million USD to 42.5 million USD. The base year of 2025 anchors a forecast period that extends through 2032, during which the market is projected to expand at a compound annual growth rate of 7.21 percent.
This growth profile is not merely a function of volume scaling; it reflects a structural revaluation of lignin from a low-value pulp byproduct to a high-value, specification-driven biopolymer. Forecast trajectories through 2032 indicate continued appreciation, with revenue levels expected to surpass 69 million USD by the close of the forecast window. The compounding nature of this expansion underscores the importance of early-mover positioning, capacity alignment, and application-specific qualification timelines that can span multiple years in regulated end markets.
Several macro forces are reinforcing this trajectory. Stringent carbon policies and circular-economy mandates across Europe are accelerating lignin valorization through bioeconomy funding mechanisms and green public procurement frameworks. Simultaneously, regulatory pressure on traditional chemical inputs, including chrome restrictions in drilling fluids and expanding disclosure requirements on embodied carbon, is driving end-users to qualify lignin-based alternatives in construction and oilfield service applications. These demand-side catalysts are interacting with supply-side developments in separation technology, purification capability, and integrated mill economics to reshape the competitive landscape.
Segmentation Logic and Application Pathways
Understanding the market requires a clear grasp of how value is distributed across type, application, and geography. The report dissects the high purity lignin landscape across multiple segmentation dimensions, mapping revenue contribution, growth intensity, and adoption dynamics for each node without exposing the precise percentage splits that drive commercial negotiation leverage.
Lignin Type Landscape
The market encompasses distinct lignin categories, each with unique processing routes, purity profiles, and end-market suitability. Organosolv-derived lignin dominates value contribution, reflecting its broader compatibility with higher-specification applications and its alignment with specialty chemical and polymer formulation requirements. Kraft lignin represents the second major value pillar, benefiting from established black-liquor recovery infrastructure, large-scale global availability, and growing deployment in resin, composite, and carbon material pathways. Soda lignin occupies a smaller but strategically relevant position, serving niche formulation needs where specific solubility or reactivity characteristics are required.
Global production capacity dynamics further shape type-level competition. Kraft lignin availability has expanded substantially, with global production capacity reaching significant kiloton thresholds by 2023, reinforcing its role as a foundational feedstock for scale-driven substitution. Yet high purity requirements, consistency standards, and downstream qualification processes mean that capacity alone does not translate directly into market share. Purification capability, lot-to-lot consistency, and technical service support increasingly determine commercial outcomes.
Application End-Use Dynamics
Demand is distributed across several high-growth application clusters, each with distinct qualification timelines, performance thresholds, and substitution economics. Resins and adhesives represent the largest application value pool, leveraging lignin as a renewable phenolic substitute and performance binder in engineered formulations. Carbon fiber and carbon material applications constitute a high-value secondary cluster, where lignin-derived precursors offer cost and sustainability advantages relative to conventional PAN-based routes, particularly as hard carbon and anode material development expands into next-generation battery chemistries. Bioplastics and polymer compounds form a growing segment, supported by patented transformation technologies that convert lignin into renewable thermoplastic and biomaterial grades. Specialty chemicals round out the application matrix, encompassing dispersants, binders, and functional additives where lignin's molecular architecture provides differentiated performance.
Geographic Distribution
Regional revenue distribution reflects the interplay of regulatory intensity, pulp and paper infrastructure density, and end-market demand maturity. Europe leads in value contribution, supported by ambitious bioeconomy policy frameworks, strong circular-economy procurement signals, and a dense concentration of technology developers and integrated producers. North America follows as a substantial value center, anchored by large-scale pulp operations, expanding lignin recovery investments, and growing qualification activity in construction, composites, and industrial applications. Asia Pacific and the Rest of World regions contribute incrementally but are gaining momentum as regional substitution demand, local formulation capabilities, and import-dependent supply chains evolve.
The report provides a complete geographic breakdown with market sizing, growth rates, and regional competitive mapping, but withholds granular regional percentage splits in this preview to preserve the analytical edge of the full dataset. Decision-makers requiring precise regional revenue allocations, localized demand forecasts, and country-level policy impact assessments will find those details within the complete report.
Competitive Landscape and Strategic Positioning
Market concentration is moderate, with the top three firms collectively capturing a significant share of total revenue and the top five firms extending that footprint further. This concentration profile signals a market in which scale, technology differentiation, and integrated supply relationships matter, but where specialized niche players and regional participants can still build defensible positions through purity, formulation expertise, and application-specific service models.
The competitive set includes globally established pulp-integrated producers, specialized lignin refiners, and technology-driven biomaterials developers. Borregaard brings over nine decades of experience in lignin-based biopolymers and lignosulfonates, delivering tailor-made high-purity solutions spanning dispersants, binders, and renewable alternatives to fossil chemicals. Stora Enso operates as the largest kraft lignin producer, leveraging its Lineo family of high-purity kraft lignin grades and NeoLigno binders for adhesives, composites, and carbon materials through its LignoBoost technology platform. UPM Biochemicals emphasizes consistent quality and formulation support for sustainable applications across resins, adhesives, binders, and polymer compounds. Mercer International produces high-quality lignin using the LignoBoost process across industrial applications, underpinned by sustainable forestry certifications that matter increasingly in procurement evaluations.
Regional specialization also shapes the field. Nippon Paper Industries stands as the only lignin manufacturer in Japan, offering a broad product range including SAN X, VANILLEX, and PEARLLEX grades for industrial uses. Domtar Corporation supplies high-purity kraft lignin under its BioChoice label from its Plymouth mill using LignoBoost, with a focus on sustainable lignin for binders and composites. West Fraser provides lignin products for bio-composites and binding agents derived from its pulp operations. Metsä Group develops modified lignin products such as Metsä LigO for concrete and other applications, expanding the scope of lignin-derived functional materials. Pure Lignin Environmental Technology Ltd. produces high-grade native-form lignin with purity levels reaching extremely high thresholds from biomass processing, targeting applications that demand specification-grade consistency. Lignin Industries develops lignin-based thermoplastics and biomaterials using patented technology to transform lignin into renewable plastics, illustrating the broader innovation curve beyond conventional extraction and purification.
Recent corporate activity highlights the pace of commercialization and partnership formation. In early 2025, LignEasy Oy shipped its first large-scale big-bag sample of a lignin-based product, signaling a transition from pilot-scale validation to early commercial distribution. Late 2024 saw Metsä Fibre develop a new lignin product at its Äänekoski demo plant for concrete applications aimed at replacing fossil-based chemicals. Mid-2024 brought a strategic partnership between Stora Enso and Altris to adapt lignin-derived hard carbon for anode material in sodium-ion batteries, expanding the addressable market into energy storage materials. Earlier in 2024, Lignin Industries raised over 2.2 million USD to strengthen its market position, expand its team, and increase manufacturing capacity for lignin-based bioplastics. These moves illustrate how the competitive field is being reshaped not only by production scale but by application innovation, partnership ecosystems, and targeted capital deployment.
Report Content and Operational Utility
The full research deliverable is structured to support concrete strategic workflows rather than abstract market commentary. It provides a comprehensive market sizing framework spanning historical years and the full 2026 to 2032 forecast period, with clear delineation between base-year validation and forward projections. Segmentation analysis covers type, application, and region, enabling users to isolate growth pools, assess substitution readiness, and identify where qualification cycles may create near-term opportunity or near-term risk.
Competitive profiling extends beyond static company summaries to include capacity positioning, technology platforms, product grade architecture, and strategic development activity. Industry context modules examine raw material availability, regulatory drivers, and processing economics, giving strategists a multi-variable lens on supply feasibility and demand durability. The report also integrates recent corporate developments, product launches, partnerships, and funding events, allowing readers to map the velocity of commercialization and detect emerging competitive threats or collaboration opportunities before they become widely priced into the market.
For commercial teams, the analysis supports application prioritization, pricing strategy, and customer qualification planning. For corporate development and investors, it offers a structured view of concentration dynamics, technology risk, and capacity expansion signaling. For sustainability and procurement functions, it provides a reference point for evaluating lignin-based alternatives against regulatory requirements, embodied carbon targets, and performance specifications.
Strategic Implications for 2026 Decision-Making
The 2026 decision environment demands a disciplined approach to market entry, partnership selection, and capacity alignment. Several strategic implications stand out.
First, value capture will increasingly attach to purity, consistency, and application-specific technical service rather than bulk availability alone. As end-users qualify lignin-based formulations in performance-sensitive markets, suppliers that can demonstrate lot-to-lot reliability, formulation support, and regulatory compliance will command stronger positioning.
Worldwide High Purity Lignin Market
Lignin Products Market
Second, partnership architecture is becoming a defining competitive variable. Collaborations that link lignin producers with downstream formulators, battery material developers, concrete additive specialists, and bioplastics manufacturers are accelerating qualification timelines and expanding addressable markets. Organizations that build or join these ecosystems early will be better positioned to shape specification standards and secure offtake alignment.
Third, regional policy intensity matters. Europe's regulatory and funding environment continues to support lignin valorization, while disclosure requirements and material substitution mandates in construction, oilfield, and industrial applications are expanding demand signals globally. Strategy teams should factor regional policy trajectories into capacity planning, go-to-market sequencing, and supplier selection.
Fourth, the market's moderate concentration profile means that both scaled incumbents and focused specialists can succeed, but via different playbooks. Incumbents leverage integrated mill economics, established recovery infrastructure, and broad grade portfolios. Specialists compete on purity ceilings, proprietary transformation technologies, and targeted application expertise. Understanding which model aligns with a given application pathway is essential for both procurement and investment decisions.
Conclusion
The high purity lignin market is transitioning from early-stage substitution interest to a more structured, specification-driven commercial landscape. The convergence of regulatory pressure, application innovation, and capacity expansion is creating a window in which informed strategic choices can materially affect competitive outcomes over the remainder of the decade. Our Worldwide High Purity Lignin Market research is designed to provide the depth, segmentation clarity, and competitive intelligence required to operate with precision in that environment.
The preview above highlights the structural framework, growth trajectory, segmentation logic, and competitive dynamics that define the market. The complete report delivers the full quantitative architecture, regional and application-level breakdowns, detailed company profiles, and forward-looking scenario analysis necessary for decisive 2026 planning. Readers seeking the complete dataset, exact segmentation values, and the full analytic toolkit are encouraged to access the full study for comprehensive market intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide High Purity Lignin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Facial Rejuvenation Market Hits $32.5B in 2025, Projected to Reach $57.5B by 2032 at 8.5% CAGR
By pmarketresearch, 2026-09-16
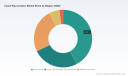
Navigating the Global Facial Rejuvenation Market: Strategic Intelligence for Leadership Decision-Making in 2026
The worldwide facial rejuvenation industry is entering a pivotal growth phase, driven by sustained demand for minimally invasive procedures, continuous innovation in injectables and energy-based platforms, and expanding access across both mature and emerging healthcare ecosystems. As organizations plan capital allocation, pipeline development, and competitive positioning for 2026, the need for calibrated, forward-looking intelligence has never been greater. PW Consulting’s latest research on the Worldwide Facial Rejuvenation Market is designed to equip boards, commercial leaders, and R&D strategists with precisely that capability: a structured, evidence-based view of where value is being created, how competitive dynamics are shifting, and what operational realities will shape execution over the 2026 to 2032 horizon.
Beauty Devices Market
This report does not merely track historical performance; it constructs an actionable strategic map. It integrates macroeconomic momentum, procedural adoption patterns, regulatory evolution, and competitive behavior into a coherent framework that decision-makers can use to stress-test assumptions, prioritize investments, and anticipate inflection points. Below, we outline the analytical architecture of the study and explain why it is essential reading for executives operating in aesthetic medicine, medical devices, injectables, and adjacent health-and-wellness segments.
Macro Trajectory and Market Architecture: Why the Numbers Matter Strategically
The global facial rejuvenation market established a clear upward trajectory between 2020 and 2025, with revenue advances reflecting both pent-up procedural demand and the maturation of treatment ecosystems in multiple regions. From a base-year starting point of USD 32,500 million in 2025, the sector is positioned to extend its growth into the 2026 to 2032 forecast period at a compound annual growth rate of approximately 8.5 percent. Over the course of that window, total market revenue advances toward a significantly larger scale, signaling durable expansion rather than a short-cycle uplift.
For leadership teams, these figures are more than directional indicators. They frame the scale of opportunity, the pace at which share can shift, and the timing at which new entrants or product extensions can realistically influence category economics. Our analysis translates this trajectory into strategic implications: where demand is structurally expanding, where growth is increasingly competitive, and where operational or regulatory friction may moderate realized returns even when procedural volume remains strong.
Equally important, the report examines how value is distributed across product categories and end-user channels without reducing the market to a static snapshot. Botulinum toxin, dermal fillers, energy-based devices, chemical peels, and microdermabrasion and related approaches each follow different adoption curves, reimbursement realities, and practitioner preferences. This heterogeneity matters for portfolio strategy. A product or device positioned in one segment may face a substantially different competitive and commercial environment than a comparable offering in another, even within the same geography or clinical setting. Our segmentation analysis highlights those distinctions and shows how growth leadership is migrating as patient expectations, clinician training, and technology accessibility continue to evolve.
Worldwide Facial Rejuvenation Market
The same logic applies to end-user demand patterns. Dermatology clinics, medical spas, and hospitals each represent distinct commercial environments with different purchasing behaviors, service models, patient demographics, and regulatory considerations. Understanding how these channels interact, where they compete for procedures, and where they complement one another is essential for go-to-market planning, distribution strategy, and service-line development. The report maps these relationships and identifies the demand nodes that matter most for both established operators and new entrants.
From Insight to Execution: What the Report Delivers
PW Consulting’s facial rejuvenation study is built for practitioners of strategy, not simply for readers of summaries. It provides a comprehensive decision-support toolkit that covers the operational, commercial, and competitive dimensions most relevant to 2026 planning. Key components include:
- An integrated view of historical performance from 2020 through 2025, combined with a detailed forecast structure for 2026 to 2032, allowing leadership teams to evaluate momentum, cyclicality, and segment-specific growth potential.
- A granular segmentation framework that breaks the market down by product type and by end-user setting, enabling more precise scenario planning, pricing strategy, and channel prioritization.
- A regional perspective that identifies where demand is concentrated, where procedural ecosystems are maturing, and where growth conditions are changing most rapidly, without reducing complex local dynamics to oversimplified rankings.
- A competitive landscape assessment that profiles the leading companies shaping categories, illustrates how portfolios are constructed, and explains which strategic moves are likely to influence the next phase of consolidation, differentiation, and capability-building.
- A practical set of market dynamics, covering regulation, reimbursement, safety oversight, practitioner qualification, and technology adoption, all of which directly affect commercialization planning and long-term category viability.
Beyond data presentation, the report is organized to answer the questions that executives actually face. Which product categories and end-user channels will generate the most durable revenue growth? Where should organizations invest in training, clinical evidence, and practitioner engagement? How do regulatory expectations and safety communications alter device and injectable strategy? Which competitive behaviors suggest that share shifts will be determined by innovation, access, and service quality rather than by scale alone? The study provides analytical depth on each of these themes so that leaders can build plans that are resilient to uncertainty and responsive to structural opportunity.
Competitive Landscape: Portfolio Logic, M&A, and Innovation Posture
The facial rejuvenation arena is shaped by companies that compete across injectables, energy-based devices, and related aesthetic platforms. Rather than treating competitors as isolated brand names, the report examines them as strategic actors with differentiated assets, geographic footprints, clinical evidence bases, and commercial architectures. This perspective is critical because competitive advantage in this market often depends on more than product performance alone. It also depends on training access, clinical credibility, indication expansion, distribution strength, and the ability to align product portfolios with patient and practitioner expectations.
Several major players illustrate the diversity of strategic positioning in the category. AbbVie, through its Allergan Aesthetics franchise, maintains a prominent role in neuromodulators and hyaluronic acid dermal fillers, supported by established brand recognition and broad practitioner familiarity. Galderma competes with a portfolio spanning hyaluronic acid fillers, biostimulatory options, and neuromodulators, while also pursuing indication development and regulatory milestones that extend the clinical utility of its platforms. Merz Pharma contributes neuromodulators and a range of filler technologies aimed at wrinkle reduction and volume restoration. Revance Therapeutics, following its acquisition by Crown Laboratories, represents a notable example of portfolio consolidation, bringing a longer-duration neuromodulator platform and resilient hyaluronic acid fillers into a broader skin-health and aesthetics ecosystem.
On the device side, the market includes a broad field of companies developing lasers, intense pulsed light systems, radiofrequency platforms, and microneedling-based technologies. Lumenis, Cynosure, Candela, Cutera, Alma Lasers, Sciton, Lutronic, and Hologic through its Solta Medical franchise all participate in the energy-based device segment with platforms designed for skin resurfacing, tightening, and photorejuvenation. Their competitive positioning depends not only on hardware performance, but also on procedural efficiency, treatment customization, clinical support, and integration into service workflows across dermatology and medical spa settings.
Additional participants broaden the competitive fabric further. Bausch Health, Anika Therapeutics, Contura International, Suneva Medical, Teoxane, and Sinclair Pharma each contribute products or technologies relevant to injectables, regenerative approaches, and facial contouring, reinforcing the market’s multi-layered structure. For strategists, this landscape conveys an important message: leadership is contested across multiple fronts, and competitive advantage increasingly arises from portfolio breadth, evidence generation, and the ability to support safe, effective, and consistent treatment delivery.
Recent industry activity underscores how quickly these strategic dynamics are evolving. In early 2026, Galderma secured FDA approval for Restylane Contour for temple hollowing correction in patients over 21, expanding the indication scope for volume restoration and facial balance. Around the same time, the company presented new data on Sculptra’s regenerative properties for face and body at IMCAS 2026, alongside updates on Restylane products and the Relfydess neuromodulator, while also advancing EU MDR certification expansion to additional body areas. These moves highlight how clinical data, regulatory positioning, and indication breadth can reinforce portfolio value. Elsewhere, AbbVie opened its third state-of-the-art AMI training center in Austin, signaling continued investment in practitioner education and service quality for facial rejuvenation procedures. In a major consolidation move, Crown Laboratories completed the acquisition of Revance Therapeutics for USD 924 million, integrating the DAXXIFY neuromodulator and RHA filler platforms with its skin health portfolio to strengthen facial aesthetics offerings. More recently, Dermalogica launched its PRO Pen Microneedling System, marking its first FDA-cleared medical aesthetic device for improving facial acne scars and illustrating how facial rejuvenation and skin-quality technologies continue to converge.
Market Dynamics That Will Shape Strategy in 2026
Commercial strategy in facial rejuvenation cannot be separated from the evolving regulatory and operational environment. The report devotes substantial attention to dynamics that influence demand, product development, device selection, and market access, because these forces often determine whether growth assumptions hold in practice.
Regulatory oversight remains a central theme. The FDA’s October 2025 safety communication drew attention to potential risks such as burns, scarring, and nerve injuries linked to certain uses of radiofrequency microneedling devices, especially when unregulated devices or unlicensed operators are involved. For device manufacturers, clinical educators, and service providers, this type of guidance has direct implications for training, product positioning, clinic protocols, and risk communication. It also reinforces why procedural safety and practitioner qualification are not peripheral concerns but core elements of credible market expansion. In parallel, ongoing compliance requirements under the Modernization of Cosmetics Regulation Act continue to shape obligations for cosmetic product facilities, including biennial registration and listing, updated FDA portal functionality, and advancing GMP-related expectations across 2025 and 2026.
Reimbursement and payment dynamics add another layer of strategic realism. Most facial rejuvenation procedures using neuromodulators, dermal fillers, and laser resurfacing are generally treated as elective cosmetic treatments and are not covered by public or private health insurance, with limited exceptions for medically necessary applications such as chronic migraine therapy. This reality influences patient acquisition models, pricing strategies, financing options, and the broader economics of service delivery. It also means that demand resilience can be sensitive to consumer discretionary spending, perceived treatment value, and the credibility of outcomes. Leaders who plan growth must therefore account for both clinical adoption and the financial behaviors of the end patient.
Licensing and procedural oversight are also evolving in key jurisdictions. In the UK, governments in England and Scotland have advanced consultations and proposed risk-based licensing systems for non-surgical cosmetic procedures, including potential minimum age requirements and tiered restrictions, with additional consultations expected in 2026. These developments illustrate how policy can reshape operating conditions, practitioner standards, and market access over time. Combined with the longstanding expectation that many injectable and filler procedures require administration by licensed physicians or properly qualified practitioners under FDA and local medical board oversight, the message is clear: commercial success in this space depends on disciplined clinical governance, credible training, and operational consistency.
How Leaders Should Use This Research
The strategic value of this study lies in its ability to convert complex market information into decision-ready insight. For portfolio and R&D teams, the segmentation and category analysis provide a foundation for prioritizing development efforts, evaluating indication opportunities, and understanding where clinical differentiation can translate into commercial advantage. For commercial and distribution leaders, the end-user and regional analyses support channel strategy, partnership evaluation, and training investment decisions. For competitive intelligence and corporate development teams, the company profiles and recent market moves create a basis for benchmarking, positioning, and assessing consolidation or partnership opportunities.
Equally important, the report’s treatment of regulation, reimbursement, and safety dynamics helps organizations test their growth plans against operational reality. A compelling product or device concept can still face headwinds if training, compliance, clinician confidence, or patient trust are not addressed systematically. By integrating these considerations into the market narrative, the research enables leaders to build strategies that are not only ambitious but also executable.
Next Steps
The Worldwide Facial Rejuvenation Market is expanding within a landscape defined by technological innovation, evolving regulation, contestable competitive positions, and changing patient expectations. Organizations that want to act with confidence in 2026 need more than top-line figures; they need a rigorous, structured view of how demand is formed, how value is distributed, and how strategic moves by peers are reshaping the category. PW Consulting’s full market research delivers that depth, with comprehensive segmentation, forecast detail, competitive profiling, and regulatory and operational context designed for executive use.
To explore the complete dataset, segment-level forecasts, regional breakdowns, and competitive analysis in full, we invite you to access the source report and accompanying materials. The detailed intelligence within the study is intended to support strategic planning, investment prioritization, and market-entry evaluation with the precision required for high-stakes decision-making in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Facial Rejuvenation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global MS Polymer Market to Reach $9.28B by 2032, 7% CAGR
By pmarketresearch, 2026-09-16
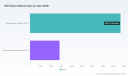
Global MS Polymer Market Outlook 2026: Strategic Intelligence for High-Growth Decision-Making
The worldwide MS Polymer market stands at a critical inflection point as enterprises navigate tightening environmental regulations, supply chain reconfiguration, and accelerating demand for high-performance hybrid sealants and adhesives. Our latest Worldwide MS Polymer Market research delivers a comprehensive, data-grounded strategic blueprint designed specifically to empower executive decision-makers, product developers, and commercial leaders operating across 2026 and the forecast window extending through 2032. By synthesizing historical performance from 2020 through the base year of 2025 with rigorous forward-looking modeling, this study equips organizations with the analytical clarity required to allocate capital efficiently, identify asymmetric growth opportunities, and outmaneuver competitors in a rapidly consolidating landscape.
Market Trajectory & Macro Growth Framework
Historical trajectory analysis reveals a resilient, structurally expanding market that has consistently outperformed baseline expectations. Revenue expanded from approximately 4.1 billion USD in 2020 to nearly 5.8 billion USD by 2025, reflecting sustained commercial momentum across multiple downstream verticals. The forecast period projects continued upward progression, with the global market size anticipated to surpass 6.1 billion USD in 2026 and advance toward a 9.3 billion USD valuation by 2032. This expansion is anchored by a composite CAGR of 7.0 percent, a growth rate that signals durable institutional demand rather than transient cyclical spikes.
Several structural forces underpin this trajectory. The global transition toward isocyanate-free, low-VOC, and solvent-free formulation architectures has fundamentally reshaped procurement standards across construction, transportation, and industrial manufacturing. MS polymer hybrid technologies, engineered through silyl-terminated polyether and silyl-terminated polyurethane chemistries, deliver the necessary balance of elastic recovery, multi-substrate adhesion, and environmental compliance. Simultaneously, capacity expansion initiatives across major production hubs are aligning with infrastructural modernization programs in Europe and Asia Pacific, reinforcing supply-side readiness. Yet, despite favorable demand signals, production economics remain sensitive to raw material price volatility, particularly for polyurethane and silicone precursors. Organizations that integrate granular cost-structure modeling and regional capacity mapping into their strategic planning will secure meaningful margin protection as input cost dynamics continue to fluctuate.
Deep-Dive Report Architecture: Operational Intelligence for Commercial Execution
This research was structured from the ground up to translate macro-level market intelligence into actionable commercial strategy. Rather than delivering a high-level snapshot, the report functions as an operational playbook. Stakeholders will gain access to meticulously disaggregated market sizing across product types, application verticals, and geographic territories, all calibrated to a consistent revenue framework denominated in million USD. The analytical architecture enables teams to isolate high-velocity demand pockets, evaluate regional penetration thresholds, and benchmark internal performance against market-wide growth benchmarks.
The study encompasses a full-spectrum competitive mapping exercise, profiling leadership positions, capacity footprints, regional formulation strategies, and go-to-market differentiation tactics. Decision-makers will find detailed assessments of how incumbent players are leveraging proprietary base resin technologies, hybrid adhesive platforms, and specialty chemical supply chains to defend market share while expanding into adjacent application categories. The report also evaluates strategic capacity deployment trends, including facility modernization, tonnage increases, and geographic supply chain localization initiatives that are actively reshaping competitive barriers to entry.
Beyond competitive benchmarking, the research integrates forward-looking regulatory and compliance analysis. As indoor air quality mandates, emissions standards, and sustainability procurement requirements continue to tighten across construction and industrial sectors, the ability to align product portfolios with next-generation environmental specifications has become a decisive commercial advantage. This study maps the regulatory trajectory and identifies formulation pathways that balance performance integrity with compliance readiness, enabling R&D and commercial teams to prioritize development roadmaps with confidence.
Supply chain resilience and raw material procurement represent additional focal points. The report dissects the underlying material architecture of MS polymer production, examining how backbone chemistry, silane end-group functionalization, and precursor sourcing strategies influence manufacturing economics and end-product performance. By contextualizing raw material dynamics within broader market pricing structures, the study provides procurement and manufacturing leaders with the analytical framework required to optimize input contracts, evaluate supplier diversification strategies, and anticipate cost dislocations before they impact margin profiles.
Competitive Landscape: Positioning, Differentiation, and Strategic Consolidation
The MS polymer competitive arena is defined by a concentrated yet dynamic roster of globally active producers and specialty chemical formulators. Market concentration indicators reflect a moderately consolidated environment, with leading participants leveraging proprietary resin architectures, established distribution networks, and cross-vertical application expertise to sustain commercial leadership. The strategic posture of these organizations varies considerably, ranging from vertically integrated resin originators to hybrid adhesive specialists and broad-platform industrial suppliers.
Kaneka Corporation maintains a differentiated position as the originator and leading global producer of MS polymer base resin technologies, with manufacturing operations spanning Japan, Belgium, the United States, and Malaysia. Its emphasis on high-performance silyl-terminated polyether chemistry has reinforced its role as a foundational supplier across construction, industrial, transportation, and DIY application channels. Sika AG commands a strong footprint as a major global supplier of MS polymer-based hybrid sealants and adhesives, prioritizing low-VOC elastic bonding solutions tailored to construction and industrial requirements. Henkel AG & Co. KGaA extends its portfolio through well-established consumer and professional brands, emphasizing region-specific formulations and broad DIY and construction segment penetration. Bostik, operating within the Arkema ecosystem, delivers low-odor, high-adhesion hybrid systems designed for construction, industrial, and transportation sealing and bonding applications.
Wacker Chemie AG contributes silyl-terminated polymer solutions and silicone-hybrid technologies, reinforcing its broader materials science capabilities across sealants, adhesives, and coatings. H.B. Fuller Company focuses on sustainable formulation development across packaging, construction, and industrial applications, aligning product strategy with evolving sustainability expectations. 3M Company leverages its performance materials heritage to supply high-performance MS polymer-based systems across industrial, construction, and transportation verticals. Dow Inc. integrates polymer technology expertise into hybrid adhesive and sealant formulation development, supporting broader construction and industrial deployment pathways.
Specialized and application-focused participants further intensify competitive dynamics. Tremco Illbruck and MAPEI S.p.A. concentrate on construction-oriented MS polymer adhesives and sealants, while Soudal Group has built recognition around hybrid MS polymer sealants with strong initial tack and multi-substrate adhesion profiles for professional and industrial utilization. Evonik Industries AG and AGC Chemicals supply critical silyl-terminated polymer materials and specialty chemical formulations that underpin downstream product development. Momentive Performance Materials contributes performance material expertise to hybrid polymer adhesive technologies, rounding out a highly interconnected supply and formulation network.
Strategic capacity and platform expansion activities underscore the intensity of current competitive positioning. In June 2024, Kaneka Corporation realized a significant capacity increase at its Belgium facility, expanding annual production to 43,000 tons to address sustained European demand. Sika AG announced European production capacity expansion for MS polymer-based adhesives in early 2025 to align with ongoing infrastructure and construction procurement momentum. More recently, in March 2026, Forza Inc. expanded its advanced MS polymer adhesive and sealant technology platform across construction, transportation, industrial manufacturing, marine, and composites applications, with explicit emphasis on strengthening made-in-USA supply chain positioning. These developments signal a market in which capacity readiness, geographic supply chain localization, and platform versatility are becoming defining competitive differentiators.
Industry Dynamics Shaping 2026 Strategy
The commercial environment surrounding MS polymer technologies continues to evolve in response to overlapping regulatory, economic, and technical pressures. Environmental compliance has transitioned from a procurement checkbox to a core product architecture requirement. MS polymer hybrid sealants and adhesives benefit from isocyanate-free, low-VOC, and solvent-free formulation profiles that align with increasingly stringent indoor air quality standards and emissions regulations across construction and industrial contexts. Companies that proactively integrate compliance-driven design into product development cycles are better positioned to secure specification approvals, meet public-sector procurement criteria, and capture premium positioning in environmentally sensitive application segments.
Worldwide MS Polymer Market
Raw material cost volatility remains a persistent strategic consideration. Fluctuations in polyurethane and silicone precursor pricing directly influence production economics and can compress margins if not addressed through proactive sourcing strategies, formulation optimization, or regional supply chain adjustments. The interplay between input cost variability and pricing power across downstream application verticals demands continuous cost-structure monitoring and scenario planning. Organizations that embed raw material sensitivity analysis into their commercial forecasting will be better equipped to maintain pricing discipline while protecting profitability.
Application-level demand divergence further shapes strategic prioritization. Building and construction continues to represent the most substantial demand driver, fueled by infrastructure modernization, façade bonding requirements, and mounting specification preference for durable, paintable, and environmentally compliant sealing solutions. Automotive and transportation applications leverage MS polymer hybrid systems for structural bonding, trim attachment, and vibration-damping applications where weight reduction and multi-material compatibility remain critical performance criteria. Industrial assembly and broader application segments contribute additional growth velocity through specialized bonding, sealing, and coating use cases that demand high initial tack, substrate versatility, and long-term elastic performance.
Capacity deployment and supply chain localization are emerging as decisive competitive levers. As regional demand patterns shift and procurement teams prioritize supply assurance, manufacturers that align production footprints with localized market requirements are gaining strategic advantage. This dynamic is particularly evident across European and Asia Pacific markets, where infrastructure-driven demand and regulatory-driven specification trends are reinforcing the need for proximate production capacity and responsive formulation support.
MS Polymer Hybrid Adhesives & Sealants Market
Translating Market Intelligence into 2026 Execution
For enterprise strategists, regional commercial leaders, and product developers, the operational value of this research lies in its ability to convert complex market dynamics into prioritized decision pathways. Executive teams can utilize the market sizing framework to validate capital allocation assumptions, assess regional expansion feasibility, and calibrate growth forecasts against realistic demand trajectories. Competitive intelligence modules enable benchmarking of capacity strategies, product platform breadth, and application targeting against established incumbents and emerging platform expanders. R&D and formulation teams gain access to technology context that clarifies the performance and compliance implications of STPE versus STPU architectures, supporting more efficient development prioritization. Procurement and supply chain stakeholders benefit from structured visibility into raw material sensitivities, regional capacity deployment trends, and supplier positioning, enabling more resilient sourcing strategies and improved cost-risk management.
The study also addresses the strategic importance of portfolio alignment. As downstream customers increasingly consolidate their specification requirements around low-VOC, isocyanate-free, and solvent-free performance profiles, companies must ensure that product roadmaps, regional formulation capabilities, and technical support infrastructure are synchronized with procurement expectations. The research provides the analytical foundation required to assess where current portfolio strength is sufficient, where formulation investment is warranted, and where partnership or acquisition strategies may accelerate market access.
Strategic Imperatives and Forward Outlook
The worldwide MS polymer market is entering a phase in which structural demand, regulatory-driven formulation shifts, and competitive capacity deployment will collectively determine commercial winners. Organizations that approach 2026 planning with granular demand visibility, disciplined cost-structure awareness, and proactive competitive positioning will be best positioned to capture disproportionate share in high-growth application verticals and regions. The strategic window is narrowing for firms that rely on reactive forecasting or broad-based portfolio assumptions; the market now rewards organizations that combine technical differentiation with supply chain readiness and compliance-aligned product architecture.
Our Worldwide MS Polymer Market research delivers the depth, precision, and strategic framing required to navigate this environment with confidence. To access the complete regional demand breakdowns, application-level sizing, full competitive profiling, capacity deployment analysis, and forward forecasting models that underpin this strategic outlook, we invite you to review the full research publication. The comprehensive dataset and analytical frameworks contained within are designed to support immediate executive decision-making and long-range strategic planning across the entire forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide MS Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Insect Growth Regulators Market to Hit USD 1.1B in 2025, 5.5% CAGR Outlook to 2032
By pmarketresearch, 2026-09-16
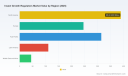
Global Insect Growth Regulators Market Outlook 2026: Strategic Imperatives for Sector Leaders
The worldwide landscape for insect growth regulators (IGRs) is undergoing a period of sustained transformation. Driven by evolving pest resistance patterns, stricter regulatory frameworks, and the expanding demand for sustainable crop protection and vector management, the sector has demonstrated consistent revenue progression over the past half-decade. Forecast models project the global market to cross the 1212.6 million USD threshold in 2026, reflecting a measured pace of expansion that underscores the specialized yet indispensable role of IGRs in modern integrated pest management strategies.
For agricultural executives, chemical manufacturers, and pest control service providers, understanding the underlying traction of this market is no longer optional. It is a prerequisite for capital allocation, R&D prioritization, and geopolitical risk assessment. This analysis draws from our forthcoming Worldwide Insect Growth Regulators Market report, a comprehensive intelligence brief designed to equip decision-makers with the structural clarity required to navigate a mature, highly regulated, and increasingly innovative industry.
Market Trajectory and Macroeconomic Context
Historical revenue tracking from 2020 through 2025 reveals a steady upward climb, moving from approximately 845.5 million USD to 1105.04 million USD. This progression reflects the compounding effect of several structural drivers: the gradual phase-out of broad-spectrum conventional insecticides in sensitive ecological zones, the rising commercial preference for mode-of-action rotation to delay pest resistance, and the growing integration of IGR formulations into both conventional agriculture and urban pest management programs.
Plant Growth Regulators Market
Looking forward, the forecast period spanning 2026 to 2032 models a compound annual growth rate of 5.5 percent. This trajectory is neither speculative nor overly aggressive; it mirrors a market where established chemical classes continue to anchor demand while next-generation formulations and regional commercialization efforts provide incremental uplift. By the close of the forecast window, projected revenues approach 1607.48 million USD, indicating that IGRs will remain a core revenue pillar for crop protection portfolios and specialty pest control enterprises alike.
Such sustained growth does not occur in a vacuum. It is shaped by raw material economics, regulatory labeling requirements, and the pace at which major chemical manufacturers introduce differentiated active ingredients. For instance, the synthesis of widely utilized IGR compounds relies on specialized chemical intermediates, including phenoxyphenyl derivatives and juvenile hormone analogs, which introduce supply chain complexity and pricing sensitivity. Simultaneously, regulatory bodies maintain stringent labeling standards for EPA-registered products, dictating specific usage parameters for slower developmental activity on target insects and restricting certain granular formulations from sensitive crop environments. These operational constraints shape regional adoption patterns and influence how quickly new products can scale.
Technological and Formulation Dynamics
The chemistry behind insect growth regulation continues to diversify. The market is anchored by three principal mechanistic categories, each addressing distinct physiological pathways in insect development. Chitin synthesis inhibitors disrupt the formation of the exoskeleton, preventing successful molting in immature stages. Juvenile hormone mimics interfere with the hormonal regulation of metamorphosis, effectively locking pests in non-reproductive developmental phases. Ecdysone agonists manipulate the hormonal triggers that initiate molting and reproduction, offering an alternative mode of action for resistance management programs.
Commercial adoption across these categories reflects a balance between agronomic efficacy, environmental compliance, and application convenience. The chart of global commercial activity shows a prominent share of revenue flowing toward chitin synthesis inhibitors, followed by a robust contribution from juvenile hormone mimics, while ecdysone-based solutions occupy a more specialized niche. This distribution is not static. It is continually reshaped by product launches, regional regulatory approvals, and the specific pest pressures faced by different agricultural ecosystems.
Recent commercial milestones illustrate the pace of this evolution. Leading innovators have introduced next-generation systemic formulations designed to penetrate leaf tissue and root systems, extending residual control for sap-feeding pests that are notoriously difficult to manage with contact-based chemistry. In parallel, companies have expanded urban pest control portfolios with enhanced formulations specifically engineered to address resistance patterns in cockroach populations. Meanwhile, greenhouse and protected-crop applications have seen the introduction of compliance-driven IGR sprays targeting thrips and whiteflies under increasingly stringent regional registration requirements. These developments highlight a broader industry trend: the shift from generic pest suppression toward precision-targeted, resistance-aware, and environmentally calibrated IGR offerings.
For procurement strategists and R&D directors, this implies that product evaluation frameworks must go beyond initial efficacy data. Formulators and end-users must consider developmental stage dependency, application timing, compatibility with integrated control programs, and the specific regulatory pathway required for intended use cases. Certain granular IGR products, for example, carry explicit labeling restrictions that exclude usage in rice cultivation, requiring strategic formulation selection based on crop and geography. Such nuances determine commercial viability at the field level and can make the difference between product adoption and market rejection.
Competitive Landscape: Consolidation, Innovation, and Regional Footprints
The industry exhibits a moderately concentrated structure. Market concentration metrics indicate that the top three players command roughly 42.5 percent of global revenue, while the top five collectively secure approximately 58.3 percent. This distribution reflects the presence of large, diversified crop protection corporations alongside specialized pest management firms that maintain strong regional positioning and niche formulation expertise.
At the center of the competitive arena are multinational enterprises with integrated crop protection portfolios, extensive R&D infrastructure, and established distribution networks. BASF SE maintains a robust lineup of IGR offerings within its broader agricultural protection framework, with a strategic emphasis on chitin synthesis inhibitors and juvenile hormone analogs for field crop pest management. Bayer AG has advanced the market with next-generation ketoenol-class innovations designed to deliver systemic movement through plant tissues, targeting sap-feeding pests in high-value crops such as cotton and vegetables. Syngenta AG continues to strengthen its urban and agricultural footprint through dual-action formulations that combine pyriproxyfen and novaluron, with recent portfolio expansion efforts explicitly addressing cockroach resistance in professional pest control environments.
Complementing these European giants are regionally anchored innovators and vertically integrated subsidiaries that bring specialized application knowledge. Sumitomo Chemical Co., Ltd. supplies IGR solutions with a focus on rice paddy pests and horticultural applications, leveraging low-residue chitin synthesis inhibitor chemistry aligned with Asia-Pacific agricultural practices. Its U.S.-based subsidiary, Valent U.S.A. LLC, translates that technical foundation into agricultural and urban pest management offerings tailored to North American markets. Corteva Agriscience and FMC Corporation embed IGR technology within broader crop protection and specialty pest control portfolios, emphasizing integrated pest management compatibility and resistance management. ADAMA Ltd. has carved out a strong presence in greenhouse applications, particularly for thrips and whitefly control, with recent introductions reflecting strict compliance with local regulatory standards.
The competitive field also includes firms that specialize in non-crop and animal health applications. Central Life Sciences, operating under Central Garden & Pet Co., focuses on feed-through IGR technology such as methoprene-based products for livestock horn fly management, alongside professional pest management solutions. MGK provides IGR-based fly control formulations for poultry operations and professional pest control programs. Russell IPM Ltd. and Nufarm Limited contribute additional depth through integrated pest management solutions and crop protection portfolios that serve global agricultural markets.
This competitive mosaic creates both opportunities and pressures. Large incumbents benefit from scale, regulatory expertise, and multi-channel commercialization capabilities. Smaller or more specialized companies can differentiate through targeted formulation expertise, regional registration agility, and application-specific performance claims. The market structure rewards strategies that align product capabilities with precise use-case requirements rather than pursuing undifferentiated broad-spectrum positioning.
Strategic Implications for 2026 Decision-Makers
As enterprises prepare their 2026 operating plans, several strategic priorities emerge from the structural realities of the IGR market.
First, portfolio alignment with mode-of-action diversification should be treated as a baseline requirement rather than a tactical enhancement. The continued pressure from pest resistance, combined with regulatory expectations for stewardship, makes it essential for growers and pest management providers to rotate active ingredients across different developmental pathways. Companies that can offer complementary IGR chemistries, or that can position IGRs within broader integrated programs, will capture greater long-term loyalty and contract stability.
Second, regional commercialization strategies must account for divergent regulatory environments and crop-specific restrictions. The same active ingredient may face different labeling parameters, residue tolerances, and application constraints depending on geography and crop type. Businesses that invest in localized registration strategies, region-specific formulation adjustments, and clear compliance documentation will gain faster market access and reduced launch friction. Conversely, attempts to deploy uniform global formulations without accounting for local regulatory conditions risk delayed commercialization or limited adoption.
Third, supply chain resilience for specialized chemical intermediates deserves heightened attention. The production of IGR active ingredients depends on a network of specialty synthesis inputs, including phenoxyphenyl derivatives and juvenile hormone analogs, which are not commoditized in the same way as bulk agrochemical precursors. Price volatility, supplier concentration, and manufacturing capacity constraints can influence product margins and availability. Forward-looking procurement strategies should map the intermediate supply chain, evaluate multi-sourcing options, and consider long-term offtake arrangements where feasible.
Fourth, innovation must extend beyond active ingredient chemistry into formulation science and application delivery. The recent wave of product introductions demonstrates that systemic movement, resistance mitigation, greenhouse compliance, and urban pest resistance management are all becoming decisive purchase drivers. Enterprises that pair active ingredient development with advanced formulation technologies—whether through improved translaminar movement, targeted release profiles, or compatibility with integrated pest management programs—will be better positioned to command premium positioning and defend against commoditization pressure.
Finally, competitive monitoring should extend to both portfolio activity and corporate structuring. Recent launches, portfolio expansions, and regional introductions by major players signal where R&D capital is being deployed and which pest complexes are attracting the greatest commercial attention. Observing the interplay between multinational portfolios and regionally focused specialists offers early visibility into potential partnership, licensing, or competitive response opportunities.
Why the Full Report Matters for Strategic Planning
The insights summarized above represent only the structural surface of a far more detailed intelligence exercise. Our Worldwide Insect Growth Regulators Market report expands this foundation into a working strategic toolkit designed for executives, commercial leaders, and market intelligence teams. It provides a full historical baseline, a multi-year forecast model, and a granular dissection of market segmentation by type, application, and regional distribution. The analysis integrates company-level profiles, recent product and portfolio developments, regulatory context, and supply chain considerations into a single cohesive framework.
For organizations making resource allocation decisions in 2026, the report offers practical guidance on where demand is structurally strongest, which mechanistic categories are gaining commercial momentum, and how leading players are positioning their innovation pipelines. It also provides context on the competitive concentration dynamics that shape pricing behavior, distribution leverage, and market entry feasibility. Readers will gain a clearer understanding of how EPA classification groups, labeling requirements, and crop-specific usage restrictions influence product suitability and regional adoption. Equally important, the report contextualizes the role of specialized raw material inputs within the broader cost structure and supply chain planning conversation.
Accessing the complete report enables stakeholders to move beyond generalized market narratives and into the level of specificity required for investment committee reviews, product launch assessments, regional expansion planning, and competitive benchmarking. The full dataset, segmentation breakdowns, and company analysis are structured to support scenario modeling, go-to-market planning, and strategic risk assessment.
Conclusion
The worldwide insect growth regulators market is entering a phase defined by steady expansion, regulatory refinement, and a broadening spectrum of application-specific innovations. With projected revenue crossing 1212.6 million USD in 2026 and a 5.5 percent compound annual growth rate extending through 2032, the sector presents a viable growth environment for companies that can align chemical expertise, regulatory agility, and precise use-case positioning. The competitive landscape remains moderately concentrated, but differentiation through formulation technology, regional compliance strategy, and integrated pest management compatibility continues to reshape how value is captured.
For business leaders preparing 2026 strategies, the imperative is clear: navigate the market with a detailed, evidence-based view of segmentation, competitive moves, regulatory constraints, and supply chain realities. Our full Worldwide Insect Growth Regulators Market report delivers that intelligence in a structured, decision-ready format. We invite executives and strategy teams to review the complete findings and integrate the full segmentation and company-level analysis into their planning processes.
Worldwide Insect Growth Regulators Market
For detailed analysis of this topic, please visit the official page: Worldwide Insect Growth Regulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Linear Sensors to Hit $4.3B in 2025, Growing 6.45% CAGR to $6.66B by 2032
By pmarketresearch, 2026-09-16
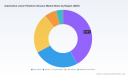
Navigating the Automotive Linear Positions Sensors Market: Strategic Intelligence for 2026 and Beyond
The automotive industry is undergoing a profound transformation, driven by electrification, advanced driver-assistance systems, and increasingly stringent regulatory frameworks. At the heart of these technological shifts lies the critical need for precision measurement and feedback control. Automotive linear positions sensors have emerged as indispensable components, enabling everything from throttle control to suspension management. For stakeholders operating within this sector, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative.
Our latest comprehensive study, the Worldwide Automotive Linear Positions Sensors Market research, provides a definitive analysis of the industry landscape from 2020 through 2032. This report is designed to equip executives, investors, and engineering leaders with the actionable intelligence required to navigate the complexities of the forecasting period beginning in 2026. Below, we outline the strategic value of this research and the key dynamics shaping the future of linear position sensing in vehicles.
Executive Summary: Market Trajectory and Growth Potential
The global automotive linear positions sensors market has demonstrated resilient growth over the past five years, reflecting the broader trend toward sensorization in modern vehicles. Based on historical data from 2020 to 2025, the market has evolved from a valuation of approximately 3.12 billion USD to an estimated 4.30 billion USD in 2025. This upward trajectory is expected to continue robustly through the forecast period ending in 2032.
Our analysis projects that the market will reach a valuation of roughly 4.63 billion USD in 2026, growing at a Compound Annual Growth Rate (CAGR) of 6.45 percent. By the end of the forecast horizon in 2032, the revenue is anticipated to exceed 6.66 billion USD. This growth is not linear; it is influenced by varying adoption rates across vehicle segments, regional manufacturing shifts, and technological breakthroughs. The base year of 2025 serves as a critical anchor point, reflecting post-pandemic supply chain stabilization and the acceleration of next-generation vehicle platforms.
For decision-makers, these figures represent more than just revenue potential. They indicate the scale of opportunity for component suppliers, the volume of procurement required by original equipment manufacturers, and the intensity of competition likely to define the sector. Understanding where the market stands in 2026 versus where it is heading toward 2032 allows companies to align their capacity planning, R&D investments, and partnership strategies with long-term demand signals.
Strategic Segmentation: Technology and Application Landscapes
The market is multifaceted, driven by diverse technological approaches and a wide range of vehicular applications. Our research dissects these layers to reveal where value is being created and where vulnerabilities may exist.
Technology Analysis
Three primary technologies dominate the current landscape: Hall Effect, Inductive, and Potentiometric sensors, alongside emerging solutions such as Magnetostrictive systems. The Hall Effect technology currently commands a significant share of the market, favored for its non-contact nature, durability, and compatibility with modern electronic control units. Inductive sensors offer distinct advantages in harsh environments, providing cost-effective alternatives to traditional LVDTs with better tolerance to metal targets and misalignment. Potentiometric sensors remain relevant in specific cost-sensitive applications, though their mechanical wear limitations are driving innovation toward wear-free solutions.
The strategic implication for manufacturers lies in selecting the right technology mix for target applications. While Hall Effect solutions are prevalent in safety-critical and high-volume segments, inductive technologies are gaining traction in transmission and suspension systems where specific environmental tolerances are required. Our report details the performance metrics, cost structures, and adoption curves associated with each technology, enabling stakeholders to assess where their proprietary solutions fit within the broader ecosystem.
Application Analysis
Automotive linear positions sensors are deployed across several key vehicle systems, each with unique performance requirements. The Powertrain and Transmission segment represents a substantial portion of demand, driven by the need for precise control in engine management, throttle positioning, and increasingly complex transmission systems in both internal combustion and electrified vehicles. The Chassis and Suspension sector is another major growth driver, as luxury and mainstream vehicles alike adopt adaptive damping systems that rely on precise linear feedback.
Braking and Steering applications constitute a critical segment, particularly with the rise of electric power steering and advanced braking assist systems that require high reliability and redundancy. Meanwhile, the Body and Comfort segment, while smaller in relative volume compared to powertrain applications, offers opportunities in seat positioning, mirror adjustment, and other convenience features where cost optimization is paramount.
Understanding the revenue distribution across these applications is vital for targeting sales efforts and customizing product portfolios. Our research provides a granular view of how demand is shifting between these segments, influenced by regulatory mandates on safety and emissions, as well as consumer preferences for comfort and autonomy.
Regional Dynamics and Supply Chain Considerations
Geographic demand patterns reveal significant variations in adoption rates and manufacturing hubs. The Asia Pacific region stands as a dominant force in the market, reflecting the high volume of vehicle production in countries such as China, Japan, and South Korea. Europe remains a key market characterized by stringent emissions regulations and a strong presence of premium vehicle manufacturers, which drives demand for high-performance sensor solutions. North America continues to exhibit steady growth, supported by the commercial vehicle sector and an evolving regulatory landscape.
Latin America and the Middle East and Africa represent emerging opportunities, though they currently account for smaller shares of the global revenue mix. For companies looking to expand their footprint, understanding the local regulatory environments, supplier ecosystems, and customer preferences in these regions is essential. Our report analyzes the regional revenue splits and highlights the specific dynamics influencing procurement decisions in each geographic zone.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment is characterized by a mix of global giants and specialized niche players. Market concentration metrics indicate that while the top three companies hold a notable share of the market, the top five collectively command a larger portion, suggesting a moderately consolidated landscape with room for specialized competitors. The competitiveness of the market is further intensified by the technical barriers to entry and the long qualification cycles associated with automotive supply chains.
Several key companies define the current leadership positions.
Bosch
continues to be a global leader, supplying Hall-effect and other linear position sensors for a wide array of automotive applications including pedal position, suspension, and transmission systems.
Continental AG
provides a broad range of position sensors, including linear variants, for powertrain, chassis, and safety systems in passenger and commercial vehicles, leveraging its deep integration with vehicle platform development.
Worldwide Automotive Linear Positions Sensors Market
In the United States,
Honeywell International Inc.
offers non-contact Hall-effect linear position sensors and SMART Position Sensors designed for motion control in harsh automotive environments.
CTS Corporation
designs and manufactures both contacting and non-contacting Hall-effect linear position sensors for accelerator pedals, clutches, brakes, and emissions compliance applications.
Sensata Technologies
supplies the 9600 Series spring-return linear position sensors and other solutions tailored for space-constrained automotive feedback applications.
European presence is also strong, with
TE Connectivity
manufacturing linear and rotary position sensors for steering, chassis, and powertrain systems.
Infineon Technologies AG
develops magnetic and Hall-effect based sensor ICs used in linear position sensing for automotive safety and powertrain systems.
Piher Sensing Systems
specializes in custom inductive linear position sensors for automotive transmissions, suspensions, hydraulic cylinders, and steering systems.
Other notable participants include
Littelfuse
, which provides off-the-shelf and custom linear position sensors operating in static and dynamic magnetic fields, and
Phinia
, offering contact-free inductive linear position sensors for automated manual transmissions and gearbox solutions in commercial vehicles.
Vishay Intertechnology
produces Hall Effect-based linear position sensors, including recent models suitable for automotive motion control.
Allegro MicroSystems
supplies magnetic linear and angular position sensor ICs widely used in automotive applications, while
Novotechnik U.S., Inc.
offers wear-free linear position sensors for both automotive and industrial applications.
Recent developments underscore the dynamic nature of this competition. For instance, in March 2026, Vishay Intertechnology introduced the 40 LHE linear position sensor, a Hall Effect-based device featuring up to 40mm electrical stroke, ±1 percent linearity, and 12 micrometer resolution. Such product launches highlight the industry focus on enhancing resolution and stroke capabilities to meet evolving motion control requirements.
Market Dynamics: Regulations, Materials, and Innovation
The market is heavily influenced by external forces, particularly regulatory mandates and material science advancements. Automotive linear position sensors are engineered to support compliance with worldwide emissions and performance requirements in applications such as throttle control and exhaust systems. Similarly, linear position sensors for automated manual transmissions contribute to efficiency improvements in commercial vehicles under ongoing global emissions standards. As governments tighten regulations regarding fuel efficiency and pollutant emissions, the demand for precise sensing solutions that enable optimized engine and transmission performance is expected to rise.
On the technology side, inductive linear position sensors provide an alternative to LVDTs with advantages in cost and tolerance to metal targets and misalignment in automotive environments. This versatility makes them attractive for specific applications where robustness is prioritized. Additionally, the shift toward electrification and autonomous driving features is creating new requirements for sensors with higher reliability, longer lifespans, and integration capabilities with electronic control architectures.
Why This Report is Essential for 2026 Decision-Making
For organizations operating in or entering the automotive linear positions sensors market, access to accurate and forward-looking data is critical. This research report goes beyond high-level statistics to provide a deep dive into the factors driving growth, the challenges facing suppliers, and the opportunities emerging from technological shifts.
Worldwide Automotive Angular Position Sensor Market
Key deliverables include detailed segmentation analysis by region, technology, and application, allowing stakeholders to identify high-growth niches and assess competitive threats. The report also covers the competitive landscape, profiling major players and analyzing their strategic moves, product portfolios, and market positions. Furthermore, the inclusion of recent industry developments and regulatory contexts ensures that the analysis remains relevant to the current operating environment.
Investors can use this intelligence to evaluate market attractiveness and identify potential acquisition targets or partnership opportunities. Manufacturers can refine their product development roadmaps based on anticipated demand shifts and technology adoption curves. Procurement leaders can gain insights into supply chain dynamics and regional pricing trends. Ultimately, this report serves as a strategic compass, helping organizations navigate uncertainty and capitalize on the growth projected for the 2026 to 2032 period.
The automotive linear positions sensors market is poised for continued expansion, driven by the relentless push toward smarter, safer, and more efficient vehicles. By understanding the underlying drivers and competitive forces, stakeholders can position themselves to thrive in this evolving landscape. We invite you to explore the full findings of our research to gain the comprehensive insights necessary for informed strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Linear Positions Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Buruli Ulcer Treatment Market Hits $78.45M in 2025, Expected 4.8% CAGR to $108.92M by 2032
By pmarketresearch, 2026-09-16
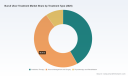
Strategic Intelligence for a Neglected Tropical Disease: The Business Case for the 2026-2032 Buruli Ulcer Treatment Market
In the world of global health strategy, few challenges are as complex as allocating commercial resources toward Neglected Tropical Diseases (NTDs). Buruli ulcer, caused by Mycobacterium ulcerans, remains one of these enigmatic conditions. It is a disease where clinical urgency intersects with a constrained commercial landscape, driven by WHO-supported free treatment programs in endemic regions. For pharmaceutical manufacturers, medical device suppliers, and healthcare investors, understanding the economic nuance of this sector is not merely an academic exercise—it is a prerequisite for strategic positioning.
As we release our latest comprehensive analysis, the Worldwide Buruli Ulcer Treatment Market, our goal is to provide a clear lens through which to view a market characterized by steady growth, defined therapeutic protocols, and a highly specific supply chain dynamic. This article serves as a strategic preview of our findings, highlighting the macro-trends and structural realities that will define the investment landscape from 2026 through 2032. We delve into the market size trajectories, therapeutic segmentation, and the competitive ecosystem dominated by generic antibiotic suppliers and WHO prequalification pathways, while deliberately reserving the granular, actionable breakdowns for our full paid intelligence report.
Decoding the Growth Trajectory: A Macro-Economic View
The commercial story of Buruli ulcer treatment begins with a baseline understanding of market scale and velocity. Our historical analysis captures the market's evolution over the past half-decade, revealing a sector that has navigated the post-pandemic recovery with resilience. The global revenue generated by Buruli ulcer treatments expanded from approximately 62.15 million USD in 2020 to 78.45 million USD in 2025, reflecting a compound annual growth rate that underscores persistent demand despite the niche nature of the disease.
Worldwide Monkeypox Treatment Market
Projecting forward, the forecast period of 2026 to 2032 indicates a continuation of this positive trajectory. The market is anticipated to reach a valuation of 108.92 million USD by 2032. This growth is powered by a CAGR of 4.8 percent, a figure that may appear modest compared to high-growth biotech sectors, yet it represents a robust, steady expansion for a therapy area heavily reliant on essential medicines and public health infrastructure. This growth is not driven by price inflation or novel blockbuster drugs, but rather by the scaling of treatment access, improved case detection in West Africa, and the sustained procurement of generic antibiotics and wound care supplies under national program frameworks.
Strategic observers should note that this CAGR reflects a baseline expansion. In our full report, we dissect the variance across different therapeutic modalities and regional procurement cycles, identifying pockets of higher growth intensity that are critical for supply chain planning. However, the headline trajectory confirms that the market is stabilizing and growing, offering a predictable environment for stakeholders who can navigate the volume-based, low-margin economics of generic antibiotic supply.
The Clinical Imperative: Treatment Modalities and Market Segmentation
The Buruli ulcer treatment market is not a monolith; it is defined by WHO guidelines that dictate a multidisciplinary approach. The standard of care, reaffirmed in the October 2023 WHO guideline update, recommends eight weeks of daily rifampicin and clarithromycin as first-line therapy. For advanced lesions, surgery and wound management remain indispensable. This clinical reality directly shapes the revenue streams of the market.
Our segmentation analysis categorizes the market by treatment type, end-user, and region, providing a three-dimensional view of where value is captured. The treatment landscape is dominated by wound management and surgery, alongside antibiotic therapy. These two pillars account for the bulk of market activity, reflecting the dual challenge of infectious eradication and tissue repair. While antibiotic regimens rely heavily on fixed-dose combinations and generic sourcing, the wound management component encompasses surgical interventions and rehabilitation services, which vary significantly by the degree of lesion severity and the healthcare infrastructure available in endemic countries.
Physiotherapy and rehabilitation also constitute a distinct segment, addressing the functional recovery required after severe ulceration. This niche, though smaller in revenue proportion, is critical for long-term patient outcomes and represents an area where specialized service providers and rehabilitation equipment suppliers can find strategic entry points, particularly in regions strengthening their post-treatment care networks.
In terms of end-user distribution, hospitals and specialized clinics naturally command the largest share of treatment volume. These facilities handle the bulk of surgical interventions and severe cases. Ambulatory surgical centers and homecare settings follow, representing channels that are increasingly relevant as healthcare systems in endemic regions decentralize care to reduce the burden on major tertiary institutions. The allocation of treatment across these settings is deeply influenced by reimbursement structures; notably, in many endemic areas including West Africa, treatment is provided free through WHO-supported national programs, fundamentally altering the traditional payer dynamics seen in commercial pharmaceutical markets.
Geographically, the disease burden is overwhelmingly concentrated. Over 90 percent of cases are reported in West Africa, making this region the epicenter of demand. However, the market's regional profile also includes Asia Pacific, the Americas, and Europe and others, where surveillance programs, imported cases, and specialized clinic management create smaller but operationally significant demand streams. Australia, for instance, maintains robust surveillance despite declining incidence, sustaining a specialized treatment niche. Our report maps these regional dynamics in detail, quantifying the relative weight of each geography without relying on simplistic percentage splits that obscure local procurement nuances.
The Supply Chain Reality: Generic Antibiotics and Prequalification Pathways
A defining characteristic of the Buruli ulcer treatment market is its reliance on generic antibiotics sourced from a concentrated manufacturing base. The commercial incentive for developing novel branded therapies for NTDs is low; consequently, the supply chain is anchored by established generic manufacturers who can produce rifampicin, clarithromycin, and combination packs at scale. India has emerged as a pivotal hub in this ecosystem, with manufacturers aligning their production with WHO prequalification standards to access procurement contracts for national programs.
This reliance on generic supply introduces specific strategic considerations. Market concentration is evident, with a handful of key players capturing a significant portion of the value chain. The CR3 and CR5 metrics highlight the consolidated nature of the competitive landscape, where a few large suppliers of WHO-prequalified essential medicines dominate volume procurement. For new entrants, the barrier to entry is not just manufacturing capacity but also the rigorous qualification process and the ability to meet the consistent quality requirements of global health buyers.
Recent developments underscore the importance of this prequalification pathway. For example, WHO updates in October 2023 confirmed rifampicin-clarithromycin as the first-line regimen, reinforcing the demand stability for these molecules. Simultaneously, suppliers like Macleods Pharmaceuticals have secured WHO prequalification for fixed-dose combinations specific to multidrug therapy, positioning themselves as preferred vendors for large-scale health initiatives. Other major generic players, including Cipla and Sandoz, also contribute to the supply of rifampicin and clarithromycin, maintaining a competitive yet coordinated environment where volume and compliance drive procurement decisions.
Strategic decisions regarding supply chain partnerships, distribution agreements, and manufacturing investments must account for this prequalification reality. Our analysis examines the profiles of these core companies, their headquarters, their product portfolios, and their positioning within the WHO prequalification framework. However, the exact share of each competitor, their specific contract volumes, and the detailed pricing dynamics across different procurement rounds remain critical intelligence for corporate strategy. We reserve these deep competitive dossiers and the full financial profiling of key suppliers for the complete market report, where clients can benchmark their positioning against the actual market leaders.
Worldwide Buruli Ulcer Treatment Market
Implications for 2026 Decision-Making: Where Strategy Meets Execution
As organizations look toward 2026 and beyond, the Buruli ulcer treatment market presents a set of strategic questions that require more than high-level observations. For generic antibiotic manufacturers, the opportunity lies in expanding prequalified product lines, optimizing cost structures to remain competitive in volume tenders, and potentially exploring fixed-dose combinations that simplify regimen adherence. The market's dependence on Indian-sourced generics also opens avenues for regional supply chain diversification, an increasingly relevant consideration given global logistics volatility.
For medical device and wound care suppliers, the market offers a different value proposition. The emphasis on surgery and wound management for advanced cases creates demand for surgical consumables, dressing materials, and rehabilitation tools. However, access to this segment is mediated by the public health infrastructure and the funding mechanisms of national programs. Understanding which facilities are expanding surgical capacity, how reimbursement flows for non-drug interventions, and where home-based wound care is emerging are all strategic puzzles that our report's regional and end-user breakdowns address.
Investors and strategy teams must also navigate the risk factors inherent in NTD markets. The reliance on free treatment through WHO-supported programs means that revenue is tied to the continuity of donor funding and government health budgets. Policy shifts, changes in case reporting, or the introduction of alternative therapeutic protocols could alter demand patterns. Conversely, increased case detection through improved surveillance in West Africa could drive volume growth, while the absence of a specific vaccine means that treatment remains the primary intervention for the foreseeable future. These dynamics require scenario planning that goes beyond a single-point forecast.
Our report provides the tools for this planning. It integrates regulatory updates, reimbursement contexts, and raw material dependencies into a cohesive strategic framework. We analyze the impact of the WHO's eight-week regimen on procurement cycles, the implications of low commercial market incentives on supply resilience, and the regional variations in case management that affect product mix. For decision-makers, this translates into actionable intelligence on where to allocate resources, which partnerships to prioritize, and how to structure supply agreements to capture growth in a responsible and sustainable manner.
Inside the Report: What Comprehensive Intelligence Delivers
This article has outlined the macro landscape, the segmentation logic, and the competitive forces shaping the Buruli ulcer treatment market. Yet, the true value of our Worldwide Buruli Ulcer Treatment Market research lies in the depth of detail that only a full strategic assessment can provide. Our report goes beyond the top-level revenue figures and CAGR to deliver operational intelligence.
Clients will gain access to a granular segmentation of the market by treatment type, end-user, and region, with detailed revenue breakdowns and growth rates that allow for precise sizing of opportunity pockets. We map the competitive landscape with individual company profiles, prequalification status, and strategic positioning, enabling benchmarking against WHO-prequalified suppliers and other generic manufacturers. The report also features a deep dive into recent developments, including guideline updates from WHO and prequalification milestones, contextualizing these events within the market's evolution.
Furthermore, the analysis incorporates a thorough examination of market dynamics, including regulatory frameworks, reimbursement mechanisms, and raw material dependencies. This contextual layer is essential for understanding the constraints and enablers of market growth. Our forecast models provide scenario-based projections that account for variations in case detection, funding continuity, and supply chain resilience, giving clients a robust foundation for strategic planning in 2026 and the forecast period through 2032.
The report is designed for strategic consultants, pharmaceutical and medical device executives, procurement specialists, and investors who need to move from general awareness to precise, data-driven action. By combining macro market size analysis with micro-level segmentation and competitive profiling, it serves as a comprehensive guide to navigating a market defined by public health imperatives and specialized supply chain requirements.
Conclusion: Positioning for Growth in a Defined Niche
The Buruli ulcer treatment market is a compelling example of a healthcare sector where impact and commerce intersect within a constrained but steadily expanding framework. Growth is anchored in essential medicines, standardized regimens, and public health programs, yet it offers meaningful opportunities for stakeholders who understand the nuances of prequalification, regional demand concentration, and the segmentation of care delivery. The projected revenue trajectory through 2032 reflects a market that is maturing in its structure while retaining the capacity for volume-driven expansion.
For organizations preparing their 2026 strategies, the imperative is clear: engagement with this market requires a deep understanding of the WHO-aligned treatment protocols, the competitive dynamics of generic antibiotic supply, and the regional realities of disease burden and healthcare infrastructure. Our full report delivers this understanding with rigor and precision, providing the granular data and strategic context necessary to make informed decisions. We invite you to access the complete Worldwide Buruli Ulcer Treatment Market intelligence to unlock the full spectrum of insights, segmentations, and competitive benchmarks that will guide your path forward in this vital and evolving sector.
For detailed analysis of this topic, please visit the official page: Worldwide Buruli Ulcer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Non-Thermal Food Processing Market to Hit $10.68 Billion by 2032 at 10% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for a Preservative-Free Era: An Introduction to the Worldwide Non-Thermal Food Processing Market Report
Executive Overview
The global food industry is undergoing a profound transformation driven by consumer demand for clean labels, extended shelf life, and uncompromised nutritional integrity. As traditional thermal methods increasingly face scrutiny for their impact on flavor and vitamin retention, non-thermal processing technologies have emerged as the cornerstone of next-generation food preservation. Our latest comprehensive study, Worldwide Non-Thermal Food Processing Market, provides a rigorous analysis of this dynamic landscape, projecting the market valuation to reach approximately 10,680.4 Million USD by 2032. With a registered compound annual growth rate of 10.0 percent spanning the forecast horizon from 2026 through 2032, this trajectory signals a decisive shift in capital allocation and operational strategy across the global supply chain.
Worldwide Non-Thermal Food Processing Market
Food Processing Equipment Market
This report is not merely a statistical compilation. It is a strategic decision-support instrument designed for executive leadership teams, venture capitalists, procurement directors, and R&D managers who require granular visibility into technology adoption curves, regional deployment patterns, and competitive maneuvering. As we navigate the post-pandemic normalization of supply chains and the intensifying regulatory focus on food safety, understanding the economics of pasteurization alternatives has become a critical competency. The data presented herein captures the inflection points where investment yields the highest marginal returns, allowing stakeholders to position their portfolios ahead of the market curve.
Market Architecture and Technological Divergence
The expansion of the non-thermal sector is underpinned by a diverse array of processing technologies, each offering distinct advantages regarding microbial inactivation, texture preservation, and energy efficiency. Historical data reveals a robust recovery and acceleration pattern following the supply chain disruptions of the early 2020s. Starting from a baseline of roughly 3,450 Million USD in 2020, the market demonstrated resilience with valuations climbing to 5,480.73 Million USD by 2025. This upward momentum is expected to sustain, pushing valuations past the 6,000 Million USD threshold in the immediate forecast year before accelerating toward the decade-end targets.
Our segmentation analysis dissects this growth across several pivotal technological vectors. High Pressure Processing continues to command a dominant share of the technology mix, reflecting its maturity and widespread acceptance in juice and meat preservation. However, the strategic narrative is increasingly defined by the rapid scaling of Pulsed Electric Fields and Ultrasound Processing, which offer lower operational footprints and specialized applications in cell disintegration and extraction efficiency. Cold Plasma technology, while currently representing a smaller fraction of total revenue, presents a high-growth frontier for surface decontamination and packaging integration. Coupled with emerging niche methodologies categorized under other innovations, the technology landscape offers a multifaceted toolkit for manufacturers seeking to optimize specific product lines.
Cross-referencing these technological streams with application verticals reveals critical deployment trends. Beverages represent a primary anchor for non-thermal adoption, driven by the premiumization of cold-pressed juices and functional drinks. Simultaneously, the Meat, Poultry and Seafood segment is witnessing intensified investment as processors seek to reduce sodium and chemical preservatives without sacrificing safety. Fruits and Vegetables, Dairy Products, and a variety of specialized application categories collectively form a resilient demand matrix that mitigates sector-specific volatility. By mapping technology performance against these application requirements, our report enables clients to identify where process compatibility aligns with market premiumization strategies.
Regional Dynamics and Competitive Concentration
Geographically, the market exhibits a mature yet evolving distribution of value creation. North America and Europe have historically anchored the revenue base, reflecting early regulatory acceptance, established infrastructure for premium food brands, and high consumer willingness to pay for clean-label attributes. Yet, the forecast period highlights significant growth vectors in Asia Pacific, Latin America, and the Middle East and Africa, where urbanization and the expansion of modern retail channels are catalyzing demand for processed foods that meet international safety standards. Our analysis provides a nuanced look at how trade compliance, import-export regulations, and localized manufacturing capabilities influence regional market penetration.
The competitive environment is characterized by a moderately concentrated landscape. The top three industry players account for approximately 42.5 percent of total market revenue, while the top five firms capture around 58.8 percent. This concentration suggests a market where scale advantages and proprietary technology patents play a decisive role in securing long-term contracts, yet ample opportunity remains for specialized innovators and regional service providers. The leading entities have established strong footholds through continuous product innovation and strategic facility expansions. For instance, industry leaders based in Europe and North America have been actively upgrading their equipment portfolios, with notable launches such as advanced high-pressure systems designed to optimize juice yields and pulsed electric field demonstrators showcased at major industry expos to validate processing efficiency for potato and vegetable applications.
Furthermore, multinational corporations are reinforcing their global supply footprints to meet regional demand surges. Recent strategic moves include the commissioning of new manufacturing facilities in key growth markets like Brazil, signaling a commitment to localized production and reduced logistics latency. These developments underscore the importance of monitoring corporate strategy as a leading indicator of regional market maturity. Our report details the operational profiles of key companies, including their headquarters, technological specializations, and recent corporate activities, providing a clear map of who controls which nodes in the value chain.
Regulatory Tailwinds and Operational Realities
Technological viability in food processing does not exist in a vacuum; it is inextricably linked to regulatory validation and operational economics. The non-thermal market benefits from a favorable regulatory environment that increasingly recognizes alternatives to thermal pasteurization. Authorities in major jurisdictions have validated high-pressure processing as a pasteurization method equivalent to thermal processes for specific product categories, providing a clear compliance pathway for manufacturers. Similarly, European regulations have validated pulsed electric field methods for pathogen reduction in ready-to-eat foods, reinforcing the technology's role in meeting stringent microbiological criteria.
However, successful market entry requires navigating a complex matrix of compliance requirements, particularly for companies engaged in cross-border trade. Exporting non-thermally processed goods, such as juices, to stringent markets like the European Union involves adherence to Novel Food Regulations, which demands rigorous documentation and safety substantiation. Our report synthesizes these regulatory nuances, offering a compliance roadmap that mitigates the risk of market access delays.
Operational cost structures also play a pivotal role in investment decisions. While non-thermal processing can reduce reliance on chemical preservatives and extend shelf life, it introduces specific input cost variables. Raw material price volatility remains a constant consideration, with commodity prices for inputs like fresh avocados or meats directly influencing the cost base for processed outputs. Additionally, labor cost differentials across regions significantly impact the total cost of ownership for processing lines. In markets where industrial wages are substantial, the efficiency and automation level of non-thermal equipment become critical determinants of profitability. By integrating data on labor economics and commodity trends, our analysis helps clients model total operational expenditure scenarios, ensuring that capital investments are robust against macroeconomic fluctuations.
Report Methodology and Strategic Utility
The Worldwide Non-Thermal Food Processing Market report is constructed using a rigorous, multi-phase research methodology designed to deliver actionable intelligence rather than generic market noise. Our analytical framework combines top-down macroeconomic modeling with bottom-up validation through primary industry interviews, company filings, and trade data assessment. The study covers a historical review period from 2020 to 2025, establishing a reliable baseline for trend extrapolation, and extends across a comprehensive forecast horizon through 2032.
Stakeholders utilizing this report will gain access to:
- Detailed Technology Assessment: Comparative performance metrics, scalability benchmarks, and adoption barriers for High Pressure Processing, Pulsed Electric Fields, Ultrasound, Cold Plasma, and other emerging modalities.
- Application Vertical Forecasts: Revenue projections and growth drivers across Beverages, Meat and Poultry, Fruits and Vegetables, Dairy, and specialized segments, enabling precise portfolio alignment.
- Regional Market Intelligence: Country-level deployment insights, trade flow analysis, regulatory impact assessments, and localization strategies for North America, Europe, Asia Pacific, Latin America, and MENA regions.
- Competitive Landscape Mapping: Profiles of key market participants, including strategic moves, facility expansions, product launches, and patent activity, allowing for benchmarking and gap analysis.
- Operational Cost Modeling: Insights into labor dynamics, raw material price correlations, and regulatory compliance costs to refine ROI calculations for new processing lines or retrofitting projects.
Conclusion: Positioning for the Future of Food Preservation
The transition toward non-thermal food processing represents more than a technological upgrade; it is a strategic reorientation of the food industry toward sustainability, health, and quality preservation. With a projected market valuation exceeding 10,680 Million USD by 2032 and a consistent double-digit growth rate, the window for strategic positioning is open but will not remain so indefinitely. Early movers who secure access to the right technology partnerships, navigate regulatory frameworks with agility, and target high-growth application segments will define the competitive standards of the next decade.
This report is designed to equip decision-makers with the comprehensive intelligence necessary to navigate this complex landscape. By synthesizing macroeconomic trends, segmentation dynamics, regulatory mandates, and competitive intelligence into a single cohesive document, we provide the clarity required to allocate capital with confidence. For organizations committed to leading in the clean-label and advanced preservation space, the insights contained within this study are indispensable. To access the full depth of data, including specific regional breakdowns, detailed company profiles, and granular forecast tables, we invite you to explore the complete Worldwide Non-Thermal Food Processing Market research on our portal.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Thermal Food Processing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Water Tube Industrial Boilers Market Hits $9.45B in 2025, Projects 4.51% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Water Tube Industrial Boilers Market (2026–2032)
The industrial steam generation sector is entering a decisive phase of structural transformation. As facilities navigate decarbonization mandates, shifting fuel economics, and the need for operational resilience, water tube industrial boilers have emerged as the preferred backbone for high-pressure, high-capacity thermal applications. PW Consulting's newly published Worldwide Water Tube Industrial Boilers Market report provides a comprehensive, decision-grade intelligence framework for executives, procurement leaders, and capital planners who must align technology selection, capacity expansion, and competitive positioning through 2032. This overview synthesizes the study's strategic architecture and demonstrates how its analytical layers translate into actionable corporate strategy for the 2026 planning cycle.
Commercial Boilers Market
Market Trajectory and the 2026–2032 Forecast Architecture
The global water tube industrial boiler market has demonstrated consistent, compounding revenue growth across the historical evaluation window, reflecting steady industrial expansion, modernization of aging thermal assets, and incremental capacity additions across process-intensive sectors. Building on this established trajectory, the forecast period projects continued medium-term expansion, with annual revenue progressing from a baseline just above nine thousand million USD in 2025 toward a materially higher valuation by 2032. The compound annual growth rate of 4.51 percent frames a market that is neither stagnant nor explosively volatile, but rather one characterized by sustained, technology-driven reinvestment. This growth cadence carries direct implications for capital allocation: engineering, procurement, and construction teams must plan for phased capacity deployment rather than single-cycle overhauls, while product developers and system integrators should calibrate manufacturing scaling and service-network investment to match a steady but increasingly competitive demand curve.
The study's temporal design spans historical performance from 2020 through 2025, anchoring trend analysis in a complete pre-forecast baseline, and extends forward through 2032 to capture multiple investment horizons. This structure allows decision-makers to separate cyclical fluctuations from durable secular shifts, particularly as fuel pricing volatility, emission regulation, and fuel-switching incentives reshape procurement economics. The forecast modeling integrates these variables into a structured revenue outlook, enabling scenario planning for capacity additions, retrofits, and replacement cycles without relying on speculative short-term indicators.
Segmentation Intelligence: Fuel, Application, and Regional Architecture
Effective market strategy depends on understanding where growth concentrates and how structural demand diverges across technology and end-use configurations. The report dissects the market across fuel type, application, and regional dimensions, revealing the operational and economic logic that shapes procurement priorities and technology roadmaps.
Fuel-type segmentation captures the ongoing transition within industrial thermal generation. Natural gas continues to anchor a substantial share of installed and projected capacity, favored for balancing efficiency, availability, and operational flexibility. Coal retains a meaningful footprint, particularly where legacy infrastructure, cost structures, or regional fuel access sustain its relevance. Biomass is gaining strategic attention as organizations pursue renewable heat pathways and leverage policy incentives, while oil and alternative fuel configurations persist in specialized or transitional applications. The study evaluates each fuel pathway not as a static share snapshot but as a dynamic selection environment, where operators weigh total cost of ownership, emissions compliance, supply-security considerations, and future-proofing against regulatory trajectories.
Application segmentation illuminates how industrial boiler demand maps onto distinct process requirements. Power generation represents a major demand pillar, driven by utility-scale and captive power needs where reliability and scale are paramount. The chemical and petrochemical sector follows closely, reflecting continuous-process steam requirements and stringent performance expectations. Food and beverage, pulp and paper, refineries, and other industrial verticals each present differentiated operating profiles, influencing boiler sizing, fuel compatibility, uptime demands, and service cadence. By mapping these application layers, the analysis equips manufacturers and service providers with a clearer view of where specification priorities diverge and where aftermarket and parts revenue opportunities accumulate.
Regional analysis situates these demand drivers within geographic market structures. Asia Pacific captures the largest revenue footprint, consistent with broad industrial expansion, infrastructure intensification, and manufacturing capacity growth across the region. North America and Europe represent mature but still evolving markets, shaped by efficiency mandates, retrofit cycles, and fuel-transition programs. Middle East and Africa and Latin America contribute distinct demand profiles, often linked to industrial diversification, resource-processing activities, and localized energy strategies. The study treats regional variation as a strategic variable rather than a static distribution chart, enabling readers to evaluate where localization, distribution partnerships, and specification adaptation will determine competitive performance.
Competitive Dynamics and Strategic Positioning
The market operates within a moderately concentrated landscape, where a core group of established manufacturers holds meaningful share while a broader field of specialists, regional producers, and technology-differentiated players competes on efficiency, customization, and service reach. The report's competitive architecture examines the positioning, product portfolios, and strategic orientations of leading participants, including Babcock & Wilcox, Cleaver-Brooks, Miura Boiler Co., Ltd., Indeck Power Equipment Company, Hurst Boiler & Welding Co., Unilux Advanced Manufacturing, LLC, Victory Energy, Rentech Boiler Systems, Thermax Limited, ZOZEN Boiler Co., Ltd., Bryan Boilers, Parker Boiler Co., and Babcock Wanson.
These companies illustrate the breadth of competitive approaches shaping the market. Some emphasize large-scale, customized industrial configurations with broad application coverage and long service histories, while others focus on modular, high-efficiency designs that reduce footprint, accelerate installation, and support lower-emission operation. Several players maintain strong regional manufacturing and distribution bases to serve localized demand, while others extend their reach through international project execution and cross-market product platforms. The study evaluates these strategies in terms of how they influence pricing architecture, specification competition, and customer-switching dynamics, helping readers understand where differentiation is sustainable and where commoditization pressure intensifies.
Beyond static profiles, the report integrates recent industry activity to show how competitive momentum is being created in real time. Display of eco-friendly water tube boiler solutions at a major trade exhibition in early 2026 signaled continued emphasis on low-emission, fuel-flexible product narratives. Parallel commissioning and conversion milestones elsewhere have demonstrated operational pathways toward oxy-combustion configurations and hydrogen-ready operation, indicating that technology leadership is increasingly tied to decarbonization capability rather than output capacity alone. Similarly, recent project awards for biomass-fired industrial boilers with advanced flue gas cleaning reflect growing execution activity in segments where policy incentives and corporate sustainability commitments are converging. For competitors and investors alike, these developments illustrate that the strategic battlefield is shifting toward fuel adaptability, emissions performance, and demonstration-scale credibility.
Worldwide Water Tube Industrial Boilers Market
Technology Trends and Regulatory Tailwinds
Industrial boiler strategy in 2026 cannot be separated from the broader decarbonization and efficiency agenda. Regulatory pressure, corporate net-zero commitments, and the economics of carbon exposure are aligning to create demand for boiler designs that can maintain reliability while accommodating cleaner fuel inputs and higher-efficiency operating modes. Oxy-combustion and hydrogen-ready capabilities are increasingly being incorporated into next-generation industrial boiler architectures, enabling organizations to align steam generation with advancing emission mandates and, in certain configurations, support high-efficiency carbon capture pathways. These design trends are not merely compliance features; they are becoming central to asset longevity, financing conditions, and the ability to operate under future fuel regimes without stranded-capacity risk.
At the same time, raw material economics are reshaping the cost environment for boiler manufacturing and replacement programs. Recent pricing movements for hot-rolled coil steel reflect a structural upward shift, influenced by demand patterns, supply conditions, and broader industrial input costs. For boiler OEMs, fabricators, and end-users planning retrofits or new installations, these input-cost dynamics affect equipment pricing, project budgeting, and procurement timing. The study places these material-cost signals in context, linking them to capacity planning, contract structuring, and the relative economics of new builds versus life-extension projects. This integration of macro input trends with market-level forecasting helps executives anticipate cost pressure rather than react to it after the fact.
A parallel trend is the accelerating adoption of biomass-fired water tube boiler configurations in sectors such as paper and packaging, where natural gas replacement strategies are being supported by government decarbonization programs and industrial sustainability initiatives. This shift highlights how policy-enabled fuel switching can reshape segment demand and alter the competitive value of fuel-flexible equipment. The report captures these dynamics as part of a broader transition narrative, showing where policy, technology, and industrial process requirements are reinforcing one another and where friction remains between legacy infrastructure and future fuel strategies.
What the Study Delivers for 2026 Decision-Making
The Worldwide Water Tube Industrial Boilers Market report is designed as an operational intelligence asset rather than a high-level overview. Its architecture supports multiple decision functions that are immediate priorities for 2026 planning:
- Demand and revenue context that frames the overall market trajectory and links historical performance to the forward forecast, giving executives a stable reference point for growth assumptions and capacity planning.
- Segment-level logic across fuel type, application, and region, enabling readers to identify where specification competition, aftermarket potential, and technology substitution are most active.
- Competitive landscape mapping that clarifies the strategic posture of leading manufacturers and highlights the differentiation levers shaping customer selection, including efficiency, modularity, emissions performance, and service infrastructure.
- Technology and regulatory alignment that connects boiler design evolution, fuel-flexibility trends, and decarbonization mandates to practical implications for procurement, retrofitting, and lifecycle planning.
- Input-cost and project-environment awareness that embeds raw material pricing signals and recent project activity into the market narrative, helping organizations interpret near-term cost and execution risk.
This combination of market structure, competitive intelligence, and trend integration allows the study to serve as a reference for capital investment decisions, product planning, regional expansion evaluation, and supplier selection. By organizing the market into decision-relevant layers, the report supports both corporate-level strategy and functional execution, whether the priority is entering a new application vertical, assessing a fuel-transition pathway, or benchmarking competitive position against established incumbents.
Why This Research Matters Now
The water tube industrial boiler market sits at the intersection of industrial reliability, fuel economics, and decarbonization pressure. In that position, it rewards organizations that can read structural shifts early and translate them into technology, sourcing, and geographic decisions before competitors lock in their responses. The 2026–2032 outlook presents a market expanding at a measured but meaningful pace, with growth distributed across fuel pathways, applications, and regions in ways that reward precision planning rather than generic assumptions.
PW Consulting's full study goes beyond the summary contours outlined here. It provides the deeper segmentation analysis, regional and application-level breakdowns, competitive positioning details, and scenario-supported forecast logic that executives need to convert market awareness into disciplined strategy. For teams preparing procurement roadmaps, product development plans, or investment evaluations, the complete report offers the contextual depth required to act with confidence in a market where efficiency, emissions performance, and fuel adaptability increasingly determine long-term value.
To access the full market intelligence, segmentation detail, and strategic analysis behind this overview, explore the complete Worldwide Water Tube Industrial Boilers Market report and integrate its findings into your 2026 decision framework.
For detailed analysis of this topic, please visit the official page: Worldwide Water Tube Industrial Boilers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Thoracic Drainage Devices Market to Hit $1,459M by 2032 with 6.48% CAGR
By pmarketresearch, 2026-09-16
The Future of Thoracic Drainage Devices: A Strategic Outlook for 2026 and Beyond
The global thoracic drainage devices market stands at a critical inflection point. As we move through 2026, healthcare systems worldwide are grappling with evolving surgical techniques, digital transformation, and shifting reimbursement paradigms. For medical device manufacturers, hospital procurement leaders, and investors, understanding the trajectory of this essential category of critical care products is no longer optional—it is a strategic imperative. This article serves as a preview of the comprehensive intelligence contained within the PW Consulting Worldwide Thoracic Drainage Devices Market report, offering a high-level view of the forces shaping the industry while highlighting the depth of analysis available to decision-makers who require actionable granular intelligence.
Market Trajectory and Growth Dynamics
The thoracic drainage market has demonstrated remarkable resilience and steady expansion over the past half-decade. Market valuation in 2025 reached approximately $940 million, reflecting the essential role that chest drainage systems play in thoracic surgery, cardiac procedures, pulmonology interventions, and emergency trauma care. Looking ahead, the forecast period from 2026 through 2032 projects sustained growth, with the market expected to surpass the $1.4 billion threshold by the end of the forecast horizon. This expansion is underpinned by a compound annual growth rate of 6.48 percent, a figure that reflects both the maturation of established markets and the emergence of new demand drivers in developing economies.
Several macro-level factors are converging to fuel this growth trajectory. The aging global population continues to drive higher volumes of cardiothoracic and pulmonary surgeries, while advances in minimally invasive techniques are expanding the addressable patient population for procedures requiring thoracic drainage. Furthermore, the ongoing integration of digital monitoring technologies into traditional drainage platforms is creating premium product tiers that command higher reimbursement rates and deliver measurable clinical benefits. At the same time, regulatory frameworks and reimbursement policies remain in flux, requiring market participants to maintain agile compliance and market access strategies. The interplay of these forces creates a complex operating environment where companies that fail to adapt risk losing share to more innovative and strategically positioned rivals.
A key structural feature of the competitive landscape is the degree of market concentration. The top three companies collectively command approximately 42.15 percent of total market revenue, while the top five players control roughly 58.6 percent. This concentration level indicates that while large multinational medtech firms currently dominate, there remains meaningful room for specialized manufacturers and regional players to capture niche segments and differentiate through innovation, pricing, or localized service capabilities. For stakeholders evaluating market entry, partnership opportunities, or competitive positioning, understanding the dynamics behind this concentration—and the gaps it leaves open—is essential.
Product and Application Landscape
Thoracic drainage products encompass a diverse array of systems, catheters, and accessory components, each serving distinct clinical workflows and economic considerations. The market is broadly segmented into thoracic drainage systems, thoracic drainage catheters, and accessories. Each of these product categories addresses specific stages of patient care, from intraoperative placement to postoperative monitoring and removal. Systems typically integrate collection chambers, suction control mechanisms, and water seal capabilities, while catheters vary in material composition, diameter, and design features such as trocar assistance or fluted configurations for improved pleural drainage. Accessories round out the ecosystem, providing the ancillary components that support safe and effective deployment.
Worldwide Expectoration Machine Market
From an application perspective, thoracic drainage devices are utilized across several high-acuity clinical settings. Thoracic surgery and pulmonology procedures represent a major demand center, driven by lobectomies, pneumonectomies, and interventions for pleural effusions and pneumothoraces. Cardiac surgery constitutes another significant application area, where chest tubes are routinely employed following coronary artery bypass grafting, valve replacement, and other cardiothoracic interventions to manage postoperative fluid and air accumulation. Trauma and emergency care rounds out the application mix, as thoracic drainage remains a cornerstone of emergency management for chest injuries, hemothorax, and tension pneumothorax in both hospital and pre-hospital settings.
The clinical trend toward earlier mobility and enhanced recovery after surgery has placed renewed emphasis on drainage solutions that support patient ambulation without compromising monitoring accuracy or safety. Traditional water-seal systems, while time-tested, can restrict patient movement and rely on subjective clinical interpretation of bubbling and fluid oscillation. This has accelerated adoption of digital thoracic drainage platforms that provide objective, quantifiable air leak monitoring and real-time fluid output tracking. Such systems not only improve clinical decision-making but also align with institutional goals to reduce length of stay and optimize resource utilization—factors that carry direct implications for procurement priorities and satisfaction with device performance.
Regional Dynamics and Access Considerations
The global thoracic drainage market exhibits distinct regional characteristics shaped by healthcare infrastructure maturity, surgical volume, regulatory environment, and purchasing dynamics. North America remains the largest revenue contributor, supported by a high concentration of sophisticated hospital systems, established reimbursement frameworks, and a strong presence of major manufacturer headquarters. The region's market is characterized by rapid uptake of advanced digital drainage technologies and a procurement environment that increasingly values clinical evidence, total cost of ownership, and integration with electronic health record workflows.
Europe represents a substantial and growing market, with diverse national healthcare systems that present both opportunities and complexity. Varying reimbursement structures, procurement centralization trends, and differing clinical guidelines across countries require manufacturers to adopt nuanced market access strategies. Meanwhile, the Asia Pacific region continues to attract strategic attention due to rising surgical volumes, expanding healthcare infrastructure, and growing awareness of advanced drainage technologies. Latin America and the Middle East and Africa markets, though smaller in absolute revenue terms, offer long-term growth potential tied to healthcare modernization initiatives and increasing access to specialized surgical care.
It is important to recognize that regional dynamics extend beyond raw volume. Supply chain resilience, local regulatory requirements, distribution partnerships, and the ability to provide responsive clinical support all influence a company's ability to compete effectively in each geography. Firms that build robust regional strategies—rather than relying solely on global product platforms—tend to outperform when navigating the heterogeneous realities of thoracic drainage procurement worldwide.
Competitive Landscape: Key Players and Recent Developments
The competitive arena for thoracic drainage devices is populated by a mix of large diversified medtech corporations and focused specialist manufacturers. Becton, Dickinson and Company (BD) offers a portfolio of thoracic drainage catheters and systems for pleural and pericardial drainage, integrating chest tubes into its broader critical care portfolio. Getinge AB, through its Atrium brand, provides comprehensive thoracic drainage solutions including Oasis dry suction water seal chest drains, Express mini mobile dry seal drains, and soft or firm PVC thoracic catheters suitable for cardiac, thoracic, and pediatric patients. These offerings underscore the importance of broad clinical coverage and brand recognition in driving formulary inclusion and clinician loyalty.
Teleflex Incorporated markets chest drainage systems such as the Pleur-Evac Sahara, designed for the removal of air and fluid from the pleural space, while Cook Medical supplies an extensive line of chest tubes and catheters, including Wayne Pneumothorax Catheter Sets, for pleural and pericardial drainage. Medtronic plc participates in the market with product offerings that support cardiothoracic procedures, leveraging its broader presence in surgical technologies. Medela AG has gained prominence for its Thopaz+ digital chest drainage and monitoring system, which is used after thoracic and cardiac surgery and exemplifies the shift toward intelligent drainage platforms with objective monitoring capabilities.
ATMOS MedizinTechnik GmbH & Co. KG develops digital thoracic drainage systems including the ATMOS C 051 Cardiothoracic Digital Drain and Observation System, contributing to the growing ecosystem of advanced monitoring solutions. Vygon SA supplies thoracic drainage catheters and systems as part of its critical care and surgical portfolio, while Utah Medical Products, Inc. offers thoracic drainage solutions within its medical device range. Smaller or regionally focused players are also making meaningful contributions: Sinapi Biomedical manufactures the Sinapi Chest Drain System for cardiothoracic applications and has actively participated in international forums such as SCTS 2026 to showcase its technology. Redax S.p.A. specializes in portable chest drains, thoracic catheters, fluted drains, and wearable thoracic drainage systems, including the Drentech line, highlighting innovation in mobility and patient comfort. In India, Sterimed Group produces thoracic and chest drainage catheters using medical-grade PVC with depth markings for post-operative care, and Angiplast Private Limited manufactures chest drainage solutions and related medical devices for surgical needs. Centese has developed the Thoraguard digital intelligence system for automated clog clearance and measurement in cardiothoracic surgical drainage, illustrating how targeted innovation can address specific clinical pain points.
Recent events underscore the dynamic nature of this competitive field. In July 2025, Cardinal Health announced the discontinuation of its line of chest drainage units in the US commercial region effective November 30, 2025, a move that reshapes procurement alternatives for US hospitals and creates openings for competitors to capture displaced volume. Shortly thereafter, in January 2026, the FDA issued a Class 2 device recall for Cardinal Health's Sentinel Seal, Altitude, AquaSeal, and ThoraSeal Chest Drainage Units, further emphasizing the importance of quality management and post-market surveillance. Meanwhile, FluidAI Medical (NERv Technology Inc.) received FDA 510(k) clearance in August 2025 for a device related to surgical drainage monitoring, signaling continued regulatory momentum for intelligent drainage technologies. These developments illustrate how product launches, regulatory actions, and strategic divestitures interact to continuously redefine the competitive landscape.
Regulatory, Reimbursement, and Technology Drivers
Thoracic drainage devices are primarily regulated as Class II medical devices cleared via the FDA 510(k) pathway in the United States, a framework that emphasizes substantial equivalence to predicate devices while requiring manufacturers to demonstrate safety and performance. Chest drainage units must also comply with FDA consensus standards for electrical safety and performance where applicable, adding a layer of technical rigor for products that incorporate digital monitoring or powered suction functionality. In other jurisdictions, similar regulatory structures govern market access, and differences in clearance timelines, clinical evidence expectations, and post-market requirements can create uneven competitive dynamics across regions.
Reimbursement considerations further shape market behavior. Thoracic surgery procedures involving chest tube insertion are typically coded under CPT 32551, with associated APC and MS-DRG payments that consider complication or comorbidity status. This coding and payment environment influences hospital procurement decisions by affecting the economic calculus of procedure cost, length of stay, and resource utilization. As healthcare payers and providers increasingly focus on value-based outcomes, drainage solutions that demonstrably reduce complications, accelerate discharge, or improve monitoring reliability may gain preferential treatment in formulary evaluations and purchasing contracts.
On the technology front, digital thoracic drainage systems such as Thopaz+ and ATMOS C 051 provide objective air leak monitoring and mobility advantages over traditional water-seal systems. These platforms enable clinicians to quantify air leaks, track fluid output with precision, and support earlier patient mobilization—all of which align with enhanced recovery protocols and can contribute to improved patient experiences. As hospitals seek to standardize care pathways and reduce variability, the adoption of digitally enabled drainage devices is likely to expand, particularly in centers of excellence and health systems pursuing operational efficiency.
Strategic Insights for 2026 Decision-Making
For organizations operating in or entering the thoracic drainage market, the current environment presents both opportunities and challenges that demand careful strategic planning. The steady compound growth rate projected through 2032 suggests that demand will continue to expand, but capturing value will require more than riding secular trends. Companies must articulate clear clinical value propositions, navigate an evolving regulatory and reimbursement landscape, and respond nimbly to competitive moves such as product discontinuations, recalls, and the introduction of novel digital solutions.
Worldwide Thoracic Drainage Devices Market
Procurement leaders at hospitals and health systems face a parallel set of strategic questions. With certain established product lines being discontinued in key markets, organizations must evaluate alternatives that maintain clinical performance while ensuring supply continuity. The growing availability of digital drainage options introduces trade-offs between upfront device cost and downstream benefits such as reduced monitoring burden, improved documentation, and potentially shorter length of stay. Understanding total cost of ownership, compatibility with existing workflows, and the quality of vendor support will be critical to making informed purchasing decisions.
From an investment and partnership perspective, the market's moderate concentration leaves room for innovation-driven entrants and regional specialists to carve out defensible positions. Technologies that address unmet clinical needs—whether through automated clog clearance, enhanced mobility, integrated monitoring, or cost-effective designs—may achieve rapid adoption in targeted segments. Simultaneously, the presence of well-resourced incumbents with broad portfolios means that new offerings must be supported by robust clinical evidence, regulatory compliance, and effective commercialization strategies to gain traction.
The complexity of these decisions underscores the value of comprehensive, rigorously sourced market intelligence. While this article provides a strategic overview of the thoracic drainage market's trajectory, competitive dynamics, and key trends, many of the detailed assessments required for concrete planning—such as segment-level sizing, regional growth breakdowns, precise market share distributions, and granular competitive profiling—demand the full depth of primary and secondary research that underpins a dedicated industry study.
Why the Full Report Matters
PW Consulting's Worldwide Thoracic Drainage Devices Market report is designed to equip executives, commercial leaders, and investors with the detailed, decision-ready intelligence that a high-level summary cannot fully capture. The study provides a structured deep dive into market sizing across historical and forecast periods, segmentation analysis by product type and application, and regional assessments that illuminate growth hotspots and competitive intensity. It also delivers detailed profiles of key companies, analysis of recent developments such as product discontinuations, recalls, regulatory clearances, and trade show activity, and an evaluation of the regulatory and reimbursement factors that shape market access.
Importantly, the report synthesizes these elements into actionable strategic takeaways, enabling readers to benchmark their positioning, identify white-space opportunities, assess competitive threats, and calibrate entry or expansion strategies with confidence. In a market where product portfolios are being reshaped, digital technologies are gaining prominence, and procurement decisions increasingly hinge on clinical and economic evidence, having access to precise, current, and well-validated data is a distinct competitive advantage.
The insights outlined here represent only the opening frame of a much larger analytical picture. To access the full market sizing detail, segmentation breakdowns, regional growth trajectories, company-level competitive assessments, and the complete set of strategic recommendations, we invite you to explore the complete Worldwide Thoracic Drainage Devices Market research on the PW Consulting website. For decision-makers who require depth, precision, and forward-looking context to navigate 2026 and beyond, the full report delivers the intelligence needed to act with clarity and conviction.
For detailed analysis of this topic, please visit the official page: Worldwide Thoracic Drainage Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global fMRI Market Reaches $4.1B in 2025, Projected 6.42% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Decade: Inside the Worldwide Functional Magnetic Resonance Imaging Market
The landscape of neuroimaging is undergoing a structural transformation. As brain mapping transitions from purely research-oriented endeavors to clinically actionable diagnostics, the Worldwide Functional Magnetic Resonance Imaging (fMRI) Market is poised for sustained expansion. This article serves as an executive introduction to PW Consulting's latest comprehensive analysis, a study designed to equip C-suite executives, investment strategists, and healthcare administrators with the foresight required to navigate the 2026-2032 forecast period.
Understanding the trajectory of fMRI technology is no longer optional; it is a strategic imperative. The convergence of hardware innovation, regulatory shifts, and volatile supply chain dynamics creates a complex environment where data-driven decision-making separates market leaders from laggards. Our latest report dissects this complexity, offering a granular view of the revenue streams, segmentation drivers, and competitive maneuvers that will define the industry for the next decade.
Market Trajectory: From Resilience to Acceleration
The historical data underscores a narrative of resilience and steady growth. Between 2020 and 2025, the global fMRI market expanded from approximately 3,025 Million USD to 4,117 Million USD. This historical baseline establishes a foundation of stability despite global economic headwinds. However, the forward-looking data suggests an acceleration in value capture. The market is projected to grow from a base of 4,318 Million USD in 2026 to over 6,365 Million USD by 2032.
MRI (Magnetic Resonance Imaging System) Market
This growth corresponds to a forecasted Compound Annual Growth Rate (CAGR) of 6.42 percent. For strategic planners, this figure is not merely a statistic; it represents the pace at which capital must be allocated to maintain market share. A 6.42 percent CAGR in a specialized medical imaging sector indicates robust demand drivers, likely stemming from increased adoption in clinical diagnostics and a broadening scope in neuroscience research. The report details how this growth trajectory is unevenly distributed across technology tiers and geographic zones, creating pockets of high opportunity that require specific strategic responses.
Technological Stratification and Hardware Evolution
The fMRI market is not a monolith. It is deeply stratified by field strength, and each tier serves a distinct purpose in the clinical and research ecosystem. Our analysis breaks down the revenue composition across 3T, 1.5T, and 7T and ultra-high field systems. While the market has historically favored the workhorse capabilities of 3T systems for their balance of signal-to-noise ratio and clinical utility, the dynamics are shifting.
Ultra-high field systems are garnering increased attention for specialized neuroscience applications, though they face distinct adoption barriers. Conversely, 1.5T systems remain critical for specific patient populations and accessibility-focused deployments. The strategic nuance lies in understanding where the value lies within each segment. The report provides a detailed examination of how hardware specifications align with workflow requirements, helping buyers and investors understand which field strengths are driving the bulk of revenue versus which are driving future innovation potential. This segmentation is critical for vendors tailoring their R&D pipelines and for healthcare providers optimizing capital expenditure based on patient demographics and research goals.
Application Drivers: Clinical Diagnostics vs. Neuroscience Research
Demand for fMRI is fueled by two primary engines: Clinical Diagnostics and Neuroscience Research. These applications are not growing in isolation; they are increasingly intertwined. Clinical diagnostics rely on fMRI for pre-surgical brain mapping and the assessment of neurological disorders, while research applications drive the development of new protocols and connectivity analyses that eventually trickle down to clinical settings.
The report analyzes the revenue split between these applications to reveal where the immediate cash flow resides versus where the long-term growth potential lies. Clinical diagnostics often represent the stable base, while research applications can be more volatile but offer higher margins for specialized centers. Understanding the interplay between these two sectors is vital for market participants. For instance, a surge in research funding can spur hardware upgrades that later benefit clinical throughput. PW Consulting's analysis delves into the specific drivers influencing each application vertical, identifying the regulatory and reimbursement landscapes that will determine the speed of adoption in different healthcare systems.
Geographic Distribution and Regional Dynamics
Geography plays a pivotal role in market performance. The revenue landscape is divided across North America, Europe, Asia Pacific, and the Rest of the World. While North America has traditionally held a significant share due to advanced healthcare infrastructure and high research funding, the report highlights shifting dynamics in other regions.
The Asia Pacific region represents a critical growth vector, driven by expanding healthcare access and increasing investment in medical infrastructure. Europe remains a stronghold for both clinical deployment and research excellence. However, the report avoids simplistic rankings to focus on the strategic implications of regional distribution. Where are the untapped opportunities? Which regions are facing regulatory bottlenecks? How do local manufacturing capabilities influence supply chain resilience? These are the questions answered in the full market intelligence document. The analysis provides a roadmap for expanding market presence, taking into account local competitor strength and varying reimbursement policies that dictate purchasing power.
Competitive Landscape: Incumbents and Disruptors
The market concentration is significant, with the top three companies accounting for over 62 percent of the market and the top five holding over 78 percent. This high concentration suggests a mature market where scale and technological leadership are paramount. However, the entry of new technologies and the agility of specialized players are creating pressure points within this hierarchy.
Worldwide Functional Magnetic Resonance Imaging Market
Our report profiles the key companies shaping this landscape. Major players such as Siemens Healthineers, GE HealthCare, Philips Healthcare, Canon Medical Systems Corporation, and United Imaging Healthcare dominate the hardware supply chain. Each brings distinct advantages. Siemens Healthineers continues to leverage its MAGNETOM family, recently securing FDA clearance for the 70cm bore MAGNETOM Flow 1.5T platform featuring virtually helium-free DryCool technology. This move addresses both patient comfort and operational cost concerns. GE HealthCare has similarly advanced its portfolio, receiving FDA 510(k) clearances for next-generation SIGNA technologies including Signa Sprint with Freelium and the Signa One AI workflow platform, enhancing precision imaging capabilities.
Philips Healthcare maintains its position through Ingenia systems enhanced by AI-powered reconstruction tools like SmartSpeed, which accelerate neuroimaging workflows. Canon Medical Systems Corporation integrates functional MR applications into its Vantage systems, supporting BOLD signal analysis and pre-surgical planning. United Imaging Healthcare is also making waves with its uMR series, including high-performance platforms like the uMR Ultra 3T system unveiled with dynamic videography capabilities.
Beyond the hardware giants, specialized firms like NordicNeuroLab play a crucial role by providing all-in-one plug-and-play fMRI solutions, including hardware for stimulus presentation and software for workflow standardization. These complementary solutions are essential for ensuring reliable data acquisition across different scanner platforms. The full report provides a deep dive into the strategic positioning of these companies, analyzing their recent developments and how they are navigating the competitive terrain.
Industry Dynamics: Supply Chain Risks and Regulatory Catalysts
No market analysis is complete without addressing the external forces that can disrupt growth curves. Two critical dynamics are currently reshaping the fMRI landscape: raw material supply chains and regulatory approvals.
The dependency on liquid helium remains a significant operational constraint. MRI systems typically require 1,500 to 2,000 liters of liquid helium for initial superconducting magnet fills, with periodic top-ups adding to operational costs. This vulnerability was starkly highlighted in early 2026, when global helium supply disruptions linked to geopolitical events in Qatar led to spot price spikes of 50 to 100 percent. These spikes increased service and operational costs for conventional MRI systems, squeezing margins and prompting a strategic search for alternatives.
In response, the regulatory environment has become a facilitator of innovation. The FDA issued 510(k) clearances in 2025 and 2026 for virtually helium-free or low-helium MRI platforms. Technologies like the Siemens MAGNETOM Flow and GE Signa Sprint with Freelium are not just engineering feats; they are strategic responses to supply chain risk mitigation. This shift is likely to accelerate the depreciation of older, helium-intensive assets and drive procurement toward newer, supply-chain-resilient platforms. The report analyzes how these regulatory clearances influence purchasing decisions and how companies are positioning their portfolios to capitalize on the transition to low-helium technologies.
Operational Intelligence and Strategic Value
PW Consulting's Worldwide Functional Magnetic Resonance Imaging Market study is designed to go beyond high-level summaries. It offers operational intelligence that can be directly applied to strategy formulation. The report includes detailed segmentation analysis, allowing stakeholders to validate assumptions about market size in specific regions or applications without relying on aggregated industry estimates. It covers the forecast period from 2026 to 2032, providing a long-term horizon for capital planning and R&D investment.
Readers will find actionable insights on market concentration, helping to assess the risk of relying on a small number of suppliers or competitors. The inclusion of recent developments, such as product launches and regulatory clearances, ensures that the intelligence is current and relevant. Furthermore, the analysis addresses the nuances of device classification, noting that functional MRI systems are primarily indicated for research, pre-surgical brain mapping, and clinical neuroscience applications, and are subject to Class II medical device regulations. This regulatory context is essential for understanding market entry barriers and compliance requirements.
Conclusion: Navigating the Future of Neuroimaging
The period from 2026 to 2032 will be defined by the intersection of technological advancement, supply chain resilience, and expanding clinical utility. The projected growth to over 6,365 Million USD indicates a market that is not only surviving but evolving. However, capturing this value requires more than passive observation. It demands a clear understanding of where the growth is concentrated, which technologies are becoming obsolete, and how competitors are maneuvering to secure market share.
This article has provided a strategic overview and a glimpse into the depth of our analysis. However, the specific segmentation data, regional growth rates, and detailed competitive profiles contained within the full report are essential for making precise investment and procurement decisions. To access the complete intelligence, including the full dataset and strategic recommendations, we invite you to consult the full Worldwide Functional Magnetic Resonance Imaging Market research document. Equip your organization with the detailed foresight needed to lead in the next decade of neuroimaging innovation.
For detailed analysis of this topic, please visit the official page: Worldwide Functional Magnetic Resonance Imaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com