

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Thoracic Drainage Devices Market to Hit $1,459M by 2032 with 6.48% CAGR

The Future of Thoracic Drainage Devices: A Strategic Outlook for 2026 and Beyond
The global thoracic drainage devices market stands at a critical inflection point. As we move through 2026, healthcare systems worldwide are grappling with evolving surgical techniques, digital transformation, and shifting reimbursement paradigms. For medical device manufacturers, hospital procurement leaders, and investors, understanding the trajectory of this essential category of critical care products is no longer optional—it is a strategic imperative. This article serves as a preview of the comprehensive intelligence contained within the PW Consulting Worldwide Thoracic Drainage Devices Market report, offering a high-level view of the forces shaping the industry while highlighting the depth of analysis available to decision-makers who require actionable granular intelligence.
Market Trajectory and Growth Dynamics
The thoracic drainage market has demonstrated remarkable resilience and steady expansion over the past half-decade. Market valuation in 2025 reached approximately $940 million, reflecting the essential role that chest drainage systems play in thoracic surgery, cardiac procedures, pulmonology interventions, and emergency trauma care. Looking ahead, the forecast period from 2026 through 2032 projects sustained growth, with the market expected to surpass the $1.4 billion threshold by the end of the forecast horizon. This expansion is underpinned by a compound annual growth rate of 6.48 percent, a figure that reflects both the maturation of established markets and the emergence of new demand drivers in developing economies.
Several macro-level factors are converging to fuel this growth trajectory. The aging global population continues to drive higher volumes of cardiothoracic and pulmonary surgeries, while advances in minimally invasive techniques are expanding the addressable patient population for procedures requiring thoracic drainage. Furthermore, the ongoing integration of digital monitoring technologies into traditional drainage platforms is creating premium product tiers that command higher reimbursement rates and deliver measurable clinical benefits. At the same time, regulatory frameworks and reimbursement policies remain in flux, requiring market participants to maintain agile compliance and market access strategies. The interplay of these forces creates a complex operating environment where companies that fail to adapt risk losing share to more innovative and strategically positioned rivals.
A key structural feature of the competitive landscape is the degree of market concentration. The top three companies collectively command approximately 42.15 percent of total market revenue, while the top five players control roughly 58.6 percent. This concentration level indicates that while large multinational medtech firms currently dominate, there remains meaningful room for specialized manufacturers and regional players to capture niche segments and differentiate through innovation, pricing, or localized service capabilities. For stakeholders evaluating market entry, partnership opportunities, or competitive positioning, understanding the dynamics behind this concentration—and the gaps it leaves open—is essential.
Product and Application Landscape
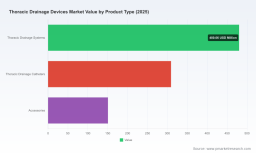
Thoracic drainage products encompass a diverse array of systems, catheters, and accessory components, each serving distinct clinical workflows and economic considerations. The market is broadly segmented into thoracic drainage systems, thoracic drainage catheters, and accessories. Each of these product categories addresses specific stages of patient care, from intraoperative placement to postoperative monitoring and removal. Systems typically integrate collection chambers, suction control mechanisms, and water seal capabilities, while catheters vary in material composition, diameter, and design features such as trocar assistance or fluted configurations for improved pleural drainage. Accessories round out the ecosystem, providing the ancillary components that support safe and effective deployment.
Worldwide Expectoration Machine Market
From an application perspective, thoracic drainage devices are utilized across several high-acuity clinical settings. Thoracic surgery and pulmonology procedures represent a major demand center, driven by lobectomies, pneumonectomies, and interventions for pleural effusions and pneumothoraces. Cardiac surgery constitutes another significant application area, where chest tubes are routinely employed following coronary artery bypass grafting, valve replacement, and other cardiothoracic interventions to manage postoperative fluid and air accumulation. Trauma and emergency care rounds out the application mix, as thoracic drainage remains a cornerstone of emergency management for chest injuries, hemothorax, and tension pneumothorax in both hospital and pre-hospital settings.
The clinical trend toward earlier mobility and enhanced recovery after surgery has placed renewed emphasis on drainage solutions that support patient ambulation without compromising monitoring accuracy or safety. Traditional water-seal systems, while time-tested, can restrict patient movement and rely on subjective clinical interpretation of bubbling and fluid oscillation. This has accelerated adoption of digital thoracic drainage platforms that provide objective, quantifiable air leak monitoring and real-time fluid output tracking. Such systems not only improve clinical decision-making but also align with institutional goals to reduce length of stay and optimize resource utilization—factors that carry direct implications for procurement priorities and satisfaction with device performance.
Regional Dynamics and Access Considerations
The global thoracic drainage market exhibits distinct regional characteristics shaped by healthcare infrastructure maturity, surgical volume, regulatory environment, and purchasing dynamics. North America remains the largest revenue contributor, supported by a high concentration of sophisticated hospital systems, established reimbursement frameworks, and a strong presence of major manufacturer headquarters. The region's market is characterized by rapid uptake of advanced digital drainage technologies and a procurement environment that increasingly values clinical evidence, total cost of ownership, and integration with electronic health record workflows.
Europe represents a substantial and growing market, with diverse national healthcare systems that present both opportunities and complexity. Varying reimbursement structures, procurement centralization trends, and differing clinical guidelines across countries require manufacturers to adopt nuanced market access strategies. Meanwhile, the Asia Pacific region continues to attract strategic attention due to rising surgical volumes, expanding healthcare infrastructure, and growing awareness of advanced drainage technologies. Latin America and the Middle East and Africa markets, though smaller in absolute revenue terms, offer long-term growth potential tied to healthcare modernization initiatives and increasing access to specialized surgical care.
It is important to recognize that regional dynamics extend beyond raw volume. Supply chain resilience, local regulatory requirements, distribution partnerships, and the ability to provide responsive clinical support all influence a company's ability to compete effectively in each geography. Firms that build robust regional strategies—rather than relying solely on global product platforms—tend to outperform when navigating the heterogeneous realities of thoracic drainage procurement worldwide.
Competitive Landscape: Key Players and Recent Developments
The competitive arena for thoracic drainage devices is populated by a mix of large diversified medtech corporations and focused specialist manufacturers. Becton, Dickinson and Company (BD) offers a portfolio of thoracic drainage catheters and systems for pleural and pericardial drainage, integrating chest tubes into its broader critical care portfolio. Getinge AB, through its Atrium brand, provides comprehensive thoracic drainage solutions including Oasis dry suction water seal chest drains, Express mini mobile dry seal drains, and soft or firm PVC thoracic catheters suitable for cardiac, thoracic, and pediatric patients. These offerings underscore the importance of broad clinical coverage and brand recognition in driving formulary inclusion and clinician loyalty.
Teleflex Incorporated markets chest drainage systems such as the Pleur-Evac Sahara, designed for the removal of air and fluid from the pleural space, while Cook Medical supplies an extensive line of chest tubes and catheters, including Wayne Pneumothorax Catheter Sets, for pleural and pericardial drainage. Medtronic plc participates in the market with product offerings that support cardiothoracic procedures, leveraging its broader presence in surgical technologies. Medela AG has gained prominence for its Thopaz+ digital chest drainage and monitoring system, which is used after thoracic and cardiac surgery and exemplifies the shift toward intelligent drainage platforms with objective monitoring capabilities.
ATMOS MedizinTechnik GmbH & Co. KG develops digital thoracic drainage systems including the ATMOS C 051 Cardiothoracic Digital Drain and Observation System, contributing to the growing ecosystem of advanced monitoring solutions. Vygon SA supplies thoracic drainage catheters and systems as part of its critical care and surgical portfolio, while Utah Medical Products, Inc. offers thoracic drainage solutions within its medical device range. Smaller or regionally focused players are also making meaningful contributions: Sinapi Biomedical manufactures the Sinapi Chest Drain System for cardiothoracic applications and has actively participated in international forums such as SCTS 2026 to showcase its technology. Redax S.p.A. specializes in portable chest drains, thoracic catheters, fluted drains, and wearable thoracic drainage systems, including the Drentech line, highlighting innovation in mobility and patient comfort. In India, Sterimed Group produces thoracic and chest drainage catheters using medical-grade PVC with depth markings for post-operative care, and Angiplast Private Limited manufactures chest drainage solutions and related medical devices for surgical needs. Centese has developed the Thoraguard digital intelligence system for automated clog clearance and measurement in cardiothoracic surgical drainage, illustrating how targeted innovation can address specific clinical pain points.
Recent events underscore the dynamic nature of this competitive field. In July 2025, Cardinal Health announced the discontinuation of its line of chest drainage units in the US commercial region effective November 30, 2025, a move that reshapes procurement alternatives for US hospitals and creates openings for competitors to capture displaced volume. Shortly thereafter, in January 2026, the FDA issued a Class 2 device recall for Cardinal Health's Sentinel Seal, Altitude, AquaSeal, and ThoraSeal Chest Drainage Units, further emphasizing the importance of quality management and post-market surveillance. Meanwhile, FluidAI Medical (NERv Technology Inc.) received FDA 510(k) clearance in August 2025 for a device related to surgical drainage monitoring, signaling continued regulatory momentum for intelligent drainage technologies. These developments illustrate how product launches, regulatory actions, and strategic divestitures interact to continuously redefine the competitive landscape.
Regulatory, Reimbursement, and Technology Drivers
Thoracic drainage devices are primarily regulated as Class II medical devices cleared via the FDA 510(k) pathway in the United States, a framework that emphasizes substantial equivalence to predicate devices while requiring manufacturers to demonstrate safety and performance. Chest drainage units must also comply with FDA consensus standards for electrical safety and performance where applicable, adding a layer of technical rigor for products that incorporate digital monitoring or powered suction functionality. In other jurisdictions, similar regulatory structures govern market access, and differences in clearance timelines, clinical evidence expectations, and post-market requirements can create uneven competitive dynamics across regions.
Reimbursement considerations further shape market behavior. Thoracic surgery procedures involving chest tube insertion are typically coded under CPT 32551, with associated APC and MS-DRG payments that consider complication or comorbidity status. This coding and payment environment influences hospital procurement decisions by affecting the economic calculus of procedure cost, length of stay, and resource utilization. As healthcare payers and providers increasingly focus on value-based outcomes, drainage solutions that demonstrably reduce complications, accelerate discharge, or improve monitoring reliability may gain preferential treatment in formulary evaluations and purchasing contracts.
On the technology front, digital thoracic drainage systems such as Thopaz+ and ATMOS C 051 provide objective air leak monitoring and mobility advantages over traditional water-seal systems. These platforms enable clinicians to quantify air leaks, track fluid output with precision, and support earlier patient mobilization—all of which align with enhanced recovery protocols and can contribute to improved patient experiences. As hospitals seek to standardize care pathways and reduce variability, the adoption of digitally enabled drainage devices is likely to expand, particularly in centers of excellence and health systems pursuing operational efficiency.
Strategic Insights for 2026 Decision-Making
For organizations operating in or entering the thoracic drainage market, the current environment presents both opportunities and challenges that demand careful strategic planning. The steady compound growth rate projected through 2032 suggests that demand will continue to expand, but capturing value will require more than riding secular trends. Companies must articulate clear clinical value propositions, navigate an evolving regulatory and reimbursement landscape, and respond nimbly to competitive moves such as product discontinuations, recalls, and the introduction of novel digital solutions.
Worldwide Thoracic Drainage Devices Market
Procurement leaders at hospitals and health systems face a parallel set of strategic questions. With certain established product lines being discontinued in key markets, organizations must evaluate alternatives that maintain clinical performance while ensuring supply continuity. The growing availability of digital drainage options introduces trade-offs between upfront device cost and downstream benefits such as reduced monitoring burden, improved documentation, and potentially shorter length of stay. Understanding total cost of ownership, compatibility with existing workflows, and the quality of vendor support will be critical to making informed purchasing decisions.
From an investment and partnership perspective, the market's moderate concentration leaves room for innovation-driven entrants and regional specialists to carve out defensible positions. Technologies that address unmet clinical needs—whether through automated clog clearance, enhanced mobility, integrated monitoring, or cost-effective designs—may achieve rapid adoption in targeted segments. Simultaneously, the presence of well-resourced incumbents with broad portfolios means that new offerings must be supported by robust clinical evidence, regulatory compliance, and effective commercialization strategies to gain traction.
The complexity of these decisions underscores the value of comprehensive, rigorously sourced market intelligence. While this article provides a strategic overview of the thoracic drainage market's trajectory, competitive dynamics, and key trends, many of the detailed assessments required for concrete planning—such as segment-level sizing, regional growth breakdowns, precise market share distributions, and granular competitive profiling—demand the full depth of primary and secondary research that underpins a dedicated industry study.
Why the Full Report Matters
PW Consulting's Worldwide Thoracic Drainage Devices Market report is designed to equip executives, commercial leaders, and investors with the detailed, decision-ready intelligence that a high-level summary cannot fully capture. The study provides a structured deep dive into market sizing across historical and forecast periods, segmentation analysis by product type and application, and regional assessments that illuminate growth hotspots and competitive intensity. It also delivers detailed profiles of key companies, analysis of recent developments such as product discontinuations, recalls, regulatory clearances, and trade show activity, and an evaluation of the regulatory and reimbursement factors that shape market access.
Importantly, the report synthesizes these elements into actionable strategic takeaways, enabling readers to benchmark their positioning, identify white-space opportunities, assess competitive threats, and calibrate entry or expansion strategies with confidence. In a market where product portfolios are being reshaped, digital technologies are gaining prominence, and procurement decisions increasingly hinge on clinical and economic evidence, having access to precise, current, and well-validated data is a distinct competitive advantage.
The insights outlined here represent only the opening frame of a much larger analytical picture. To access the full market sizing detail, segmentation breakdowns, regional growth trajectories, company-level competitive assessments, and the complete set of strategic recommendations, we invite you to explore the complete Worldwide Thoracic Drainage Devices Market research on the PW Consulting website. For decision-makers who require depth, precision, and forward-looking context to navigate 2026 and beyond, the full report delivers the intelligence needed to act with clarity and conviction.
For detailed analysis of this topic, please visit the official page: Worldwide Thoracic Drainage Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com