

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global MS Polymer Market to Reach $9.28B by 2032, 7% CAGR

Global MS Polymer Market Outlook 2026: Strategic Intelligence for High-Growth Decision-Making
The worldwide MS Polymer market stands at a critical inflection point as enterprises navigate tightening environmental regulations, supply chain reconfiguration, and accelerating demand for high-performance hybrid sealants and adhesives. Our latest Worldwide MS Polymer Market research delivers a comprehensive, data-grounded strategic blueprint designed specifically to empower executive decision-makers, product developers, and commercial leaders operating across 2026 and the forecast window extending through 2032. By synthesizing historical performance from 2020 through the base year of 2025 with rigorous forward-looking modeling, this study equips organizations with the analytical clarity required to allocate capital efficiently, identify asymmetric growth opportunities, and outmaneuver competitors in a rapidly consolidating landscape.
Market Trajectory & Macro Growth Framework
Historical trajectory analysis reveals a resilient, structurally expanding market that has consistently outperformed baseline expectations. Revenue expanded from approximately 4.1 billion USD in 2020 to nearly 5.8 billion USD by 2025, reflecting sustained commercial momentum across multiple downstream verticals. The forecast period projects continued upward progression, with the global market size anticipated to surpass 6.1 billion USD in 2026 and advance toward a 9.3 billion USD valuation by 2032. This expansion is anchored by a composite CAGR of 7.0 percent, a growth rate that signals durable institutional demand rather than transient cyclical spikes.
Several structural forces underpin this trajectory. The global transition toward isocyanate-free, low-VOC, and solvent-free formulation architectures has fundamentally reshaped procurement standards across construction, transportation, and industrial manufacturing. MS polymer hybrid technologies, engineered through silyl-terminated polyether and silyl-terminated polyurethane chemistries, deliver the necessary balance of elastic recovery, multi-substrate adhesion, and environmental compliance. Simultaneously, capacity expansion initiatives across major production hubs are aligning with infrastructural modernization programs in Europe and Asia Pacific, reinforcing supply-side readiness. Yet, despite favorable demand signals, production economics remain sensitive to raw material price volatility, particularly for polyurethane and silicone precursors. Organizations that integrate granular cost-structure modeling and regional capacity mapping into their strategic planning will secure meaningful margin protection as input cost dynamics continue to fluctuate.
Deep-Dive Report Architecture: Operational Intelligence for Commercial Execution
This research was structured from the ground up to translate macro-level market intelligence into actionable commercial strategy. Rather than delivering a high-level snapshot, the report functions as an operational playbook. Stakeholders will gain access to meticulously disaggregated market sizing across product types, application verticals, and geographic territories, all calibrated to a consistent revenue framework denominated in million USD. The analytical architecture enables teams to isolate high-velocity demand pockets, evaluate regional penetration thresholds, and benchmark internal performance against market-wide growth benchmarks.
The study encompasses a full-spectrum competitive mapping exercise, profiling leadership positions, capacity footprints, regional formulation strategies, and go-to-market differentiation tactics. Decision-makers will find detailed assessments of how incumbent players are leveraging proprietary base resin technologies, hybrid adhesive platforms, and specialty chemical supply chains to defend market share while expanding into adjacent application categories. The report also evaluates strategic capacity deployment trends, including facility modernization, tonnage increases, and geographic supply chain localization initiatives that are actively reshaping competitive barriers to entry.
Beyond competitive benchmarking, the research integrates forward-looking regulatory and compliance analysis. As indoor air quality mandates, emissions standards, and sustainability procurement requirements continue to tighten across construction and industrial sectors, the ability to align product portfolios with next-generation environmental specifications has become a decisive commercial advantage. This study maps the regulatory trajectory and identifies formulation pathways that balance performance integrity with compliance readiness, enabling R&D and commercial teams to prioritize development roadmaps with confidence.
Supply chain resilience and raw material procurement represent additional focal points. The report dissects the underlying material architecture of MS polymer production, examining how backbone chemistry, silane end-group functionalization, and precursor sourcing strategies influence manufacturing economics and end-product performance. By contextualizing raw material dynamics within broader market pricing structures, the study provides procurement and manufacturing leaders with the analytical framework required to optimize input contracts, evaluate supplier diversification strategies, and anticipate cost dislocations before they impact margin profiles.
Competitive Landscape: Positioning, Differentiation, and Strategic Consolidation
The MS polymer competitive arena is defined by a concentrated yet dynamic roster of globally active producers and specialty chemical formulators. Market concentration indicators reflect a moderately consolidated environment, with leading participants leveraging proprietary resin architectures, established distribution networks, and cross-vertical application expertise to sustain commercial leadership. The strategic posture of these organizations varies considerably, ranging from vertically integrated resin originators to hybrid adhesive specialists and broad-platform industrial suppliers.
Kaneka Corporation maintains a differentiated position as the originator and leading global producer of MS polymer base resin technologies, with manufacturing operations spanning Japan, Belgium, the United States, and Malaysia. Its emphasis on high-performance silyl-terminated polyether chemistry has reinforced its role as a foundational supplier across construction, industrial, transportation, and DIY application channels. Sika AG commands a strong footprint as a major global supplier of MS polymer-based hybrid sealants and adhesives, prioritizing low-VOC elastic bonding solutions tailored to construction and industrial requirements. Henkel AG & Co. KGaA extends its portfolio through well-established consumer and professional brands, emphasizing region-specific formulations and broad DIY and construction segment penetration. Bostik, operating within the Arkema ecosystem, delivers low-odor, high-adhesion hybrid systems designed for construction, industrial, and transportation sealing and bonding applications.
Wacker Chemie AG contributes silyl-terminated polymer solutions and silicone-hybrid technologies, reinforcing its broader materials science capabilities across sealants, adhesives, and coatings. H.B. Fuller Company focuses on sustainable formulation development across packaging, construction, and industrial applications, aligning product strategy with evolving sustainability expectations. 3M Company leverages its performance materials heritage to supply high-performance MS polymer-based systems across industrial, construction, and transportation verticals. Dow Inc. integrates polymer technology expertise into hybrid adhesive and sealant formulation development, supporting broader construction and industrial deployment pathways.
Specialized and application-focused participants further intensify competitive dynamics. Tremco Illbruck and MAPEI S.p.A. concentrate on construction-oriented MS polymer adhesives and sealants, while Soudal Group has built recognition around hybrid MS polymer sealants with strong initial tack and multi-substrate adhesion profiles for professional and industrial utilization. Evonik Industries AG and AGC Chemicals supply critical silyl-terminated polymer materials and specialty chemical formulations that underpin downstream product development. Momentive Performance Materials contributes performance material expertise to hybrid polymer adhesive technologies, rounding out a highly interconnected supply and formulation network.
Strategic capacity and platform expansion activities underscore the intensity of current competitive positioning. In June 2024, Kaneka Corporation realized a significant capacity increase at its Belgium facility, expanding annual production to 43,000 tons to address sustained European demand. Sika AG announced European production capacity expansion for MS polymer-based adhesives in early 2025 to align with ongoing infrastructure and construction procurement momentum. More recently, in March 2026, Forza Inc. expanded its advanced MS polymer adhesive and sealant technology platform across construction, transportation, industrial manufacturing, marine, and composites applications, with explicit emphasis on strengthening made-in-USA supply chain positioning. These developments signal a market in which capacity readiness, geographic supply chain localization, and platform versatility are becoming defining competitive differentiators.
Industry Dynamics Shaping 2026 Strategy
The commercial environment surrounding MS polymer technologies continues to evolve in response to overlapping regulatory, economic, and technical pressures. Environmental compliance has transitioned from a procurement checkbox to a core product architecture requirement. MS polymer hybrid sealants and adhesives benefit from isocyanate-free, low-VOC, and solvent-free formulation profiles that align with increasingly stringent indoor air quality standards and emissions regulations across construction and industrial contexts. Companies that proactively integrate compliance-driven design into product development cycles are better positioned to secure specification approvals, meet public-sector procurement criteria, and capture premium positioning in environmentally sensitive application segments.
Worldwide MS Polymer Market
Raw material cost volatility remains a persistent strategic consideration. Fluctuations in polyurethane and silicone precursor pricing directly influence production economics and can compress margins if not addressed through proactive sourcing strategies, formulation optimization, or regional supply chain adjustments. The interplay between input cost variability and pricing power across downstream application verticals demands continuous cost-structure monitoring and scenario planning. Organizations that embed raw material sensitivity analysis into their commercial forecasting will be better equipped to maintain pricing discipline while protecting profitability.
Application-level demand divergence further shapes strategic prioritization. Building and construction continues to represent the most substantial demand driver, fueled by infrastructure modernization, façade bonding requirements, and mounting specification preference for durable, paintable, and environmentally compliant sealing solutions. Automotive and transportation applications leverage MS polymer hybrid systems for structural bonding, trim attachment, and vibration-damping applications where weight reduction and multi-material compatibility remain critical performance criteria. Industrial assembly and broader application segments contribute additional growth velocity through specialized bonding, sealing, and coating use cases that demand high initial tack, substrate versatility, and long-term elastic performance.
Capacity deployment and supply chain localization are emerging as decisive competitive levers. As regional demand patterns shift and procurement teams prioritize supply assurance, manufacturers that align production footprints with localized market requirements are gaining strategic advantage. This dynamic is particularly evident across European and Asia Pacific markets, where infrastructure-driven demand and regulatory-driven specification trends are reinforcing the need for proximate production capacity and responsive formulation support.
MS Polymer Hybrid Adhesives & Sealants Market
Translating Market Intelligence into 2026 Execution
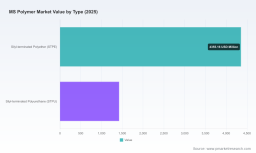
For enterprise strategists, regional commercial leaders, and product developers, the operational value of this research lies in its ability to convert complex market dynamics into prioritized decision pathways. Executive teams can utilize the market sizing framework to validate capital allocation assumptions, assess regional expansion feasibility, and calibrate growth forecasts against realistic demand trajectories. Competitive intelligence modules enable benchmarking of capacity strategies, product platform breadth, and application targeting against established incumbents and emerging platform expanders. R&D and formulation teams gain access to technology context that clarifies the performance and compliance implications of STPE versus STPU architectures, supporting more efficient development prioritization. Procurement and supply chain stakeholders benefit from structured visibility into raw material sensitivities, regional capacity deployment trends, and supplier positioning, enabling more resilient sourcing strategies and improved cost-risk management.
The study also addresses the strategic importance of portfolio alignment. As downstream customers increasingly consolidate their specification requirements around low-VOC, isocyanate-free, and solvent-free performance profiles, companies must ensure that product roadmaps, regional formulation capabilities, and technical support infrastructure are synchronized with procurement expectations. The research provides the analytical foundation required to assess where current portfolio strength is sufficient, where formulation investment is warranted, and where partnership or acquisition strategies may accelerate market access.
Strategic Imperatives and Forward Outlook
The worldwide MS polymer market is entering a phase in which structural demand, regulatory-driven formulation shifts, and competitive capacity deployment will collectively determine commercial winners. Organizations that approach 2026 planning with granular demand visibility, disciplined cost-structure awareness, and proactive competitive positioning will be best positioned to capture disproportionate share in high-growth application verticals and regions. The strategic window is narrowing for firms that rely on reactive forecasting or broad-based portfolio assumptions; the market now rewards organizations that combine technical differentiation with supply chain readiness and compliance-aligned product architecture.
Our Worldwide MS Polymer Market research delivers the depth, precision, and strategic framing required to navigate this environment with confidence. To access the complete regional demand breakdowns, application-level sizing, full competitive profiling, capacity deployment analysis, and forward forecasting models that underpin this strategic outlook, we invite you to review the full research publication. The comprehensive dataset and analytical frameworks contained within are designed to support immediate executive decision-making and long-range strategic planning across the entire forecast horizon.
For detailed analysis of this topic, please visit the official page: Worldwide MS Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com