

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Water Tube Industrial Boilers Market Hits $9.45B in 2025, Projects 4.51% CAGR Through 2032

Strategic Imperatives in the Global Water Tube Industrial Boilers Market (2026–2032)
The industrial steam generation sector is entering a decisive phase of structural transformation. As facilities navigate decarbonization mandates, shifting fuel economics, and the need for operational resilience, water tube industrial boilers have emerged as the preferred backbone for high-pressure, high-capacity thermal applications. PW Consulting's newly published Worldwide Water Tube Industrial Boilers Market report provides a comprehensive, decision-grade intelligence framework for executives, procurement leaders, and capital planners who must align technology selection, capacity expansion, and competitive positioning through 2032. This overview synthesizes the study's strategic architecture and demonstrates how its analytical layers translate into actionable corporate strategy for the 2026 planning cycle.
Commercial Boilers Market
Market Trajectory and the 2026–2032 Forecast Architecture
The global water tube industrial boiler market has demonstrated consistent, compounding revenue growth across the historical evaluation window, reflecting steady industrial expansion, modernization of aging thermal assets, and incremental capacity additions across process-intensive sectors. Building on this established trajectory, the forecast period projects continued medium-term expansion, with annual revenue progressing from a baseline just above nine thousand million USD in 2025 toward a materially higher valuation by 2032. The compound annual growth rate of 4.51 percent frames a market that is neither stagnant nor explosively volatile, but rather one characterized by sustained, technology-driven reinvestment. This growth cadence carries direct implications for capital allocation: engineering, procurement, and construction teams must plan for phased capacity deployment rather than single-cycle overhauls, while product developers and system integrators should calibrate manufacturing scaling and service-network investment to match a steady but increasingly competitive demand curve.
The study's temporal design spans historical performance from 2020 through 2025, anchoring trend analysis in a complete pre-forecast baseline, and extends forward through 2032 to capture multiple investment horizons. This structure allows decision-makers to separate cyclical fluctuations from durable secular shifts, particularly as fuel pricing volatility, emission regulation, and fuel-switching incentives reshape procurement economics. The forecast modeling integrates these variables into a structured revenue outlook, enabling scenario planning for capacity additions, retrofits, and replacement cycles without relying on speculative short-term indicators.
Segmentation Intelligence: Fuel, Application, and Regional Architecture
Effective market strategy depends on understanding where growth concentrates and how structural demand diverges across technology and end-use configurations. The report dissects the market across fuel type, application, and regional dimensions, revealing the operational and economic logic that shapes procurement priorities and technology roadmaps.
Fuel-type segmentation captures the ongoing transition within industrial thermal generation. Natural gas continues to anchor a substantial share of installed and projected capacity, favored for balancing efficiency, availability, and operational flexibility. Coal retains a meaningful footprint, particularly where legacy infrastructure, cost structures, or regional fuel access sustain its relevance. Biomass is gaining strategic attention as organizations pursue renewable heat pathways and leverage policy incentives, while oil and alternative fuel configurations persist in specialized or transitional applications. The study evaluates each fuel pathway not as a static share snapshot but as a dynamic selection environment, where operators weigh total cost of ownership, emissions compliance, supply-security considerations, and future-proofing against regulatory trajectories.
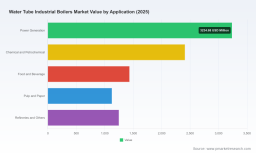
Application segmentation illuminates how industrial boiler demand maps onto distinct process requirements. Power generation represents a major demand pillar, driven by utility-scale and captive power needs where reliability and scale are paramount. The chemical and petrochemical sector follows closely, reflecting continuous-process steam requirements and stringent performance expectations. Food and beverage, pulp and paper, refineries, and other industrial verticals each present differentiated operating profiles, influencing boiler sizing, fuel compatibility, uptime demands, and service cadence. By mapping these application layers, the analysis equips manufacturers and service providers with a clearer view of where specification priorities diverge and where aftermarket and parts revenue opportunities accumulate.
Regional analysis situates these demand drivers within geographic market structures. Asia Pacific captures the largest revenue footprint, consistent with broad industrial expansion, infrastructure intensification, and manufacturing capacity growth across the region. North America and Europe represent mature but still evolving markets, shaped by efficiency mandates, retrofit cycles, and fuel-transition programs. Middle East and Africa and Latin America contribute distinct demand profiles, often linked to industrial diversification, resource-processing activities, and localized energy strategies. The study treats regional variation as a strategic variable rather than a static distribution chart, enabling readers to evaluate where localization, distribution partnerships, and specification adaptation will determine competitive performance.
Competitive Dynamics and Strategic Positioning
The market operates within a moderately concentrated landscape, where a core group of established manufacturers holds meaningful share while a broader field of specialists, regional producers, and technology-differentiated players competes on efficiency, customization, and service reach. The report's competitive architecture examines the positioning, product portfolios, and strategic orientations of leading participants, including Babcock & Wilcox, Cleaver-Brooks, Miura Boiler Co., Ltd., Indeck Power Equipment Company, Hurst Boiler & Welding Co., Unilux Advanced Manufacturing, LLC, Victory Energy, Rentech Boiler Systems, Thermax Limited, ZOZEN Boiler Co., Ltd., Bryan Boilers, Parker Boiler Co., and Babcock Wanson.
These companies illustrate the breadth of competitive approaches shaping the market. Some emphasize large-scale, customized industrial configurations with broad application coverage and long service histories, while others focus on modular, high-efficiency designs that reduce footprint, accelerate installation, and support lower-emission operation. Several players maintain strong regional manufacturing and distribution bases to serve localized demand, while others extend their reach through international project execution and cross-market product platforms. The study evaluates these strategies in terms of how they influence pricing architecture, specification competition, and customer-switching dynamics, helping readers understand where differentiation is sustainable and where commoditization pressure intensifies.
Beyond static profiles, the report integrates recent industry activity to show how competitive momentum is being created in real time. Display of eco-friendly water tube boiler solutions at a major trade exhibition in early 2026 signaled continued emphasis on low-emission, fuel-flexible product narratives. Parallel commissioning and conversion milestones elsewhere have demonstrated operational pathways toward oxy-combustion configurations and hydrogen-ready operation, indicating that technology leadership is increasingly tied to decarbonization capability rather than output capacity alone. Similarly, recent project awards for biomass-fired industrial boilers with advanced flue gas cleaning reflect growing execution activity in segments where policy incentives and corporate sustainability commitments are converging. For competitors and investors alike, these developments illustrate that the strategic battlefield is shifting toward fuel adaptability, emissions performance, and demonstration-scale credibility.
Worldwide Water Tube Industrial Boilers Market
Technology Trends and Regulatory Tailwinds
Industrial boiler strategy in 2026 cannot be separated from the broader decarbonization and efficiency agenda. Regulatory pressure, corporate net-zero commitments, and the economics of carbon exposure are aligning to create demand for boiler designs that can maintain reliability while accommodating cleaner fuel inputs and higher-efficiency operating modes. Oxy-combustion and hydrogen-ready capabilities are increasingly being incorporated into next-generation industrial boiler architectures, enabling organizations to align steam generation with advancing emission mandates and, in certain configurations, support high-efficiency carbon capture pathways. These design trends are not merely compliance features; they are becoming central to asset longevity, financing conditions, and the ability to operate under future fuel regimes without stranded-capacity risk.
At the same time, raw material economics are reshaping the cost environment for boiler manufacturing and replacement programs. Recent pricing movements for hot-rolled coil steel reflect a structural upward shift, influenced by demand patterns, supply conditions, and broader industrial input costs. For boiler OEMs, fabricators, and end-users planning retrofits or new installations, these input-cost dynamics affect equipment pricing, project budgeting, and procurement timing. The study places these material-cost signals in context, linking them to capacity planning, contract structuring, and the relative economics of new builds versus life-extension projects. This integration of macro input trends with market-level forecasting helps executives anticipate cost pressure rather than react to it after the fact.
A parallel trend is the accelerating adoption of biomass-fired water tube boiler configurations in sectors such as paper and packaging, where natural gas replacement strategies are being supported by government decarbonization programs and industrial sustainability initiatives. This shift highlights how policy-enabled fuel switching can reshape segment demand and alter the competitive value of fuel-flexible equipment. The report captures these dynamics as part of a broader transition narrative, showing where policy, technology, and industrial process requirements are reinforcing one another and where friction remains between legacy infrastructure and future fuel strategies.
What the Study Delivers for 2026 Decision-Making
The Worldwide Water Tube Industrial Boilers Market report is designed as an operational intelligence asset rather than a high-level overview. Its architecture supports multiple decision functions that are immediate priorities for 2026 planning:
- Demand and revenue context that frames the overall market trajectory and links historical performance to the forward forecast, giving executives a stable reference point for growth assumptions and capacity planning.
- Segment-level logic across fuel type, application, and region, enabling readers to identify where specification competition, aftermarket potential, and technology substitution are most active.
- Competitive landscape mapping that clarifies the strategic posture of leading manufacturers and highlights the differentiation levers shaping customer selection, including efficiency, modularity, emissions performance, and service infrastructure.
- Technology and regulatory alignment that connects boiler design evolution, fuel-flexibility trends, and decarbonization mandates to practical implications for procurement, retrofitting, and lifecycle planning.
- Input-cost and project-environment awareness that embeds raw material pricing signals and recent project activity into the market narrative, helping organizations interpret near-term cost and execution risk.
This combination of market structure, competitive intelligence, and trend integration allows the study to serve as a reference for capital investment decisions, product planning, regional expansion evaluation, and supplier selection. By organizing the market into decision-relevant layers, the report supports both corporate-level strategy and functional execution, whether the priority is entering a new application vertical, assessing a fuel-transition pathway, or benchmarking competitive position against established incumbents.
Why This Research Matters Now
The water tube industrial boiler market sits at the intersection of industrial reliability, fuel economics, and decarbonization pressure. In that position, it rewards organizations that can read structural shifts early and translate them into technology, sourcing, and geographic decisions before competitors lock in their responses. The 2026–2032 outlook presents a market expanding at a measured but meaningful pace, with growth distributed across fuel pathways, applications, and regions in ways that reward precision planning rather than generic assumptions.
PW Consulting's full study goes beyond the summary contours outlined here. It provides the deeper segmentation analysis, regional and application-level breakdowns, competitive positioning details, and scenario-supported forecast logic that executives need to convert market awareness into disciplined strategy. For teams preparing procurement roadmaps, product development plans, or investment evaluations, the complete report offers the contextual depth required to act with confidence in a market where efficiency, emissions performance, and fuel adaptability increasingly determine long-term value.
To access the full market intelligence, segmentation detail, and strategic analysis behind this overview, explore the complete Worldwide Water Tube Industrial Boilers Market report and integrate its findings into your 2026 decision framework.
For detailed analysis of this topic, please visit the official page: Worldwide Water Tube Industrial Boilers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com