

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Linear Sensors to Hit $4.3B in 2025, Growing 6.45% CAGR to $6.66B by 2032

Navigating the Automotive Linear Positions Sensors Market: Strategic Intelligence for 2026 and Beyond
The automotive industry is undergoing a profound transformation, driven by electrification, advanced driver-assistance systems, and increasingly stringent regulatory frameworks. At the heart of these technological shifts lies the critical need for precision measurement and feedback control. Automotive linear positions sensors have emerged as indispensable components, enabling everything from throttle control to suspension management. For stakeholders operating within this sector, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative.
Our latest comprehensive study, the Worldwide Automotive Linear Positions Sensors Market research, provides a definitive analysis of the industry landscape from 2020 through 2032. This report is designed to equip executives, investors, and engineering leaders with the actionable intelligence required to navigate the complexities of the forecasting period beginning in 2026. Below, we outline the strategic value of this research and the key dynamics shaping the future of linear position sensing in vehicles.
Executive Summary: Market Trajectory and Growth Potential
The global automotive linear positions sensors market has demonstrated resilient growth over the past five years, reflecting the broader trend toward sensorization in modern vehicles. Based on historical data from 2020 to 2025, the market has evolved from a valuation of approximately 3.12 billion USD to an estimated 4.30 billion USD in 2025. This upward trajectory is expected to continue robustly through the forecast period ending in 2032.
Our analysis projects that the market will reach a valuation of roughly 4.63 billion USD in 2026, growing at a Compound Annual Growth Rate (CAGR) of 6.45 percent. By the end of the forecast horizon in 2032, the revenue is anticipated to exceed 6.66 billion USD. This growth is not linear; it is influenced by varying adoption rates across vehicle segments, regional manufacturing shifts, and technological breakthroughs. The base year of 2025 serves as a critical anchor point, reflecting post-pandemic supply chain stabilization and the acceleration of next-generation vehicle platforms.
For decision-makers, these figures represent more than just revenue potential. They indicate the scale of opportunity for component suppliers, the volume of procurement required by original equipment manufacturers, and the intensity of competition likely to define the sector. Understanding where the market stands in 2026 versus where it is heading toward 2032 allows companies to align their capacity planning, R&D investments, and partnership strategies with long-term demand signals.
Strategic Segmentation: Technology and Application Landscapes
The market is multifaceted, driven by diverse technological approaches and a wide range of vehicular applications. Our research dissects these layers to reveal where value is being created and where vulnerabilities may exist.
Technology Analysis
Three primary technologies dominate the current landscape: Hall Effect, Inductive, and Potentiometric sensors, alongside emerging solutions such as Magnetostrictive systems. The Hall Effect technology currently commands a significant share of the market, favored for its non-contact nature, durability, and compatibility with modern electronic control units. Inductive sensors offer distinct advantages in harsh environments, providing cost-effective alternatives to traditional LVDTs with better tolerance to metal targets and misalignment. Potentiometric sensors remain relevant in specific cost-sensitive applications, though their mechanical wear limitations are driving innovation toward wear-free solutions.
The strategic implication for manufacturers lies in selecting the right technology mix for target applications. While Hall Effect solutions are prevalent in safety-critical and high-volume segments, inductive technologies are gaining traction in transmission and suspension systems where specific environmental tolerances are required. Our report details the performance metrics, cost structures, and adoption curves associated with each technology, enabling stakeholders to assess where their proprietary solutions fit within the broader ecosystem.
Application Analysis
Automotive linear positions sensors are deployed across several key vehicle systems, each with unique performance requirements. The Powertrain and Transmission segment represents a substantial portion of demand, driven by the need for precise control in engine management, throttle positioning, and increasingly complex transmission systems in both internal combustion and electrified vehicles. The Chassis and Suspension sector is another major growth driver, as luxury and mainstream vehicles alike adopt adaptive damping systems that rely on precise linear feedback.
Braking and Steering applications constitute a critical segment, particularly with the rise of electric power steering and advanced braking assist systems that require high reliability and redundancy. Meanwhile, the Body and Comfort segment, while smaller in relative volume compared to powertrain applications, offers opportunities in seat positioning, mirror adjustment, and other convenience features where cost optimization is paramount.
Understanding the revenue distribution across these applications is vital for targeting sales efforts and customizing product portfolios. Our research provides a granular view of how demand is shifting between these segments, influenced by regulatory mandates on safety and emissions, as well as consumer preferences for comfort and autonomy.
Regional Dynamics and Supply Chain Considerations
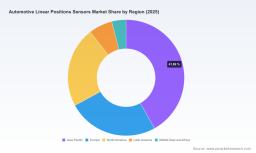
Geographic demand patterns reveal significant variations in adoption rates and manufacturing hubs. The Asia Pacific region stands as a dominant force in the market, reflecting the high volume of vehicle production in countries such as China, Japan, and South Korea. Europe remains a key market characterized by stringent emissions regulations and a strong presence of premium vehicle manufacturers, which drives demand for high-performance sensor solutions. North America continues to exhibit steady growth, supported by the commercial vehicle sector and an evolving regulatory landscape.
Latin America and the Middle East and Africa represent emerging opportunities, though they currently account for smaller shares of the global revenue mix. For companies looking to expand their footprint, understanding the local regulatory environments, supplier ecosystems, and customer preferences in these regions is essential. Our report analyzes the regional revenue splits and highlights the specific dynamics influencing procurement decisions in each geographic zone.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment is characterized by a mix of global giants and specialized niche players. Market concentration metrics indicate that while the top three companies hold a notable share of the market, the top five collectively command a larger portion, suggesting a moderately consolidated landscape with room for specialized competitors. The competitiveness of the market is further intensified by the technical barriers to entry and the long qualification cycles associated with automotive supply chains.
Several key companies define the current leadership positions.
Bosch
continues to be a global leader, supplying Hall-effect and other linear position sensors for a wide array of automotive applications including pedal position, suspension, and transmission systems.
Continental AG
provides a broad range of position sensors, including linear variants, for powertrain, chassis, and safety systems in passenger and commercial vehicles, leveraging its deep integration with vehicle platform development.
Worldwide Automotive Linear Positions Sensors Market
In the United States,
Honeywell International Inc.
offers non-contact Hall-effect linear position sensors and SMART Position Sensors designed for motion control in harsh automotive environments.
CTS Corporation
designs and manufactures both contacting and non-contacting Hall-effect linear position sensors for accelerator pedals, clutches, brakes, and emissions compliance applications.
Sensata Technologies
supplies the 9600 Series spring-return linear position sensors and other solutions tailored for space-constrained automotive feedback applications.
European presence is also strong, with
TE Connectivity
manufacturing linear and rotary position sensors for steering, chassis, and powertrain systems.
Infineon Technologies AG
develops magnetic and Hall-effect based sensor ICs used in linear position sensing for automotive safety and powertrain systems.
Piher Sensing Systems
specializes in custom inductive linear position sensors for automotive transmissions, suspensions, hydraulic cylinders, and steering systems.
Other notable participants include
Littelfuse
, which provides off-the-shelf and custom linear position sensors operating in static and dynamic magnetic fields, and
Phinia
, offering contact-free inductive linear position sensors for automated manual transmissions and gearbox solutions in commercial vehicles.
Vishay Intertechnology
produces Hall Effect-based linear position sensors, including recent models suitable for automotive motion control.
Allegro MicroSystems
supplies magnetic linear and angular position sensor ICs widely used in automotive applications, while
Novotechnik U.S., Inc.
offers wear-free linear position sensors for both automotive and industrial applications.
Recent developments underscore the dynamic nature of this competition. For instance, in March 2026, Vishay Intertechnology introduced the 40 LHE linear position sensor, a Hall Effect-based device featuring up to 40mm electrical stroke, ±1 percent linearity, and 12 micrometer resolution. Such product launches highlight the industry focus on enhancing resolution and stroke capabilities to meet evolving motion control requirements.
Market Dynamics: Regulations, Materials, and Innovation
The market is heavily influenced by external forces, particularly regulatory mandates and material science advancements. Automotive linear position sensors are engineered to support compliance with worldwide emissions and performance requirements in applications such as throttle control and exhaust systems. Similarly, linear position sensors for automated manual transmissions contribute to efficiency improvements in commercial vehicles under ongoing global emissions standards. As governments tighten regulations regarding fuel efficiency and pollutant emissions, the demand for precise sensing solutions that enable optimized engine and transmission performance is expected to rise.
On the technology side, inductive linear position sensors provide an alternative to LVDTs with advantages in cost and tolerance to metal targets and misalignment in automotive environments. This versatility makes them attractive for specific applications where robustness is prioritized. Additionally, the shift toward electrification and autonomous driving features is creating new requirements for sensors with higher reliability, longer lifespans, and integration capabilities with electronic control architectures.
Why This Report is Essential for 2026 Decision-Making
For organizations operating in or entering the automotive linear positions sensors market, access to accurate and forward-looking data is critical. This research report goes beyond high-level statistics to provide a deep dive into the factors driving growth, the challenges facing suppliers, and the opportunities emerging from technological shifts.
Worldwide Automotive Angular Position Sensor Market
Key deliverables include detailed segmentation analysis by region, technology, and application, allowing stakeholders to identify high-growth niches and assess competitive threats. The report also covers the competitive landscape, profiling major players and analyzing their strategic moves, product portfolios, and market positions. Furthermore, the inclusion of recent industry developments and regulatory contexts ensures that the analysis remains relevant to the current operating environment.
Investors can use this intelligence to evaluate market attractiveness and identify potential acquisition targets or partnership opportunities. Manufacturers can refine their product development roadmaps based on anticipated demand shifts and technology adoption curves. Procurement leaders can gain insights into supply chain dynamics and regional pricing trends. Ultimately, this report serves as a strategic compass, helping organizations navigate uncertainty and capitalize on the growth projected for the 2026 to 2032 period.
The automotive linear positions sensors market is poised for continued expansion, driven by the relentless push toward smarter, safer, and more efficient vehicles. By understanding the underlying drivers and competitive forces, stakeholders can position themselves to thrive in this evolving landscape. We invite you to explore the full findings of our research to gain the comprehensive insights necessary for informed strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Linear Positions Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com