

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global High Purity Lignin Market to Reach $69.18M by 2032, 7.21% CAGR

Global High Purity Lignin Market Outlook: Strategic Intelligence for the 2026 Business Cycle
The transition from fossil-based feedstocks to renewable biopolymers represents one of the most significant structural shifts in the global chemicals and materials landscape. As we move through 2026, high purity lignin has emerged as a critical enabler of this transition, offering viable pathways for decarbonization across adhesives, composites, carbon materials, and specialty chemicals. Our latest Worldwide High Purity Lignin Market research provides decision-makers with a rigorous, forward-looking intelligence framework designed to navigate capacity deployment, competitive positioning, and application commercialization over the 2026 to 2032 horizon.
For executives, investors, and strategy teams, the imperative is clear: market timing, technology selection, and partnership strategy will dictate who captures value in a rapidly maturing bio-based supply chain. This report delivers the granular market architecture, technology roadmaps, and competitive scaffolding required to make those decisions with confidence.
Market Trajectory and Growth Architecture
The global high purity lignin market has demonstrated sustained expansion over the past half-decade, driven by accelerating substitution demand, regulatory tailwinds, and scale-up activity across pulp-integrated and standalone biorefinery operations. Historical performance from 2020 through 2025 reflects a consistent upward trajectory, with total market revenue climbing from approximately 31.25 million USD to 42.5 million USD. The base year of 2025 anchors a forecast period that extends through 2032, during which the market is projected to expand at a compound annual growth rate of 7.21 percent.
This growth profile is not merely a function of volume scaling; it reflects a structural revaluation of lignin from a low-value pulp byproduct to a high-value, specification-driven biopolymer. Forecast trajectories through 2032 indicate continued appreciation, with revenue levels expected to surpass 69 million USD by the close of the forecast window. The compounding nature of this expansion underscores the importance of early-mover positioning, capacity alignment, and application-specific qualification timelines that can span multiple years in regulated end markets.
Several macro forces are reinforcing this trajectory. Stringent carbon policies and circular-economy mandates across Europe are accelerating lignin valorization through bioeconomy funding mechanisms and green public procurement frameworks. Simultaneously, regulatory pressure on traditional chemical inputs, including chrome restrictions in drilling fluids and expanding disclosure requirements on embodied carbon, is driving end-users to qualify lignin-based alternatives in construction and oilfield service applications. These demand-side catalysts are interacting with supply-side developments in separation technology, purification capability, and integrated mill economics to reshape the competitive landscape.
Segmentation Logic and Application Pathways
Understanding the market requires a clear grasp of how value is distributed across type, application, and geography. The report dissects the high purity lignin landscape across multiple segmentation dimensions, mapping revenue contribution, growth intensity, and adoption dynamics for each node without exposing the precise percentage splits that drive commercial negotiation leverage.
Lignin Type Landscape
The market encompasses distinct lignin categories, each with unique processing routes, purity profiles, and end-market suitability. Organosolv-derived lignin dominates value contribution, reflecting its broader compatibility with higher-specification applications and its alignment with specialty chemical and polymer formulation requirements. Kraft lignin represents the second major value pillar, benefiting from established black-liquor recovery infrastructure, large-scale global availability, and growing deployment in resin, composite, and carbon material pathways. Soda lignin occupies a smaller but strategically relevant position, serving niche formulation needs where specific solubility or reactivity characteristics are required.
Global production capacity dynamics further shape type-level competition. Kraft lignin availability has expanded substantially, with global production capacity reaching significant kiloton thresholds by 2023, reinforcing its role as a foundational feedstock for scale-driven substitution. Yet high purity requirements, consistency standards, and downstream qualification processes mean that capacity alone does not translate directly into market share. Purification capability, lot-to-lot consistency, and technical service support increasingly determine commercial outcomes.
Application End-Use Dynamics
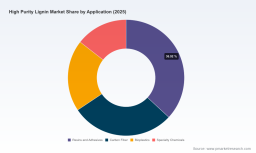
Demand is distributed across several high-growth application clusters, each with distinct qualification timelines, performance thresholds, and substitution economics. Resins and adhesives represent the largest application value pool, leveraging lignin as a renewable phenolic substitute and performance binder in engineered formulations. Carbon fiber and carbon material applications constitute a high-value secondary cluster, where lignin-derived precursors offer cost and sustainability advantages relative to conventional PAN-based routes, particularly as hard carbon and anode material development expands into next-generation battery chemistries. Bioplastics and polymer compounds form a growing segment, supported by patented transformation technologies that convert lignin into renewable thermoplastic and biomaterial grades. Specialty chemicals round out the application matrix, encompassing dispersants, binders, and functional additives where lignin's molecular architecture provides differentiated performance.
Geographic Distribution
Regional revenue distribution reflects the interplay of regulatory intensity, pulp and paper infrastructure density, and end-market demand maturity. Europe leads in value contribution, supported by ambitious bioeconomy policy frameworks, strong circular-economy procurement signals, and a dense concentration of technology developers and integrated producers. North America follows as a substantial value center, anchored by large-scale pulp operations, expanding lignin recovery investments, and growing qualification activity in construction, composites, and industrial applications. Asia Pacific and the Rest of World regions contribute incrementally but are gaining momentum as regional substitution demand, local formulation capabilities, and import-dependent supply chains evolve.
The report provides a complete geographic breakdown with market sizing, growth rates, and regional competitive mapping, but withholds granular regional percentage splits in this preview to preserve the analytical edge of the full dataset. Decision-makers requiring precise regional revenue allocations, localized demand forecasts, and country-level policy impact assessments will find those details within the complete report.
Competitive Landscape and Strategic Positioning
Market concentration is moderate, with the top three firms collectively capturing a significant share of total revenue and the top five firms extending that footprint further. This concentration profile signals a market in which scale, technology differentiation, and integrated supply relationships matter, but where specialized niche players and regional participants can still build defensible positions through purity, formulation expertise, and application-specific service models.
The competitive set includes globally established pulp-integrated producers, specialized lignin refiners, and technology-driven biomaterials developers. Borregaard brings over nine decades of experience in lignin-based biopolymers and lignosulfonates, delivering tailor-made high-purity solutions spanning dispersants, binders, and renewable alternatives to fossil chemicals. Stora Enso operates as the largest kraft lignin producer, leveraging its Lineo family of high-purity kraft lignin grades and NeoLigno binders for adhesives, composites, and carbon materials through its LignoBoost technology platform. UPM Biochemicals emphasizes consistent quality and formulation support for sustainable applications across resins, adhesives, binders, and polymer compounds. Mercer International produces high-quality lignin using the LignoBoost process across industrial applications, underpinned by sustainable forestry certifications that matter increasingly in procurement evaluations.
Regional specialization also shapes the field. Nippon Paper Industries stands as the only lignin manufacturer in Japan, offering a broad product range including SAN X, VANILLEX, and PEARLLEX grades for industrial uses. Domtar Corporation supplies high-purity kraft lignin under its BioChoice label from its Plymouth mill using LignoBoost, with a focus on sustainable lignin for binders and composites. West Fraser provides lignin products for bio-composites and binding agents derived from its pulp operations. Metsä Group develops modified lignin products such as Metsä LigO for concrete and other applications, expanding the scope of lignin-derived functional materials. Pure Lignin Environmental Technology Ltd. produces high-grade native-form lignin with purity levels reaching extremely high thresholds from biomass processing, targeting applications that demand specification-grade consistency. Lignin Industries develops lignin-based thermoplastics and biomaterials using patented technology to transform lignin into renewable plastics, illustrating the broader innovation curve beyond conventional extraction and purification.
Recent corporate activity highlights the pace of commercialization and partnership formation. In early 2025, LignEasy Oy shipped its first large-scale big-bag sample of a lignin-based product, signaling a transition from pilot-scale validation to early commercial distribution. Late 2024 saw Metsä Fibre develop a new lignin product at its Äänekoski demo plant for concrete applications aimed at replacing fossil-based chemicals. Mid-2024 brought a strategic partnership between Stora Enso and Altris to adapt lignin-derived hard carbon for anode material in sodium-ion batteries, expanding the addressable market into energy storage materials. Earlier in 2024, Lignin Industries raised over 2.2 million USD to strengthen its market position, expand its team, and increase manufacturing capacity for lignin-based bioplastics. These moves illustrate how the competitive field is being reshaped not only by production scale but by application innovation, partnership ecosystems, and targeted capital deployment.
Report Content and Operational Utility
The full research deliverable is structured to support concrete strategic workflows rather than abstract market commentary. It provides a comprehensive market sizing framework spanning historical years and the full 2026 to 2032 forecast period, with clear delineation between base-year validation and forward projections. Segmentation analysis covers type, application, and region, enabling users to isolate growth pools, assess substitution readiness, and identify where qualification cycles may create near-term opportunity or near-term risk.
Competitive profiling extends beyond static company summaries to include capacity positioning, technology platforms, product grade architecture, and strategic development activity. Industry context modules examine raw material availability, regulatory drivers, and processing economics, giving strategists a multi-variable lens on supply feasibility and demand durability. The report also integrates recent corporate developments, product launches, partnerships, and funding events, allowing readers to map the velocity of commercialization and detect emerging competitive threats or collaboration opportunities before they become widely priced into the market.
For commercial teams, the analysis supports application prioritization, pricing strategy, and customer qualification planning. For corporate development and investors, it offers a structured view of concentration dynamics, technology risk, and capacity expansion signaling. For sustainability and procurement functions, it provides a reference point for evaluating lignin-based alternatives against regulatory requirements, embodied carbon targets, and performance specifications.
Strategic Implications for 2026 Decision-Making
The 2026 decision environment demands a disciplined approach to market entry, partnership selection, and capacity alignment. Several strategic implications stand out.
First, value capture will increasingly attach to purity, consistency, and application-specific technical service rather than bulk availability alone. As end-users qualify lignin-based formulations in performance-sensitive markets, suppliers that can demonstrate lot-to-lot reliability, formulation support, and regulatory compliance will command stronger positioning.
Worldwide High Purity Lignin Market
Lignin Products Market
Second, partnership architecture is becoming a defining competitive variable. Collaborations that link lignin producers with downstream formulators, battery material developers, concrete additive specialists, and bioplastics manufacturers are accelerating qualification timelines and expanding addressable markets. Organizations that build or join these ecosystems early will be better positioned to shape specification standards and secure offtake alignment.
Third, regional policy intensity matters. Europe's regulatory and funding environment continues to support lignin valorization, while disclosure requirements and material substitution mandates in construction, oilfield, and industrial applications are expanding demand signals globally. Strategy teams should factor regional policy trajectories into capacity planning, go-to-market sequencing, and supplier selection.
Fourth, the market's moderate concentration profile means that both scaled incumbents and focused specialists can succeed, but via different playbooks. Incumbents leverage integrated mill economics, established recovery infrastructure, and broad grade portfolios. Specialists compete on purity ceilings, proprietary transformation technologies, and targeted application expertise. Understanding which model aligns with a given application pathway is essential for both procurement and investment decisions.
Conclusion
The high purity lignin market is transitioning from early-stage substitution interest to a more structured, specification-driven commercial landscape. The convergence of regulatory pressure, application innovation, and capacity expansion is creating a window in which informed strategic choices can materially affect competitive outcomes over the remainder of the decade. Our Worldwide High Purity Lignin Market research is designed to provide the depth, segmentation clarity, and competitive intelligence required to operate with precision in that environment.
The preview above highlights the structural framework, growth trajectory, segmentation logic, and competitive dynamics that define the market. The complete report delivers the full quantitative architecture, regional and application-level breakdowns, detailed company profiles, and forward-looking scenario analysis necessary for decisive 2026 planning. Readers seeking the complete dataset, exact segmentation values, and the full analytic toolkit are encouraged to access the full study for comprehensive market intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide High Purity Lignin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com