

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Buruli Ulcer Treatment Market Hits $78.45M in 2025, Expected 4.8% CAGR to $108.92M by 2032

Strategic Intelligence for a Neglected Tropical Disease: The Business Case for the 2026-2032 Buruli Ulcer Treatment Market
In the world of global health strategy, few challenges are as complex as allocating commercial resources toward Neglected Tropical Diseases (NTDs). Buruli ulcer, caused by Mycobacterium ulcerans, remains one of these enigmatic conditions. It is a disease where clinical urgency intersects with a constrained commercial landscape, driven by WHO-supported free treatment programs in endemic regions. For pharmaceutical manufacturers, medical device suppliers, and healthcare investors, understanding the economic nuance of this sector is not merely an academic exercise—it is a prerequisite for strategic positioning.
As we release our latest comprehensive analysis, the Worldwide Buruli Ulcer Treatment Market, our goal is to provide a clear lens through which to view a market characterized by steady growth, defined therapeutic protocols, and a highly specific supply chain dynamic. This article serves as a strategic preview of our findings, highlighting the macro-trends and structural realities that will define the investment landscape from 2026 through 2032. We delve into the market size trajectories, therapeutic segmentation, and the competitive ecosystem dominated by generic antibiotic suppliers and WHO prequalification pathways, while deliberately reserving the granular, actionable breakdowns for our full paid intelligence report.
Decoding the Growth Trajectory: A Macro-Economic View
The commercial story of Buruli ulcer treatment begins with a baseline understanding of market scale and velocity. Our historical analysis captures the market's evolution over the past half-decade, revealing a sector that has navigated the post-pandemic recovery with resilience. The global revenue generated by Buruli ulcer treatments expanded from approximately 62.15 million USD in 2020 to 78.45 million USD in 2025, reflecting a compound annual growth rate that underscores persistent demand despite the niche nature of the disease.
Worldwide Monkeypox Treatment Market
Projecting forward, the forecast period of 2026 to 2032 indicates a continuation of this positive trajectory. The market is anticipated to reach a valuation of 108.92 million USD by 2032. This growth is powered by a CAGR of 4.8 percent, a figure that may appear modest compared to high-growth biotech sectors, yet it represents a robust, steady expansion for a therapy area heavily reliant on essential medicines and public health infrastructure. This growth is not driven by price inflation or novel blockbuster drugs, but rather by the scaling of treatment access, improved case detection in West Africa, and the sustained procurement of generic antibiotics and wound care supplies under national program frameworks.
Strategic observers should note that this CAGR reflects a baseline expansion. In our full report, we dissect the variance across different therapeutic modalities and regional procurement cycles, identifying pockets of higher growth intensity that are critical for supply chain planning. However, the headline trajectory confirms that the market is stabilizing and growing, offering a predictable environment for stakeholders who can navigate the volume-based, low-margin economics of generic antibiotic supply.
The Clinical Imperative: Treatment Modalities and Market Segmentation
The Buruli ulcer treatment market is not a monolith; it is defined by WHO guidelines that dictate a multidisciplinary approach. The standard of care, reaffirmed in the October 2023 WHO guideline update, recommends eight weeks of daily rifampicin and clarithromycin as first-line therapy. For advanced lesions, surgery and wound management remain indispensable. This clinical reality directly shapes the revenue streams of the market.
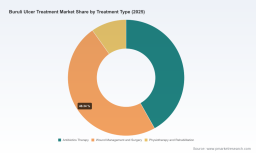
Our segmentation analysis categorizes the market by treatment type, end-user, and region, providing a three-dimensional view of where value is captured. The treatment landscape is dominated by wound management and surgery, alongside antibiotic therapy. These two pillars account for the bulk of market activity, reflecting the dual challenge of infectious eradication and tissue repair. While antibiotic regimens rely heavily on fixed-dose combinations and generic sourcing, the wound management component encompasses surgical interventions and rehabilitation services, which vary significantly by the degree of lesion severity and the healthcare infrastructure available in endemic countries.
Physiotherapy and rehabilitation also constitute a distinct segment, addressing the functional recovery required after severe ulceration. This niche, though smaller in revenue proportion, is critical for long-term patient outcomes and represents an area where specialized service providers and rehabilitation equipment suppliers can find strategic entry points, particularly in regions strengthening their post-treatment care networks.
In terms of end-user distribution, hospitals and specialized clinics naturally command the largest share of treatment volume. These facilities handle the bulk of surgical interventions and severe cases. Ambulatory surgical centers and homecare settings follow, representing channels that are increasingly relevant as healthcare systems in endemic regions decentralize care to reduce the burden on major tertiary institutions. The allocation of treatment across these settings is deeply influenced by reimbursement structures; notably, in many endemic areas including West Africa, treatment is provided free through WHO-supported national programs, fundamentally altering the traditional payer dynamics seen in commercial pharmaceutical markets.
Geographically, the disease burden is overwhelmingly concentrated. Over 90 percent of cases are reported in West Africa, making this region the epicenter of demand. However, the market's regional profile also includes Asia Pacific, the Americas, and Europe and others, where surveillance programs, imported cases, and specialized clinic management create smaller but operationally significant demand streams. Australia, for instance, maintains robust surveillance despite declining incidence, sustaining a specialized treatment niche. Our report maps these regional dynamics in detail, quantifying the relative weight of each geography without relying on simplistic percentage splits that obscure local procurement nuances.
The Supply Chain Reality: Generic Antibiotics and Prequalification Pathways
A defining characteristic of the Buruli ulcer treatment market is its reliance on generic antibiotics sourced from a concentrated manufacturing base. The commercial incentive for developing novel branded therapies for NTDs is low; consequently, the supply chain is anchored by established generic manufacturers who can produce rifampicin, clarithromycin, and combination packs at scale. India has emerged as a pivotal hub in this ecosystem, with manufacturers aligning their production with WHO prequalification standards to access procurement contracts for national programs.
This reliance on generic supply introduces specific strategic considerations. Market concentration is evident, with a handful of key players capturing a significant portion of the value chain. The CR3 and CR5 metrics highlight the consolidated nature of the competitive landscape, where a few large suppliers of WHO-prequalified essential medicines dominate volume procurement. For new entrants, the barrier to entry is not just manufacturing capacity but also the rigorous qualification process and the ability to meet the consistent quality requirements of global health buyers.
Recent developments underscore the importance of this prequalification pathway. For example, WHO updates in October 2023 confirmed rifampicin-clarithromycin as the first-line regimen, reinforcing the demand stability for these molecules. Simultaneously, suppliers like Macleods Pharmaceuticals have secured WHO prequalification for fixed-dose combinations specific to multidrug therapy, positioning themselves as preferred vendors for large-scale health initiatives. Other major generic players, including Cipla and Sandoz, also contribute to the supply of rifampicin and clarithromycin, maintaining a competitive yet coordinated environment where volume and compliance drive procurement decisions.
Strategic decisions regarding supply chain partnerships, distribution agreements, and manufacturing investments must account for this prequalification reality. Our analysis examines the profiles of these core companies, their headquarters, their product portfolios, and their positioning within the WHO prequalification framework. However, the exact share of each competitor, their specific contract volumes, and the detailed pricing dynamics across different procurement rounds remain critical intelligence for corporate strategy. We reserve these deep competitive dossiers and the full financial profiling of key suppliers for the complete market report, where clients can benchmark their positioning against the actual market leaders.
Worldwide Buruli Ulcer Treatment Market
Implications for 2026 Decision-Making: Where Strategy Meets Execution
As organizations look toward 2026 and beyond, the Buruli ulcer treatment market presents a set of strategic questions that require more than high-level observations. For generic antibiotic manufacturers, the opportunity lies in expanding prequalified product lines, optimizing cost structures to remain competitive in volume tenders, and potentially exploring fixed-dose combinations that simplify regimen adherence. The market's dependence on Indian-sourced generics also opens avenues for regional supply chain diversification, an increasingly relevant consideration given global logistics volatility.
For medical device and wound care suppliers, the market offers a different value proposition. The emphasis on surgery and wound management for advanced cases creates demand for surgical consumables, dressing materials, and rehabilitation tools. However, access to this segment is mediated by the public health infrastructure and the funding mechanisms of national programs. Understanding which facilities are expanding surgical capacity, how reimbursement flows for non-drug interventions, and where home-based wound care is emerging are all strategic puzzles that our report's regional and end-user breakdowns address.
Investors and strategy teams must also navigate the risk factors inherent in NTD markets. The reliance on free treatment through WHO-supported programs means that revenue is tied to the continuity of donor funding and government health budgets. Policy shifts, changes in case reporting, or the introduction of alternative therapeutic protocols could alter demand patterns. Conversely, increased case detection through improved surveillance in West Africa could drive volume growth, while the absence of a specific vaccine means that treatment remains the primary intervention for the foreseeable future. These dynamics require scenario planning that goes beyond a single-point forecast.
Our report provides the tools for this planning. It integrates regulatory updates, reimbursement contexts, and raw material dependencies into a cohesive strategic framework. We analyze the impact of the WHO's eight-week regimen on procurement cycles, the implications of low commercial market incentives on supply resilience, and the regional variations in case management that affect product mix. For decision-makers, this translates into actionable intelligence on where to allocate resources, which partnerships to prioritize, and how to structure supply agreements to capture growth in a responsible and sustainable manner.
Inside the Report: What Comprehensive Intelligence Delivers
This article has outlined the macro landscape, the segmentation logic, and the competitive forces shaping the Buruli ulcer treatment market. Yet, the true value of our Worldwide Buruli Ulcer Treatment Market research lies in the depth of detail that only a full strategic assessment can provide. Our report goes beyond the top-level revenue figures and CAGR to deliver operational intelligence.
Clients will gain access to a granular segmentation of the market by treatment type, end-user, and region, with detailed revenue breakdowns and growth rates that allow for precise sizing of opportunity pockets. We map the competitive landscape with individual company profiles, prequalification status, and strategic positioning, enabling benchmarking against WHO-prequalified suppliers and other generic manufacturers. The report also features a deep dive into recent developments, including guideline updates from WHO and prequalification milestones, contextualizing these events within the market's evolution.
Furthermore, the analysis incorporates a thorough examination of market dynamics, including regulatory frameworks, reimbursement mechanisms, and raw material dependencies. This contextual layer is essential for understanding the constraints and enablers of market growth. Our forecast models provide scenario-based projections that account for variations in case detection, funding continuity, and supply chain resilience, giving clients a robust foundation for strategic planning in 2026 and the forecast period through 2032.
The report is designed for strategic consultants, pharmaceutical and medical device executives, procurement specialists, and investors who need to move from general awareness to precise, data-driven action. By combining macro market size analysis with micro-level segmentation and competitive profiling, it serves as a comprehensive guide to navigating a market defined by public health imperatives and specialized supply chain requirements.
Conclusion: Positioning for Growth in a Defined Niche
The Buruli ulcer treatment market is a compelling example of a healthcare sector where impact and commerce intersect within a constrained but steadily expanding framework. Growth is anchored in essential medicines, standardized regimens, and public health programs, yet it offers meaningful opportunities for stakeholders who understand the nuances of prequalification, regional demand concentration, and the segmentation of care delivery. The projected revenue trajectory through 2032 reflects a market that is maturing in its structure while retaining the capacity for volume-driven expansion.
For organizations preparing their 2026 strategies, the imperative is clear: engagement with this market requires a deep understanding of the WHO-aligned treatment protocols, the competitive dynamics of generic antibiotic supply, and the regional realities of disease burden and healthcare infrastructure. Our full report delivers this understanding with rigor and precision, providing the granular data and strategic context necessary to make informed decisions. We invite you to access the complete Worldwide Buruli Ulcer Treatment Market intelligence to unlock the full spectrum of insights, segmentations, and competitive benchmarks that will guide your path forward in this vital and evolving sector.
For detailed analysis of this topic, please visit the official page: Worldwide Buruli Ulcer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com