

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Liquid Termiticides Market Hits $2.85B in 2025, Projected 5.12% CAGR to 2032

Strategic Intelligence in Global Pest Management: Decoding the Worldwide Liquid Termiticides Market Outlook 2026–2032
Urbanization, climate-induced pest migration, and tightening regulatory frameworks are reshaping the structural pest control landscape. At the center of this transformation lies the liquid termiticide segment, a critical tier within the broader crop protection and professional pest management ecosystem. As property development expands across emerging regions and older infrastructures demand rigorous post-construction interventions, stakeholders require more than aggregate industry rhetoric. They need a disciplined, data-grounded view of market mechanics, competitive positioning, and the evolving cost structure that defines profitability. PW Consulting’s latest research initiative, the Worldwide Liquid Termiticides Market study, delivers precisely that calibrated intelligence for executive teams, procurement leaders, R&D strategists, and investment analysts preparing for the 2026 decision cycle.
This market intelligence briefing is designed to function as a strategic compass. It translates multi-year historical performance, forward-looking growth trajectories, and structural market forces into actionable frameworks. Rather than offering superficial category summaries, the study dissects the operational realities that determine market share, margin resilience, and regulatory compliance readiness. The following sections outline the analytical architecture of the report, highlight the core dynamics shaping the sector, and illustrate how decision-makers can convert these insights into defensible market positioning over the next seven years.
Market Architecture and Growth Trajectory
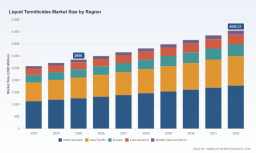
The worldwide liquid termiticides market has demonstrated consistent expansion over the historical analysis window, driven by sustained demand for soil-applied structural protection and professional pest management services. The market reached an estimated valuation of 2850.0 million in the 2025 base year, reflecting a steady upward arc from the 2023 baseline of 2579.14 million and the 2024 reading of 2711.19 million. This trajectory underscores a segment that has matured beyond cyclical dormancy and now operates with predictable resilience, even as input costs and regulatory pressures fluctuate.
Looking ahead, the forecast horizon extending through 2032 positions the market for continued expansion, with the projected figure reaching 4042.31 million by the end of the period. This escalation is anchored by a forecast compound annual growth rate of 5.12 percent across the 2026–2032 interval. For strategic planners, this growth rate is not merely a statistical marker; it signals a market in which incremental share gains, formulation optimization, and channel efficiency will increasingly separate high-performing operators from those reliant on legacy pricing models. The transition from 2995.92 million in 2026 to 3149.31 million in 2027, and onward through successive annual milestones, reflects a compounding environment where product differentiation, application methodology, and regulatory agility become decisive competitive levers.
Within this landscape, the study systematically maps how market value is distributed across operational and geographical dimensions, providing a structural reference for capacity planning and regional go-to-market design. The segmentation architecture reveals that non-repellent liquid termiticides command the larger share of market activity at 1824.0 million, while repellent liquid termiticides account for 1026.0 million. This bifurcation is highly instructive for product portfolio strategy. Non-repellent chemistries tend to benefit from transfer-effect dynamics and soil penetration characteristics that appeal to integrated pest management protocols, whereas repellent formulations maintain relevance in specific barrier-use scenarios where immediate avoidance behavior is operationally desirable. Understanding the strategic implications of these two technology streams—and how their relative positioning shifts in response to active ingredient availability, resistance management concerns, and applicator preference—is central to formulation roadmapping and commercial messaging.
The application dimension further sharpens the market lens. Post-construction treatment remains the dominant deployment context at 1653.0 million, reflecting the ongoing need to retrofit existing structures against subterranean termite pressure. Pre-construction treatment contributes 1197.0 million, highlighting the embedded role of soil preparation and barrier establishment during new building cycles. These two application pathways are not interchangeable from an execution standpoint. Post-construction work involves access constraints, treatment precision, and customer communication challenges, while pre-construction interventions are tightly coupled with construction timelines, contractor coordination, and formulation application standards. The report provides decision-makers with the operational context needed to align product offerings, sales force specialization, and service-delivery models with the distinct economics of each use case.
Geographically, the market exhibits a pronounced concentration of activity in North America at 1254.0 million, followed by Asia Pacific at 855.0 million, Europe at 342.0 million, Latin America at 285.0 million, and the Middle East and Africa at 114.0 million. This distribution is not a simple function of property stock; it integrates regulatory maturity, professional pest control penetration, housing and infrastructure investment cycles, and the localization of distribution networks. For multinational manufacturers and regional formulators alike, these geographic gradients inform where to prioritize formulation registration, where to invest in technical sales coverage, and where to anticipate shifts in competitive intensity as local players expand their registered portfolios.
Competitive Positioning and the Shape of the Industry Landscape
The liquid termiticide sector is characterized by a moderately consolidated competitive structure. The study quantifies this concentration through a CR3 of 42.5 percent and a CR5 of 58.8 percent, indicating that a small group of leading enterprises holds a substantial portion of market value, while a broader field of specialty manufacturers, regional suppliers, and generic formulation houses competes for the remainder. In practical terms, this means that scale, registration portfolios, technical service capability, and supply continuity are decisive elements of competitive advantage. It also means that market entry and share expansion strategies must be carefully calibrated, particularly where incumbents have deep-rooted relationships with professional applicators and established placement in procurement specifications.
BASF SE, headquartered in Ludwigshafen, Germany, is positioned around a well-recognized termiticide portfolio that includes Termidor SC, Termidor HE High-Efficiency, and Termidor HP II liquid termiticides for both pre- and post-construction soil treatments against subterranean termites. Its product architecture illustrates the strategic importance of tiered offerings that address varying application efficiencies, soil conditions, and customer throughput requirements. Syngenta AG, based in Basel, Switzerland, brings a reduced-risk, chlorantraniliprole-based approach through its Altriset termiticide, a liquid soil-applied product designed for indoor and outdoor structural protection with low mammalian toxicity. This positioning reflects a broader industry pivot toward active ingredients and formulations that align with evolving stewardship expectations and customer sensitivity to handler safety.
FMC Corporation, with headquarters in Philadelphia, USA, supplies bifenthrin and other pyrethroid-based liquid termiticides for professional pest management, anchoring its relevance in well-established active ingredient families that are widely understood by applicators and integrated into standard treatment protocols. Bayer AG, located in Leverkusen, Germany, offers imidacloprid-based liquid termiticides such as Premise for soil barrier treatments in residential and commercial structures, reinforcing the importance of chemistry breadth and multi-market applicability. Nufarm Limited, from Melbourne, Australia, produces and supplies a range of insecticide formulations including liquid termiticides for professional pest control markets, representing the strategic role of agile manufacturing and international distribution in serving varied regional demand profiles. Sumitomo Chemical Co., Ltd., in Tokyo, Japan, develops and markets synthetic pyrethroid and other active ingredient-based liquid termiticides for global structural pest control, highlighting the relevance of Asian innovation capacity and export-oriented formulation strategy.
The competitive field also includes specialized players with focused operational models. Control Solutions Inc., based in Pasadena, USA, manufactures and distributes liquid termiticide products including generic formulations of fipronil and bifenthrin for professional use, demonstrating how cost-structured alternatives can gain traction where applicators prioritize economic efficiency and compatible performance characteristics. Ensystex Inc., located in Fayetteville, USA, provides liquid termiticide options alongside bait systems for comprehensive termite management, underscoring the growing importance of integrated solution design rather than single-product competition. Across these profiles, a consistent strategic theme emerges: competitive advantage is increasingly defined not only by chemistry, but by the ability to bundle technical support, regulatory readiness, application guidance, and supply reliability into a coherent value proposition for professional channels.
Regulatory Flux, Input Economics, and Structural Market Dynamics
Market performance in the liquid termiticide segment does not evolve in a vacuum. It is shaped by regulatory developments, active ingredient economics, and supply chain conditions that collectively influence cost structures, product viability, and time-to-market for new formulations. One of the most consequential recent regulatory updates occurred in November 2025, when the U.S. Environmental Protection Agency established a time-limited tolerance for residues of chlorantraniliprole in or on rice grain at 15 ppm, expiring December 31, 2028. While this action is framed around agricultural residue tolerances, its strategic relevance for the termiticide market lies in the broader signal it sends regarding chlorantraniliprole’s regulatory treatment and the continuing scrutiny applied to active ingredients with dual-use implications. For product managers and regulatory affairs teams, such developments require continuous monitoring because tolerance frameworks, use patterns, and species-protection measures can affect formulation strategy, labeling flexibility, and customer confidence.
In April 2025, the U.S. EPA released the final Insecticide Strategy intended to reduce exposure of federally listed endangered species from conventional agricultural insecticides, including mitigation measures applicable to termiticide use patterns. This policy direction reinforces a regulatory environment in which environmental stewardship, non-target organism protection, and application-method accountability are increasingly embedded in operational decision-making. At the same time, the broader active ingredient landscape is being shaped by restrictions on certain chemistries. Fipronil and imidacloprid use in agriculture is severely restricted in the US and EU due to acute toxicity to non-target arthropods, particularly pollinators. These limitations do not merely affect crop protection markets; they reverberate into structural pest control by influencing active ingredient availability, registration momentum, substitution dynamics, and perceived chemical risk among applicators and end customers.
On the input side, the sector has absorbed meaningful cost pressure. The price of fipronil and bifenthrin, common active ingredients in liquid termiticides, increased by 16 percent between 2022 and 2024. This movement matters because active ingredient cost is a primary driver of formulation economics, margin design, and pricing strategy. In a market where product performance, regulatory status, and applicator acceptance all hinge on chemistry choice, ingredient cost inflation can compress profitability unless manufacturers and distributors actively manage sourcing strategy, product mix, and value-based pricing. Compounding these pressures, supply chain disruptions for specialty chemicals due to geopolitical tensions and transportation bottlenecks have affected production capacities of liquid termiticide manufacturers. The practical consequence is that supply continuity has become a strategic asset. Companies that can maintain stable production pathways, diversify sourcing where feasible, and provide reliable fulfillment timelines are better positioned to retain professional channel trust, especially during periods when competitor shortages or lead-time variability create procurement uncertainty.
What the Study Delivers: Analytical Depth, Practical Utility, and Decision-Ready Structure
The Worldwide Liquid Termiticides Market research is engineered to translate complex industry signals into clear operational guidance. It does so through a layered analytical design that links macro market behavior to the tactical decisions made by commercial, supply chain, and regulatory teams. The study maps historical performance and projected growth in a way that helps leadership test assumptions about demand durability and investment timing. It situates product categories and application contexts within the broader ecosystem so that portfolio decisions reflect real-world deployment conditions rather than abstract category definitions. It also contextualizes competitive activity by examining how established players and specialized manufacturers structure their offerings, where they derive differentiation, and how concentration dynamics influence pricing and channel access.
Beyond top-line market sizing, the research emphasizes the operational drivers that determine commercial outcomes. This includes the interplay between non-repellent and repellent technology streams, the economics of pre-construction versus post-construction deployment, and the geographic nuances that shape registration priorities, distribution strategies, and technical service intensity. The report also integrates market dynamics that are directly relevant to cost planning and risk management, including regulatory trajectory, active ingredient price behavior, and the operational implications of specialty chemical supply constraints. By linking these forces to competitive strategy, the study helps organizations anticipate where margin pressure may intensify, where product substitution could accelerate, and where market access may become more demanding due to compliance or stewardship requirements.
Liquid Copper Fungicide Market
This is not a static snapshot. The study is structured to support scenario thinking, allowing decision-makers to evaluate how changes in construction activity, professional pest control adoption, regulatory interpretation, and input cost trends could affect strategic priorities across the forecast period. It provides a coherent framework for assessing whether to expand into new formulations, deepen presence in priority geographies, refine channel partnerships, or strengthen supply-side resilience. In doing so, it converts raw market intelligence into a usable strategic asset.
Strategic Use Cases for the 2026 Decision Cycle
For R&D and formulation teams, the report offers a structured basis for prioritizing active ingredient and delivery-system development. By clarifying how product categories perform across applications and regions, it helps identify where technical differentiation is most likely to yield commercial returns and where competing on cost or convenience may be more appropriate. For procurement and supply chain leaders, the study frames the market in terms of concentration, input cost volatility, and supply continuity risk, supporting more informed sourcing strategies and inventory planning in an environment where specialty chemical availability can shift quickly.
For commercial and sales leadership, the segmentation and geographic context provides a foundation for territory planning, channel specialization, and value proposition design. Understanding the distinct operational characteristics of post-construction and pre-construction deployments, as well as the relative scale of non-repellent and repellent formulations, enables more precise alignment between product messaging, applicator training, and customer engagement models. For corporate strategy and investment teams, the competitive concentration data, company profiles, and regulatory developments create a practical basis for evaluating market entry opportunities, partnership potential, and long-term positioning in a segment where incumbency advantages and registration assets carry substantial weight.
Conclusion
The worldwide liquid termiticides market is entering a phase in which durable growth must be paired with disciplined strategic execution. The 2025 baseline of 2850.0 million and the forward path toward 4042.31 million by 2032, supported by a CAGR of 5.12 percent, defines a market with meaningful scale and continued expansion potential. Yet the real strategic challenge lies in navigating the forces that shape competitive advantage within that growth: technology preference across non-repellent and repellent categories, the economics of post-construction and pre-construction applications, geographic demand distribution, regulatory evolution, input cost inflation, and the supply chain vulnerabilities that affect production continuity. PW Consulting’s Worldwide Liquid Termiticides Market research is built to address these complexities with analytical rigor and practical relevance. It equips organizations with the evidence base needed to make informed decisions in 2026 and beyond, while preserving the deeper segmentation detail, competitive intelligence, and scenario-level analysis that executive teams require to act with confidence.
Worldwide Liquid Termiticides Market
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Termiticides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com