

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Multiwall Paper Bags Market 2026: Why the 4.5% CAGR and $244.7M Outlook Changes Everything
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Multiwall Paper Bags Market
Navigating Transition: Market Overview and Key Challenges
The multiwall paper bags market has established itself as a critical component of industrial packaging, serving sectors ranging from construction to agriculture. Over the past five years, the market has demonstrated steady expansion, with revenue climbing from approximately 135.4 million U.S. dollars in 2020 to an estimated 179.5 million in 2025. This trajectory reflects a compound annual growth rate of 4.5 percent, positioning the sector for continued moderate expansion through 2032, when revenues are projected to approach 244.7 million U.S. dollars. While the growth profile is stable rather than explosive, the underlying dynamics are shifting in ways that create meaningful strategic implications for manufacturers, investors, and procurement leaders.
The market structure remains relatively fragmented at the top, with the top three players collectively holding about 22.4 percent of revenue and the top five accounting for 28.7 percent. This concentration level indicates a landscape where scale advantages exist but do not fully dictate outcomes, leaving room for regional specialists and product-focused innovators to compete effectively. The distribution of revenue across regions shows North America as the largest contributor, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but growing shares. Across product types, kraft paper continues to anchor the market, while coated and recycled variants occupy meaningful niches. On the application side, building materials represent the largest end-use segment, with agriculture, chemicals, food, and minerals following in varying degrees of demand intensity.
Despite the constructive growth baseline, the industry is confronting several transition points that will shape competitive outcomes over the next five years. First, volatile raw material costs are compressing margins and forcing manufacturers to rethink procurement strategies and pricing models. Second, regulatory frameworks are accelerating the shift away from plastic-heavy multilayer sacks toward fully recyclable paper-based solutions, raising compliance costs but also opening differentiation opportunities. Third, demand patterns are evolving as end-users prioritize sustainability credentials, moisture resistance, and supply chain reliability, pushing suppliers to balance performance with environmental claims. These challenges are not merely headwinds; they are re-shaping the criteria by which companies win or lose in the market.
Key Drivers Reshaping the Landscape
Regulatory and compliance pressures are among the most consequential forces currently influencing the market. The EU Packaging and Packaging Waste Regulation, which begins applying from August 2026, requires improved recyclability documentation and labeling compliance for packaging, including multiwall paper bags. By 2030, all packaging must be recyclable, a mandate that favors sack kraft paper over multilayer sacks with high plastic content in multiwall applications. In parallel, plastic bag bans in various regions are compelling manufacturers to pivot toward sustainable, recyclable, and biodegradable materials as compliant alternatives. These regulatory shifts are raising the bar for product design and documentation, but they also reward suppliers that can demonstrate credible recyclability and reduced plastic use.
Raw material dynamics are equally central to the market's evolution. Benchmark kraft linerboard prices surged by 22 percent year-on-year in 2023 due to constrained supply and high energy costs, and volatility has persisted into subsequent periods. Fluctuating prices for paper and adhesives continue to challenge manufacturers, as rising input costs directly impact production economics and profit margins. This environment favors companies with vertically integrated production, diversified sourcing, and the ability to pass through cost adjustments without eroding customer relationships. It also incentivizes material efficiency innovations that reduce weight or improve strength-per-unit, helping to offset cost pressure while meeting performance requirements.
Kraft Paper Bag Market
Demand-side behavior is shifting in ways that reward performance and sustainability simultaneously. End-users in building materials, agriculture, chemicals, and food sectors are increasingly scrutinizing packaging for moisture resistance, durability, and environmental impact. For humidity-sensitive products, the ability to maintain integrity without relying on plastic layers has become a competitive differentiator. At the same time, procurement teams are seeking suppliers that can provide consistent quality, flexible sizing, and transparent sustainability credentials. These expectations are pushing manufacturers to invest in product development that addresses both functional and regulatory demands, rather than treating sustainability as a separate initiative.
Technology and process innovation are beginning to play a more visible role in competitive positioning. While multiwall paper bags may appear to be a mature product category, advances in production optimization, material formulation, and design intelligence are enabling suppliers to improve strength, reduce weight, and enhance moisture barriers. Recent product-level activity illustrates this direction: in May 2025, Mondi Group launched its re/cycle PaperPlus Bag Advanced, a high-performance paper bag designed for humidity-sensitive products with up to 60 percent reduced plastic use and a strong moisture barrier. This launch underscores how sustainability and performance are converging, setting a benchmark that other players will need to match or differentiate around.
Competitive Positioning and the Evolution of Market Structure
The competitive landscape features a mix of global packaging leaders and specialized manufacturers, each pursuing distinct positioning strategies. Mondi Group, headquartered in Vienna, focuses on AI-powered multiwall bag production, sustainable paper-based packaging, and moisture-resistant bag solutions for industrial applications including cement and chemicals. Its emphasis on humidity-sensitive performance and reduced plastic use aligns closely with regulatory and demand trends. Smurfit Kappa, based in Atlanta, specializes in AI-enhanced bag design, lightweight yet durable multiwall sacks, and eco-friendly industrial packaging, positioning itself around design intelligence and sustainability. Segezha Group, headquartered in Moscow, provides AI-assisted high-strength multiwall bags, biodegradable packaging solutions, and customizable industrial paper sacks for food and agricultural sectors, leveraging customization and biodegradability as differentiators.
WestRock Company, also headquartered in Atlanta, focuses on AI-driven material optimization, high-barrier multiwall bags, and recyclable paper bag technologies for building materials, chemicals, and agriculture sectors, emphasizing barrier performance and recyclability. Sonoco Products Company and International Paper contribute from the U.S. with broad industrial and consumer packaging portfolios, with International Paper supplying kraft paper bags and corrugated packaging for industrial and consumer applications. More regionally focused players add further diversity: Bag Supply Company manufactures millions of high-quality multiwall paper bags annually for agricultural, industrial, construction, and consumer goods; Southern Packaging LP supplies customizable multi-wall paper packaging solutions through vertically integrated production facilities for industrial bulk packaging; JohnPac produces cost-effective multiwall paper bags for seed and grain storage and transport with custom shapes and sizes; and Novolex offers its Dubl Life line of FSC-certified or 100 percent recycled kraft paper bags for industrial and consumer use.
PW Consulting
The strategic logic across these players reveals several differentiation paths. One is performance-led, targeting moisture resistance, strength, and barrier properties for demanding applications. Another is sustainability-led, emphasizing reduced plastic use, recyclability, biodegradability, and certified fiber sources. A third is cost and customization-led, serving specific end-use verticals with tailored sizes and economical production. Vertical integration and sourcing flexibility are recurring advantages in a volatile raw material environment, while investments in design and production intelligence are increasingly used to improve efficiency and product consistency.
Industry events and community engagement are also shaping the competitive rhythm. The PSSMA 2026 Production Managers' Seminar and Bag Boot Camp in Greenville, South Carolina, along with the PSSMA 2026 Annual Meeting in Napa, California, reflect ongoing지식交流 and capability-building within the sector. These gatherings provide forums for sharing operational best practices and aligning on emerging standards, which can accelerate adoption of improved processes and compliance practices across the supply base.
Looking at market structure evolution, the current fragmentation at the top suggests room for selective consolidation among regional players seeking scale, while also leaving space for differentiated specialists to thrive. New entrants are unlikely to disrupt the market through volume alone; instead, they will need to bring clear advantages in sustainability credentials, moisture performance, customization, or cost efficiency. The interplay between regulatory deadlines, raw material volatility, and end-user expectations will likely reward companies that can combine operational resilience with credible product innovation.
Forward Outlook: Trends Shaping the Next Three to Five Years
The first major trend is the acceleration of recyclable and reduced-plastic multiwall paper bag designs as regulatory and customer expectations converge. With the EU requiring all packaging to be recyclable by 2030 and plastic bag bans expanding in various regions, suppliers that can deliver high-performance paper-based sacks with minimal or no plastic content will gain a structural advantage. This trend creates opportunities for product differentiation tied to documented recyclability, reduced plastic use, and moisture barrier performance that does not rely on multilayer plastic construction. The commercial implication is clear: sustainability is becoming a performance attribute, not just a compliance checkbox.
The second trend is continued raw material cost volatility paired with a growing emphasis on material efficiency and supply chain resilience. As kraft linerboard and adhesive prices remain sensitive to supply constraints and energy costs, manufacturers will increasingly value sourcing flexibility, vertical integration, and design choices that improve strength-to-weight ratios. Companies that can maintain quality while optimizing material usage will be better positioned to protect margins and offer competitive pricing. Procurement leaders should expect more variability in lead times and input costs, making supplier reliability and transparency increasingly valuable.
The third trend is the gradual integration of production and design intelligence into multiwall bag manufacturing. While not a wholesale transformation of the category, AI-assisted design and material optimization are enabling suppliers to improve consistency, reduce waste, and tailor bags to specific end-use requirements. This trend supports both cost efficiency and product performance, and it may become a baseline expectation for leading suppliers over the forecast period. The opportunity lies in pairing these capabilities with clear customer benefits, such as customized sizing, enhanced moisture resistance, or faster response to specification changes.
Tea Bag Paper Market
Potential risks and uncertainties should not be overlooked. Regulatory timelines may shift or be implemented with varying rigor across jurisdictions, creating compliance complexity for suppliers operating in multiple markets. Raw material price swings could intensify if energy costs or supply disruptions escalate, pressuring margins even for well-prepared manufacturers. End-user demand could also evolve in unexpected ways if alternative packaging materials gain traction in specific applications, or if economic conditions slow procurement in construction and agriculture. Navigating these uncertainties will require scenario planning, flexible sourcing, and product portfolios that can adapt to changing requirements without sacrificing core performance.
Implications and Actionable Considerations for Decision Makers
For manufacturers, the priority is to align product development with the converging demands of recyclability, moisture performance, and cost efficiency. Investing in reduced-plastic or fully recyclable multiwall designs, improving material utilization, and strengthening sourcing flexibility can help protect margins while meeting regulatory and customer expectations. Building documentation and labeling capabilities that support compliance in key markets, particularly where recyclability requirements are tightening, will also reduce execution risk. Where possible, enhancing production and design intelligence can improve consistency and responsiveness, giving suppliers an edge in customized or performance-sensitive segments.
For investors, the market offers moderate growth with meaningful differentiation potential rather than uniform upside. Attention should focus on players with credible sustainability credentials, resilient cost structures, and clear positioning in performance-sensitive applications such as building materials, chemicals, and humidity-sensitive food or agricultural products. Vertical integration, diversified sourcing, and evidence of product innovation that reduces plastic content or improves barrier performance are useful indicators of competitive strength. At the same time, raw material volatility and regulatory complexity warrant careful assessment of margin resilience and compliance readiness across geographies.
For procurement and supply chain leaders, the emphasis should be on supplier capability and transparency rather than price alone. Evaluating suppliers on moisture resistance, recyclability documentation, customization flexibility, and sourcing stability can reduce risk in demanding applications. Given ongoing input cost variability, diversifying the supplier base where feasible and securing commitments that balance cost with reliability can improve outcomes. Engaging suppliers early on specification changes and compliance requirements can also smooth transitions as regulatory deadlines approach and performance expectations rise.
Strategic decisions in this market benefit from detailed, up-to-date intelligence on segment-level demand patterns, regional dynamics, and competitor movements. PW Consulting's comprehensive research report on the Multiwall Paper Bags Market provides deeper segmentation data, regional breakdowns, and customized guidance to support planning and investment choices. Accessing that level of detail can help translate the trends and considerations outlined here into precise, actionable strategies tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Multiwall Paper Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Manned Security Services Market: The 7.12% CAGR Signals a Strategic Shift
By pmarketresearch, 2026-09-21
The Manned Security Services Market: Strategic Trends and Commercial Opportunities in an Evolving Landscape
The manned security services market has reached a critical inflection point. In 2025, the sector crossed the $242.5 million threshold in annual revenue, building on a steady recovery from the $185.3 million baseline observed at the start of the decade. Over the past five years, the trajectory has reflected not just post-pandemic normalization, but a fundamental recalibration of how organizations think about physical protection. The market is projected to expand at a compound annual growth rate of 7.12 percent through 2032, reaching an estimated $393.1 million by the end of the forecast period. This growth is not merely an extension of historical patterns; it is being shaped by structural shifts in technology, regulation, labor dynamics, and buyer expectations. For executives, investors, and procurement leaders, understanding where value is being created—and where it is being eroded—requires looking beyond top-line numbers and examining the forces that will determine competitive advantage in the years ahead.
Market Snapshot and Core Challenges
A Sector in Transition
The market has grown consistently from 2020 through 2025, but the composition of that growth tells a more nuanced story. Commercial facilities continue to anchor demand, while industrial sites and residential complexes represent secondary but strategically important demand pools. The service mix remains dominated by traditional guarding, though cash and valuables protection and specialized security services contribute distinct, higher-margin segments that reflect evolving risk profiles. This diversification is a response to the reality that one-size-fits-all security models no longer satisfy the operational complexity of modern facilities, logistics networks, and public-facing institutions.
Challenge One: Labor Scarcity and Wage Pressure
The most persistent constraint on the industry is human capital. Manned security remains, by definition, labor-intensive. Organizations that rely on guard presence at perimeter points, access control stations, and roaming patrols are competing for a workforce that is simultaneously in high demand across adjacent sectors such as logistics, facilities management, and hospitality. Wage escalation is no longer a temporary fluctuation; it is a structural cost input that compresses margins for providers that compete primarily on price. In markets where basic guarding is commoditized, the pressure is especially acute, with thousands of active security companies vying for the same talent pool. The result is a two-tier dynamic: providers that can attract, retain, and professionalize their personnel through career pathways, training, and competitive compensation are gaining share, while those locked into low-cost models face turnover, service inconsistency, and reputational risk.
Worldwide Site Safety Service Market
Challenge Two: Regulatory Friction and Compliance Complexity
Regulation is reshaping how manned security operates across jurisdictions. In some regions, foreign ownership restrictions are mandating local control and altering the competitive playing field for international operators. In others, procurement frameworks are introducing new clauses that affect how private security functions are structured and contracted, particularly in cross-border or government-adjacent environments. These dynamics do not simply add administrative overhead; they influence market entry strategy, partnership models, and the cost of scaling. Companies that treat compliance as a one-time onboarding exercise are exposed, whereas those that embed regulatory intelligence into their operating design can convert constraints into barriers that protect incumbent positions.
Challenge Three: The Technology Expectation Gap
Buyers increasingly expect that manned security will be augmented by technology—remote monitoring, video analytics, access control integration, and data-driven reporting. Yet the integration of these capabilities with human presence remains uneven. Some incumbents have built seamless hybrid offerings; others are stitching together point solutions that create operational friction. The expectation gap is widening the wedge between providers that can deliver coordinated, intelligence-led protection and those that offer body-only presence without situational awareness. For decision-makers, this creates a procurement challenge: how to ensure that the human element and the technological layer reinforce each other rather than operate in parallel silos.
Key Drivers Shaping the Market
Technology as a Force Multiplier, Not a Replacement
The most consequential driver of market evolution is the maturation of technology that amplifies the effectiveness of security personnel rather than displacing them. Remote guarding stations, analytics-enabled video feeds, and integrated alarm response platforms allow a smaller on-site footprint to achieve coverage that previously required a larger physical guard complement. This is particularly relevant for organizations managing multiple sites, variable-risk environments, or extended operating hours. The strategic implication is not simply cost reduction; it is the ability to redeploy personnel to higher-value tasks such as incident response, customer engagement, and specialized patrols. Where technology is deployed thoughtfully, it raises the baseline quality of service and creates differentiation in a market that has historically competed on headcount and price.
Policy and Regulatory Signals Redirecting Investment
Recent policy developments are acting as catalysts for reallocation. The closure of a significant government business unit by one of the largest global providers illustrates how portfolio choices are being shaped by shifting contract landscapes and regulatory considerations. Simultaneously, procurement frameworks that govern private security functions abroad are introducing clarity—and complexity—into how services are structured for international operations. These signals matter because they influence not only who wins contracts, but how services are designed, staffed, and audited. Providers that proactively align their operating models with emerging compliance expectations are better positioned to secure long-term public and quasi-public contracts, while those that lag face re-bid risks and margin compression.
Demand-Side Shifts: Risk Profiles Are Becoming More Granular
On the demand side, organizations are moving away from generic security packages toward solutions that reflect the specific risk profile of their facilities, supply chains, and reputational exposures. Commercial facilities are prioritizing customer experience and loss prevention within a single security function. Industrial sites are emphasizing perimeter integrity, access control, and rapid incident escalation. Residential complexes are balancing resident safety with privacy and community integration. This granularity is driving demand for specialized services and for guard personnel who are trained not only in presence and deterrence, but in de-escalation, observation, and communication. The buyers who are winning contracts are those that articulate a clear security mission and tie it to measurable outcomes, rather than treating security as a generic cost center.
Cost Structure Evolution and the Pursuit of Predictability
Cost structures are shifting as labor, insurance, technology, and compliance costs converge. Providers are responding by standardizing service tiers, incorporating technology-assisted monitoring to moderate labor intensity, and building clearer pricing models that improve predictability for clients. This evolution benefits both sides: organizations gain budgeting clarity and service consistency, while providers gain operational discipline and reduced churn. The market is increasingly rewarding business models that balance human presence with scalable infrastructure, because that balance delivers the reliability that risk-conscious buyers require.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market features several large, globally active providers whose strategies reveal how scale, footprint, and integration are being leveraged. Allied Universal operates across North America with a broad service portfolio spanning manned guarding, mobile patrols, risk consulting, and technology-enabled solutions, anchored by strong government and commercial contracts. Its positioning reflects the value of a large, diversified contract base and the ability to offer integrated services that span physical presence and advisory support. Securitas, headquartered in Sweden, operates in dozens of markets with a focus on on-site guarding, mobile guarding, remote guarding, and integrated solutions, emphasizing manned personnel services supported by technology. Its strategy underscores the importance of geographic breadth and the hybrid model of human presence combined with remote capabilities. Prosegur, based in Spain, specializes in manned guarding combined with alarms, logistics, and integrated security solutions across a wide country footprint, illustrating how logistics-adjacent security can create cross-selling opportunities and operational synergies. GardaWorld, headquartered in Canada, delivers manned security, cash logistics, and risk management with a strong presence in government and high-risk environments, highlighting the premium that specialized, high-assurance services can command. Paladin Security and InterCon Security, both with North American foundations, emphasize government and commercial guarding contracts, demonstrating that regional depth and relationship-driven account management remain viable paths to growth even as global players expand.
Recent Developments as Strategic Signals
Recent contract activity and recognition highlight how incumbents are reinforcing their positions. A major provider secured a new contract for guard services at county mental health facilities and clinics, a type of engagement that blends public-sector procurement with the need for trained, sensitive, and consistent personnel. Another provider ratified a renewed contract with a university that expanded protections and included wage increases, reflecting both the prioritization of campus safety and the willingness to invest in personnel to sustain service quality. Separately, a North American security provider received multiple industry awards, signaling that excellence in execution, client service, and operational discipline continues to be recognized and rewarded. These examples are consistent with a broader pattern: winning engagements often requires a combination of reputation, reliable staffing, and the ability to adapt services to the specific environment.
Market Structure: Consolidation Pressures and Differentiated Niches
The market is characterized by a moderate concentration at the top, with the largest players holding meaningful but not dominant shares, and a long tail of regional and specialty providers. This structure creates two simultaneous dynamics. First, there is pressure for consolidation among mid-tier and regional firms seeking to achieve scale in staffing, technology deployment, and contract procurement, particularly as compliance and labor costs rise. Second, there is room for differentiation in niches such as high-risk environments, cash and valuables logistics, specialized facility protection, and integrated remote-plus-on-site models. New entrants that can combine technology fluency with disciplined personnel management are finding traction, but they face the same labor and compliance realities as incumbents. The net effect is a market that is neither fully consolidated nor highly fragmented, but one in which strategic positioning—clear service boundaries, credible integration, and reliable execution—is becoming the primary determinant of sustainable share gains.
Future Trends and Commercial Opportunities
Trend One: Hybrid Security Models Will Become the Standard
Over the next three to five years, the distinction between manned and technology-assisted security will increasingly blur into hybrid models that are treated as the baseline offering. Remote monitoring, analytics, and integrated alarm response will be combined with on-site personnel deployed in a more targeted fashion. The commercial opportunity lies in designing service packages that explicitly map technology functions to human responsibilities, so that clients receive a coordinated outcome rather than a stack of separate capabilities. Providers that can demonstrate measurable improvements in response times, coverage efficiency, and reporting clarity will be better positioned to win multi-site and long-term contracts. The risk is that poorly integrated hybrids create confusion about accountability and degrade client trust; therefore, execution discipline and clear service definitions will be critical.
Trend Two: Professionalization of the Security Workforce Will Differentiate Providers
Professionalization—through structured training, clear career pathways, measurable performance standards, and competitive compensation—will move from a nice-to-have to a core competitive requirement. Organizations will increasingly evaluate providers not only on availability and price, but on the quality, consistency, and retention of the personnel assigned to their sites. The opportunity is to build workforce models that reduce turnover, improve service reliability, and create reputational advantage. In commoditized segments, however, wage and staffing pressure will remain a headwind, and providers that lack a clear workforce value proposition will find it harder to defend margins or win complex contracts. The uncertainty lies in the pace of wage escalation across different regions and the extent to which technology can offset labor intensity without compromising service quality.
Trend Three: Regulatory Clarity Will Reshape Market Access and Portfolio Choices
As regulatory frameworks around ownership, procurement, and cross-border private security functions become more defined, market access will be recalibrated. Providers with strong local knowledge, compliant ownership structures, and established relationships will have advantages in certain regions, while others may need to partner, restructure, or refocus their portfolios. The commercial opportunity is to use regulatory intelligence to shape where to compete, how to structure contracts, and which assets to retain or divest. Recent portfolio adjustments by large providers are a reminder that strategic withdrawal from specific segments can free resources for higher-conviction areas. The risk is that regulatory change introduces sudden compliance costs or contract re-bidding, particularly for operators with exposure to government-adjacent or internationally regulated engagements.
Strategic Recommendations for Decision-Makers
For Providers and Operators
Design service models around outcomes, not headcount. Clients increasingly buy protection that is visible, measurable, and integrated, rather than simply the presence of personnel. Providers that can articulate how manned presence, remote support, and reporting work together will command stronger positioning. Invest in workforce stability as a strategic asset: structured training, predictable scheduling, and competitive compensation are not merely cost items; they are the foundation of service quality and client retention. Where commoditization is intense, differentiate through specialization, reliability, or integration rather than price alone, because price competition in a high-turnover environment erodes both margins and reputation.
Managed Security Services System Market
For Investors and Sponsors
Evaluate potential investments with a clear view of labor economics and regulatory exposure. Business models that rely heavily on low-cost staffing without a credible plan for retention and professionalization are exposed to margin volatility and service risk. Preference should be given to operators with demonstrated ability to integrate technology into manned operations in a way that improves coverage and reporting, as well as those with diversified contract bases that reduce dependence on any single public-sector or cyclical customer. Pay close attention to geography and ownership rules, because compliance architecture can either enable scale or constrain it. In markets where concentration is moderate and fragmentation persists, there may be opportunities to build value through disciplined consolidation, shared services, and technology standardization, provided that integration risk is managed carefully.
For Procurement and Risk Leaders
Buy security as a coordinated capability, not as a commodity line item. Define the security mission for each site or portfolio in terms of outcomes—deterrence, response, access control, customer experience, and reporting—then evaluate providers against how they assign responsibilities across personnel and technology. Require evidence of workforce stability, training standards, and escalation protocols, because these factors determine whether service quality holds under stress. Favor contracts that include clear performance metrics, regular reporting, and defined accountability for both on-site and remote components. When regulated environments or cross-border operations are involved, confirm ownership, compliance, and contracting structures early, because late-stage surprises can disrupt delivery and increase cost.
The manned security services market is expanding, but growth alone does not guarantee profitability or competitive advantage. The sector is being reshaped by labor dynamics, regulatory evolution, technology integration, and a more demanding demand base. Organizations that treat these forces as signals to redesign service models, workforce strategies, and portfolio choices will be better positioned to capture value. For those seeking deeper granularity—segment-level sizing, regional dynamics, competitive benchmarking, and tailored scenario analysis—a comprehensive research resource is available to support more precise planning and decision-making.
PW Consulting
For detailed analysis of this topic, please visit the official page: Manned Security Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Beneath the Surface: Strategic Trends and Commercial Opportunities in the Marine Trenchers Market
The marine trenchers market has entered a phase of steady structural expansion, underpinned by growing offshore infrastructure investment and evolving technical requirements for subsea installation. Valued at approximately 120.0 million USD in 2020, the market reached an estimated 148.5 million USD by 2025, reflecting a compound annual growth rate of 4.0 percent over the 2020–2025 period. Forward projections extend through 2032, with revenue anticipated to approach 195.5 million USD by the end of the forecast horizon. While the growth trajectory appears measured in percentage terms, the underlying shift in project complexity, operational depth, and equipment specialization tells a more dynamic story. Marine trenching has moved from a supporting activity in pipeline and cable deployment to a critical capability that directly influences project economics, environmental compliance, and operational risk.
Several inflection points define the current market environment. First, the push toward deeper water projects and more complex seabed conditions is placing new demands on trenching systems, particularly around tool interchangeability, remote operation, and sediment adaptability. Second, rising project costs linked to maintenance, specialized labor, and equipment wear are forcing operators to prioritize reliability and lifecycle performance rather than upfront price comparisons. Third, the growing emphasis on offshore wind, interconnectors, and gas infrastructure is expanding the number of burial and trenching campaigns, but also compressing scheduling windows and increasing the premium on proven, repeatable execution. These dynamics are not merely operational concerns; they are reshaping procurement strategies, fleet planning, and competitive positioning across the supply chain.
Key Drivers Shaping the Market Trajectory
Technological Innovation and the Shift Toward High-Performance, Multi-Mode Systems
One of the most visible drivers in the marine trenchers market is the continued advancement of equipment capability. The industry is moving beyond single-purpose designs toward systems that can switch between mechanical cutting, jetting, and hybrid modes depending on sediment type and burial depth. This flexibility is increasingly valued because seabed conditions are rarely uniform, and project specifications often require precise depth control, minimal surface disturbance, and adaptable tool configurations. Higher horsepower platforms, improved hydraulic and electro-hydraulic architectures, and more robust cutting chains and bits are enabling operators to maintain productivity in harder sediments where wear rates and ground speed have historically limited performance.
Recent equipment milestones illustrate this direction. In October 2025, Osbit Ltd secured a contract with NKT to design and build the T3600 subsea trencher, described as one of the most powerful systems in the segment with 3,600 horsepower and dual jetting and cutting tools. The concept reflects a broader preference for machines that can handle heavier workloads while reducing the need for multiple vessel-based interventions. By February 2026, the T3600 had arrived at the Port of Blyth for final fit-out and commissioning ahead of operational use in 2027. This kind of development signals an industry leaning toward higher-capacity platforms that can address longer burial campaigns, more demanding ground conditions, and tighter project schedules.
For decision-makers, the implication is clear: equipment selection is becoming less about whether a trencher can complete a burial task and more about how effectively it can do so across variable conditions, with lower downtime and fewer operational compromises. Manufacturers that can demonstrate measurable improvements in tool life, ground speed stability, and mode switching are better positioned to capture perceived value, even when capital or rental costs are higher.
Policy, Regulation, and the Spreading Footprint of Offshore Infrastructure
Regulatory and policy environments are exerting a quiet but persistent influence on trenching demand. Environmental standards, seabed protection requirements, and cable and pipeline burial specifications are increasingly factored into project design, which in turn raises the baseline expectation for trenching quality and consistency. In many regions, burial is no longer treated as a discretionary step; it is a core requirement for protection against fishing activity, anchor damage, and environmental disturbance.
Broader energy and infrastructure trends reinforce this direction. European offshore wind capacity reached approximately 25 GW by 2020, and the continued expansion of wind farms and interconnector networks has sustained demand for cable burial equipment and related trenching standards. At the same time, Europe imported 85 billion cubic meters of LNG in 2020, helping accelerate demand for subsea pipeline burial and associated marine trenching in the region. These figures are not just energy statistics; they represent the kind of large-scale infrastructure activity that creates recurring requirements for burial, rehabilitation, and intervention services.
The policy-driven opportunity is twofold. Projects are increasingly spread across multiple geographies and seabed environments, which broadens the addressable market for trenching equipment and services. At the same time, regulatory expectations can raise the bar for execution, favoring operators with documented quality control, traceability, and compliance capabilities. Procurement teams are likely to weigh not only schedule and cost, but also the ability to meet region-specific burial standards and environmental safeguards.
Demand-Side Changes: More Burial Work, More Complexity, More Coordination
Demand for marine trenchers is being shaped by a shift in how offshore projects are planned and executed. Cable and pipeline installations are no longer isolated activities; they are integrated into wider grid, gas, and industrial networks that require coordinated scheduling across multiple contractors and vessels. As a result, trenching work is often planned around limited weather windows, restricted seabed access, and tight connection milestones. This places a premium on equipment availability, predictable performance, and rapid mobilization.
Pipeline burial remains the largest application area in terms of revenue contribution, reflecting the continued importance of protected subsea transport infrastructure. Cable burial is also significant, driven by interconnectors, wind farm export and array cables, and telecommunications links. Umbilical burial represents a smaller but technically demanding segment, often involving more delicate handling requirements and specialized burial approaches. The practical takeaway is that demand is diversified across infrastructure types, but the common thread is a need for burial solutions that can be deployed reliably across different project phases and seabed conditions.
For buyers and operators, this means that trenching capability is being evaluated within a broader project ecosystem. Equipment that can be integrated easily with different vessel configurations, ROV support, and survey and monitoring workflows is more attractive than a standalone machine optimized for a narrow set of conditions. The market is rewarding flexibility and service integration as much as raw trenching power.
Cost Structure and Operational Pressures: Wear, Labor, and Maintenance
Cost dynamics remain a significant driver of purchasing and operating behavior. Subsea trenching operations face elevated costs when sediment conditions accelerate chain and bit wear, especially in harder ground where achievable ground speeds and component life must be carefully managed. Performance monitoring against established geotechnical reference frameworks has become a practical necessity rather than an academic exercise, because underestimated wear or overly optimistic speed assumptions can materially affect project budgets and schedules.
Labor and maintenance costs add another layer of pressure. Specialized subsea trenching maintenance and operator training contribute meaningfully to overall project expenses, particularly for offshore infrastructure campaigns that require sustained operational readiness. High skill requirements, limited pools of experienced personnel, and the cost of keeping complex systems in field-ready condition all feed into total cost of ownership. This is an important shift from a purely equipment-purchase mindset to a broader operating-cost perspective.
Worldwide Underwater Dredging Robot Market
Recent project activity highlights how these cost and performance considerations play out in practice. In April 2025, Van Oord added a new Jet-It subsea trencher to its cable burial fleet following successful North Sea testing, reinforcing the value of proven shallow-water cable burial capability. In January 2025, DeepOcean completed a subsea trenching project in the US Gulf of Mexico using a 2,800hp trencher for cable and pipeline burial, demonstrating the continued relevance of powerful mechanical and jetting systems in active offshore regions. These deployments show that performance validation in real seabed conditions is a decisive factor in fleet expansion and project award decisions.
PW Consulting
Competitive Landscape and Leading Strategies
The marine trenchers market is characterized by a concentrated but diverse set of participants. Market concentration is notable, with the top three companies accounting for roughly 62.0 percent of revenue and the top five firms holding about 78.0 percent. This level of concentration suggests that scale, technological reputation, and established project relationships matter significantly, while still leaving room for specialized players and regional specialists to compete on differentiated capabilities.
Several companies illustrate the range of strategic positions in the market. Soil Machine Dynamics Ltd, based in Wallsend, Tyne & Wear, United Kingdom, manufactures subsea trenchers, burial machines, and related intervention equipment for pipeline and cable laying, including the Q-Trencher and Shallow Water Trencher models. Royal IHC, headquartered in Kinderdijk, Netherlands, designs and manufactures the Hi-Traq® multi-tool subsea trenchers, jetters, and tracked trenching vehicles for shallow water cable burial and offshore wind projects. Seatools B.V., based in the Netherlands, specializes in custom subsea trenching vehicles, mechanical and jet trenchers, cable ploughs, and upgrades for pipeline and cable installations. Osbit Ltd, also in the United Kingdom, designs, builds, and upgrades subsea trenching systems including mechanical, jetting, and cutter trenchers for cable and pipeline burial. Mastenbroek Limited, another UK-based manufacturer, provides subsea trenchers with conventional or undercut/rotary heads, available in hydrostatic or electro-hydraulic configurations for various sediment types.
The competitive field also includes operators and integrated service providers that use or deploy trenching equipment as part of broader campaign execution. Allseas Group, based in the Netherlands, operates Digging Donald, a fully remote-controlled pipeline burial trencher capable of depths up to 450 meters with interchangeable tools. DeepOcean Group, headquartered in the United Kingdom, operates a fleet and provides marine trenching equipment including mechanical trenchers, jetting ROVs, and ploughs for pipeline, cable, and umbilical burial. Van Oord, also in the Netherlands, operates and manufactures its own fleet of trenchers including Deep Dig-It, Dig-It, and Jet-It for subsea cable burial up to more than 5 meters below the seabed.
Differentiation Through Capability, Flexibility, and Execution track Record
What distinguishes the stronger positions is not simply equipment ownership, but the ability to match trenching technology to project needs and to prove performance in the field. Some manufacturers compete on power and tool versatility, emphasizing high horsepower and dual-mode systems that can adapt to harder or mixed sediments. Others compete on specialization, focusing on shallow water cable burial, tracked vehicles, or custom trenching vehicles that can be tailored to specific seabed and water-depth constraints. A third group differentiates through remote operation, depth capability, and tool interchangeability, which matters when projects require precise burial at greater depths or when surface vessel exposure must be minimized.
Recent developments show how these strategies are being reinforced. The T3600 contract award to Osbit and its subsequent arrival for fit-out point to a push toward higher-power, multi-tool systems that can serve demanding pipeline and cable projects. Van Oord's addition of a new Jet-It trencher after North Sea testing reflects a practical emphasis on validated cable burial performance in a region with active wind and interconnector work. DeepOcean's Gulf of Mexico project completion demonstrates the value of proven fleet deployment in geographically diverse markets.
Market Evolution: Consolidation, Specialization, and Selective New Entry
The market is likely to continue evolving around three themes. First, consolidation may remain attractive for firms seeking to broaden geographic reach, capture more of the project lifecycle, or combine equipment manufacturing with service delivery. Second, specialization will persist because seabed conditions, water depths, and project types are too varied for a single equipment architecture to dominate all segments. Shallow water cable burial, deep pipeline burial, umbilical handling, and mixed-sediment trenching each reward different design priorities. Third, new entry and expansion will depend on credible technical differentiation and demonstrated execution, rather than brand presence alone. In a market where top suppliers already hold a substantial share, credibility is built through project record, performance data, and the ability to integrate with operator and client workflows.
For strategic planners, the competitive takeaway is that procurement is increasingly comparative and evidence-based. Vendors that can articulate measurable differences in wear performance, operating efficiency, and deployment flexibility are better placed to defend pricing and win repeat work. For investors and industry participants, the more interesting question is not whether the market will grow, but which capabilities will be rewarded as project conditions become more varied and cost scrutiny intensifies.
Future Trends to Watch Over the Next 3 to 5 Years
Trend 1: Higher-Capacity, Multi-Mode Trenching as a Baseline Expectation
Over the next few years, the threshold for competitive trenching capability is likely to rise. Projects in harder sediments, deeper water, and more constrained schedules will push operators toward higher horsepower platforms with interchangeable tools and multiple burial modes. The recent emphasis on powerful dual-function systems is not an isolated product trend; it reflects a broader expectation that trenching equipment should reduce the need for rework, handle variable ground conditions, and keep campaigns on schedule.
The commercial opportunity here lies in equipment and service packages that lower total operating risk rather than simply increase peak power. Manufacturers and fleet providers that pair high-capacity machines with proven tool management, maintenance planning, and operational support may find stronger demand than those competing on hardware specifications alone. The risk is that power upgrades can raise capital and maintenance costs, so any advantage must be translated into measurable gains in productivity, component life, or schedule reliability.
Trend 2: Greater Integration of Remote Operation, Monitoring, and Fleet Standardization
Remote-controlled and remotely supervised trenching is likely to become more prominent as projects seek to improve precision, reduce vessel exposure, and standardize execution across multiple sites. The growth of fully remote pipeline burial systems and ROV-supported jetting and mechanical trenchers indicates a market moving toward operational models that depend less on manual intervention and more on controlled, repeatable processes. At the same time, operators managing multiple vessels and campaigns will increasingly value fleet standardization, common maintenance regimes, and shared training pathways.
Marine Deck Machinery Market
This trend creates opportunities for companies that can offer not just equipment, but consistent operating interfaces, training support, and lifecycle management. For buyers, standardized fleets and remote operation can simplify crew deployment and reduce variability between projects. The uncertainty is operational maturity: remote and semi-remote systems require dependable communications, maintenance readiness, and skilled oversight, so the benefits will depend on how well they are integrated into real-world campaign planning.
Trend 3: Regional Demand Diversification with Uneven Pace
Demand for marine trenching is expected to remain geographically diverse, supported by offshore wind, interconnectors, pipeline and cable networks, and energy infrastructure expansion in multiple regions. However, the pace of growth is unlikely to be uniform. Some markets will see sustained activity driven by large-scale wind and grid investments, while others may experience more intermittent demand tied to specific pipeline or LNG-related projects. This uneven pattern means that fleet planning and regional positioning will matter more than broad but shallow market exposure.
The associated opportunity is to align equipment portfolios and service coverage with the regions and project types most likely to generate recurring work. Companies that understand local seabed conditions, regulatory expectations, and project scheduling realities will be better positioned to capture demand without overextending into less predictable segments. The main risk is overgeneralizing from one region's pipeline or wind activity to the entire market; seabed conditions, permitting environments, and vessel logistics vary enough to make regional nuance a strategic necessity.
Strategic Recommendations for Decision-Makers
For manufacturers and equipment developers, the priority should be to translate technical differentiation into commercial clarity. Higher power, multi-mode tools, and remote operation features are attractive, but their value increases when they are linked to measurable outcomes such as reduced rework, longer component life in challenging sediments, and faster mobilization. Investment in demonstration projects, peer-reviewed performance data, and lifecycle support can be as important as the hardware itself. Companies should also consider how their offerings fit into broader project ecosystems, including compatibility with different vessel types, ROV support, and survey workflows.
For investors and strategic partners, the most defensible opportunities are likely to be found where market concentration, technical lead times, and execution track record intersect. A concentrated market can create durable positions for firms with proven capability, but it also means that competitive advantage must be continually renewed through product evolution and reliable project delivery. Capital allocation decisions should account for the reality that trenching demand is tied to large infrastructure cycles, which can be strong but unevenly timed. Preference for operators and manufacturers with diversified project exposure, disciplined cost structures, and credible maintenance and training capabilities may offer a more balanced risk profile than pure capacity expansion.
For procurement teams and project developers, equipment selection should be evaluated against total project risk rather than headline performance alone. Burial depth requirements, sediment variability, maintenance readiness, training burden, and regional support availability all influence long-term outcomes. Where possible, validation through recent deployments in comparable conditions can provide more useful guidance than specification comparisons in isolation. Buyers may also benefit from considering fleet compatibility and service integration, especially when multiple projects or regions are involved, because standardization can reduce training costs and improve scheduling predictability.
Across all perspectives, the most valuable intelligence is the kind that connects equipment capability to real operational conditions and project economics. Market size and growth rates provide context, but the decisions that matter most are usually about which trenching approach fits a given seabed profile, which fleet configuration best supports regional demand, and which performance trade-offs are acceptable when wear, labor, and maintenance costs are factored in. Detailed segmentation data, company-level positioning, and region-specific demand analysis can make those choices sharper and less reliant on assumption.
Closing Perspective
The marine trenchers market is expanding at a steady pace, but its strategic significance is growing faster than the headline numbers suggest. Burial and trenching are increasingly integral to the safe, compliant, and cost-effective deployment of offshore pipelines, cables, and umbilicals. That shift rewards systems that combine power, flexibility, remote operability, and proven field performance, while also rewarding operators and manufacturers that can manage the practical realities of wear, specialized labor, and project scheduling. The next several years will likely favor participants who treat trenching capability as part of an integrated infrastructure solution rather than as a standalone tool purchase. For executives, investors, and procurement leaders, the most useful next step is to align equipment and service choices with the specific seabed conditions, regional demand patterns, and cost structures that will shape each project's outcome.
For detailed analysis of this topic, please visit the official page: Marine Trenchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ballast Water Treatment Equipment Market: Why 8.7% CAGR Changes Everything
By pmarketresearch, 2026-09-21
The Ballast Water Treatment Equipment Market: Navigating the Next Wave of Maritime Compliance and Capital Opportunities
The global fleet is undergoing a quiet but profound transformation. As environmental regulations tighten and port state inspections become more rigorous, ballast water treatment has shifted from a compliance checkbox to a strategic operational priority. The market has expanded at a steady pace, with revenues crossing the seven-billion-dollar threshold in 2025 and projected to surpass ten billion before 2030, maintaining a compound annual growth rate of 8.72 percent through 2032. This trajectory reflects more than incremental fleet upgrades; it signals a structural realignment in how shipowners, regulators, and technology providers approach ballast water management as a long-term operational and sustainability imperative.
Growth is broad-based, spanning mature and emerging maritime regions, with Asia Pacific representing the largest share of activity, followed by Europe and North America. While the regional distribution reflects differing fleet compositions and regulatory timelines, the underlying momentum is universal: older vessels are being retrofitted, newbuilds are specifying treatment systems at the design stage, and operators are seeking equipment that balances performance with minimal downtime. Against this backdrop, the market is no longer defined solely by regulatory compliance deadlines. It is increasingly shaped by technology maturity, cost-of-ownership dynamics, and the growing emphasis on electronic record-keeping and verifiable treatment performance under intensifying inspection regimes.
Market Landscape and Core Challenges
The current phase of the ballast water treatment equipment market is characterized by a maturing technology base, heightened enforcement activity, and a competitive environment that favors players capable of demonstrating reliable performance across diverse water conditions and vessel types. Revenue growth has been consistent, supported by a pipeline of retrofit projects and newbuild specifications. Yet beneath the headline figures lie structural tensions that will determine which companies and investors capture durable value.
1. Treatment Performance Under Real-World Variability
Ballast water systems must handle wide fluctuations in salinity, temperature, turbidity, and biological load. This variability continues to challenge system reliability, particularly for technologies sensitive to water quality or requiring precise chemical dosing. Operators are increasingly scrutinizing performance data, service histories, and the ease of maintenance when selecting equipment. The implication is clear: systems that can demonstrate consistent efficacy with simpler maintenance profiles, and that integrate cleanly into existing vessel operations, are gaining preference over solutions that demand frequent calibration or extensive crew intervention.
2. Regulatory Tightening and Inspection Pressure
The regulatory environment is moving from baseline compliance toward verifiable, auditable performance. Recent amendments to the Ballast Water Management Convention have updated record-keeping requirements, including revised Ballast Water Record Book forms and the introduction of electronic records, reinforcing the expectation that operators maintain detailed, accessible documentation. Concurrently, port state control concentrated inspection campaigns have targeted ballast water management during specific windows, employing structured questionnaires and on-site verification to assess system compliance. These developments elevate the importance of systems that not only meet technical standards but also facilitate transparent reporting and straightforward audits.
3. Capital Allocation and Retrofit Economics
Shipowners face competing capital priorities, particularly in an environment where dry-dock schedules, compliance upgrades, and operational efficiency investments all compete for limited budgets. Retrofitting ballast water treatment equipment requires careful planning around vessel downtime, installation complexity, and integration with existing piping and control systems. For fleet operators, the decision often hinges on total cost of ownership rather than upfront price alone, including energy consumption, consumables, service availability, and the potential for future regulatory changes. This dynamic is reshaping procurement behavior toward solutions that offer predictable operating costs and adaptable configurations.
Key Drivers Redefining Market Dynamics
Several interconnected forces are accelerating growth and reshaping competitive priorities in the ballast water treatment equipment market. Understanding these drivers is essential for identifying where demand is heading and which capabilities will differentiate successful participants.
Technology Innovation and Treatment Modality Evolution
The technology landscape reflects a shift toward hybrid and multi-barrier approaches that combine filtration with disinfection methods such as ultraviolet treatment, electrolysis, and chlorine-based disinfection. Filtration-plus-UV configurations are widely recognized for their chemical-free operation and suitability across many vessel types, while electrolysis-based systems offer compact footprints and strong disinfection performance. Chlorination-focused solutions provide effective treatment in certain operating conditions but require careful handling and monitoring. The practical trend is toward systems that can adapt to varying ballast water quality, minimize consumables dependency, and integrate smoothly with vessel automation and data systems. This is not merely a technical preference; it reflects operational priorities around crew workload, maintenance intervals, and regulatory verifiability.
Policy and Regulatory Momentum
Policy remains the foundational demand driver, but its influence is deepening beyond initial compliance. The ongoing review of the ballast water management framework, informed by accumulated data and operational experience, points to potential amendments that could further refine performance requirements and measurement approaches. For manufacturers and shipowners alike, this means designing for future-proofing. Systems that are modular, upgradable, and capable of producing auditable electronic records will be better positioned as the regulatory framework evolves. The emphasis on documentation and verification also raises the strategic importance of service and support, since compliance is increasingly judged by both equipment performance and the quality of operational records.
Demand-Side Shifts in Fleet Strategy
Shipowners and operators are recalibrating fleet strategy in response to energy efficiency goals, operational resilience, and reputational considerations. Ballast water treatment is now part of a broader conversation about vessel sustainability and operational risk management. Newbuild orders increasingly include treatment specifications as standard, while retrofit activity is being prioritized for vessels with longer remaining service lives. This demand-side shift favors solutions that can be installed with minimal disruption, integrated with existing bridge and automation systems, and supported by local service networks. In addition, operators are increasingly factoring in the ease of proving compliance during inspections, which makes system transparency and documentation support a material purchasing consideration.
Supply Chain and Cost Structure Pressures
Cost structures in the equipment and services space are being re-evaluated as operators seek to manage total expenditure over the lifecycle of the vessel. While initial pricing remains relevant, buyers are paying greater attention to energy use, filter replacement cycles, chemical handling where applicable, and the availability of service and spare parts across key operating regions. This has encouraged a broader view of value, with some operators favoring solutions that reduce recurring consumable costs or that offer service agreements aligned with planned maintenance schedules. At the same time, supply chain resilience matters, particularly for components that must be available across multiple regions and vessel types. Providers that can combine reliable hardware with predictable service delivery are increasingly differentiated.
Competitive Positioning and Strategic Differentiation
The competitive landscape is moderately concentrated, with a handful of leading firms accounting for a significant share of activity. This concentration reflects the credibility requirements of the market: shipowners prefer suppliers with established certification status, proven installation experience, and the ability to support vessels across regions. At the same time, the diversity of treatment technologies and vessel requirements leaves room for specialized offerings and regional strengths.
Technology Archetypes and Differentiators
Leading participants are building distinct identities around treatment architecture, service capability, and integration depth. Alfa Laval, for example, has focused on filtration-plus-UV systems with an emphasis on compact design and compatibility with a range of vessel types, positioning its PureBallast product line around operational simplicity and performance consistency. Techcross has emphasized electrochemical approaches through direct and indirect electrolysis systems, catering to operators seeking robust disinfection performance and a footprint suited to certain vessel configurations. Hyde Marine’s Guardian series combines filtration and UV treatment with a focus on reliability and installation flexibility. Optimarin offers filtration-plus-UV systems with a strong service orientation, while De Nora Marine and Evoqua Water Technologies are associated with filtration-plus-electrolysis architectures that appeal to operators prioritizing disinfection performance and compact layouts. Wärtsilä presents both UV and electrochemical options, leveraging broad marine system integration capabilities. Norwegian Greentech, Trojan Marinex, and Ecochlor round out a field that includes filtration-plus-UV and filtration-plus-chlorine disinfection approaches, each with distinct operating trade-offs.
The strategic implication is that no single technology archetype dominates across all segments. Instead, differentiation is emerging around the fit between treatment method and vessel profile, the quality of documentation and inspection readiness, and the reliability of regional service support. Companies that can articulate clear performance cases, provide robust training and maintenance pathways, and align their offerings with electronic record-keeping expectations are likely to strengthen their position as scrutiny intensifies.
Concentration, Consolidation, and Market Evolution
The market’s moderate concentration suggests room for both consolidation and targeted fragmentation. Larger players with integrated marine system portfolios can leverage cross-selling, service networks, and engineering partnerships to deepen their footprint. At the same time, specialized manufacturers and regional service providers can compete by offering niche performance advantages, faster installation, or customized support for specific vessel types. Recent certification updates from classification bodies have reaffirmed approvals for a broad set of manufacturers, underscoring that the market remains open to multiple qualified participants. This environment favors companies that can demonstrate not only technical compliance but also the operational credibility to withstand inspection campaigns and evolving record-keeping expectations.
A further evolution likely to shape the competitive landscape is the increasing importance of digital readiness. Systems that produce clean, auditable data trails and interface with vessel reporting processes are better positioned for the inspection environment and the broader movement toward electronic records. This is not only a compliance consideration; it is becoming a differentiator in how operators assess risk, manage audits, and maintain documentation across fleets.
Strategic Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, several trends are likely to define the direction of the ballast water treatment equipment market and its commercial opportunities.
1. Compliance Becomes Continuous, Not Episodic
As inspection activity intensifies and electronic record-keeping becomes standard, the market will increasingly value systems that support ongoing verification rather than one-time certification. This trend favors solutions with clear documentation outputs, straightforward maintenance, and service models that help operators sustain compliance over time. For equipment providers, the opportunity lies in embedding compliance support into the product experience and service package, reducing the administrative burden on shipowners while strengthening reliability during audits.
Commercial implication: Providers that combine robust hardware with documentation-ready workflows, crew training, and localized service can create stickier relationships and reduce attrition in competitive retrofit and newbuild decisions.
2. Technology Convergence Around Practical Performance
While multiple treatment modalities will persist, the market is likely to see greater emphasis on practical performance across variable water conditions, ease of maintenance, and compatibility with vessel systems. Hybrid approaches that pair pre-treatment filtration with a disinfection method selected for the operating profile will remain central. Over the next few years, differentiation will increasingly hinge on real-world reliability, energy efficiency, and the ability to adapt configurations to specific vessel types and routes. This could encourage more modular designs and more flexible service agreements.
Commercial implication: Manufacturers that invest in field performance data, simplify maintenance, and align configurations to vessel operating patterns can strengthen their value proposition beyond compliance certification alone.
3. Regulatory Refinement Will Reshape Requirements and Planning Horizons
The ongoing review of the ballast water management framework, informed by operational data, suggests that requirements could evolve. Potential amendments may influence measurement approaches, reporting expectations, or performance verification methods. For shipowners and builders, this means adopting a forward-looking procurement stance, favoring systems that can be updated or reconfigured without major rework. For suppliers, it means designing products and service offerings with regulatory adaptability in mind.
Commercial implication: Early alignment with likely regulatory directions can reduce future retrofit risk and position companies to capture demand from operators seeking durable, adaptable solutions rather than short-term compliance fixes.
Worldwide Black Water Treatment System for Boats Market
Risks and Uncertainties to Monitor
No strategic outlook is complete without acknowledging uncertainty. The pace and content of future regulatory amendments remain dependent on international consensus and technical review processes. Inspection campaigns can vary in intensity and focus across regions, affecting short-term demand patterns. Economic conditions, vessel utilization, and capital availability will influence the timing of retrofit investments, particularly for older tonnage. In addition, technological trade-offs among treatment methods mean that performance claims must be carefully matched to specific operating conditions, and that supplier claims should be validated against real-world service data where possible.
PW Consulting
These uncertainties do not diminish the long-term trajectory; they reinforce the value of informed, scenario-aware decision-making. The operators and investors who succeed will be those who treat ballast water management not as a single compliance event but as a continuing operational capability.
Actionable Recommendations for Decision-Makers
For manufacturers, investors, and procurement teams, the current market environment calls for a balanced focus on compliance credibility, operational practicality, and lifecycle economics.
Water Treatment Equipment Market
For Equipment Manufacturers and Technology Providers
Position offerings around verifiable performance and inspection readiness, not certification alone. Invest in field performance documentation, crew training materials, and service models that reduce downtime and support electronic record-keeping. Consider modular architectures that allow configuration adjustments as requirements evolve. Strengthen regional service presence where retrofit and newbuild activity is concentrated, since responsiveness and parts availability increasingly influence purchasing decisions.
For Investors Evaluating Exposure
Assess exposure through the lens of total cost of ownership rather than unit pricing, with attention to service attach rates, consumable economics, and the breadth of certification and approval status across key regions. Differentiate between players with broad marine system integration capabilities and those with focused technology strengths. Monitor regulatory developments that could shift demand timing or favor particular treatment approaches, and weigh the resilience of service networks against the risk of regional inspection variability.
For Shipowners and Procurement Teams
Prioritize solutions that match the vessel’s operating profile, expected water quality variability, and inspection exposure, while keeping total cost of ownership at the center of evaluation. Favor systems that simplify maintenance, integrate with existing control and reporting workflows, and provide clear documentation support. Plan retrofit campaigns with dry-dock scheduling and service availability in mind, and seek configurations that can adapt to potential regulatory updates without major rework.
In all cases, the strategic value of detailed, up-to-date market intelligence is substantial. Segment-level demand patterns, regional inspection nuances, and technology-specific performance considerations can materially affect procurement timing and product selection. Access to granular data and tailored scenarios helps decision-makers move from broad trends to specific, defensible choices. PW Consulting’s in-depth research on the ballast water treatment equipment market provides that layer of detail, offering segmented analysis and customized viewpoints to support planning with greater precision.
For detailed analysis of this topic, please visit the official page: Ballast Water Treatment Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
UV Light Disinfection Market 2026: Why 15.4% CAGR Signals Strategic Shifts Beyond Water Treatment
By pmarketresearch, 2026-09-21
The UV Light Disinfection Market: Strategic Trends and Commercial Opportunities Through 2032
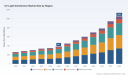
The UV light disinfection market has moved from a niche operational consideration to a central pillar of public health, infrastructure resilience, and facility safety strategies. Over the historical period from 2020 to 2025, the industry demonstrated consistent expansion, with the global market reaching approximately USD 387.0 million by the base year of 2025. Forward projections indicate sustained momentum, with the market expected to grow at a compound annual growth rate of 15.4 percent through the forecast period ending in 2032, ultimately approaching a valuation near USD 1,055.0 million. This trajectory reflects more than cyclical demand recovery; it signals a structural reorientation in how organizations approach microbial risk, regulatory compliance, and operational efficiency.
The scale and pace of this expansion carry meaningful implications for strategic decision-makers. A mid-teens CAGR across a seven-year horizon suggests that UV disinfection is transitioning from reactive procurement to embedded capital planning. The acceleration is not uniform across all use cases or geographies, and the concentration of revenue among a handful of established players indicates that competitive positioning will increasingly depend on regulatory clearance, application-specific validation, and total cost of ownership performance rather than standalone hardware specifications.
Market Snapshot and Structural Context
The market's expansion over the past half-decade has been characterized by broad-based adoption across water infrastructure, healthcare environments, and public-facing facilities. Revenue growth during the historical window reflects a combination of post-pandemic hygiene awareness, aging water treatment assets requiring modernization, and a growing acceptance of ultraviolet technology as a chemical-free or chemical-reducing intervention. The forecast period is expected to extend these dynamics while introducing new layers of complexity around device validation, reimbursement pathways, and cost-competitiveness against conventional alternatives.
A useful way to frame the market's current state is through its concentration profile. The sector remains moderately consolidated, with the top three participants capturing roughly 45 percent of revenue and the top five collectively accounting for approximately 55 percent. This level of concentration suggests that scale advantages, established distribution channels, and existing regulatory track records still matter, but it also leaves meaningful space for specialized entrants that can demonstrate superior performance in narrowly defined applications or high-value clinical workflows. The market is neither fully fragmented nor tightly monopolized, which creates a strategic environment where focused innovation can gain traction before larger players respond through acquisition or product line expansion.
UV Disinfection Equipment Market
Key Challenges and Inflection Points
Despite favorable demand signals, the industry faces several structural challenges that will shape which companies and applications succeed over the next decade. The first challenge revolves around validation and standardization. As UV disinfection moves into more regulated settings, buyers increasingly demand reproducible efficacy data under real-world operating conditions, not just laboratory benchmarks. Devices that cannot clearly demonstrate consistent microbial reduction across variable surface geometries, airflow patterns, or water turbidity profiles will face growing scrutiny from procurement teams and clinical stakeholders.
A second challenge lies in balancing capital expenditure against lifecycle economics. While ultraviolet systems can reduce ongoing chemical handling, manual cleaning labor, and infection-related costs, the upfront investment and replacement cycle for lamps, sleeves, and controller units remain important considerations. Organizations with constrained capital budgets need transparent payback logic, and suppliers must be able to articulate how equipment longevity, energy consumption, and maintenance intervals translate into measurable operational savings. The market is shifting from a purchase-of-equipment mindset to an evaluation of total intervention cost, which raises the bar for commercial messaging and economic modeling.
A third challenge is the growing complexity of regulatory expectations. Health authorities and standards bodies are refining how UV devices should be tested, documented, and integrated into existing infection control or water safety plans. This is a positive development for long-term credibility, but it introduces short-term friction for manufacturers that must navigate differing clearance pathways, regional normative references, and buyer-specific documentation requirements. Companies that treat regulatory engagement as a one-time event rather than an ongoing capability risk losing relevance as procurement criteria become more formalized.
These challenges are not simply obstacles; they are also the forces redefining competitive advantage. Suppliers that align product design, clinical or environmental validation, and economic documentation with the way end-users now make decisions will be better positioned to capture share in a market that is becoming more demanding, not just larger.
Drivers Reshaping the UV Disinfection Landscape
Technology Innovation and Application-Specific Engineering
The most durable driver of market expansion is the continued refinement of ultraviolet hardware and system architecture. Historically, generic lamp-based solutions addressed broad disinfection needs, but the market is increasingly rewarding designs engineered for specific environments and use cases. In healthcare and life sciences, for example, the ability to deliver validated microbial reduction across complex room geometries or sensitive instrumentation has become a key differentiator. Devices that combine targeted emitter configurations, consistent dosing control, and workflow-compatible form factors are gaining traction because they reduce the gap between laboratory performance and operational reliability.
A parallel innovation track is the evolution of UV-C LED systems and related component technologies. LED-based architectures offer advantages in form factor, directing options, and integration flexibility, which makes them attractive for applications where traditional lamps may be less practical. At the same time, capital expenditure payback periods for such systems have been evaluated in the range of about 2.5 to 3.5 years, supported by lamp lifetimes commonly spanning 10,000 to 20,000 hours. These parameters matter because they give facility and operations leaders a more concrete framework for comparing UV investments against alternatives, especially where labor intensity, chemical storage, or downtime are significant cost drivers.
The strategic implication is that innovation is no longer measured by brightness or output alone. It is increasingly measured by how reliably a solution delivers repeatable disinfection in the context of real workflows, maintenance constraints, and energy budgets. Suppliers that develop modular platforms, adjustable dosing logic, and application-tailored validation packages are likely to outperform those offering one-size-fits-all hardware.
PW Consulting
Regulatory Momentum and Standards Development
Policy and regulatory dynamics are playing an increasingly decisive role in shaping demand. In healthcare and medical device contexts, clearance pathways and normative references have become essential prerequisites for adoption, not optional credentials. Recent industry activity illustrates how rapidly the environment is evolving. In early 2026, Xenex Disinfection Services achieved Health Canada registration for its LightStrike6 UV-C robot, extending its North American authorization footprint for healthcare use. Later in the same year, UV Smart Technologies B.V. secured FDA 510(k) clearance for its D60 UV-C system designed specifically for transesophageal echocardiography probe disinfection, marking a first for that application. Around the same period, Surfacide, LLC introduced its Helios+ UV-C system, which received FDA 510(k) clearance as a whole-room microbial reduction device using continuous 254 nm germicidal UV light.
These developments are significant because they show regulatory review moving toward more application-specific and workflow-specific scrutiny. Rather than treating ultraviolet disinfection as a single homogeneous category, agencies and advisory bodies are examining study designs, intended use cases, and device-specific risk profiles. This trend was reinforced by broader engagement from the FDA General Hospital and Personal Use Devices Panel Advisory Committee, which convened in late 2025 to discuss study design considerations for germicidal UV devices intended to help reduce healthcare-associated infections. At the same time, regional standards activity such as the Netherlands' NEN 8281:2025 framework for validating UV-C disinfection of non-critical and semi-critical medical devices signals that structured validation expectations are becoming more explicit across parts of Europe as well.
For market participants, the implication is clear: regulatory engagement is no longer a downstream compliance task. It is a central element of product strategy. Companies that invest early in well-designed clinical or environmental evidence, that understand the difference between clearance types and their commercial consequences, and that can map their devices to applicable standards will gain meaningful purchase over competitors that rely solely on generic performance claims.
Demand-Side Shifts in Healthcare, Water, and Public Infrastructure
Demand is being reshaped not only by regulation but also by changing organizational priorities. In healthcare, the emphasis on reducing healthcare-associated infections continues to drive interest in complementary disinfection layers that can support, rather than replace, existing hygiene and cleaning protocols. UV-based interventions are increasingly evaluated against practical economic benchmarks, including the total cost of environmental control per bed or per procedure area. Publicly available comparisons have suggested that UV-C sanitization devices can present a median cost profile of roughly AUD 360 per bed per year, compared with approximately AUD 965 associated with hand hygiene protocols in some analyses. While such figures must be interpreted in context and vary by setting, they illustrate a broader point: procurement teams are looking for solutions that fit within cost-constrained infection prevention programs and offer quantifiable operational trade-offs.
In water and wastewater applications, demand is being driven by the need to modernize aging infrastructure, meet stricter effluent and drinking water quality expectations, and reduce chemical handling in treatment workflows. Municipal and industrial operators are evaluating UV systems not only for pathogen control but also for integration with existing treatment trains, energy constraints, and lifecycle maintenance plans. This creates a market environment where success depends less on the novelty of the concept and more on service reliability, dosing consistency, and the ability to support large-scale operational continuity.
Across both clinical and infrastructure settings, the common theme is a shift from awareness to evaluation. Buyers are not simply asking whether UV disinfection works in principle; they are asking which configuration works best in their environment, how it interacts with current processes, and what the real total cost of ownership looks like over multiple years.
Supply Chain, Component Economics, and Total Cost Positioning
Cost structure and supply chain resilience are becoming more visible as decision factors. The UV disinfection market spans lamps, reactor chambers, quartz sleeves, controller units, and a range of ancillary components, each with its own replacement cadence, sourcing complexity, and performance sensitivity. Fluctuations in raw material availability, electronics supply, and specialized glass or quartz components can affect product lead times and cost stability, particularly for manufacturers that depend on tightly integrated component chains.
At the same time, the market is seeing growing attention to design choices that reduce long-term operating burden. Longer service life for light sources, robust controller electronics, and serviceable chamber or sleeve designs all contribute to total cost positioning in ways that matter to buyers. The strategic relevance of this driver is that competitiveness increasingly depends on engineering for maintainability and cost transparency, not just peak disinfection output. Suppliers that can document predictable maintenance intervals, spare part availability, and energy usage patterns are better equipped to defend their pricing and build trust in sectors where downtime or compliance failures carry substantial consequences.
Competitive Positioning in a Maturing Market
The landscape of leading participants reflects the market's dual character: it contains broad-platform vendors serving large utility and industrial segments, as well as specialized players targeting high-value, regulation-sensitive applications. Firms such as Xylem Inc. and Trojan Technologies Group ULC have long been associated with UV disinfection systems for water and wastewater treatment, where scale, reliability, and integration with treatment infrastructure are paramount. Their strategic positioning tends to center on proven performance in demanding continuous-operation environments, supported by service networks and a focus on municipal and industrial procurement cycles.
Halma PLC and Atlantic Ultraviolet Corporation represent additional depth in UV equipment and product portfolios that span air and water applications, often with an emphasis on established distribution, component reliability, and broad market coverage. OSRAM GmbH and Heraeus Holding GmbH contribute important upstream and component-oriented capabilities, particularly around UV lamps and related equipment, reinforcing a supply base that is crucial for downstream system performance and availability. Koninklijke Philips N.V. has extended its presence into UV-C systems and air purification solutions, leveraging a position that intersects consumer-adjacent, clinical, and environmental health requirements.
At the same time, the market is being shaped by companies that compete through application specificity and regulatory differentiation. Xenex Disinfection Services has built its profile around UV-C whole-room microbial reduction robots, with recent North American authorization milestones reinforcing its positioning in healthcare settings. Surfacide, LLC has emphasized continuous 254 nm germicidal UV light for whole-room microbial reduction with FDA 510(k) cleared devices, distinguishing its approach through emitter configuration and clearance status. UV Smart Technologies B.V. has focused on UV-C high-level disinfection systems, including devices for transesophageal echocardiography probes, targeting specialized clinical workflows where application-specific clearance creates meaningful barriers to comparison. PuraCath Medical similarly targets a narrow but consequential need through UV disinfection systems for needleless connectors intended to reduce central line-associated bloodstream infections.
These distinctions matter because they reveal how competitive advantage is being redefined. The market is not simply moving toward consolidation through scale; it is also fragmenting into high-value niches where regulatory clearance, intended-use specificity, and workflow fit determine commercial value. Some of the strongest opportunities are emerging where a solution can demonstrate a defensible claim in a tightly defined use case, then expand from there through adjacent applications or geographic rollout.
Strategic Differentiation and Market Evolution
Looking across the leading set, several strategic postures emerge. One approach is platform breadth: supplying a wide range of UV products and services across water, air, and surface applications, with competitive advantage rooted in reliability, service coverage, and existing customer relationships. A second approach is clinical or procedural specificity: developing devices that address a particular disinfection workflow, often supported by targeted regulatory clearances and evidence packages. A third approach is component or upstream strength, where leadership in lamps, optics, or material performance underpins downstream system competitiveness.
The market is likely to see continued evolution along both consolidating and differentiating lines. Larger integrators may pursue acquisitions or internal platform expansion to cover more applications and geographies, especially where water infrastructure or broad facility management portfolios are concerned. At the same time, smaller or mid-sized innovators may capture premium positioning by solving validation, usability, or workflow-integration problems that broader competitors have not prioritized. New entrants will find the most viable openings in areas where buyers face clear pain points, where standards are becoming explicit, and where the economics of chemical reduction or labor savings can be clearly quantified.
Importantly, the concentration structure of the market does not imply that innovation is throttled by incumbency. Because the top three firms capture less than half of revenue, there is room for specialized devices, regional champions, and application-first strategies to gain momentum before the landscape fully stabilizes. This creates a strategic window for organizations that can move quickly on evidence generation, regulatory alignment, and operational proof points.
Forward Trends Shaping the Next Three to Five Years
From General Efficacy to Validated, Application-Specific Deployment
One of the most important trends expected to intensify through the forecast period is the shift from broad efficacy claims to validated, application-specific deployment. Buyers in healthcare, food and beverage, and water treatment are increasingly looking for documentation that matches their operational context. This means devices will need to show not only that they can achieve microbial reduction in principle, but also that they do so consistently under defined use conditions, with traceable testing, and within a workflow that staff can realistically sustain.
This trend will likely reward suppliers that invest in structured validation programs, that design for repeatable dosing, and that can communicate performance in operationally relevant terms. It also creates an opportunity for differentiation around service and support, since a UV system that is validated but difficult to maintain will lose its advantage over time. Companies that build validation, training, and lifecycle support into the core offering are better positioned to convert early adoption into durable deployment.
Integration of UV Systems into Broader Environmental and Water Safety Strategies
Another trend is the growing integration of UV disinfection into broader environmental health, water safety, and facility operations planning. Rather than treating ultraviolet systems as standalone interventions, organizations are increasingly considering how they fit alongside chemical treatment, filtration, ventilation, and hygiene protocols. This integration mindset favors solutions that can be monitored, controlled, and maintained within existing operational frameworks, and it encourages the use of UV technology where it can reduce chemical handling, simplify compliance, or improve resilience in continuous-use environments.
Commercial opportunities here include bundled service models, remote monitoring or performance reporting, and flexible system architectures that adapt to changing throughput or regulatory requirements. In water and wastewater contexts, in particular, the next several years are likely to see continued demand for systems that balance pathogen control with energy efficiency, maintenance predictability, and integration into large-scale treatment operations.
Cost Discipline, Lifecycle Economics, and Financing-Sensitive Procurement
A third trend is the increasing weight of lifecycle economics in procurement decisions. As organizations compare UV solutions against conventional cleaning, chemical treatment, or alternative disinfection technologies, they are focusing more closely on payback, replacement cycles, energy consumption, and labor impacts. The trend is especially relevant where capital budgets are constrained or where infection-related costs, chemical compliance, or facility downtime create strong incentives to justify investment with transparent economic logic.
This trend encourages two strategic responses. For manufacturers, it raises the importance of credible total cost of ownership narratives and long-life component design. For buyers, it creates an opportunity to move beyond price-per-unit comparisons and toward evaluations that capture operational savings, compliance risk reduction, and service continuity. The organizations that can quantify these elements effectively will have an advantage in both selling and buying decisions.
Potential Risks and Uncertainties
Several uncertainties could shape the trajectory of the market. Regulatory expectations may continue to tighten or diverge across regions, which would reward companies with strong documentation capabilities while pressuring those that rely on generalized claims. Economic volatility and capital expenditure constraints could slow adoption in some segments, particularly where buyers must prioritize competing infrastructure needs. There is also the risk that underperforming or poorly validated devices could damage trust in specific application categories, making the quality of evidence and service support even more important across the board. Finally, component supply dynamics and lamp or LED replacement cycles remain operational realities that can affect margins and customer satisfaction if not managed carefully.
These risks do not undermine the market's fundamental direction, but they do suggest that success will depend on disciplined execution: clear claims, strong validation, operational reliability, and credible cost modeling.
Actionable Implications for Decision-Makers
For Manufacturers and Technology Providers
Focus on application-specific value rather than generic disinfection messaging. The competitive edge in the next phase will likely belong to companies that can match device capabilities to well-defined workflows, support them with credible evidence, and document total cost of ownership including maintenance, replacement, and energy considerations. Regulatory engagement should be treated as a strategic capability, not a compliance afterthought, especially as clearance pathways become more application-aware and expectations around study design and validation become more structured.
In practical terms, this means prioritizing the development of validation packages that reflect how customers actually use devices, building serviceable and durable system architectures, and preparing for a landscape where procurement decisions are increasingly influenced by lifecycle economics and regional standards alignment. Companies that can demonstrate consistent performance in the exact context where they are sold will have stronger positioning than those that rely on broad but less differentiated claims.
For Investors
Pay attention to where regulatory clearance, application specificity, and documented cost advantages intersect. The market is large enough to support both scaled platforms and focused innovators, but the most durable returns are likely to come from businesses that can defend a clear intended-use niche while building evidence and service capabilities that make adoption repeatable. In water and wastewater, scale, reliability, and integration strength remain central; in healthcare and specialized surface or instrument disinfection, clearance status and workflow fit can create higher barriers to comparison and stronger pricing power.
Investors should also weigh supply chain exposure and component lifecycle economics, since lamp life, controller durability, and replacement part availability can materially affect both commercial margins and end-user satisfaction. A disciplined approach to assessing evidence quality, regulatory status, and operational economics will be more useful than broad assumptions about market growth alone.
UV Infection Control Device Market
For Procurement and Operations Leaders
Evaluate UV disinfection as part of a broader risk-reduction and operational efficiency strategy, not as a single-point purchase. Ask for evidence that reflects your actual operating conditions, clarify the total cost of ownership over the equipment's service life, and consider how the system will integrate with existing cleaning, treatment, ventilation, or infection prevention workflows. Where possible, prioritize solutions that provide transparent maintenance expectations, service support, and performance documentation that can be reviewed by clinical, environmental, or compliance stakeholders.
In water and wastewater contexts, emphasize reliability, energy and maintenance implications, and integration with existing treatment processes. In healthcare and public-facing settings, give appropriate weight to clearance status, validation methodology, and the practical realities of staff workflow. The organizations that make decisions on this basis are more likely to realize the intended benefits without encountering hidden operational friction.
For decision-makers who need to move quickly across multiple segments, regions, or application categories, the most efficient next step is to anchor strategy in a structured market view that connects macro growth trajectories with the specific segment dynamics, regulatory milestones, and competitive distinctions shaping adoption today. A detailed reference point that consolidates these dimensions can help teams compare opportunities, prioritize validation and procurement pathways, and identify where further due diligence is required. Readers seeking a fuller breakdown of segment-level dynamics, regional variation, and targeted commercial scenarios can explore the complete PW Consulting market analysis for additional depth and customized guidance.
For detailed analysis of this topic, please visit the official page: UV Light Disinfection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Refractories Market 2026: Why 5.7% CAGR and Asia Pacific’s Scale Redefine Strategy
By pmarketresearch, 2026-09-21
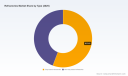
Strategic Shifts and Commercial Opportunities in the Refractories Market
Navigating a Sector at the Intersection of Industrial Demand and Sustainability Imperatives
The global refractories market is entering a phase of measured expansion, underpinned by steady industrial activity and a gradual shift toward higher-performance, environmentally compliant materials. With total market revenue reaching approximately USD 359.4 million in the base year of 2025, the sector has recovered from earlier cyclical slowdowns and now reflects a compound annual growth rate of 5.7 percent across the historical window spanning 2020 through 2025. Projections for the forecast period extending from 2026 through 2032 indicate continued upward momentum, with revenue expected to climb steadily toward USD 522.49 million by 2032. This trajectory suggests that the industry is not merely rebounding to pre-downturn levels, but is absorbing structural changes in end-user requirements, material science advancements, and supply chain reconfiguration.
The market scale observed in 2024, at USD 336.06 million, already reflected a meaningful acceleration from the 2023 baseline of USD 325.58 million, signaling that industrial infrastructure upgrades, capacity restorations in select regions, and sustained throughput in metals and construction-linked industries are translating into firmer demand for high-temperature containment solutions. As the sector moves deeper into the forecast horizon, the growth narrative will increasingly be shaped by how companies navigate material sourcing constraints, regulatory pressure on carbon intensity, and the competitive dynamics of a concentrated industry where the top three players collectively account for roughly 40 percent of revenue and the top five capture approximately 45 percent. These concentration figures point to a market where scale, technological differentiation, and regional reach remain decisive, yet they also leave meaningful room for specialized entrants and regional specialists to capture value in niche applications and localized supply ecosystems.
Worldwide Refractory Anchor Market
For executives and investors, the immediate takeaway is that the refractories sector is no longer a commodity-like volume play. Instead, it is evolving into a performance-driven, compliance-sensitive segment where margin resilience depends on product innovation, supply chain agility, and the ability to align with downstream decarbonization roadmaps. The following sections unpack the core challenges, demand drivers, competitive moves, and forward-looking trends that will define strategy in this market over the next several years.
Market Snapshot: Scale, Trajectory, and Structural Signals
The revenue progression from 2020 through 2025 illustrates a market that has navigated external disruptions while maintaining a positive growth arc. After a base of USD 282.66 million in 2020, the industry recorded sequential gains that culminated in the 2025 figure of USD 359.4 million. This upward slope reflects more than simple recovery; it suggests shifting procurement patterns, a gradual premiumization trend toward products capable of withstanding higher thermal and chemical stress, and durable utilization rates in core industrial segments. The forecast path continues this direction, with revenue expected to rise through 2032, ending at USD 522.49 million. The compound annual growth rate of 5.7 percent across the full 2020 to 2032 horizon implies that growth will be consistent rather than explosive, emphasizing the importance of operational efficiency, product mix optimization, and regional execution over sheer volume expansion.
A notable characteristic of the current landscape is the dominance of Asia Pacific in overall market revenue, which underscores the region’s role as the primary engine of industrial throughput and refractory consumption. At the same time, the presence of meaningful revenue bases in other regions indicates that demand is not monolithic. Different geographies are responding to distinct infrastructure cycles, regulatory environments, and industrial composition, which means global players must tailor their go-to-market strategies rather than rely on a uniform expansion model. The concentration profile of the market further reinforces the strategic importance of differentiation. In a sector where top-tier firms hold a substantial share of total revenue, competitive advantage increasingly derives from specialized material formulations, application engineering, service layering, and supply reliability rather than price competition alone.
Critical Challenges and Inflection Points
One of the most pressing challenges shaping the refractories market is the tension between performance requirements and sustainability mandates. End-users in steel, cement, glass, and non-ferrous metals are under intensifying pressure to reduce operational emissions, which in turn places expectations on refractory suppliers to deliver materials that support energy-efficient processes and lower thermal losses. This demand is not purely aspirational; it is increasingly codified in procurement standards, customer sustainability targets, and in some cases, regulatory frameworks. Companies that cannot demonstrate credible pathways toward lower-carbon products, responsible raw material sourcing, and reduced waste generation risk losing relevance in bids where lifecycle and environmental criteria carry growing weight alongside traditional technical specifications.
A second challenge lies in the fragility and concentration of certain raw material supply chains. The dependence on specific mineral inputs, combined with geopolitical developments and trade policy shifts, creates exposure for manufacturers and end-users alike. Tariff adjustments, import flow variability, and sourcing disruptions can affect input costs and lead times, forcing producers to balance cost control with continuity of supply. This environment favors organizations that diversify sourcing options, invest in alternative material formulations, and maintain transparent supplier risk monitoring. Where input volatility persists, the ability to secure consistent quality at stable costs becomes a competitive differentiator as much as a procurement necessity.
A third inflection point is the accelerating pace of competitive consolidation and capability expansion. Recent corporate activity indicates that leading firms are actively pursuing scale, capacity additions, targeted acquisitions, and capability investments aimed at strengthening their positions in high-value product categories. This behavior signals that the market is moving toward a structure where adjacency expansion, technology-enabled product development, and localized manufacturing presence are used to deepen customer relationships and defend share. For smaller or regionally focused players, the challenge will be to identify defensible niches, whether through application specialization, technical service depth, or regional responsiveness, rather than competing directly on broad commodity fronts.
Core Demand Drivers Reshaping the Market
Technology Innovation and Material Performance Gains
Advancements in material science and application engineering are reshaping what refractories can deliver in demanding operating environments. The industry is seeing a greater emphasis on formulations that extend service life, reduce maintenance frequency, and improve thermal stability under severe mechanical and chemical stress. Investments in research, including collaborations that integrate advanced modeling and artificial intelligence into material development, are shortening development cycles and enabling more precise tailoring of products to specific process conditions. These capabilities matter because refractory replacement cycles directly affect throughput, downtime, and operating costs for end-users. A product that performs longer and fail more predictably can create measurable value beyond its unit price, which shifts purchasing decisions toward total cost of ownership and reliability rather than initial cost alone.
Recent developments in the sector demonstrate how innovation is being operationalized. One Japanese manufacturer announced a strategic partnership with a leading technology firm in mid-2025 to develop advanced refractory materials using artificial intelligence, signaling a broader interest in data-driven formulation optimization. At the same time, U.S.-based firms have expanded capacity in critical product categories; for example, a major monolithic refractory producer acquired a facility in Ohio during mid-2025 to expand its production footprint for precast and monolithic solutions. These moves illustrate that innovation is not limited to laboratory-level breakthroughs. It also includes manufacturing footprint decisions that improve responsiveness, reduce logistics friction, and support higher-value product lines where application engineering and repeatability are key.
Policy, Regulation, and Environmental Compliance
Regulatory and policy dynamics are increasingly shaping both input availability and product design priorities. In the United States, trade-related adjustments have influenced the flow and cost of certain minerals used in refractories production. Tariff increases on specific imported materials, alongside temporary exemptions and procedural extensions, have introduced uncertainty into sourcing strategies and encouraged suppliers to reassess exposure to single-origin dependencies. These developments matter because refractory manufacturers rely on a range of mineral inputs whose availability and pricing can directly affect margins and delivery reliability. The practical response from progressive suppliers and buyers alike has been to strengthen supply chain visibility, evaluate substitution pathways, and incorporate compliance considerations into product development from the outset rather than treating them as afterthoughts.
On the product side, environmental compliance is moving from a constraint to a strategic lever. The incorporation of recycled materials into certain brick formulations, while maintaining regulatory limits on contaminants such as chromium, reflects an emerging capacity to reconcile sustainability goals with performance requirements. This type of progress is significant because it demonstrates that compliance-driven material changes can be implemented without abandoning technical integrity. As industrial customers align procurement with decarbonization objectives, suppliers that can document lower environmental impact, responsible sourcing, and measurable performance under real operating conditions will be better positioned to win preference in competitive evaluations.
Demand-Side Evolution in Core Industrial Segments
Demand for refractories remains closely tied to the operating intensity of heavy industrial sectors, especially iron and steel, where thermal containment and wear resistance are fundamental to continuous production. Beyond primary metals, applications in cement, glass, and non-ferrous processing continue to contribute meaningful revenue, each with distinct technical requirements and procurement rhythms. What is changing is the emphasis on lifecycle value and process efficiency. End-users are increasingly interested in solutions that reduce energy loss, withstand longer campaign lengths, and support stable operations in environments where downtime is expensive and process variability carries direct financial consequences.
Refractory Bricks Market
This demand-side evolution is also visible in the way customers evaluate suppliers. Technical capability, application support, and delivery consistency are gaining relative importance alongside price. In many procurement environments, the decision is no longer a simple choice among comparable products; it is a selection among differentiated offerings that vary in formulation quality, installation support, service responsiveness, and regional supply reliability. For refractory producers, this means that value creation depends on being able to demonstrate how a given solution contributes to the customer’s operational and sustainability goals. For buyers, it means that supplier evaluation frameworks should account for total operating impact rather than unit price in isolation.
Supply Chain Reconfiguration and Cost Structure Pressures
Cost structures in the refractories sector are being influenced by a combination of raw material volatility, energy exposure, logistics complexity, and the strategic need to localize production in response to customer expectations and trade dynamics. Some input markets have experienced disruptions that reduced import volumes and forced procurement teams to adjust sourcing plans, while trade policy changes have altered the relative attractiveness of different supply routes. These conditions are encouraging a broader reassessment of how refractory companies structure their upstream dependencies and downstream delivery networks.
At the same time, expansion into new manufacturing locations is becoming a strategic response to demand geography and supply risk. A notable example is the establishment of a new manufacturing facility in Vietnam by a major engineered ceramics and metal flow solutions provider in mid-2025, reflecting a deliberate effort to strengthen regional capacity and align production more closely with demand centers in Asia. This kind of location strategy can improve lead times, reduce freight exposure, and enhance the ability to serve customers with region-specific requirements. For the broader market, it suggests that competitive positioning will increasingly depend on where capacity is located, how flexibly it can be reconfigured, and whether suppliers can maintain cost discipline while meeting higher service expectations.
Competitive Landscape and Strategic Positioning
The refractories market is characterized by a group of established international players with strong application expertise, global distribution reach, and growing emphasis on differentiated product portfolios. In high-grade refractory products and systems, a Vienna-based leader remains prominent across steel, cement, glass, and non-ferrous metals, with a profile built on breadth of offering and industrialapplication depth. A London-headquartered provider has strengthened its relevance through engineered ceramics and metal flow solutions, particularly in steelmaking and foundry contexts where flow control and thermal performance intersect. A Paris-based specialist continues to focus on high-performance ceramics and refractories for extreme-temperature applications, emphasizing the performance envelope required in the most demanding process environments.
Asian manufacturers also play a significant role. A Tokyo-based producer is recognized for high-quality refractory bricks, monolithics, and functional products used in blast furnace, casting, and kiln applications, while another Japanese firm maintains a strong presence in high-quality bricks and materials for the iron and steel industry. In India, a Kolkata-headquartered specialist provides refractory solutions tailored to iron-steel and foundry requirements, reflecting the importance of regional application knowledge and customer proximity. In the United States, a Columbus-based company is known as a global leader in monolithic refractory ceramics and precast shapes, with an emphasis on solutions that support faster installation, repeatability, and reduced downtime.
These profiles point to several patterns in strategic positioning. First, market leaders are building advantage not just through scale, but through application-specific expertise, service integration, and the ability to support complex customer requirements across multiple industries. Second, differentiation is increasingly tied to product performance under severe conditions, installation efficiency, and the use of advanced development methods that accelerate formulation refinement. Third, regional expansion and targeted capacity additions are being used to strengthen responsiveness and reduce exposure to long supply chains. Rather than treating refractories as a standardized product category, leading players are advancing it as a solutions space where technical reliability, delivery assurance, and evolving environmental performance all contribute to competitive advantage.
Market Evolution and Structural Trends
One clear trend in the competitive landscape is selective consolidation and capability deepening. Recent activity includes capacity-expanding acquisitions, new product introductions aimed at reducing carbon emissions in industrial processes, and partnerships that bring advanced analytical methods into material development. An acquisition completed in the United States during mid-2025 expanded monolithic refractory production capacity, reinforcing a broader industry emphasis on precast and monolithic solutions that can improve installation speed and consistency. A product launch later in the year introduced a new line of eco-friendly refractory products designed to reduce carbon emissions in industrial processes, highlighting how environmental performance is becoming a stated product strategy rather than a side initiative.
At the same time, market structure is evolving through facility expansion in strategically relevant geographies and technology-linked partnerships that aim to raise the bar on material performance. These moves suggest a market in which incumbents are reinforcing their positions while also seeking new avenues for differentiation. For newer or smaller players, the likely path to relevance lies in specialization: targeted applications, regional service advantages, formulation expertise in specific material families, or superior responsiveness in supply chains where reliability is highly valued. The presence of both global scale players and regionally embedded specialists indicates that the market will remain pluralistic, but competition will increasingly reward those who can combine technical credibility with operational dependability.
PW Consulting
Outlook: Three Trends to Watch Over the Next Three to Five Years
The first trend is the continued alignment of refractory development with downstream decarbonization goals. As industrial operators set targets for energy efficiency and emissions reduction, refractory suppliers will face greater expectation to offer products that help lower thermal losses, extend campaign life, and support cleaner process designs. Commercial opportunity will accrue to companies that can substantiate performance claims, provide transparent environmental data, and integrate compliance considerations into product architecture. The associated risk is that sustainability expectations may outpace the technical feasibility of certain material substitutions, creating tension between customer ambitions and achievable performance.
The second trend is the growing importance of supply chain resilience and input diversification. Trade policy changes, import flow variability, and mineral sourcing dependencies are likely to keep pressure on procurement strategies. Companies that broaden their supplier base, qualify alternative materials where feasible, and maintain visibility into geopolitical and logistics risks will be better positioned to protect margins and delivery reliability. The opportunity here is to turn supply chain rigor into customer trust, especially in markets where continuity of supply and predictable lead times are valued as part of the overall solution. The risk is that rapid shifts in trade rules or unexpected disruptions can still affect costs and availability, particularly for specialized inputs with limited substitution options.
The third trend is the shift from product selling toward solutions-oriented engagement. This includes greater emphasis on application engineering, installation support, lifecycle assessment, and performance monitoring. As end-users prioritize operational stability and total cost of ownership, suppliers that can provide integrated support across the product lifecycle will gain stronger positioning. The commercial opportunity lies in service differentiation and customer lock-in through technical value rather than price competition. The risk is that service commitments increase exposure to performance variability and require disciplined execution across regions, especially where local capabilities and skilled labor availability differ.
Implications and Strategic Actions for Decision-Makers
For refractory manufacturers, the priority is to strengthen product differentiation while managing input and compliance risk. This means investing in formulations and development methods that improve durability and thermal performance, documenting sustainability attributes in ways that withstand procurement scrutiny, and aligning capacity decisions with demand geography and service expectations. Manufacturers should also assess where monolithic, precast, or specialized brick solutions can deliver measurable advantages in installation speed, repeatability, and lifecycle cost, and structure their portfolios accordingly. Where raw material exposure is concentrated, diversifying sourcing and qualifying alternatives should be treated as strategic actions rather than purely procurement tasks.
For investors, the relevant question is where value creation is most durable. Markets with steady industrial demand and growing emphasis on performance, reliability, and environmental compliance are likely to reward companies with strong application expertise, clear product differentiation, and disciplined execution in regional expansion. Due diligence should pay attention to raw material exposure, supply chain geography, and the credibility of sustainability claims, since these factors increasingly influence competitive positioning and margin resilience. Investment theses should also consider whether a company is competing on scale alone or has defensible advantages in formulation, service, or regional responsiveness, because those distinctions often determine long-term share dynamics in concentrated markets.
For procurement and industrial buyers, the opportunity is to move beyond unit-price comparisons and incorporate total cost of ownership, campaign life, installation efficiency, and environmental performance into supplier evaluation. In environments where downtime is expensive and process stability is critical, a refractory solution that reduces maintenance frequency or extends service intervals can generate value that is not visible in the initial purchase price. Buyers should also evaluate supplier risk on inputs and logistics, since continuity of supply can be as important as technical specifications. Where possible, procurement frameworks should include documentation of material origin, recycled content where applicable, and compliance with relevant environmental limits, so that purchasing decisions align with operational and sustainability requirements.
For all stakeholders, the strategic implication is that timely, granular intelligence matters. Market direction is visible at the aggregate level, but the real decisions—where to expand capacity, which formulations to prioritize, how to manage input exposure, and how to respond to competitor moves—require detailed segmentation, regional nuance, and a clear view of competitor activity. Detailed research that breaks down performance by application requirements, material families, regional demand patterns, and competitive maneuvers can help decision-makers move from general awareness to specific action.
Deepening the Strategy Conversation
The refractories market is not simply expanding; it is being reshaped by the intersection of industrial demand, material innovation, supply chain realignment, and sustainability expectations. That combination creates opportunities for suppliers that can deliver superior performance and credible compliance, for investors that can identify durable competitive advantages, and for buyers that can align procurement with total operational value. At the same time, the sector remains exposed to input volatility, trade policy shifts, and the execution challenges that accompany product and capacity strategy changes. In this environment, clarity on segmentation, regional dynamics, and competitive behavior is essential for confident decision-making. More detailed data, application-level breakdowns, and company-specific developments are available in the full research report, which provides the depth needed to turn these strategic themes into concrete plans.
For detailed analysis of this topic, please visit the official page: Refractories Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wheel Flange Lubrication System Market: Why 4.46% CAGR Redefines Track Performance
By pmarketresearch, 2026-09-21
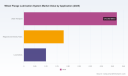
Global Wheel Flange Lubrication System Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Steady Growth Anchored in Infrastructure Modernization
The global wheel flange lubrication system market has transitioned from a specialized niche to a critical component of railway maintenance ecosystems. Valued at USD 0.56 billion in 2020, the market has followed a consistent upward trajectory, reaching approximately USD 0.70 billion by 2025. Projections through 2032 indicate continued expansion, with the market expected to reach USD 0.95 billion by the end of the forecast period, supported by a compound annual growth rate of 4.46%. This trajectory reflects a maturing but still evolving landscape where reliability, environmental compliance, and lifecycle cost optimization drive procurement decisions across transport operators and infrastructure managers.
The market structure remains concentrated, with the top three and top five players collectively commanding roughly 70% of global revenue. This concentration suggests entrenched relationships with rolling stock manufacturers, railway operators, and municipal transit authorities, while simultaneously leaving meaningful room for differentiated challengers who can address specific operational pain points. Geographically, demand is distributed across multiple regions, with mature markets in North America and Europe maintaining steady procurement cycles and emerging infrastructure programs in Asia Pacific, Latin America, and the Middle East and Africa contributing incremental growth. The application mix is anchored by urban transport networks, which represent the largest share of deployments, followed by regional and intercity trains and locomotive operations. By system type, wayside configurations account for the majority of installations, while on-board solutions occupy a smaller but strategically important segment tied to fleet flexibility and space-constrained platforms.
This growth is not accidental. It reflects a broader shift in railway operations from reactive maintenance toward predictive, condition-based, and environmentally conscious asset management. The market’s trajectory through 2032 will be shaped less by raw volume expansion and more by the ability of stakeholders to align lubrication technologies with evolving compliance standards, operational reliability targets, and total cost of ownership expectations.
Critical Challenges and Industry Inflection Points
The market faces a set of intertwined challenges that are reshaping procurement behavior and technology selection. First, the operational trade-off between lubrication effectiveness and contamination risk continues to force operators to reconsider liquid versus solid delivery architectures. Recent industry publications have highlighted shunt failure issues caused by excess oil from liquid wheel flange lubrication systems in metro applications, underscoring how over-application or poorly managed dispersion can create downstream reliability problems. This has reignited operator scrutiny around dosing precision, delivery placement, and the operational footprint of lubricant residues on track infrastructure.
Second, regulatory and environmental constraints are tightening the boundaries of acceptable lubricant selection. Equipment standards such as EN 15427-1-1:2022 specify requirements for equipment used to apply lubricant to the interface between the wheel flange and the gauge face of the rail, which pushes suppliers to align hardware design, nozzle performance, and application controls with recognized engineering expectations. Beyond equipment specifications, environmental permitting and lubricant discharge limits in certain jurisdictions restrict lubricant types and affect a meaningful portion of trial sites reported by operators. These constraints are not theoretical; they influence procurement timelines, site approvals, and the willingness of operators to adopt new chemistries without localized validation.
Third, material and design choices are increasingly scrutinized through a lifecycle lens. Modern wheel flange lubrication systems are often built on a polymer matrix with dry solid lubricant integrated, a configuration that reflects the broader industry shift toward reduced residue, simplified maintenance, and lower contamination risk. However, performance consistency across varying rail profiles, weather conditions, and traffic densities remains a recurring operational challenge. Suppliers that can demonstrate repeatable friction reduction, controlled wear characteristics, and compatibility with different rail and wheel materials will have a distinct advantage in a market where operators increasingly evaluate solutions across multi-year service life rather than initial capex.
PW Consulting
These challenges do not signal stagnation. Instead, they mark an inflection point where the winning offerings will be those that balance application precision, environmental acceptability, and maintenance-friendly design rather than those that simply maximize lubricant volume or hardware complexity.
Core Drivers Shaping Market Direction
Several interconnected forces are accelerating change in wheel flange lubrication system demand and purchasing behavior.
Technological innovation is pushing the category beyond mechanical dispensing toward controlled delivery, material science advancement, and more predictable friction management. Patented application techniques and specialized material formulations are being used to improve lubrication consistency while reducing excess spread. Dry solid lubricant approaches, particularly carbon-based products designed to lower friction and wear without heavy residue, are gaining traction where operators seek to reduce cleaning cycles and minimize track contamination. At the same time, on-board and wayside architectures are being refined to address specific operating environments, from high-frequency urban tram networks to heavier regional and intercity services. The result is a more segmented technology landscape in which performance claims must be validated under real track conditions, not just in laboratory settings.
Policy and regulatory dynamics are simultaneously shaping the market by narrowing lubricant choices and increasing documentation expectations. Newer equipment requirements and evolving environmental expectations are making compliance an integral part of procurement rather than an afterthought. The growing proportion of biodegradable and low-VOC lubricant selections in new contracts signals that sustainability considerations are moving from peripheral interest to active evaluation criteria. This shift does not eliminate performance requirements, but it does raise the bar for solution providers: lubricant formulations and delivery systems must now demonstrate operational value alongside environmental acceptability.
Demand-side behavior is also changing. Urban transport authorities and regional operators are increasingly focused on service continuity, reduced wheel and rail wear, and lower maintenance burden. These priorities are especially relevant where network utilization is high and downtime carries significant operational and financial consequences. Procurement teams are therefore weighing lubrication systems not only against upfront cost, but also against expected service intervals, ease of refilling or replacement, and the ability to reduce unplanned interventions. In that context, lubrication solutions that simplify field service and deliver consistent performance can justify premium positioning even in cost-sensitive environments.
Supply chain and cost structure considerations add another layer of influence. Material availability, carbon-based feedstock characteristics, polymer matrix design, and manufacturing scalability all influence both product performance and commercial resilience. As operators become more sensitive to total cost of ownership, suppliers that can manage material sourcing, maintain formulation consistency, and support service networks with predictable lead times are better positioned to secure long-term contracts. Cost compression alone is unlikely to drive purchasing decisions in this segment; reliability, compliance, and serviceability typically carry more weight in operational evaluations.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a blend of established multinational suppliers, specialized lubrication manufacturers, and material-focused innovators. Large incumbents tend to leverage broad railway portfolios, global service reach, and longstanding relationships with rolling stock and infrastructure stakeholders. This scale advantage supports system integration, cross-platform compatibility, and the ability to offer both wayside and on-board configurations within a single supplier relationship. For operators seeking consolidation of supply and standardized maintenance practices, these players remain natural first stops in the evaluation process.
At the same time, differentiated specialists are competing through technology specificity and application expertise. Companies promoting patented delivery methods are positioning around precision, reduced waste, and performance consistency in targeted use cases. Suppliers of carbon-based dry lubricants are emphasizing friction reduction and wear mitigation with a focus on lower contamination and simplified field handling. Others are promoting solid lubricant sticks, applicators, and corrosion-resistant designs tailored for metro, tram, and industrial railway environments where residue control and durability are especially important. This specialization matters because wheel flange lubrication is inherently site-sensitive; a solution that performs well in one operating environment may require adaptation in another.
Recent developments indicate a market that is active but selective. Industry participation in technology exhibitions and targeted case study publications suggests continued emphasis on demonstration, validation, and operator education. Showcasing lubrication technologies at sector events helps suppliers reach transit authorities, maintenance teams, and engineering decision-makers who evaluate solutions based on compatibility with existing infrastructure and anticipated service impact. At the same time, published case discussions around excess oil and shunt-related issues reinforce the market’s sensitivity to over-application and contamination, pushing the conversation toward controlled delivery and cleaner interface management.
The competitive landscape is likely to evolve through a mix of consolidation and targeted entry rather than uniform convergence. Consolidation may continue where scale, service coverage, and system integration create durable advantages. Fragmentation may persist where niche performance, regional compliance needs, or specific material advantages allow focused players to win meaningful contracts. New entrants will need to demonstrate more than equipment availability; they will need to show credible validation, operator-relevant service support, and alignment with environmental and reliability expectations. For incumbents, the challenge is to avoid over-reliance on portfolio breadth alone and to maintain compelling product-level differentiation as procurement teams become more sophisticated about lifecycle performance.
Forward-Looking Trends: 2026 to 2032
Several trends are likely to define commercial direction over the next several years.
Trend 1: Controlled delivery and residue-sensitive architectures will gain preference. As operators confront the operational consequences of over-application and track contamination, demand will increasingly favor systems that emphasize dosing accuracy, targeted placement, and cleaner interface management. This trend supports both dry solid and refined liquid approaches, but only where performance can be demonstrated without creating secondary maintenance burdens. Commercial opportunity lies in solutions that reduce cleaning frequency, improve consistency across varying traffic conditions, and simplify operator procedures. The risk is that overly aggressive claims about “cleaner” systems will be challenged if field validation does not match controlled-environment expectations.
Trend 2: Environmental acceptability will become a core procurement filter, not a secondary consideration. With biodegradable and low-VOC options representing a growing share of new contract selections and environmental permitting constraints affecting a notable portion of trial activity, sustainability criteria will play a larger role in vendor shortlists. Solutions that align with local discharge expectations, demonstrate reduced environmental footprint, and maintain mechanical performance will be better positioned for broader adoption. The commercial upside is clear for suppliers that can provide compliant chemistries, application hardware, and documentation support in a single value proposition. The uncertainty lies in regulatory variation across jurisdictions, which may require region-specific validation and slow standardization of lubricant preferences.
Trend 3: Lifecycle value and service integration will increasingly outweigh initial hardware cost. Operators managing dense urban networks and publicly accountable transport systems are likely to evaluate lubrication systems through total cost of ownership, including maintenance labor, refilling logistics, wear reduction, and downtime avoidance. This creates opportunities for suppliers that bundle application reliability with field service support, predictable consumable supply, and design choices that simplify inspection and replenishment. Over the next few years, contracts may increasingly reward proven serviceability and operational consistency. The risk is that supply chain volatility, material availability, or inconsistent manufacturing quality can undermine the expected lifecycle benefits and erode buyer confidence.
Automatic Lubrication Systems Market
Strategic Implications for Decision-Makers
For manufacturers and technology suppliers, the priority is to align product development with the market’s shifting evaluation criteria. Differentiation is strongest when it directly addresses application precision, residue management, and environmental compliance without sacrificing reliable friction control. Investments in validation documentation, pilot-scale demonstrations, and region-specific lubricant compatibility can improve credibility with operators and engineering teams. Supplier strategies that depend solely on hardware presence or legacy relationships are more vulnerable to competitors offering cleaner, more controllable, and more service-friendly solutions.
For investors and strategic partners, the attractive value lies in capabilities that strengthen lifecycle value and compliance readiness rather than in volume expansion alone. Technology positions tied to controlled delivery, dry solid formulations, and durable consumable designs may offer more defensible differentiation in a market where contamination risk and environmental constraints are rising in importance. Equally important is the operational side: distribution, service readiness, and the ability to support trial-to-scale transitions can determine whether a promising product translates into durable contract wins. Due diligence should account for regional regulatory variation and the potential need for localized validation before widespread adoption.
For procurement teams and transport operators, the most effective approach is to evaluate lubrication systems through a combined lens of reliability, compliance, and maintenance burden. Specifying solutions based only on upfront price can increase exposure to repeat application issues, cleaning requirements, and downstream infrastructure concerns. Where possible, procurement should incorporate trial data, operator-relevant performance metrics, and supplier support capabilities into the decision process, especially for urban networks and high-utilization services where downtime carries significant operational cost. Balancing equipment standards alignment with lubricant selection criteria can also reduce approval friction and improve long-term contract stability.
Railway Grease Market
As the market moves toward 2032, the differentiating questions will not be limited to whether a system can apply lubricant, but whether it can do so with controlled dispersion, compliant chemistry, and maintenance-friendly execution across the intended operating environment. Organizations that secure detailed segment-level insight, region-specific regulatory context, and supplier-by-supplier positioning will be better equipped to time investments, refine specifications, and target the most commercially relevant opportunities.
For detailed analysis of this topic, please visit the official page: Wheel Flange Lubrication System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
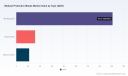
Medical Protective Masks Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for medical protective masks has entered a new phase of structural maturation, transitioning from crisis-driven demand to a more predictable, compliance-shaped growth trajectory. With a 2025 revenue baseline of 215.0 million USD and a projected compound annual growth rate of 6.95 percent through 2032, the sector is expanding toward a 344.8 million USD valuation by the end of the forecast window. The historical arc from 2020 through 2025 reveals a market that absorbed unprecedented shocks, stabilized around renewed procurement rhythms, and is now being reshaped by regulatory recalibration, regional capacity realignment, and shifting end-user expectations. For executives, investors, and procurement leaders, the central question has moved beyond whether demand will persist to how value will be captured in a market where certification status, domestic sourcing preferences, and performance standardization increasingly dictate commercial outcomes.
N95 Grade Medical Protective Masks Market
Market Landscape and Core Challenges
The revenue progression from 2020 to 2025 establishes a baseline of steady expansion, with annual figures moving from 163.15 million USD to 215.0 million USD. The forecast path to 2032 indicates continued upward movement, though the growth profile is not linear. Acceleration in the near term is supported by renewed institutional purchasing and updated performance expectations, while longer-term expansion depends on how quickly manufacturers can align production with evolving compliance frameworks and how procurement systems integrate new domestic sourcing incentives. The market remains moderately fragmented. The combined share of the three largest participants sits at 24.6 percent, while the top five account for 26.2 percent. This concentration pattern signals that scale alone does not confer decisive dominance. Instead, competitive advantage is increasingly tied to certification portfolios, regulatory responsiveness, and the ability to maintain consistent supply to healthcare and institutional buyers who prioritize reliable compliance over pure price competition.
Several structural challenges are redefining how participants operate. The first is regulatory volatility around approval frameworks. Recent actions by NIOSH, including the voluntary rescission of multiple approvals for major respirator manufacturers, have introduced uncertainty into product line continuity and inventory planning. For manufacturers, this creates a need to treat certification status as a dynamic asset rather than a static credential. For procurement teams, it complicates long-term sourcing commitments and raises the importance of supplier diversification. The second challenge lies in the tension between global cost optimization and emerging domestic procurement preferences. Policy signals, including CMS proposals to maintain equitable adjustment authority for domestic N95 respirator costs and a January 2026 advance notice of proposed rulemaking seeking input on incentivizing domestic procurement of personal protective equipment, indicate a directional shift toward supply chain localization. Companies that rely heavily on centralized overseas production without regional backup capacity may face margin pressure or eligibility constraints in certain procurement channels. The third challenge is standardization reform. The introduction of EN 14683:2025, which specifies updated construction, design, performance requirements, and test methods for medical face masks, raises the bar for product consistency and documentation. While stronger standards improve end-user confidence and interoperability across procurement systems, they also increase compliance costs and can slow product launches for manufacturers that have not invested in testing infrastructure and quality system upgrades.
Key Drivers Shaping Market Trajectory
The market's direction is being shaped by four interlocking forces: technology and design innovation, regulatory and policy evolution, demand-side behavior changes, and supply chain cost structure realignment. Each driver carries distinct implications for commercial strategy.
Technology and Performance Innovation
Product differentiation is increasingly anchored in filtration consistency, fit optimization, and material durability rather than basic barrier functionality. N95 respirators remain the largest product category, reflecting sustained preference for higher filtration performance in clinical and high-exposure environments. At the same time, manufacturers are expanding surgical N95 variants and ASTM-aligned surgical masks to address settings where both fluid resistance and respiratory protection are required. Recent commercial activity illustrates how companies are using product breadth and certification coverage to strengthen positioning. Makrite's participation in Tool Japan 2025 highlighted a strategy of showcasing N95, surgical, and KN95/FFP2 variants together, reinforcing a portfolio approach that aligns with procurement teams seeking single-source compatibility across multiple use cases. Harley Commodity's emphasis on surgical N95 models with adjustable head straps reflects attention to fit and wearer compliance, factors that increasingly influence repeat purchasing decisions in healthcare environments. For businesses, the strategic implication is clear: performance claims must be backed by active approvals and demonstrable test alignment, and product roadmaps should anticipate overlaps between respirator and surgical mask requirements as institutions consolidate purchasing categories.
Regulatory and Policy Environment
Policy frameworks are moving from emergency-era flexibility toward more structured oversight and procurement incentives. FDA draft guidance for FY2025 on enforcement discretion policy for premarket and other requirements for NIOSH-approved air purifying respirators signals an effort to clarify how compliance expectations will be applied in routine market conditions. NIOSH's conformity assessment activity, including the September 2025 voluntary rescission of approvals for multiple major manufacturers, underscores that approval status can change quickly and that manufacturers must maintain rigorous quality system discipline. On the procurement side, CMS proposals related to equitable adjustment authority for domestic N95 respirator costs and the January 2026 advance notice of proposed rulemaking on domestic PPE procurement incentives point toward financial and policy mechanisms that may favor domestic production in certain purchasing pathways. These developments do not erase global supply chains, but they introduce a new layer of strategic planning. Companies that can demonstrate stable approval status, transparent compliance documentation, and flexible sourcing options will be better positioned to navigate both regulatory scrutiny and procurement preference shifts.
PW Consulting
Demand-Side Behavior and Institutional Purchasing
End-user behavior has shifted from reactive stockpiling to more disciplined, specification-driven purchasing. Healthcare remains the dominant application arena, reflecting continued emphasis on staff protection, infection control protocols, and standardized procurement in clinical settings. Industrial and other application segments contribute meaningful demand, but the commercial center of gravity remains in environments where compliance documentation, batch traceability, and performance consistency are non-negotiable. Procurement teams are increasingly evaluating suppliers on the stability of their approval portfolios and the resilience of their supply commitments rather than on short-term price advantages alone. This shift favors manufacturers that can provide clear certification status, predictable lead times, and product lines that match multiple procurement specifications. It also creates an opening for intermediaries and verification-focused organizations that help buyers navigate approval status, sourcing authenticity, and specification matching. Project N95's role in vetting, sourcing, and distributing respirators from approved manufacturers reflects a broader market need for trusted validation pathways, especially when procurement decisions must balance speed, compliance, and supply assurance.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by the interaction of raw material availability, manufacturing geography, and compliance-related operating costs. Domestic capacity expansion is one visible response to supply assurance concerns and procurement preference signals. 3M's opening of a new N95 respirator manufacturing facility in North Carolina in March 2025 illustrates a strategic move to increase domestic production capacity for medical protective masks, reducing dependence on distant supply nodes and improving responsiveness to regional demand fluctuations. At the same time, manufacturers with strong positions in Asian production networks are pursuing market-facing visibility and certification breadth to maintain competitiveness. The broader cost picture is not simply about labor arbitrage; it is increasingly about the total cost of maintaining approval status, meeting updated standards, and satisfying procurement rules that may favor localized supply. Businesses that treat supply chain design as a compliance and responsiveness issue, rather than purely a cost-minimization exercise, are more likely to sustain margin stability through regulatory and demand shocks.
Competitive Landscape and Leading Strategies
The competitive field combines established multinational manufacturers, specialized respirator producers, and sourcing and verification platforms that help institutional buyers navigate approval and authenticity concerns. Leading participants are pursuing distinct strategic positions that reflect their manufacturing base, certification coverage, and go-to-market focus.
Several U.S.-based manufacturers hold active NIOSH approvals and emphasize respirator product lines with surgical variants. 3M Company produces N95 respirators including surgical variants and the 9205+ Aura series, and has reinforced its domestic production posture through new facility investment. Honeywell International Inc. manufactures N95 respirators and surgical N95 variants while maintaining active NIOSH approvals, positioning around recognizable brand trust and institutional procurement familiarity. Kimberly-Clark Corporation produces N95 respirators and surgical masks with active NIOSH approvals, leveraging broader health and hygiene commercial infrastructure to support distribution and buyer relationships. DemeTech Corporation manufactures N95 respirators and surgical masks with ASTM Level 3 compliance and holds active NIOSH approvals, emphasizing specification alignment for higher-barrier surgical use cases. These players share a common strategic thread: maintaining active approvals, expanding or protecting domestic capacity where advantageous, and aligning product lines with procurement categories that value both respiratory protection and fluid-resistance performance.
International manufacturers are competing through certification breadth, model variety, and regional market presence. Makrite produces surgical N95 respirators, ASTM Level 1-3 surgical masks, and KN95/FFP2 variants, with active NIOSH, CE, and other certifications. Its exhibition activity at Tool Japan 2025 reflects a market-facing strategy that emphasizes cross-variant availability and direct engagement with procurement and distribution channels. Harley Commodity produces surgical N95 respirators with adjustable head straps and holds active NIOSH approvals and FDA clearance, focusing on fit-oriented design and compliance documentation that supports institutional purchasing requirements. These companies illustrate how non-domestic producers can remain relevant by combining certification coverage with product features that address wearability, specification range, and channel visibility.
A separate but important part of the landscape is occupied by verification and distribution intermediaries such as Project N95, which vets, sources, and distributes N95 respirators and KN95 masks from approved manufacturers. This model addresses a persistent market need: buyers want to reduce the risk of sourcing non-conforming products and need practical pathways to approved supply. The presence of such organizations indicates that trust and verification are becoming more valuable as compliance scrutiny intensifies and procurement teams seek to reduce administrative and product-risk burdens.
The market structure is evolving along three directions. First, consolidation pressure exists where scale, approval maintenance, and distribution reach create advantages, particularly in healthcare procurement where supplier reliability is heavily weighted. Second, differentiation is increasing among manufacturers that can combine approval stability with product features such as fit adjustment, surgical compatibility, or multi-standard coverage. Third, new-entry and intermediary activity is likely to persist where verification, sourcing transparency, and regulatory navigation offer commercial value. The overall effect is a market that rewards compliance discipline and supply reliability as much as production volume.
Future Trends and Commercial Opportunities
Looking toward the next three to five years, several trends are likely to shape commercial outcomes. The first is a more formal separation between emergency-surge purchasing and routine procurement. As policy frameworks settle into structured oversight and domestic sourcing incentives, buyers will likely standardize around suppliers that can demonstrate steady approval status, consistent documentation, and resilient supply. This creates opportunity for manufacturers that invest early in quality system robustness, approval maintenance, and transparent communication about certification status. It also raises the importance of portfolio planning so that product offerings match the specifications most likely to be required in routine healthcare and institutional purchasing.
The second trend is the widening role of standards and verification as commercial differentiators. Updated mask performance standards and ongoing conformity assessment activity increase the value of demonstrable compliance. Companies that can align product design, testing, and documentation with current requirements will face fewer market-access frictions and will be better positioned to serve buyers who must justify purchasing decisions through compliance evidence. Verification-focused intermediaries and platform models may also gain stature as buyers look for reduced-risk sourcing pathways, especially when approval status or product origin must be confirmed quickly.
The third trend is geographic and supply chain reconfiguration. Domestic capacity investments and procurement incentive signals suggest that regional supply resilience will become a more important part of commercial positioning. This does not mean global production will disappear, but it does mean that dual-sourcing strategies, regional backup capacity, and procurement-channel alignment will matter more than in the pre-2020 era. Businesses that can offer supply flexibility while maintaining approval integrity will be better placed to capture demand from buyers who are balancing cost, compliance, and continuity.
These trends carry commercial opportunities for different players. Manufacturers can pursue portfolio breadth that covers respirator and surgical needs, invest in approval maintenance and testing alignment, and develop supply-chain flexibility that supports both domestic and export channels. Investors can focus on companies with stable certification positions, credible compliance infrastructure, and credible pathways to benefit from domestic procurement preference shifts. Procurement organizations can reduce risk by prioritizing suppliers with transparent approval status, diversified sourcing options, and documentation that supports audit and compliance requirements. At the same time, uncertainty remains. Approval rescissions, evolving enforcement discretion guidance, and changes in reimbursement or procurement incentive rules can alter competitive positioning quickly. Businesses should therefore treat compliance status and sourcing flexibility as living strategic assets rather than fixed advantages.
Medical Face Masks Market
Strategic Actions for Decision-Makers
For manufacturers, the priority is to treat certification and compliance as core commercial infrastructure. Maintaining active approvals, aligning products with current standards, and communicating approval status clearly can reduce market-access risk and improve buyer confidence. Portfolio planning should anticipate overlap between respirator and surgical mask requirements, since many institutional buyers prefer suppliers that can serve multiple specifications without fragmenting the supply base. Supply chain design should incorporate regional flexibility where possible, both to respond to procurement preference signals and to improve continuity during disruption. Companies that combine technical credibility with supply resilience are more likely to secure recurring institutional demand.
For investors, due diligence should place significant weight on approval stability, quality system maturity, and exposure to regulatory or procurement shifts. Revenue growth potential is important, but in a market where approval status can change and compliance costs can rise, the durability of a company's certification portfolio and its ability to maintain supply under scrutiny may be equally decisive. Preference should be given to businesses that demonstrate clear compliance documentation, diversified product coverage, and realistic pathways to benefit from domestic sourcing incentives without overconcentrating risk in a single channel or geography.
For procurement leaders and institutional buyers, the strategic imperative is to move from transactional sourcing to supply assurance planning. That means evaluating suppliers on approval continuity, documentation transparency, and the ability to provide consistent product across respirator and surgical categories where needed. Diversification of approved sources, attention to standard updates such as EN 14683:2025, and alignment with procurement incentives that may favor domestic supply can reduce both compliance and continuity risk. Verification support from trusted intermediaries can also help reduce the administrative burden of confirming approval status and product authenticity.
Detailed segmentation data, company-level benchmarking, and scenario-based procurement guidance can materially improve the speed and quality of these decisions. The broader market trajectory is clear enough to justify strategic action, but the value of any specific move depends on precise figures, approval-status mapping, and procurement-context nuance that vary by region, application, and buyer type. Readers seeking deeper segmentation detail, competitive benchmarking, and customized sourcing or investment implications can access the full PW Consulting market research report for comprehensive data and tailored analysis supporting the strategic directions outlined here.
For detailed analysis of this topic, please visit the official page: Medical Protective Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sodium Chlorite Market: Why 5.49% CAGR and Water Treatment Demand Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Sodium Chlorite Market
Sodium chlorite has steadily moved from a niche chemical intermediate to a critical enabler of modern water disinfection, industrial bleaching, and food safety processes. The market’s trajectory over the past five years reflects a broader shift toward safer disinfectants, stricter water quality mandates, and the need for reliable on-site generation chemistry. With a market valued at USD 231.3 million in 2025 and an expected climb to USD 335.9 million by 2032, the sector is expanding at a compound annual growth rate of 5.49 percent. This growth is neither accidental nor purely cyclical; it is being shaped by a combination of regulatory momentum, technological maturation, and supply-side restructuring that together create distinct strategic entry points for manufacturers, investors, and procurement leaders.
Sodium Hypochlorite Market
Behind the headline figures lies a market that is structurally bifurcated. Industrial and technical grade chemistry continues to dominate volume, driven by pulp and paper processing, textile bleaching, and large-scale disinfection systems. Food grade and potable water compliant grades, while smaller in total revenue, command higher regulatory scrutiny and often stronger pricing power where certified supply is constrained. The geographic distribution of demand further complicates the picture, with mature water infrastructure markets in Europe and North America anchoring steady consumption, while Asia Pacific reflects faster capacity additions and shifting industrial footprints. Rather than treating the market as a single block, executives should view it as a set of interconnected demand pockets, each with its own regulatory cadence, certification requirements, and supply reliability expectations.
Core Challenges and Inflection Points
The sodium chlorite market is entering a phase where growth is no longer guaranteed by end-use expansion alone. Several structural challenges are reshaping how value is created and captured.
- Raw material and energy volatility is pressuring cost structures. The electrochemical production of sodium chlorite is closely linked to sodium chlorate pricing and electricity costs. As chlorate prices have moved sharply in key production hubs, downstream manufacturers face more unpredictable input economics, which complicates long-term pricing agreements and margin planning.
- Regulatory and certification friction is raising the barrier to supply. Drinking water quality standards, NSF/ANSI certifications, and municipal approval processes are becoming more stringent and more visible. Suppliers that cannot demonstrate compliant grades, traceable manufacturing, and robust quality documentation are increasingly shut out of high-value water treatment contracts.
- Capacity realignment is creating both risk and opportunity. The industry is witnessing selective closures and targeted expansions rather than broad-based build-outs. Some producers are narrowing their chlor-alkali portfolios, while others are adding sodium chlorite-specific capacity to serve faster-growing disinfection and water treatment demand. This uneven landscape is redrawing regional availability and competitive dynamics.
These challenges matter because they alter the competitive logic of the market. Sodium chlorite is not a commodity in practice; it is a regulated, application-specific chemical where reliability, certification, and technical support often matter as much as unit price. The inflection point is that buyers and suppliers alike can no longer rely on static supply assumptions. Strategic decisions now need to account for input cost exposure, certification readiness, and the willingness of leading producers to invest in compliant capacity where demand is most regulated and most durable.
Key Drivers Shaping the Market
Technological Innovation and On-Site Generation
One of the most important demand engines for sodium chlorite is its role in chlorine dioxide generation systems. On-site generation offers water utilities and industrial operators a way to produce disinfectant close to the point of use, reducing storage risks and improving operational flexibility. This application model favors sodium chlorite suppliers that can provide consistent grades, reliable logistics, and technical integration support rather than competing solely on bulk pricing.
Technological progress is also improving the usability and safety profile of sodium chlorite in industrial settings. Better handling protocols, more standardized dosing practices, and improved compatibility with downstream generation equipment are reducing operational friction. For end users, this translates into lower total cost of ownership even when chemical prices rise. For suppliers, it opens the door to value-added positioning: certified product lines, application guidance, and dependable supply continuity become differentiators rather than extras.
Recent capacity moves by established producers underscore this shift. Expanding sodium chlorite production to support water treatment utilities adopting chlorine dioxide disinfection systems signals that manufacturers see durable demand tied to infrastructure modernization and disinfection upgrades. That kind of investment is rarely made in response to short-term price spikes; it reflects confidence in a structural application trend.
PW Consulting
Policy, Regulation, and Certification as Demand Catalysts
Regulation is not merely a constraint in this market; it is a demand shaper. Stricter drinking water quality expectations, evolving disinfection byproduct management, and municipal procurement standards are pushing utilities toward disinfectants and generation chemistries that meet higher compliance thresholds. Sodium chlorite’s relevance in potable water treatment depends heavily on certification and documented compliance, which means regulatory momentum can directly translate into incremental demand for approved grades.
Certification renewal and expansion are concrete indicators of how regulatory alignment supports commercial access. Renewed NSF/ANSI/CAN 60 certification for expanded product lines used in municipal drinking water treatment reinforces a supplier’s ability to participate in regulated water markets. In practice, these certifications function as market access credentials. They reduce procurement risk for utilities, shorten approval cycles, and increase theStrategic Trends and Commercial Opportunities in the Sodium Chlorite Market strategic value of the supplier relationship. For market participants, the implication is clear: regulatory readiness is becoming a competitive asset, not a compliance overhead.
Demand-Side Shifts in Industrial and Municipal Users
End-user behavior is changing in ways that favor reliability and service depth. Water utilities and industrial buyers are increasingly focused on supply resilience, especially where disinfection systems are integrated into critical operations. This is not simply about finding the lowest price per metric ton; it is about minimizing downtime, avoiding qualification delays, and ensuring that the chemical supplied matches the exact specifications required by generation equipment and end-use standards.
In parallel, industrial users in pulp, paper, and textiles continue to rely on sodium chlorite for bleaching and disinfection, but their purchasing logic is becoming more sophisticated. Mills and manufacturers are weighing chemical consistency, inventory buffers, and the operational impact of switching grades. Where sodium chlorite can deliver predictable performance with fewer process adjustments, it earns a stronger place in the input mix. That dynamic benefits suppliers that can prove consistency across batches and provide application-level support.
Supply Chain and Cost Structure Realignment
The supply side is undergoing a quieter but equally important transformation. Sodium chlorite economics are sensitive to upstream chlor-alkali dynamics, energy costs, and plant utilization decisions. Electricity cost volatility has already surfaced as a material factor in chlorate pricing, and because chlorate is a key input for chlorite production, the effect cascades downstream. This means cost leadership is increasingly tied to energy efficiency, plant location, and input procurement strategy rather than to scale alone.
At the same time, producers are making deliberate portfolio choices. Some are closing loosely aligned operations to streamline their chlor-alkali footprint. Others are expanding sodium chlorite capacity in regions where water treatment demand and regulatory compliance create stronger revenue visibility. The net effect is a market in which supply security is being re-evaluated. Buyers may need to qualify multiple sources, and suppliers may need to decide where to commit capital to compliant, cost-efficient capacity. This realignment creates opportunities for producers that can combine regulatory credibility with disciplined cost management.
Competitive Landscape and Leading Strategies
The competitive field in sodium chlorite is concentrated but not uniform. With a CR3 near 31.9 percent and a CR5 near 42.5 percent, the market has meaningful incumbency advantages, yet there is still room for differentiation based on grade specialization, regional presence, certification strength, and technical service. The leading companies illustrate several distinct strategic postures.
- ERCO Worldwide has positioned itself as a leading supplier of bulk sodium chlorite for on-site chlorine dioxide generation across water treatment, food safety, and industrial disinfection. Its recent production capacity expansion in North America and its decision to close sodium chlorate operations at a Manitoba site both point to a focused strategy: concentrate resources on higher-value chlorite-related demand while simplifying the broader portfolio. This suggests a company optimizing for application relevance and supply prioritization rather than trying to compete across every chlor-alkali segment.
- International Dioxcide is known as the largest producer and distributor of bulk sodium chlorite in North America under its ERCOPure™ brand, with strong EPA and ANSI/NSF credentials. Its strategic advantage lies in scale within a regulated geography, combined with the certifications that unlock municipal and industrial water applications. In a market where compliance documentation can be as decisive as price, this positioning is commercially powerful.
- OxyChem stands out as the only U.S. producer of sodium chlorite, manufacturing Purox S and OxyChlorite grades at its Wichita facility for water treatment and disinfection. Its recent NSF/ANSI/CAN 60 certification renewal for an expanded product line reinforces domestic supply credibility for municipal drinking water use. The “only U.S. producer” positioning gives it a structural role in domestic supply continuity discussions, which can be especially valuable where local content, logistics, and approval timelines matter.
- Ercros operates as the largest European manufacturer of sodium chlorite, with multiple production plants and grades tailored for potable and industrial water treatment. Its regional scale in Europe positions it well for markets where water infrastructure compliance and industrial disinfection demand intersect. In a region with mature regulatory expectations, a locally anchored supply base with multiple plants can provide resilience and responsiveness that distant suppliers struggle to match.
- Osaka Soda Co., Ltd. reflects a different application emphasis, with significant production tied to textile bleaching, disinfecting detergents, fabric softeners, and broader industrial uses. Its strategy illustrates how sodium chlorite demand can be diversified beyond water treatment into consumer-adjacent and industrial chemical applications. This diversification can cushion exposure to any single regulatory cycle while requiring strong application expertise and consistent grade control.
These profiles show that leadership in sodium chlorite is not defined solely by tonnage. It is increasingly defined by the ability to secure regulated market access, maintain supply reliability, and align capacity with the most defensible demand pockets. The competitive landscape is likely to keep evolving through selective expansion, portfolio narrowing, and continued emphasis on certification and technical support. New entrants will face the practical hurdle of establishing compliance credibility and supply trust, while existing players may compete more intensely on service, availability, and regional coverage than on headline price alone.
Future Trends and Commercial Implications
Trend 1: Regulated Water Treatment Demand Will Remain the Strongest Structural Anchor
Over the next three to five years, sodium chlorite demand tied to water treatment and disinfection is likely to remain the most durable growth engine. Municipal and industrial users continue to modernize disinfection practices, and compliance-driven procurement tends to be less elastic than price-driven procurement. The commercial implication is that suppliers with certified, application-ready products will have more resilient demand than those competing only in less regulated segments. For buyers, the opportunity lies in locking in reliable supply partnerships before certification cycles or capacity constraints tighten availability.
A related risk is that regulatory intensity can also increase compliance costs and delay new supply qualification. If certification requirements become more demanding or if approval timelines lengthen, the market may reward established, already-approved suppliers even more. That would reinforce concentration among players with strong compliance infrastructure and reduce the speed at which new capacity can be commercially absorbed.
Trend 2: Cost and Energy Dynamics Will Separate Efficient Producers from the Rest
Electricity cost volatility and chlorate pricing will continue to shape the economics of sodium chlorite production. In this environment, the winners are likely to be producers that can manage input exposure, optimize electrochemical efficiency, and choose plant footprints that balance logistics with energy economics. This is not just a margin issue; it is a strategic survivability issue. Producers with weaker cost structures may face difficult choices between shrinking margins, portfolio narrowing, or exiting less competitive segments.
For investors and corporate strategists, the practical implication is to evaluate sodium chlorite opportunities through a cost-structure lens as much as through demand projections. Capacity announcements are useful signals, but they only translate into durable advantage if they are paired with energy efficiency, input procurement discipline, and the ability to serve regulated demand without excessive cost penalties.
Trend 3: Regional Supply Realignment Will Create Localized Opportunities and Vulnerabilities
The market is moving toward a more regionally uneven supply picture. Some areas will see capacity additions driven by water treatment demand and regulatory compliance, while others may experience tighter availability due to portfolio streamlining or plant rationalization. This creates a dual dynamic: regional suppliers with compliant capacity can gain bargaining power and customer loyalty, while buyers in constrained regions may need to diversify sources or accept higher logistical complexity to secure supply.
In practical terms, this trend favors strategies that emphasize regional reliability, qualified backup supply, and strong customer technical support. It also suggests that procurement teams should revisit supply continuity assumptions, especially for critical applications where disruption carries operational or compliance consequences. The market is not necessarily becoming more global in a uniform sense; it is becoming more sensitive to where compliant capacity is located and how easily it can be accessed.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
- Prioritize certification and compliance readiness as a commercial asset. In regulated water and food-related applications, approved grades and documented quality systems often determine market access more directly than marginal price differences.
- Reassess portfolio fit in light of input cost volatility. Where sodium chlorite aligns with stronger demand visibility and better cost discipline, capacity and service investment are more likely to generate durable returns than broad, undifferentiated expansion.
- Strengthen application-level support. Suppliers that help customers integrate sodium chlorite into chlorine dioxide generation, bleaching, or disinfection processes can build stickier relationships and reduce price-only competition.
For Investors
- Focus on compliance-linked demand rather than aggregate volume growth alone. Segments tied to water treatment, municipal disinfection, and certified grades tend to offer more predictable commercial logic when regulatory scrutiny is rising.
- Evaluate energy and input exposure carefully. Sodium chlorite economics are sensitive to electricity costs and chlorate pricing, so production advantage increasingly depends on cost structure and plant efficiency, not simply scale.
- Watch for capacity realignment signals. Selective expansions and closures can reshape regional availability and competitive positioning, creating both acquisition/distress opportunities and supply risk warnings.
For Procurement and End-User Buyers
- Treat supply reliability and certification as primary selection criteria, especially for critical water treatment and disinfection applications. Price optimization should not come at the expense of qualified, consistent supply.
- Qualify backup sources where operational continuity is important. Regional supply realignment can create localized tightness, and multiple qualified suppliers can reduce exposure to single-source disruption.
- Align specification and inventory strategy with application requirements. Consistent grade specifications, clear handling protocols, and appropriate buffer stock can lower operational risk and improve total cost outcomes over time.
The sodium chlorite market is entering a phase where success depends less on treating the chemical as a generic bulk input and more on managing it as a regulated, application-specific enabler. Demand linked to water treatment, disinfection, and certified grades is likely to remain the most resilient core, while cost dynamics, energy volatility, and regional capacity choices will determine who can serve that demand profitably and reliably. For executives and investors, the most valuable next step is to move from broad market awareness to a sharper understanding of grade-level demand, regulatory access, regional supply positioning, and the cost structures behind competing producers. Detailed segmentation data, company-level capacity context, and tailored scenario analysis can make those decisions far more precise, especially in a market where compliance and supply continuity increasingly define commercial advantage.
Sodium Chlorate Market
For detailed analysis of this topic, please visit the official page: Sodium Chlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High Carbon Bearing Steel Market: Why 6.4% CAGR Redefines 2032 Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the High Carbon Bearing Steel Market
The high carbon bearing steel market has evolved from a steady industrial commodity segment into a strategically critical materials market shaped by precision engineering demands, regulatory tightening, and shifting end-use requirements. Valued at approximately USD 146.55 million in 2025, the market reflects a consistent growth trajectory from its 2020 base of roughly USD 109.55 million, with a forecast extending through 2032 that points to a compound annual growth rate of 6.4 percent. This expansion is not merely a function of broader industrial output; it signals a structural realignment in how bearing steels are specified, manufactured, and integrated into downstream products. As companies navigate tighter performance tolerances, sustainability mandates, and raw material volatility, the market is increasingly rewarding players who can couple metallurgical precision with supply chain resilience.
Market Snapshot and Structural Challenges
The market's size and growth profile underscore a segment that is expanding at a pace above many traditional specialty steel categories, yet it remains highly concentrated. A handful of producers command the majority of share, reflecting the technical barriers to entry, capital intensity of advanced melting and refining processes, and the long qualification cycles required by demanding end users. Revenue streams are distributed across multiple product forms, with bearing steel bars representing the dominant configuration, while plates, wire, tubes, and rods serve more specialized or volume-sensitive applications. Demand is anchored by several sectors, with automotive and industrial machinery forming the core consumption base, while aerospace, railway, and marine applications contribute incremental but increasingly strategic growth.
Key Challenges and Inflection Points
Three interlocking challenges are reshaping competitive dynamics and forcing strategic recalibration.
- Raw material and energy cost volatility: High carbon bearing steel production is highly sensitive to input price swings. Iron ore fluctuations alone have been shown to impact total production costs by up to 32 percent annually, while chromium costs vary by roughly 27 percent year over year. Energy represents another substantial burden, accounting for 20 to 25 percent of manufacturing expenses, with recent electricity price increases of about 18 percent adding pressure to margins and pricing stability.
- Regulatory and specification upgrades: Domestic mills in key regions are facing tighter cleanliness and inclusion standards that effectively require ladle furnace and vacuum degassing investments. In China, regulatory revisions have mandated cleanliness benchmarks aligned with recognized international bearing specifications, compressing the gap between domestic capability and global-tier performance. These changes raise capital requirements and accelerate the differentiation between mills that can meet advanced specifications and those that cannot.
- Demand fragmentation and qualification cycles: End-use sectors are increasingly requiring higher consistency, cleanliness, and traceable performance. Automotive powertrain designs, industrial machinery under higher cycle loads, and aerospace components all impose more stringent metallurgical expectations. At the same time, qualification timelines remain long, which limits how quickly new entrants can access premium segments and reinforces the advantage of established relationships and documented reliability.
For decision makers, these challenges translate into a simple but demanding reality: scale alone is insufficient. The winners will be those who combine cost discipline with technical capability, secure predictable input strategies, and align product development with the specifications that end users are rapidly institutionalizing.
Core Drivers of Market Change
Technological Innovation in Melting and Refining
Advances in secondary refining are central to the market's trajectory. Vacuum degassing and controlled ladle furnace treatments are no longer optional enhancements for premium bearing steel; they are becoming baseline requirements to manage inclusion content, control carbon and chromium distributions, and ensure consistent hardness and fatigue performance. Mills that have integrated these processes are better positioned to serve automotive and aerospace segments where failure risk is unacceptable and cleanliness tolerances are increasingly narrow. This technological shift also creates a natural filter in the competitive landscape: producers with modernized assets can capture higher-value orders, while those relying on older process chains face margin compression and reduced access to specification-driven demand.
Policy and Regulatory Tightening
Regulatory evolution is accelerating both capability upgrades and market realignment. The push toward cleanliness standards that mirror global bearing specifications is compelling domestic producers to invest in advanced refining, which in turn raises the bar for what qualifies as a competitive offering. Beyond product specifications, environmental and energy policies are reshaping operating economics. Energy cost trends, emissions considerations, and efficiency mandates are pushing producers to evaluate furnace optimization, process heat recovery, and more precise control over melting cycles. For companies operating across jurisdictions, regulatory divergence can become both a risk and an opportunity: early compliance and documentation can shorten sourcing approvals, while lagging capability can restrict market access.
Demand-Side Shifts Toward Reliability and Service Life
End users are increasingly prioritizing bearing steels that support longer service life, reduced maintenance intervals, and predictable performance under variable loads and speeds. Automotive manufacturers are seeking materials that can withstand higher rotational speeds and temperature variations while maintaining dimensional stability. Industrial machinery operators are under pressure to improve uptime and reduce total cost of ownership, which favors materials with consistent cleanliness and superior fatigue behavior. In aerospace and railway applications, where reliability is paramount, the demand for tighter control over microstructure and inclusion content is further reinforcing the move toward higher-specification grades. This demand-side evolution is not simply about volume growth; it is about a shift toward value-accretive specifications that reward technical differentiation and stable supply.
Supply Chain and Cost Structure Realignment
Raw material volatility and energy cost pressures are driving a rethinking of procurement and production strategies. Because iron ore and chromium price movements can materially affect total costs, producers are increasingly evaluating long-term contracting, alternative sourcing, and inventory buffering strategies to protect margins. At the same time, energy intensity is prompting attention to process efficiency and plant-level optimization. This environment favors organizations that can integrate metallurgical capability with disciplined procurement and operational flexibility, especially as end users seek suppliers who can offer stable pricing, documented quality, and continuity of supply in an unpredictable input environment.
Competitive Landscape and Leading Strategies
The market's concentrated structure reflects the technical and capital requirements of producing high-quality bearing steel at scale. Leading players are differentiating themselves through a combination of metallurgical specialization, application-targeted development, and selective capacity or product expansion. The result is a landscape where competitive advantage is increasingly tied to specification readiness, process control, and the ability to serve demanding end markets without compromising consistency.
Strategic Positioning Among Key Players
Several companies illustrate distinct paths to differentiation. Specialist steelmakers focused on high-tech engineering grades are building reputation and backlog in automotive and industrial bearing applications by offering dedicated high carbon bearing steel grades with tight tolerances and proven reliability. In Japan, producers with integrated portfolios and strong aerospace and industrial bearing focus are expanding capacity or refining product lines to capture premium demand, signaling a deliberate move toward higher-value applications. In China, major producers are leveraging environmentally conscious production methods and broadening their processed bearing steel offerings for industrial machinery, while others are expanding product ranges to address industrial performance requirements more comprehensively. These strategies point to a broader pattern: successful participants are aligning product development with the most specification-sensitive applications, investing in process capability, and using application-focused portfolios to build switching costs and customer loyalty.
Recent Developments as Strategic Signals
Recent company actions underscore where value is being sought. Capacity expansion directed at aerospace demand reflects the premium that highly controlled bearing steel commands in sectors where failure risk is unacceptable and documentation is rigorous. New product launches targeting industrial machinery indicate an effort to broaden exposure to high-performance applications while building on existing commercial relationships. Taken together, these moves suggest a market in which growth is increasingly captured by producers that can move beyond generic supply and into application-engineered solutions with verified performance.
Market Structure Evolution
The market is likely to see continued consolidation among producers that can fund advanced refining, maintain consistent quality, and serve demanding applications, while smaller or less-equipped mills may face pressure to specialize, partner, or exit higher-specification segments. New entry remains challenging due to qualification cycles and capital intensity, but targeted partnerships, subcontracting, and niche product development can provide pathways for specialized players. For buyers, this environment rewards diversification of qualified suppliers where feasible, combined with deeper collaboration with preferred producers to secure consistency, lead times, and specification alignment.
PW Consulting
Future Outlook: Trends and Commercial Implications
Trend One: Specification Upgrading as the New Baseline
Over the next three to five years, cleanliness and inclusion control are expected to become standard expectations across more applications, not just aerospace or premium automotive niches. Mills that have already invested in advanced refining will be able to serve a wider range of orders with minimal additional reconfiguration, while others will face rising obsolescence risk for legacy process chains. The commercial opportunity lies in aligning product portfolios with the specifications that procurement and engineering teams are institutionalizing, and in building the documentation and traceability that accelerate sourcing decisions.
High Strength Steel Market
Trend Two: Cost and Supply Resilience as a Competitive Moat
Given the sensitivity of production costs to iron ore, chromium, and energy prices, companies that can stabilize input exposure and optimize energy use will be better positioned to offer reliable pricing and continuity. This is likely to become a differentiator in bids and long-term supply agreements, especially for industrial machinery and railway applications where procurement teams value predictability. The strategic play is to combine technical quality with procurement and operational discipline, turning cost resilience into a repeatable advantage rather than a temporary buffer.
Bearing Steel Market
Trend Three: Application-Linked Product Development
As end-use requirements become more segmented, generic bearing steel offerings will increasingly give way to grades developed with specific application profiles in mind. The most attractive opportunities will be in segments where performance improvements translate directly into measurable gains: reduced wear, extended service intervals, higher load capacity, or better stability under variable conditions. Producers and suppliers that can co-develop grades with end users, supported by consistent process control and documented test data, are likely to capture stronger positioning and more defensible margins.
Risks and Uncertainties
The outlook is not without risk. Continued raw material and energy volatility could erode margins for producers without hedging or efficiency strategies. Regulatory divergence across regions may complicate global supply strategies and increase compliance costs. Qualification lead times and documentation burdens may slow the ability of new or upgraded players to access premium segments. Finally, demand patterns in automotive and industrial machinery can shift with broader economic cycles, influencing order timing and inventory behavior. Navigating these uncertainties will require a balance of technical readiness, supply discipline, and relationship depth.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to ensure that process capability matches the specifications that buyers are increasingly demanding. Investments in secondary refining, process control, and quality documentation are not optional enhancements; they are becoming prerequisites for access to higher-value orders and longer-term agreements. Manufacturers should also evaluate procurement and energy strategies as part of a holistic competitive plan, since input volatility can quickly undermine the benefits of technical differentiation. Aligning product development with application profiles and maintaining close dialogue with key customers can help convert specification readiness into repeat business.
For investors, the market rewards companies that combine metallurgical capability with disciplined cost management and clear application focus. Asset quality, specification breadth, and the ability to serve demanding segments are indicators of resilience and pricing power, while exposure to volatile input markets and legacy process chains can create disproportionate risk. Monitoring capacity actions, product launches, and regulatory-driven upgrades can provide early signals about which players are likely to expand their share of premium demand versus those that may face margin pressure.
For procurement and sourcing leaders, the emphasis should be on qualifying suppliers not only for price but for specification compliance, consistency, and supply continuity.Diversification of qualified sources can reduce concentration risk, while deeper collaboration with preferred producers can secure better alignment on lead times, cleanliness requirements, and documentation standards. In a market where cost volatility and specification upgrades are reshaping supply options, a procurement strategy that values technical reliability alongside price will be better positioned to protect downstream performance and total cost of ownership.
The high carbon bearing steel market is entering a phase where technical precision, regulatory compliance, and supply resilience converge to define competitive advantage. Detailed segmentation data, regional dynamics, and company-level development timelines can sharpen these strategic choices further, providing the granularity needed to prioritize investments, qualify suppliers, and time market entries with greater confidence.
For detailed analysis of this topic, please visit the official page: High Carbon Bearing Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com