

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Sodium Chlorite Market: Why 5.49% CAGR and Water Treatment Demand Redefine Growth

Strategic Trends and Commercial Opportunities in the Sodium Chlorite Market
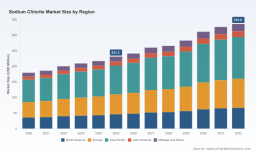
Sodium chlorite has steadily moved from a niche chemical intermediate to a critical enabler of modern water disinfection, industrial bleaching, and food safety processes. The market’s trajectory over the past five years reflects a broader shift toward safer disinfectants, stricter water quality mandates, and the need for reliable on-site generation chemistry. With a market valued at USD 231.3 million in 2025 and an expected climb to USD 335.9 million by 2032, the sector is expanding at a compound annual growth rate of 5.49 percent. This growth is neither accidental nor purely cyclical; it is being shaped by a combination of regulatory momentum, technological maturation, and supply-side restructuring that together create distinct strategic entry points for manufacturers, investors, and procurement leaders.
Sodium Hypochlorite Market
Behind the headline figures lies a market that is structurally bifurcated. Industrial and technical grade chemistry continues to dominate volume, driven by pulp and paper processing, textile bleaching, and large-scale disinfection systems. Food grade and potable water compliant grades, while smaller in total revenue, command higher regulatory scrutiny and often stronger pricing power where certified supply is constrained. The geographic distribution of demand further complicates the picture, with mature water infrastructure markets in Europe and North America anchoring steady consumption, while Asia Pacific reflects faster capacity additions and shifting industrial footprints. Rather than treating the market as a single block, executives should view it as a set of interconnected demand pockets, each with its own regulatory cadence, certification requirements, and supply reliability expectations.
Core Challenges and Inflection Points
The sodium chlorite market is entering a phase where growth is no longer guaranteed by end-use expansion alone. Several structural challenges are reshaping how value is created and captured.
- Raw material and energy volatility is pressuring cost structures. The electrochemical production of sodium chlorite is closely linked to sodium chlorate pricing and electricity costs. As chlorate prices have moved sharply in key production hubs, downstream manufacturers face more unpredictable input economics, which complicates long-term pricing agreements and margin planning.
- Regulatory and certification friction is raising the barrier to supply. Drinking water quality standards, NSF/ANSI certifications, and municipal approval processes are becoming more stringent and more visible. Suppliers that cannot demonstrate compliant grades, traceable manufacturing, and robust quality documentation are increasingly shut out of high-value water treatment contracts.
- Capacity realignment is creating both risk and opportunity. The industry is witnessing selective closures and targeted expansions rather than broad-based build-outs. Some producers are narrowing their chlor-alkali portfolios, while others are adding sodium chlorite-specific capacity to serve faster-growing disinfection and water treatment demand. This uneven landscape is redrawing regional availability and competitive dynamics.
These challenges matter because they alter the competitive logic of the market. Sodium chlorite is not a commodity in practice; it is a regulated, application-specific chemical where reliability, certification, and technical support often matter as much as unit price. The inflection point is that buyers and suppliers alike can no longer rely on static supply assumptions. Strategic decisions now need to account for input cost exposure, certification readiness, and the willingness of leading producers to invest in compliant capacity where demand is most regulated and most durable.
Key Drivers Shaping the Market
Technological Innovation and On-Site Generation
One of the most important demand engines for sodium chlorite is its role in chlorine dioxide generation systems. On-site generation offers water utilities and industrial operators a way to produce disinfectant close to the point of use, reducing storage risks and improving operational flexibility. This application model favors sodium chlorite suppliers that can provide consistent grades, reliable logistics, and technical integration support rather than competing solely on bulk pricing.
Technological progress is also improving the usability and safety profile of sodium chlorite in industrial settings. Better handling protocols, more standardized dosing practices, and improved compatibility with downstream generation equipment are reducing operational friction. For end users, this translates into lower total cost of ownership even when chemical prices rise. For suppliers, it opens the door to value-added positioning: certified product lines, application guidance, and dependable supply continuity become differentiators rather than extras.
Recent capacity moves by established producers underscore this shift. Expanding sodium chlorite production to support water treatment utilities adopting chlorine dioxide disinfection systems signals that manufacturers see durable demand tied to infrastructure modernization and disinfection upgrades. That kind of investment is rarely made in response to short-term price spikes; it reflects confidence in a structural application trend.
PW Consulting
Policy, Regulation, and Certification as Demand Catalysts
Regulation is not merely a constraint in this market; it is a demand shaper. Stricter drinking water quality expectations, evolving disinfection byproduct management, and municipal procurement standards are pushing utilities toward disinfectants and generation chemistries that meet higher compliance thresholds. Sodium chlorite’s relevance in potable water treatment depends heavily on certification and documented compliance, which means regulatory momentum can directly translate into incremental demand for approved grades.
Certification renewal and expansion are concrete indicators of how regulatory alignment supports commercial access. Renewed NSF/ANSI/CAN 60 certification for expanded product lines used in municipal drinking water treatment reinforces a supplier’s ability to participate in regulated water markets. In practice, these certifications function as market access credentials. They reduce procurement risk for utilities, shorten approval cycles, and increase theStrategic Trends and Commercial Opportunities in the Sodium Chlorite Market strategic value of the supplier relationship. For market participants, the implication is clear: regulatory readiness is becoming a competitive asset, not a compliance overhead.
Demand-Side Shifts in Industrial and Municipal Users
End-user behavior is changing in ways that favor reliability and service depth. Water utilities and industrial buyers are increasingly focused on supply resilience, especially where disinfection systems are integrated into critical operations. This is not simply about finding the lowest price per metric ton; it is about minimizing downtime, avoiding qualification delays, and ensuring that the chemical supplied matches the exact specifications required by generation equipment and end-use standards.
In parallel, industrial users in pulp, paper, and textiles continue to rely on sodium chlorite for bleaching and disinfection, but their purchasing logic is becoming more sophisticated. Mills and manufacturers are weighing chemical consistency, inventory buffers, and the operational impact of switching grades. Where sodium chlorite can deliver predictable performance with fewer process adjustments, it earns a stronger place in the input mix. That dynamic benefits suppliers that can prove consistency across batches and provide application-level support.
Supply Chain and Cost Structure Realignment
The supply side is undergoing a quieter but equally important transformation. Sodium chlorite economics are sensitive to upstream chlor-alkali dynamics, energy costs, and plant utilization decisions. Electricity cost volatility has already surfaced as a material factor in chlorate pricing, and because chlorate is a key input for chlorite production, the effect cascades downstream. This means cost leadership is increasingly tied to energy efficiency, plant location, and input procurement strategy rather than to scale alone.
At the same time, producers are making deliberate portfolio choices. Some are closing loosely aligned operations to streamline their chlor-alkali footprint. Others are expanding sodium chlorite capacity in regions where water treatment demand and regulatory compliance create stronger revenue visibility. The net effect is a market in which supply security is being re-evaluated. Buyers may need to qualify multiple sources, and suppliers may need to decide where to commit capital to compliant, cost-efficient capacity. This realignment creates opportunities for producers that can combine regulatory credibility with disciplined cost management.
Competitive Landscape and Leading Strategies
The competitive field in sodium chlorite is concentrated but not uniform. With a CR3 near 31.9 percent and a CR5 near 42.5 percent, the market has meaningful incumbency advantages, yet there is still room for differentiation based on grade specialization, regional presence, certification strength, and technical service. The leading companies illustrate several distinct strategic postures.
- ERCO Worldwide has positioned itself as a leading supplier of bulk sodium chlorite for on-site chlorine dioxide generation across water treatment, food safety, and industrial disinfection. Its recent production capacity expansion in North America and its decision to close sodium chlorate operations at a Manitoba site both point to a focused strategy: concentrate resources on higher-value chlorite-related demand while simplifying the broader portfolio. This suggests a company optimizing for application relevance and supply prioritization rather than trying to compete across every chlor-alkali segment.
- International Dioxcide is known as the largest producer and distributor of bulk sodium chlorite in North America under its ERCOPure™ brand, with strong EPA and ANSI/NSF credentials. Its strategic advantage lies in scale within a regulated geography, combined with the certifications that unlock municipal and industrial water applications. In a market where compliance documentation can be as decisive as price, this positioning is commercially powerful.
- OxyChem stands out as the only U.S. producer of sodium chlorite, manufacturing Purox S and OxyChlorite grades at its Wichita facility for water treatment and disinfection. Its recent NSF/ANSI/CAN 60 certification renewal for an expanded product line reinforces domestic supply credibility for municipal drinking water use. The “only U.S. producer” positioning gives it a structural role in domestic supply continuity discussions, which can be especially valuable where local content, logistics, and approval timelines matter.
- Ercros operates as the largest European manufacturer of sodium chlorite, with multiple production plants and grades tailored for potable and industrial water treatment. Its regional scale in Europe positions it well for markets where water infrastructure compliance and industrial disinfection demand intersect. In a region with mature regulatory expectations, a locally anchored supply base with multiple plants can provide resilience and responsiveness that distant suppliers struggle to match.
- Osaka Soda Co., Ltd. reflects a different application emphasis, with significant production tied to textile bleaching, disinfecting detergents, fabric softeners, and broader industrial uses. Its strategy illustrates how sodium chlorite demand can be diversified beyond water treatment into consumer-adjacent and industrial chemical applications. This diversification can cushion exposure to any single regulatory cycle while requiring strong application expertise and consistent grade control.
These profiles show that leadership in sodium chlorite is not defined solely by tonnage. It is increasingly defined by the ability to secure regulated market access, maintain supply reliability, and align capacity with the most defensible demand pockets. The competitive landscape is likely to keep evolving through selective expansion, portfolio narrowing, and continued emphasis on certification and technical support. New entrants will face the practical hurdle of establishing compliance credibility and supply trust, while existing players may compete more intensely on service, availability, and regional coverage than on headline price alone.
Future Trends and Commercial Implications
Trend 1: Regulated Water Treatment Demand Will Remain the Strongest Structural Anchor
Over the next three to five years, sodium chlorite demand tied to water treatment and disinfection is likely to remain the most durable growth engine. Municipal and industrial users continue to modernize disinfection practices, and compliance-driven procurement tends to be less elastic than price-driven procurement. The commercial implication is that suppliers with certified, application-ready products will have more resilient demand than those competing only in less regulated segments. For buyers, the opportunity lies in locking in reliable supply partnerships before certification cycles or capacity constraints tighten availability.
A related risk is that regulatory intensity can also increase compliance costs and delay new supply qualification. If certification requirements become more demanding or if approval timelines lengthen, the market may reward established, already-approved suppliers even more. That would reinforce concentration among players with strong compliance infrastructure and reduce the speed at which new capacity can be commercially absorbed.
Trend 2: Cost and Energy Dynamics Will Separate Efficient Producers from the Rest
Electricity cost volatility and chlorate pricing will continue to shape the economics of sodium chlorite production. In this environment, the winners are likely to be producers that can manage input exposure, optimize electrochemical efficiency, and choose plant footprints that balance logistics with energy economics. This is not just a margin issue; it is a strategic survivability issue. Producers with weaker cost structures may face difficult choices between shrinking margins, portfolio narrowing, or exiting less competitive segments.
For investors and corporate strategists, the practical implication is to evaluate sodium chlorite opportunities through a cost-structure lens as much as through demand projections. Capacity announcements are useful signals, but they only translate into durable advantage if they are paired with energy efficiency, input procurement discipline, and the ability to serve regulated demand without excessive cost penalties.
Trend 3: Regional Supply Realignment Will Create Localized Opportunities and Vulnerabilities
The market is moving toward a more regionally uneven supply picture. Some areas will see capacity additions driven by water treatment demand and regulatory compliance, while others may experience tighter availability due to portfolio streamlining or plant rationalization. This creates a dual dynamic: regional suppliers with compliant capacity can gain bargaining power and customer loyalty, while buyers in constrained regions may need to diversify sources or accept higher logistical complexity to secure supply.
In practical terms, this trend favors strategies that emphasize regional reliability, qualified backup supply, and strong customer technical support. It also suggests that procurement teams should revisit supply continuity assumptions, especially for critical applications where disruption carries operational or compliance consequences. The market is not necessarily becoming more global in a uniform sense; it is becoming more sensitive to where compliant capacity is located and how easily it can be accessed.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
- Prioritize certification and compliance readiness as a commercial asset. In regulated water and food-related applications, approved grades and documented quality systems often determine market access more directly than marginal price differences.
- Reassess portfolio fit in light of input cost volatility. Where sodium chlorite aligns with stronger demand visibility and better cost discipline, capacity and service investment are more likely to generate durable returns than broad, undifferentiated expansion.
- Strengthen application-level support. Suppliers that help customers integrate sodium chlorite into chlorine dioxide generation, bleaching, or disinfection processes can build stickier relationships and reduce price-only competition.
For Investors
- Focus on compliance-linked demand rather than aggregate volume growth alone. Segments tied to water treatment, municipal disinfection, and certified grades tend to offer more predictable commercial logic when regulatory scrutiny is rising.
- Evaluate energy and input exposure carefully. Sodium chlorite economics are sensitive to electricity costs and chlorate pricing, so production advantage increasingly depends on cost structure and plant efficiency, not simply scale.
- Watch for capacity realignment signals. Selective expansions and closures can reshape regional availability and competitive positioning, creating both acquisition/distress opportunities and supply risk warnings.
For Procurement and End-User Buyers
- Treat supply reliability and certification as primary selection criteria, especially for critical water treatment and disinfection applications. Price optimization should not come at the expense of qualified, consistent supply.
- Qualify backup sources where operational continuity is important. Regional supply realignment can create localized tightness, and multiple qualified suppliers can reduce exposure to single-source disruption.
- Align specification and inventory strategy with application requirements. Consistent grade specifications, clear handling protocols, and appropriate buffer stock can lower operational risk and improve total cost outcomes over time.
The sodium chlorite market is entering a phase where success depends less on treating the chemical as a generic bulk input and more on managing it as a regulated, application-specific enabler. Demand linked to water treatment, disinfection, and certified grades is likely to remain the most resilient core, while cost dynamics, energy volatility, and regional capacity choices will determine who can serve that demand profitably and reliably. For executives and investors, the most valuable next step is to move from broad market awareness to a sharper understanding of grade-level demand, regulatory access, regional supply positioning, and the cost structures behind competing producers. Detailed segmentation data, company-level capacity context, and tailored scenario analysis can make those decisions far more precise, especially in a market where compliance and supply continuity increasingly define commercial advantage.
Sodium Chlorate Market
For detailed analysis of this topic, please visit the official page: Sodium Chlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com