

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
UV Light Disinfection Market 2026: Why 15.4% CAGR Signals Strategic Shifts Beyond Water Treatment

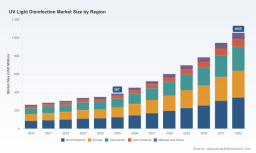
The UV Light Disinfection Market: Strategic Trends and Commercial Opportunities Through 2032
The UV light disinfection market has moved from a niche operational consideration to a central pillar of public health, infrastructure resilience, and facility safety strategies. Over the historical period from 2020 to 2025, the industry demonstrated consistent expansion, with the global market reaching approximately USD 387.0 million by the base year of 2025. Forward projections indicate sustained momentum, with the market expected to grow at a compound annual growth rate of 15.4 percent through the forecast period ending in 2032, ultimately approaching a valuation near USD 1,055.0 million. This trajectory reflects more than cyclical demand recovery; it signals a structural reorientation in how organizations approach microbial risk, regulatory compliance, and operational efficiency.
The scale and pace of this expansion carry meaningful implications for strategic decision-makers. A mid-teens CAGR across a seven-year horizon suggests that UV disinfection is transitioning from reactive procurement to embedded capital planning. The acceleration is not uniform across all use cases or geographies, and the concentration of revenue among a handful of established players indicates that competitive positioning will increasingly depend on regulatory clearance, application-specific validation, and total cost of ownership performance rather than standalone hardware specifications.
Market Snapshot and Structural Context
The market's expansion over the past half-decade has been characterized by broad-based adoption across water infrastructure, healthcare environments, and public-facing facilities. Revenue growth during the historical window reflects a combination of post-pandemic hygiene awareness, aging water treatment assets requiring modernization, and a growing acceptance of ultraviolet technology as a chemical-free or chemical-reducing intervention. The forecast period is expected to extend these dynamics while introducing new layers of complexity around device validation, reimbursement pathways, and cost-competitiveness against conventional alternatives.
A useful way to frame the market's current state is through its concentration profile. The sector remains moderately consolidated, with the top three participants capturing roughly 45 percent of revenue and the top five collectively accounting for approximately 55 percent. This level of concentration suggests that scale advantages, established distribution channels, and existing regulatory track records still matter, but it also leaves meaningful space for specialized entrants that can demonstrate superior performance in narrowly defined applications or high-value clinical workflows. The market is neither fully fragmented nor tightly monopolized, which creates a strategic environment where focused innovation can gain traction before larger players respond through acquisition or product line expansion.
UV Disinfection Equipment Market
Key Challenges and Inflection Points
Despite favorable demand signals, the industry faces several structural challenges that will shape which companies and applications succeed over the next decade. The first challenge revolves around validation and standardization. As UV disinfection moves into more regulated settings, buyers increasingly demand reproducible efficacy data under real-world operating conditions, not just laboratory benchmarks. Devices that cannot clearly demonstrate consistent microbial reduction across variable surface geometries, airflow patterns, or water turbidity profiles will face growing scrutiny from procurement teams and clinical stakeholders.
A second challenge lies in balancing capital expenditure against lifecycle economics. While ultraviolet systems can reduce ongoing chemical handling, manual cleaning labor, and infection-related costs, the upfront investment and replacement cycle for lamps, sleeves, and controller units remain important considerations. Organizations with constrained capital budgets need transparent payback logic, and suppliers must be able to articulate how equipment longevity, energy consumption, and maintenance intervals translate into measurable operational savings. The market is shifting from a purchase-of-equipment mindset to an evaluation of total intervention cost, which raises the bar for commercial messaging and economic modeling.
A third challenge is the growing complexity of regulatory expectations. Health authorities and standards bodies are refining how UV devices should be tested, documented, and integrated into existing infection control or water safety plans. This is a positive development for long-term credibility, but it introduces short-term friction for manufacturers that must navigate differing clearance pathways, regional normative references, and buyer-specific documentation requirements. Companies that treat regulatory engagement as a one-time event rather than an ongoing capability risk losing relevance as procurement criteria become more formalized.
These challenges are not simply obstacles; they are also the forces redefining competitive advantage. Suppliers that align product design, clinical or environmental validation, and economic documentation with the way end-users now make decisions will be better positioned to capture share in a market that is becoming more demanding, not just larger.
Drivers Reshaping the UV Disinfection Landscape
Technology Innovation and Application-Specific Engineering
The most durable driver of market expansion is the continued refinement of ultraviolet hardware and system architecture. Historically, generic lamp-based solutions addressed broad disinfection needs, but the market is increasingly rewarding designs engineered for specific environments and use cases. In healthcare and life sciences, for example, the ability to deliver validated microbial reduction across complex room geometries or sensitive instrumentation has become a key differentiator. Devices that combine targeted emitter configurations, consistent dosing control, and workflow-compatible form factors are gaining traction because they reduce the gap between laboratory performance and operational reliability.
A parallel innovation track is the evolution of UV-C LED systems and related component technologies. LED-based architectures offer advantages in form factor, directing options, and integration flexibility, which makes them attractive for applications where traditional lamps may be less practical. At the same time, capital expenditure payback periods for such systems have been evaluated in the range of about 2.5 to 3.5 years, supported by lamp lifetimes commonly spanning 10,000 to 20,000 hours. These parameters matter because they give facility and operations leaders a more concrete framework for comparing UV investments against alternatives, especially where labor intensity, chemical storage, or downtime are significant cost drivers.
The strategic implication is that innovation is no longer measured by brightness or output alone. It is increasingly measured by how reliably a solution delivers repeatable disinfection in the context of real workflows, maintenance constraints, and energy budgets. Suppliers that develop modular platforms, adjustable dosing logic, and application-tailored validation packages are likely to outperform those offering one-size-fits-all hardware.
PW Consulting
Regulatory Momentum and Standards Development
Policy and regulatory dynamics are playing an increasingly decisive role in shaping demand. In healthcare and medical device contexts, clearance pathways and normative references have become essential prerequisites for adoption, not optional credentials. Recent industry activity illustrates how rapidly the environment is evolving. In early 2026, Xenex Disinfection Services achieved Health Canada registration for its LightStrike6 UV-C robot, extending its North American authorization footprint for healthcare use. Later in the same year, UV Smart Technologies B.V. secured FDA 510(k) clearance for its D60 UV-C system designed specifically for transesophageal echocardiography probe disinfection, marking a first for that application. Around the same period, Surfacide, LLC introduced its Helios+ UV-C system, which received FDA 510(k) clearance as a whole-room microbial reduction device using continuous 254 nm germicidal UV light.
These developments are significant because they show regulatory review moving toward more application-specific and workflow-specific scrutiny. Rather than treating ultraviolet disinfection as a single homogeneous category, agencies and advisory bodies are examining study designs, intended use cases, and device-specific risk profiles. This trend was reinforced by broader engagement from the FDA General Hospital and Personal Use Devices Panel Advisory Committee, which convened in late 2025 to discuss study design considerations for germicidal UV devices intended to help reduce healthcare-associated infections. At the same time, regional standards activity such as the Netherlands' NEN 8281:2025 framework for validating UV-C disinfection of non-critical and semi-critical medical devices signals that structured validation expectations are becoming more explicit across parts of Europe as well.
For market participants, the implication is clear: regulatory engagement is no longer a downstream compliance task. It is a central element of product strategy. Companies that invest early in well-designed clinical or environmental evidence, that understand the difference between clearance types and their commercial consequences, and that can map their devices to applicable standards will gain meaningful purchase over competitors that rely solely on generic performance claims.
Demand-Side Shifts in Healthcare, Water, and Public Infrastructure
Demand is being reshaped not only by regulation but also by changing organizational priorities. In healthcare, the emphasis on reducing healthcare-associated infections continues to drive interest in complementary disinfection layers that can support, rather than replace, existing hygiene and cleaning protocols. UV-based interventions are increasingly evaluated against practical economic benchmarks, including the total cost of environmental control per bed or per procedure area. Publicly available comparisons have suggested that UV-C sanitization devices can present a median cost profile of roughly AUD 360 per bed per year, compared with approximately AUD 965 associated with hand hygiene protocols in some analyses. While such figures must be interpreted in context and vary by setting, they illustrate a broader point: procurement teams are looking for solutions that fit within cost-constrained infection prevention programs and offer quantifiable operational trade-offs.
In water and wastewater applications, demand is being driven by the need to modernize aging infrastructure, meet stricter effluent and drinking water quality expectations, and reduce chemical handling in treatment workflows. Municipal and industrial operators are evaluating UV systems not only for pathogen control but also for integration with existing treatment trains, energy constraints, and lifecycle maintenance plans. This creates a market environment where success depends less on the novelty of the concept and more on service reliability, dosing consistency, and the ability to support large-scale operational continuity.
Across both clinical and infrastructure settings, the common theme is a shift from awareness to evaluation. Buyers are not simply asking whether UV disinfection works in principle; they are asking which configuration works best in their environment, how it interacts with current processes, and what the real total cost of ownership looks like over multiple years.
Supply Chain, Component Economics, and Total Cost Positioning
Cost structure and supply chain resilience are becoming more visible as decision factors. The UV disinfection market spans lamps, reactor chambers, quartz sleeves, controller units, and a range of ancillary components, each with its own replacement cadence, sourcing complexity, and performance sensitivity. Fluctuations in raw material availability, electronics supply, and specialized glass or quartz components can affect product lead times and cost stability, particularly for manufacturers that depend on tightly integrated component chains.
At the same time, the market is seeing growing attention to design choices that reduce long-term operating burden. Longer service life for light sources, robust controller electronics, and serviceable chamber or sleeve designs all contribute to total cost positioning in ways that matter to buyers. The strategic relevance of this driver is that competitiveness increasingly depends on engineering for maintainability and cost transparency, not just peak disinfection output. Suppliers that can document predictable maintenance intervals, spare part availability, and energy usage patterns are better equipped to defend their pricing and build trust in sectors where downtime or compliance failures carry substantial consequences.
Competitive Positioning in a Maturing Market
The landscape of leading participants reflects the market's dual character: it contains broad-platform vendors serving large utility and industrial segments, as well as specialized players targeting high-value, regulation-sensitive applications. Firms such as Xylem Inc. and Trojan Technologies Group ULC have long been associated with UV disinfection systems for water and wastewater treatment, where scale, reliability, and integration with treatment infrastructure are paramount. Their strategic positioning tends to center on proven performance in demanding continuous-operation environments, supported by service networks and a focus on municipal and industrial procurement cycles.
Halma PLC and Atlantic Ultraviolet Corporation represent additional depth in UV equipment and product portfolios that span air and water applications, often with an emphasis on established distribution, component reliability, and broad market coverage. OSRAM GmbH and Heraeus Holding GmbH contribute important upstream and component-oriented capabilities, particularly around UV lamps and related equipment, reinforcing a supply base that is crucial for downstream system performance and availability. Koninklijke Philips N.V. has extended its presence into UV-C systems and air purification solutions, leveraging a position that intersects consumer-adjacent, clinical, and environmental health requirements.
At the same time, the market is being shaped by companies that compete through application specificity and regulatory differentiation. Xenex Disinfection Services has built its profile around UV-C whole-room microbial reduction robots, with recent North American authorization milestones reinforcing its positioning in healthcare settings. Surfacide, LLC has emphasized continuous 254 nm germicidal UV light for whole-room microbial reduction with FDA 510(k) cleared devices, distinguishing its approach through emitter configuration and clearance status. UV Smart Technologies B.V. has focused on UV-C high-level disinfection systems, including devices for transesophageal echocardiography probes, targeting specialized clinical workflows where application-specific clearance creates meaningful barriers to comparison. PuraCath Medical similarly targets a narrow but consequential need through UV disinfection systems for needleless connectors intended to reduce central line-associated bloodstream infections.
These distinctions matter because they reveal how competitive advantage is being redefined. The market is not simply moving toward consolidation through scale; it is also fragmenting into high-value niches where regulatory clearance, intended-use specificity, and workflow fit determine commercial value. Some of the strongest opportunities are emerging where a solution can demonstrate a defensible claim in a tightly defined use case, then expand from there through adjacent applications or geographic rollout.
Strategic Differentiation and Market Evolution
Looking across the leading set, several strategic postures emerge. One approach is platform breadth: supplying a wide range of UV products and services across water, air, and surface applications, with competitive advantage rooted in reliability, service coverage, and existing customer relationships. A second approach is clinical or procedural specificity: developing devices that address a particular disinfection workflow, often supported by targeted regulatory clearances and evidence packages. A third approach is component or upstream strength, where leadership in lamps, optics, or material performance underpins downstream system competitiveness.
The market is likely to see continued evolution along both consolidating and differentiating lines. Larger integrators may pursue acquisitions or internal platform expansion to cover more applications and geographies, especially where water infrastructure or broad facility management portfolios are concerned. At the same time, smaller or mid-sized innovators may capture premium positioning by solving validation, usability, or workflow-integration problems that broader competitors have not prioritized. New entrants will find the most viable openings in areas where buyers face clear pain points, where standards are becoming explicit, and where the economics of chemical reduction or labor savings can be clearly quantified.
Importantly, the concentration structure of the market does not imply that innovation is throttled by incumbency. Because the top three firms capture less than half of revenue, there is room for specialized devices, regional champions, and application-first strategies to gain momentum before the landscape fully stabilizes. This creates a strategic window for organizations that can move quickly on evidence generation, regulatory alignment, and operational proof points.
Forward Trends Shaping the Next Three to Five Years
From General Efficacy to Validated, Application-Specific Deployment
One of the most important trends expected to intensify through the forecast period is the shift from broad efficacy claims to validated, application-specific deployment. Buyers in healthcare, food and beverage, and water treatment are increasingly looking for documentation that matches their operational context. This means devices will need to show not only that they can achieve microbial reduction in principle, but also that they do so consistently under defined use conditions, with traceable testing, and within a workflow that staff can realistically sustain.
This trend will likely reward suppliers that invest in structured validation programs, that design for repeatable dosing, and that can communicate performance in operationally relevant terms. It also creates an opportunity for differentiation around service and support, since a UV system that is validated but difficult to maintain will lose its advantage over time. Companies that build validation, training, and lifecycle support into the core offering are better positioned to convert early adoption into durable deployment.
Integration of UV Systems into Broader Environmental and Water Safety Strategies
Another trend is the growing integration of UV disinfection into broader environmental health, water safety, and facility operations planning. Rather than treating ultraviolet systems as standalone interventions, organizations are increasingly considering how they fit alongside chemical treatment, filtration, ventilation, and hygiene protocols. This integration mindset favors solutions that can be monitored, controlled, and maintained within existing operational frameworks, and it encourages the use of UV technology where it can reduce chemical handling, simplify compliance, or improve resilience in continuous-use environments.
Commercial opportunities here include bundled service models, remote monitoring or performance reporting, and flexible system architectures that adapt to changing throughput or regulatory requirements. In water and wastewater contexts, in particular, the next several years are likely to see continued demand for systems that balance pathogen control with energy efficiency, maintenance predictability, and integration into large-scale treatment operations.
Cost Discipline, Lifecycle Economics, and Financing-Sensitive Procurement
A third trend is the increasing weight of lifecycle economics in procurement decisions. As organizations compare UV solutions against conventional cleaning, chemical treatment, or alternative disinfection technologies, they are focusing more closely on payback, replacement cycles, energy consumption, and labor impacts. The trend is especially relevant where capital budgets are constrained or where infection-related costs, chemical compliance, or facility downtime create strong incentives to justify investment with transparent economic logic.
This trend encourages two strategic responses. For manufacturers, it raises the importance of credible total cost of ownership narratives and long-life component design. For buyers, it creates an opportunity to move beyond price-per-unit comparisons and toward evaluations that capture operational savings, compliance risk reduction, and service continuity. The organizations that can quantify these elements effectively will have an advantage in both selling and buying decisions.
Potential Risks and Uncertainties
Several uncertainties could shape the trajectory of the market. Regulatory expectations may continue to tighten or diverge across regions, which would reward companies with strong documentation capabilities while pressuring those that rely on generalized claims. Economic volatility and capital expenditure constraints could slow adoption in some segments, particularly where buyers must prioritize competing infrastructure needs. There is also the risk that underperforming or poorly validated devices could damage trust in specific application categories, making the quality of evidence and service support even more important across the board. Finally, component supply dynamics and lamp or LED replacement cycles remain operational realities that can affect margins and customer satisfaction if not managed carefully.
These risks do not undermine the market's fundamental direction, but they do suggest that success will depend on disciplined execution: clear claims, strong validation, operational reliability, and credible cost modeling.
Actionable Implications for Decision-Makers
For Manufacturers and Technology Providers
Focus on application-specific value rather than generic disinfection messaging. The competitive edge in the next phase will likely belong to companies that can match device capabilities to well-defined workflows, support them with credible evidence, and document total cost of ownership including maintenance, replacement, and energy considerations. Regulatory engagement should be treated as a strategic capability, not a compliance afterthought, especially as clearance pathways become more application-aware and expectations around study design and validation become more structured.
In practical terms, this means prioritizing the development of validation packages that reflect how customers actually use devices, building serviceable and durable system architectures, and preparing for a landscape where procurement decisions are increasingly influenced by lifecycle economics and regional standards alignment. Companies that can demonstrate consistent performance in the exact context where they are sold will have stronger positioning than those that rely on broad but less differentiated claims.
For Investors
Pay attention to where regulatory clearance, application specificity, and documented cost advantages intersect. The market is large enough to support both scaled platforms and focused innovators, but the most durable returns are likely to come from businesses that can defend a clear intended-use niche while building evidence and service capabilities that make adoption repeatable. In water and wastewater, scale, reliability, and integration strength remain central; in healthcare and specialized surface or instrument disinfection, clearance status and workflow fit can create higher barriers to comparison and stronger pricing power.
Investors should also weigh supply chain exposure and component lifecycle economics, since lamp life, controller durability, and replacement part availability can materially affect both commercial margins and end-user satisfaction. A disciplined approach to assessing evidence quality, regulatory status, and operational economics will be more useful than broad assumptions about market growth alone.
UV Infection Control Device Market
For Procurement and Operations Leaders
Evaluate UV disinfection as part of a broader risk-reduction and operational efficiency strategy, not as a single-point purchase. Ask for evidence that reflects your actual operating conditions, clarify the total cost of ownership over the equipment's service life, and consider how the system will integrate with existing cleaning, treatment, ventilation, or infection prevention workflows. Where possible, prioritize solutions that provide transparent maintenance expectations, service support, and performance documentation that can be reviewed by clinical, environmental, or compliance stakeholders.
In water and wastewater contexts, emphasize reliability, energy and maintenance implications, and integration with existing treatment processes. In healthcare and public-facing settings, give appropriate weight to clearance status, validation methodology, and the practical realities of staff workflow. The organizations that make decisions on this basis are more likely to realize the intended benefits without encountering hidden operational friction.
For decision-makers who need to move quickly across multiple segments, regions, or application categories, the most efficient next step is to anchor strategy in a structured market view that connects macro growth trajectories with the specific segment dynamics, regulatory milestones, and competitive distinctions shaping adoption today. A detailed reference point that consolidates these dimensions can help teams compare opportunities, prioritize validation and procurement pathways, and identify where further due diligence is required. Readers seeking a fuller breakdown of segment-level dynamics, regional variation, and targeted commercial scenarios can explore the complete PW Consulting market analysis for additional depth and customized guidance.
For detailed analysis of this topic, please visit the official page: UV Light Disinfection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com