

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Medical Protective Masks Market CAGR Story: The 6.95% Growth Drivers

Medical Protective Masks Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for medical protective masks has entered a new phase of structural maturation, transitioning from crisis-driven demand to a more predictable, compliance-shaped growth trajectory. With a 2025 revenue baseline of 215.0 million USD and a projected compound annual growth rate of 6.95 percent through 2032, the sector is expanding toward a 344.8 million USD valuation by the end of the forecast window. The historical arc from 2020 through 2025 reveals a market that absorbed unprecedented shocks, stabilized around renewed procurement rhythms, and is now being reshaped by regulatory recalibration, regional capacity realignment, and shifting end-user expectations. For executives, investors, and procurement leaders, the central question has moved beyond whether demand will persist to how value will be captured in a market where certification status, domestic sourcing preferences, and performance standardization increasingly dictate commercial outcomes.
N95 Grade Medical Protective Masks Market
Market Landscape and Core Challenges
The revenue progression from 2020 to 2025 establishes a baseline of steady expansion, with annual figures moving from 163.15 million USD to 215.0 million USD. The forecast path to 2032 indicates continued upward movement, though the growth profile is not linear. Acceleration in the near term is supported by renewed institutional purchasing and updated performance expectations, while longer-term expansion depends on how quickly manufacturers can align production with evolving compliance frameworks and how procurement systems integrate new domestic sourcing incentives. The market remains moderately fragmented. The combined share of the three largest participants sits at 24.6 percent, while the top five account for 26.2 percent. This concentration pattern signals that scale alone does not confer decisive dominance. Instead, competitive advantage is increasingly tied to certification portfolios, regulatory responsiveness, and the ability to maintain consistent supply to healthcare and institutional buyers who prioritize reliable compliance over pure price competition.
Several structural challenges are redefining how participants operate. The first is regulatory volatility around approval frameworks. Recent actions by NIOSH, including the voluntary rescission of multiple approvals for major respirator manufacturers, have introduced uncertainty into product line continuity and inventory planning. For manufacturers, this creates a need to treat certification status as a dynamic asset rather than a static credential. For procurement teams, it complicates long-term sourcing commitments and raises the importance of supplier diversification. The second challenge lies in the tension between global cost optimization and emerging domestic procurement preferences. Policy signals, including CMS proposals to maintain equitable adjustment authority for domestic N95 respirator costs and a January 2026 advance notice of proposed rulemaking seeking input on incentivizing domestic procurement of personal protective equipment, indicate a directional shift toward supply chain localization. Companies that rely heavily on centralized overseas production without regional backup capacity may face margin pressure or eligibility constraints in certain procurement channels. The third challenge is standardization reform. The introduction of EN 14683:2025, which specifies updated construction, design, performance requirements, and test methods for medical face masks, raises the bar for product consistency and documentation. While stronger standards improve end-user confidence and interoperability across procurement systems, they also increase compliance costs and can slow product launches for manufacturers that have not invested in testing infrastructure and quality system upgrades.
Key Drivers Shaping Market Trajectory
The market's direction is being shaped by four interlocking forces: technology and design innovation, regulatory and policy evolution, demand-side behavior changes, and supply chain cost structure realignment. Each driver carries distinct implications for commercial strategy.
Technology and Performance Innovation
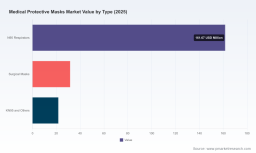
Product differentiation is increasingly anchored in filtration consistency, fit optimization, and material durability rather than basic barrier functionality. N95 respirators remain the largest product category, reflecting sustained preference for higher filtration performance in clinical and high-exposure environments. At the same time, manufacturers are expanding surgical N95 variants and ASTM-aligned surgical masks to address settings where both fluid resistance and respiratory protection are required. Recent commercial activity illustrates how companies are using product breadth and certification coverage to strengthen positioning. Makrite's participation in Tool Japan 2025 highlighted a strategy of showcasing N95, surgical, and KN95/FFP2 variants together, reinforcing a portfolio approach that aligns with procurement teams seeking single-source compatibility across multiple use cases. Harley Commodity's emphasis on surgical N95 models with adjustable head straps reflects attention to fit and wearer compliance, factors that increasingly influence repeat purchasing decisions in healthcare environments. For businesses, the strategic implication is clear: performance claims must be backed by active approvals and demonstrable test alignment, and product roadmaps should anticipate overlaps between respirator and surgical mask requirements as institutions consolidate purchasing categories.
Regulatory and Policy Environment
Policy frameworks are moving from emergency-era flexibility toward more structured oversight and procurement incentives. FDA draft guidance for FY2025 on enforcement discretion policy for premarket and other requirements for NIOSH-approved air purifying respirators signals an effort to clarify how compliance expectations will be applied in routine market conditions. NIOSH's conformity assessment activity, including the September 2025 voluntary rescission of approvals for multiple major manufacturers, underscores that approval status can change quickly and that manufacturers must maintain rigorous quality system discipline. On the procurement side, CMS proposals related to equitable adjustment authority for domestic N95 respirator costs and the January 2026 advance notice of proposed rulemaking on domestic PPE procurement incentives point toward financial and policy mechanisms that may favor domestic production in certain purchasing pathways. These developments do not erase global supply chains, but they introduce a new layer of strategic planning. Companies that can demonstrate stable approval status, transparent compliance documentation, and flexible sourcing options will be better positioned to navigate both regulatory scrutiny and procurement preference shifts.
PW Consulting
Demand-Side Behavior and Institutional Purchasing
End-user behavior has shifted from reactive stockpiling to more disciplined, specification-driven purchasing. Healthcare remains the dominant application arena, reflecting continued emphasis on staff protection, infection control protocols, and standardized procurement in clinical settings. Industrial and other application segments contribute meaningful demand, but the commercial center of gravity remains in environments where compliance documentation, batch traceability, and performance consistency are non-negotiable. Procurement teams are increasingly evaluating suppliers on the stability of their approval portfolios and the resilience of their supply commitments rather than on short-term price advantages alone. This shift favors manufacturers that can provide clear certification status, predictable lead times, and product lines that match multiple procurement specifications. It also creates an opening for intermediaries and verification-focused organizations that help buyers navigate approval status, sourcing authenticity, and specification matching. Project N95's role in vetting, sourcing, and distributing respirators from approved manufacturers reflects a broader market need for trusted validation pathways, especially when procurement decisions must balance speed, compliance, and supply assurance.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by the interaction of raw material availability, manufacturing geography, and compliance-related operating costs. Domestic capacity expansion is one visible response to supply assurance concerns and procurement preference signals. 3M's opening of a new N95 respirator manufacturing facility in North Carolina in March 2025 illustrates a strategic move to increase domestic production capacity for medical protective masks, reducing dependence on distant supply nodes and improving responsiveness to regional demand fluctuations. At the same time, manufacturers with strong positions in Asian production networks are pursuing market-facing visibility and certification breadth to maintain competitiveness. The broader cost picture is not simply about labor arbitrage; it is increasingly about the total cost of maintaining approval status, meeting updated standards, and satisfying procurement rules that may favor localized supply. Businesses that treat supply chain design as a compliance and responsiveness issue, rather than purely a cost-minimization exercise, are more likely to sustain margin stability through regulatory and demand shocks.
Competitive Landscape and Leading Strategies
The competitive field combines established multinational manufacturers, specialized respirator producers, and sourcing and verification platforms that help institutional buyers navigate approval and authenticity concerns. Leading participants are pursuing distinct strategic positions that reflect their manufacturing base, certification coverage, and go-to-market focus.
Several U.S.-based manufacturers hold active NIOSH approvals and emphasize respirator product lines with surgical variants. 3M Company produces N95 respirators including surgical variants and the 9205+ Aura series, and has reinforced its domestic production posture through new facility investment. Honeywell International Inc. manufactures N95 respirators and surgical N95 variants while maintaining active NIOSH approvals, positioning around recognizable brand trust and institutional procurement familiarity. Kimberly-Clark Corporation produces N95 respirators and surgical masks with active NIOSH approvals, leveraging broader health and hygiene commercial infrastructure to support distribution and buyer relationships. DemeTech Corporation manufactures N95 respirators and surgical masks with ASTM Level 3 compliance and holds active NIOSH approvals, emphasizing specification alignment for higher-barrier surgical use cases. These players share a common strategic thread: maintaining active approvals, expanding or protecting domestic capacity where advantageous, and aligning product lines with procurement categories that value both respiratory protection and fluid-resistance performance.
International manufacturers are competing through certification breadth, model variety, and regional market presence. Makrite produces surgical N95 respirators, ASTM Level 1-3 surgical masks, and KN95/FFP2 variants, with active NIOSH, CE, and other certifications. Its exhibition activity at Tool Japan 2025 reflects a market-facing strategy that emphasizes cross-variant availability and direct engagement with procurement and distribution channels. Harley Commodity produces surgical N95 respirators with adjustable head straps and holds active NIOSH approvals and FDA clearance, focusing on fit-oriented design and compliance documentation that supports institutional purchasing requirements. These companies illustrate how non-domestic producers can remain relevant by combining certification coverage with product features that address wearability, specification range, and channel visibility.
A separate but important part of the landscape is occupied by verification and distribution intermediaries such as Project N95, which vets, sources, and distributes N95 respirators and KN95 masks from approved manufacturers. This model addresses a persistent market need: buyers want to reduce the risk of sourcing non-conforming products and need practical pathways to approved supply. The presence of such organizations indicates that trust and verification are becoming more valuable as compliance scrutiny intensifies and procurement teams seek to reduce administrative and product-risk burdens.
The market structure is evolving along three directions. First, consolidation pressure exists where scale, approval maintenance, and distribution reach create advantages, particularly in healthcare procurement where supplier reliability is heavily weighted. Second, differentiation is increasing among manufacturers that can combine approval stability with product features such as fit adjustment, surgical compatibility, or multi-standard coverage. Third, new-entry and intermediary activity is likely to persist where verification, sourcing transparency, and regulatory navigation offer commercial value. The overall effect is a market that rewards compliance discipline and supply reliability as much as production volume.
Future Trends and Commercial Opportunities
Looking toward the next three to five years, several trends are likely to shape commercial outcomes. The first is a more formal separation between emergency-surge purchasing and routine procurement. As policy frameworks settle into structured oversight and domestic sourcing incentives, buyers will likely standardize around suppliers that can demonstrate steady approval status, consistent documentation, and resilient supply. This creates opportunity for manufacturers that invest early in quality system robustness, approval maintenance, and transparent communication about certification status. It also raises the importance of portfolio planning so that product offerings match the specifications most likely to be required in routine healthcare and institutional purchasing.
The second trend is the widening role of standards and verification as commercial differentiators. Updated mask performance standards and ongoing conformity assessment activity increase the value of demonstrable compliance. Companies that can align product design, testing, and documentation with current requirements will face fewer market-access frictions and will be better positioned to serve buyers who must justify purchasing decisions through compliance evidence. Verification-focused intermediaries and platform models may also gain stature as buyers look for reduced-risk sourcing pathways, especially when approval status or product origin must be confirmed quickly.
The third trend is geographic and supply chain reconfiguration. Domestic capacity investments and procurement incentive signals suggest that regional supply resilience will become a more important part of commercial positioning. This does not mean global production will disappear, but it does mean that dual-sourcing strategies, regional backup capacity, and procurement-channel alignment will matter more than in the pre-2020 era. Businesses that can offer supply flexibility while maintaining approval integrity will be better placed to capture demand from buyers who are balancing cost, compliance, and continuity.
These trends carry commercial opportunities for different players. Manufacturers can pursue portfolio breadth that covers respirator and surgical needs, invest in approval maintenance and testing alignment, and develop supply-chain flexibility that supports both domestic and export channels. Investors can focus on companies with stable certification positions, credible compliance infrastructure, and credible pathways to benefit from domestic procurement preference shifts. Procurement organizations can reduce risk by prioritizing suppliers with transparent approval status, diversified sourcing options, and documentation that supports audit and compliance requirements. At the same time, uncertainty remains. Approval rescissions, evolving enforcement discretion guidance, and changes in reimbursement or procurement incentive rules can alter competitive positioning quickly. Businesses should therefore treat compliance status and sourcing flexibility as living strategic assets rather than fixed advantages.
Medical Face Masks Market
Strategic Actions for Decision-Makers
For manufacturers, the priority is to treat certification and compliance as core commercial infrastructure. Maintaining active approvals, aligning products with current standards, and communicating approval status clearly can reduce market-access risk and improve buyer confidence. Portfolio planning should anticipate overlap between respirator and surgical mask requirements, since many institutional buyers prefer suppliers that can serve multiple specifications without fragmenting the supply base. Supply chain design should incorporate regional flexibility where possible, both to respond to procurement preference signals and to improve continuity during disruption. Companies that combine technical credibility with supply resilience are more likely to secure recurring institutional demand.
For investors, due diligence should place significant weight on approval stability, quality system maturity, and exposure to regulatory or procurement shifts. Revenue growth potential is important, but in a market where approval status can change and compliance costs can rise, the durability of a company's certification portfolio and its ability to maintain supply under scrutiny may be equally decisive. Preference should be given to businesses that demonstrate clear compliance documentation, diversified product coverage, and realistic pathways to benefit from domestic sourcing incentives without overconcentrating risk in a single channel or geography.
For procurement leaders and institutional buyers, the strategic imperative is to move from transactional sourcing to supply assurance planning. That means evaluating suppliers on approval continuity, documentation transparency, and the ability to provide consistent product across respirator and surgical categories where needed. Diversification of approved sources, attention to standard updates such as EN 14683:2025, and alignment with procurement incentives that may favor domestic supply can reduce both compliance and continuity risk. Verification support from trusted intermediaries can also help reduce the administrative burden of confirming approval status and product authenticity.
Detailed segmentation data, company-level benchmarking, and scenario-based procurement guidance can materially improve the speed and quality of these decisions. The broader market trajectory is clear enough to justify strategic action, but the value of any specific move depends on precise figures, approval-status mapping, and procurement-context nuance that vary by region, application, and buyer type. Readers seeking deeper segmentation detail, competitive benchmarking, and customized sourcing or investment implications can access the full PW Consulting market research report for comprehensive data and tailored analysis supporting the strategic directions outlined here.
For detailed analysis of this topic, please visit the official page: Medical Protective Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com