

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Manned Security Services Market: The 7.12% CAGR Signals a Strategic Shift

The Manned Security Services Market: Strategic Trends and Commercial Opportunities in an Evolving Landscape
The manned security services market has reached a critical inflection point. In 2025, the sector crossed the $242.5 million threshold in annual revenue, building on a steady recovery from the $185.3 million baseline observed at the start of the decade. Over the past five years, the trajectory has reflected not just post-pandemic normalization, but a fundamental recalibration of how organizations think about physical protection. The market is projected to expand at a compound annual growth rate of 7.12 percent through 2032, reaching an estimated $393.1 million by the end of the forecast period. This growth is not merely an extension of historical patterns; it is being shaped by structural shifts in technology, regulation, labor dynamics, and buyer expectations. For executives, investors, and procurement leaders, understanding where value is being created—and where it is being eroded—requires looking beyond top-line numbers and examining the forces that will determine competitive advantage in the years ahead.
Market Snapshot and Core Challenges
A Sector in Transition
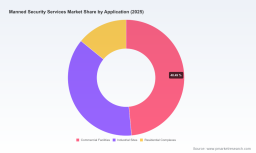
The market has grown consistently from 2020 through 2025, but the composition of that growth tells a more nuanced story. Commercial facilities continue to anchor demand, while industrial sites and residential complexes represent secondary but strategically important demand pools. The service mix remains dominated by traditional guarding, though cash and valuables protection and specialized security services contribute distinct, higher-margin segments that reflect evolving risk profiles. This diversification is a response to the reality that one-size-fits-all security models no longer satisfy the operational complexity of modern facilities, logistics networks, and public-facing institutions.
Challenge One: Labor Scarcity and Wage Pressure
The most persistent constraint on the industry is human capital. Manned security remains, by definition, labor-intensive. Organizations that rely on guard presence at perimeter points, access control stations, and roaming patrols are competing for a workforce that is simultaneously in high demand across adjacent sectors such as logistics, facilities management, and hospitality. Wage escalation is no longer a temporary fluctuation; it is a structural cost input that compresses margins for providers that compete primarily on price. In markets where basic guarding is commoditized, the pressure is especially acute, with thousands of active security companies vying for the same talent pool. The result is a two-tier dynamic: providers that can attract, retain, and professionalize their personnel through career pathways, training, and competitive compensation are gaining share, while those locked into low-cost models face turnover, service inconsistency, and reputational risk.
Worldwide Site Safety Service Market
Challenge Two: Regulatory Friction and Compliance Complexity
Regulation is reshaping how manned security operates across jurisdictions. In some regions, foreign ownership restrictions are mandating local control and altering the competitive playing field for international operators. In others, procurement frameworks are introducing new clauses that affect how private security functions are structured and contracted, particularly in cross-border or government-adjacent environments. These dynamics do not simply add administrative overhead; they influence market entry strategy, partnership models, and the cost of scaling. Companies that treat compliance as a one-time onboarding exercise are exposed, whereas those that embed regulatory intelligence into their operating design can convert constraints into barriers that protect incumbent positions.
Challenge Three: The Technology Expectation Gap
Buyers increasingly expect that manned security will be augmented by technology—remote monitoring, video analytics, access control integration, and data-driven reporting. Yet the integration of these capabilities with human presence remains uneven. Some incumbents have built seamless hybrid offerings; others are stitching together point solutions that create operational friction. The expectation gap is widening the wedge between providers that can deliver coordinated, intelligence-led protection and those that offer body-only presence without situational awareness. For decision-makers, this creates a procurement challenge: how to ensure that the human element and the technological layer reinforce each other rather than operate in parallel silos.
Key Drivers Shaping the Market
Technology as a Force Multiplier, Not a Replacement
The most consequential driver of market evolution is the maturation of technology that amplifies the effectiveness of security personnel rather than displacing them. Remote guarding stations, analytics-enabled video feeds, and integrated alarm response platforms allow a smaller on-site footprint to achieve coverage that previously required a larger physical guard complement. This is particularly relevant for organizations managing multiple sites, variable-risk environments, or extended operating hours. The strategic implication is not simply cost reduction; it is the ability to redeploy personnel to higher-value tasks such as incident response, customer engagement, and specialized patrols. Where technology is deployed thoughtfully, it raises the baseline quality of service and creates differentiation in a market that has historically competed on headcount and price.
Policy and Regulatory Signals Redirecting Investment
Recent policy developments are acting as catalysts for reallocation. The closure of a significant government business unit by one of the largest global providers illustrates how portfolio choices are being shaped by shifting contract landscapes and regulatory considerations. Simultaneously, procurement frameworks that govern private security functions abroad are introducing clarity—and complexity—into how services are structured for international operations. These signals matter because they influence not only who wins contracts, but how services are designed, staffed, and audited. Providers that proactively align their operating models with emerging compliance expectations are better positioned to secure long-term public and quasi-public contracts, while those that lag face re-bid risks and margin compression.
Demand-Side Shifts: Risk Profiles Are Becoming More Granular
On the demand side, organizations are moving away from generic security packages toward solutions that reflect the specific risk profile of their facilities, supply chains, and reputational exposures. Commercial facilities are prioritizing customer experience and loss prevention within a single security function. Industrial sites are emphasizing perimeter integrity, access control, and rapid incident escalation. Residential complexes are balancing resident safety with privacy and community integration. This granularity is driving demand for specialized services and for guard personnel who are trained not only in presence and deterrence, but in de-escalation, observation, and communication. The buyers who are winning contracts are those that articulate a clear security mission and tie it to measurable outcomes, rather than treating security as a generic cost center.
Cost Structure Evolution and the Pursuit of Predictability
Cost structures are shifting as labor, insurance, technology, and compliance costs converge. Providers are responding by standardizing service tiers, incorporating technology-assisted monitoring to moderate labor intensity, and building clearer pricing models that improve predictability for clients. This evolution benefits both sides: organizations gain budgeting clarity and service consistency, while providers gain operational discipline and reduced churn. The market is increasingly rewarding business models that balance human presence with scalable infrastructure, because that balance delivers the reliability that risk-conscious buyers require.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market features several large, globally active providers whose strategies reveal how scale, footprint, and integration are being leveraged. Allied Universal operates across North America with a broad service portfolio spanning manned guarding, mobile patrols, risk consulting, and technology-enabled solutions, anchored by strong government and commercial contracts. Its positioning reflects the value of a large, diversified contract base and the ability to offer integrated services that span physical presence and advisory support. Securitas, headquartered in Sweden, operates in dozens of markets with a focus on on-site guarding, mobile guarding, remote guarding, and integrated solutions, emphasizing manned personnel services supported by technology. Its strategy underscores the importance of geographic breadth and the hybrid model of human presence combined with remote capabilities. Prosegur, based in Spain, specializes in manned guarding combined with alarms, logistics, and integrated security solutions across a wide country footprint, illustrating how logistics-adjacent security can create cross-selling opportunities and operational synergies. GardaWorld, headquartered in Canada, delivers manned security, cash logistics, and risk management with a strong presence in government and high-risk environments, highlighting the premium that specialized, high-assurance services can command. Paladin Security and InterCon Security, both with North American foundations, emphasize government and commercial guarding contracts, demonstrating that regional depth and relationship-driven account management remain viable paths to growth even as global players expand.
Recent Developments as Strategic Signals
Recent contract activity and recognition highlight how incumbents are reinforcing their positions. A major provider secured a new contract for guard services at county mental health facilities and clinics, a type of engagement that blends public-sector procurement with the need for trained, sensitive, and consistent personnel. Another provider ratified a renewed contract with a university that expanded protections and included wage increases, reflecting both the prioritization of campus safety and the willingness to invest in personnel to sustain service quality. Separately, a North American security provider received multiple industry awards, signaling that excellence in execution, client service, and operational discipline continues to be recognized and rewarded. These examples are consistent with a broader pattern: winning engagements often requires a combination of reputation, reliable staffing, and the ability to adapt services to the specific environment.
Market Structure: Consolidation Pressures and Differentiated Niches
The market is characterized by a moderate concentration at the top, with the largest players holding meaningful but not dominant shares, and a long tail of regional and specialty providers. This structure creates two simultaneous dynamics. First, there is pressure for consolidation among mid-tier and regional firms seeking to achieve scale in staffing, technology deployment, and contract procurement, particularly as compliance and labor costs rise. Second, there is room for differentiation in niches such as high-risk environments, cash and valuables logistics, specialized facility protection, and integrated remote-plus-on-site models. New entrants that can combine technology fluency with disciplined personnel management are finding traction, but they face the same labor and compliance realities as incumbents. The net effect is a market that is neither fully consolidated nor highly fragmented, but one in which strategic positioning—clear service boundaries, credible integration, and reliable execution—is becoming the primary determinant of sustainable share gains.
Future Trends and Commercial Opportunities
Trend One: Hybrid Security Models Will Become the Standard
Over the next three to five years, the distinction between manned and technology-assisted security will increasingly blur into hybrid models that are treated as the baseline offering. Remote monitoring, analytics, and integrated alarm response will be combined with on-site personnel deployed in a more targeted fashion. The commercial opportunity lies in designing service packages that explicitly map technology functions to human responsibilities, so that clients receive a coordinated outcome rather than a stack of separate capabilities. Providers that can demonstrate measurable improvements in response times, coverage efficiency, and reporting clarity will be better positioned to win multi-site and long-term contracts. The risk is that poorly integrated hybrids create confusion about accountability and degrade client trust; therefore, execution discipline and clear service definitions will be critical.
Trend Two: Professionalization of the Security Workforce Will Differentiate Providers
Professionalization—through structured training, clear career pathways, measurable performance standards, and competitive compensation—will move from a nice-to-have to a core competitive requirement. Organizations will increasingly evaluate providers not only on availability and price, but on the quality, consistency, and retention of the personnel assigned to their sites. The opportunity is to build workforce models that reduce turnover, improve service reliability, and create reputational advantage. In commoditized segments, however, wage and staffing pressure will remain a headwind, and providers that lack a clear workforce value proposition will find it harder to defend margins or win complex contracts. The uncertainty lies in the pace of wage escalation across different regions and the extent to which technology can offset labor intensity without compromising service quality.
Trend Three: Regulatory Clarity Will Reshape Market Access and Portfolio Choices
As regulatory frameworks around ownership, procurement, and cross-border private security functions become more defined, market access will be recalibrated. Providers with strong local knowledge, compliant ownership structures, and established relationships will have advantages in certain regions, while others may need to partner, restructure, or refocus their portfolios. The commercial opportunity is to use regulatory intelligence to shape where to compete, how to structure contracts, and which assets to retain or divest. Recent portfolio adjustments by large providers are a reminder that strategic withdrawal from specific segments can free resources for higher-conviction areas. The risk is that regulatory change introduces sudden compliance costs or contract re-bidding, particularly for operators with exposure to government-adjacent or internationally regulated engagements.
Strategic Recommendations for Decision-Makers
For Providers and Operators
Design service models around outcomes, not headcount. Clients increasingly buy protection that is visible, measurable, and integrated, rather than simply the presence of personnel. Providers that can articulate how manned presence, remote support, and reporting work together will command stronger positioning. Invest in workforce stability as a strategic asset: structured training, predictable scheduling, and competitive compensation are not merely cost items; they are the foundation of service quality and client retention. Where commoditization is intense, differentiate through specialization, reliability, or integration rather than price alone, because price competition in a high-turnover environment erodes both margins and reputation.
Managed Security Services System Market
For Investors and Sponsors
Evaluate potential investments with a clear view of labor economics and regulatory exposure. Business models that rely heavily on low-cost staffing without a credible plan for retention and professionalization are exposed to margin volatility and service risk. Preference should be given to operators with demonstrated ability to integrate technology into manned operations in a way that improves coverage and reporting, as well as those with diversified contract bases that reduce dependence on any single public-sector or cyclical customer. Pay close attention to geography and ownership rules, because compliance architecture can either enable scale or constrain it. In markets where concentration is moderate and fragmentation persists, there may be opportunities to build value through disciplined consolidation, shared services, and technology standardization, provided that integration risk is managed carefully.
For Procurement and Risk Leaders
Buy security as a coordinated capability, not as a commodity line item. Define the security mission for each site or portfolio in terms of outcomes—deterrence, response, access control, customer experience, and reporting—then evaluate providers against how they assign responsibilities across personnel and technology. Require evidence of workforce stability, training standards, and escalation protocols, because these factors determine whether service quality holds under stress. Favor contracts that include clear performance metrics, regular reporting, and defined accountability for both on-site and remote components. When regulated environments or cross-border operations are involved, confirm ownership, compliance, and contracting structures early, because late-stage surprises can disrupt delivery and increase cost.
The manned security services market is expanding, but growth alone does not guarantee profitability or competitive advantage. The sector is being reshaped by labor dynamics, regulatory evolution, technology integration, and a more demanding demand base. Organizations that treat these forces as signals to redesign service models, workforce strategies, and portfolio choices will be better positioned to capture value. For those seeking deeper granularity—segment-level sizing, regional dynamics, competitive benchmarking, and tailored scenario analysis—a comprehensive research resource is available to support more precise planning and decision-making.
PW Consulting
For detailed analysis of this topic, please visit the official page: Manned Security Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com