

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Multiwall Paper Bags Market 2026: Why the 4.5% CAGR and $244.7M Outlook Changes Everything

Strategic Trends and Commercial Opportunities in the Multiwall Paper Bags Market
Navigating Transition: Market Overview and Key Challenges
The multiwall paper bags market has established itself as a critical component of industrial packaging, serving sectors ranging from construction to agriculture. Over the past five years, the market has demonstrated steady expansion, with revenue climbing from approximately 135.4 million U.S. dollars in 2020 to an estimated 179.5 million in 2025. This trajectory reflects a compound annual growth rate of 4.5 percent, positioning the sector for continued moderate expansion through 2032, when revenues are projected to approach 244.7 million U.S. dollars. While the growth profile is stable rather than explosive, the underlying dynamics are shifting in ways that create meaningful strategic implications for manufacturers, investors, and procurement leaders.
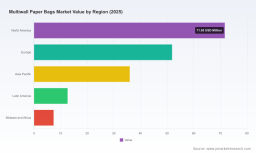
The market structure remains relatively fragmented at the top, with the top three players collectively holding about 22.4 percent of revenue and the top five accounting for 28.7 percent. This concentration level indicates a landscape where scale advantages exist but do not fully dictate outcomes, leaving room for regional specialists and product-focused innovators to compete effectively. The distribution of revenue across regions shows North America as the largest contributor, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but growing shares. Across product types, kraft paper continues to anchor the market, while coated and recycled variants occupy meaningful niches. On the application side, building materials represent the largest end-use segment, with agriculture, chemicals, food, and minerals following in varying degrees of demand intensity.
Despite the constructive growth baseline, the industry is confronting several transition points that will shape competitive outcomes over the next five years. First, volatile raw material costs are compressing margins and forcing manufacturers to rethink procurement strategies and pricing models. Second, regulatory frameworks are accelerating the shift away from plastic-heavy multilayer sacks toward fully recyclable paper-based solutions, raising compliance costs but also opening differentiation opportunities. Third, demand patterns are evolving as end-users prioritize sustainability credentials, moisture resistance, and supply chain reliability, pushing suppliers to balance performance with environmental claims. These challenges are not merely headwinds; they are re-shaping the criteria by which companies win or lose in the market.
Key Drivers Reshaping the Landscape
Regulatory and compliance pressures are among the most consequential forces currently influencing the market. The EU Packaging and Packaging Waste Regulation, which begins applying from August 2026, requires improved recyclability documentation and labeling compliance for packaging, including multiwall paper bags. By 2030, all packaging must be recyclable, a mandate that favors sack kraft paper over multilayer sacks with high plastic content in multiwall applications. In parallel, plastic bag bans in various regions are compelling manufacturers to pivot toward sustainable, recyclable, and biodegradable materials as compliant alternatives. These regulatory shifts are raising the bar for product design and documentation, but they also reward suppliers that can demonstrate credible recyclability and reduced plastic use.
Raw material dynamics are equally central to the market's evolution. Benchmark kraft linerboard prices surged by 22 percent year-on-year in 2023 due to constrained supply and high energy costs, and volatility has persisted into subsequent periods. Fluctuating prices for paper and adhesives continue to challenge manufacturers, as rising input costs directly impact production economics and profit margins. This environment favors companies with vertically integrated production, diversified sourcing, and the ability to pass through cost adjustments without eroding customer relationships. It also incentivizes material efficiency innovations that reduce weight or improve strength-per-unit, helping to offset cost pressure while meeting performance requirements.
Kraft Paper Bag Market
Demand-side behavior is shifting in ways that reward performance and sustainability simultaneously. End-users in building materials, agriculture, chemicals, and food sectors are increasingly scrutinizing packaging for moisture resistance, durability, and environmental impact. For humidity-sensitive products, the ability to maintain integrity without relying on plastic layers has become a competitive differentiator. At the same time, procurement teams are seeking suppliers that can provide consistent quality, flexible sizing, and transparent sustainability credentials. These expectations are pushing manufacturers to invest in product development that addresses both functional and regulatory demands, rather than treating sustainability as a separate initiative.
Technology and process innovation are beginning to play a more visible role in competitive positioning. While multiwall paper bags may appear to be a mature product category, advances in production optimization, material formulation, and design intelligence are enabling suppliers to improve strength, reduce weight, and enhance moisture barriers. Recent product-level activity illustrates this direction: in May 2025, Mondi Group launched its re/cycle PaperPlus Bag Advanced, a high-performance paper bag designed for humidity-sensitive products with up to 60 percent reduced plastic use and a strong moisture barrier. This launch underscores how sustainability and performance are converging, setting a benchmark that other players will need to match or differentiate around.
Competitive Positioning and the Evolution of Market Structure
The competitive landscape features a mix of global packaging leaders and specialized manufacturers, each pursuing distinct positioning strategies. Mondi Group, headquartered in Vienna, focuses on AI-powered multiwall bag production, sustainable paper-based packaging, and moisture-resistant bag solutions for industrial applications including cement and chemicals. Its emphasis on humidity-sensitive performance and reduced plastic use aligns closely with regulatory and demand trends. Smurfit Kappa, based in Atlanta, specializes in AI-enhanced bag design, lightweight yet durable multiwall sacks, and eco-friendly industrial packaging, positioning itself around design intelligence and sustainability. Segezha Group, headquartered in Moscow, provides AI-assisted high-strength multiwall bags, biodegradable packaging solutions, and customizable industrial paper sacks for food and agricultural sectors, leveraging customization and biodegradability as differentiators.
WestRock Company, also headquartered in Atlanta, focuses on AI-driven material optimization, high-barrier multiwall bags, and recyclable paper bag technologies for building materials, chemicals, and agriculture sectors, emphasizing barrier performance and recyclability. Sonoco Products Company and International Paper contribute from the U.S. with broad industrial and consumer packaging portfolios, with International Paper supplying kraft paper bags and corrugated packaging for industrial and consumer applications. More regionally focused players add further diversity: Bag Supply Company manufactures millions of high-quality multiwall paper bags annually for agricultural, industrial, construction, and consumer goods; Southern Packaging LP supplies customizable multi-wall paper packaging solutions through vertically integrated production facilities for industrial bulk packaging; JohnPac produces cost-effective multiwall paper bags for seed and grain storage and transport with custom shapes and sizes; and Novolex offers its Dubl Life line of FSC-certified or 100 percent recycled kraft paper bags for industrial and consumer use.
PW Consulting
The strategic logic across these players reveals several differentiation paths. One is performance-led, targeting moisture resistance, strength, and barrier properties for demanding applications. Another is sustainability-led, emphasizing reduced plastic use, recyclability, biodegradability, and certified fiber sources. A third is cost and customization-led, serving specific end-use verticals with tailored sizes and economical production. Vertical integration and sourcing flexibility are recurring advantages in a volatile raw material environment, while investments in design and production intelligence are increasingly used to improve efficiency and product consistency.
Industry events and community engagement are also shaping the competitive rhythm. The PSSMA 2026 Production Managers' Seminar and Bag Boot Camp in Greenville, South Carolina, along with the PSSMA 2026 Annual Meeting in Napa, California, reflect ongoing지식交流 and capability-building within the sector. These gatherings provide forums for sharing operational best practices and aligning on emerging standards, which can accelerate adoption of improved processes and compliance practices across the supply base.
Looking at market structure evolution, the current fragmentation at the top suggests room for selective consolidation among regional players seeking scale, while also leaving space for differentiated specialists to thrive. New entrants are unlikely to disrupt the market through volume alone; instead, they will need to bring clear advantages in sustainability credentials, moisture performance, customization, or cost efficiency. The interplay between regulatory deadlines, raw material volatility, and end-user expectations will likely reward companies that can combine operational resilience with credible product innovation.
Forward Outlook: Trends Shaping the Next Three to Five Years
The first major trend is the acceleration of recyclable and reduced-plastic multiwall paper bag designs as regulatory and customer expectations converge. With the EU requiring all packaging to be recyclable by 2030 and plastic bag bans expanding in various regions, suppliers that can deliver high-performance paper-based sacks with minimal or no plastic content will gain a structural advantage. This trend creates opportunities for product differentiation tied to documented recyclability, reduced plastic use, and moisture barrier performance that does not rely on multilayer plastic construction. The commercial implication is clear: sustainability is becoming a performance attribute, not just a compliance checkbox.
The second trend is continued raw material cost volatility paired with a growing emphasis on material efficiency and supply chain resilience. As kraft linerboard and adhesive prices remain sensitive to supply constraints and energy costs, manufacturers will increasingly value sourcing flexibility, vertical integration, and design choices that improve strength-to-weight ratios. Companies that can maintain quality while optimizing material usage will be better positioned to protect margins and offer competitive pricing. Procurement leaders should expect more variability in lead times and input costs, making supplier reliability and transparency increasingly valuable.
The third trend is the gradual integration of production and design intelligence into multiwall bag manufacturing. While not a wholesale transformation of the category, AI-assisted design and material optimization are enabling suppliers to improve consistency, reduce waste, and tailor bags to specific end-use requirements. This trend supports both cost efficiency and product performance, and it may become a baseline expectation for leading suppliers over the forecast period. The opportunity lies in pairing these capabilities with clear customer benefits, such as customized sizing, enhanced moisture resistance, or faster response to specification changes.
Tea Bag Paper Market
Potential risks and uncertainties should not be overlooked. Regulatory timelines may shift or be implemented with varying rigor across jurisdictions, creating compliance complexity for suppliers operating in multiple markets. Raw material price swings could intensify if energy costs or supply disruptions escalate, pressuring margins even for well-prepared manufacturers. End-user demand could also evolve in unexpected ways if alternative packaging materials gain traction in specific applications, or if economic conditions slow procurement in construction and agriculture. Navigating these uncertainties will require scenario planning, flexible sourcing, and product portfolios that can adapt to changing requirements without sacrificing core performance.
Implications and Actionable Considerations for Decision Makers
For manufacturers, the priority is to align product development with the converging demands of recyclability, moisture performance, and cost efficiency. Investing in reduced-plastic or fully recyclable multiwall designs, improving material utilization, and strengthening sourcing flexibility can help protect margins while meeting regulatory and customer expectations. Building documentation and labeling capabilities that support compliance in key markets, particularly where recyclability requirements are tightening, will also reduce execution risk. Where possible, enhancing production and design intelligence can improve consistency and responsiveness, giving suppliers an edge in customized or performance-sensitive segments.
For investors, the market offers moderate growth with meaningful differentiation potential rather than uniform upside. Attention should focus on players with credible sustainability credentials, resilient cost structures, and clear positioning in performance-sensitive applications such as building materials, chemicals, and humidity-sensitive food or agricultural products. Vertical integration, diversified sourcing, and evidence of product innovation that reduces plastic content or improves barrier performance are useful indicators of competitive strength. At the same time, raw material volatility and regulatory complexity warrant careful assessment of margin resilience and compliance readiness across geographies.
For procurement and supply chain leaders, the emphasis should be on supplier capability and transparency rather than price alone. Evaluating suppliers on moisture resistance, recyclability documentation, customization flexibility, and sourcing stability can reduce risk in demanding applications. Given ongoing input cost variability, diversifying the supplier base where feasible and securing commitments that balance cost with reliability can improve outcomes. Engaging suppliers early on specification changes and compliance requirements can also smooth transitions as regulatory deadlines approach and performance expectations rise.
Strategic decisions in this market benefit from detailed, up-to-date intelligence on segment-level demand patterns, regional dynamics, and competitor movements. PW Consulting's comprehensive research report on the Multiwall Paper Bags Market provides deeper segmentation data, regional breakdowns, and customized guidance to support planning and investment choices. Accessing that level of detail can help translate the trends and considerations outlined here into precise, actionable strategies tailored to specific business contexts.
For detailed analysis of this topic, please visit the official page: Multiwall Paper Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com