

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
High Carbon Bearing Steel Market: Why 6.4% CAGR Redefines 2032 Growth

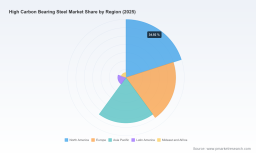
Strategic Trends and Commercial Opportunities in the High Carbon Bearing Steel Market
The high carbon bearing steel market has evolved from a steady industrial commodity segment into a strategically critical materials market shaped by precision engineering demands, regulatory tightening, and shifting end-use requirements. Valued at approximately USD 146.55 million in 2025, the market reflects a consistent growth trajectory from its 2020 base of roughly USD 109.55 million, with a forecast extending through 2032 that points to a compound annual growth rate of 6.4 percent. This expansion is not merely a function of broader industrial output; it signals a structural realignment in how bearing steels are specified, manufactured, and integrated into downstream products. As companies navigate tighter performance tolerances, sustainability mandates, and raw material volatility, the market is increasingly rewarding players who can couple metallurgical precision with supply chain resilience.
Market Snapshot and Structural Challenges
The market's size and growth profile underscore a segment that is expanding at a pace above many traditional specialty steel categories, yet it remains highly concentrated. A handful of producers command the majority of share, reflecting the technical barriers to entry, capital intensity of advanced melting and refining processes, and the long qualification cycles required by demanding end users. Revenue streams are distributed across multiple product forms, with bearing steel bars representing the dominant configuration, while plates, wire, tubes, and rods serve more specialized or volume-sensitive applications. Demand is anchored by several sectors, with automotive and industrial machinery forming the core consumption base, while aerospace, railway, and marine applications contribute incremental but increasingly strategic growth.
Key Challenges and Inflection Points
Three interlocking challenges are reshaping competitive dynamics and forcing strategic recalibration.
- Raw material and energy cost volatility: High carbon bearing steel production is highly sensitive to input price swings. Iron ore fluctuations alone have been shown to impact total production costs by up to 32 percent annually, while chromium costs vary by roughly 27 percent year over year. Energy represents another substantial burden, accounting for 20 to 25 percent of manufacturing expenses, with recent electricity price increases of about 18 percent adding pressure to margins and pricing stability.
- Regulatory and specification upgrades: Domestic mills in key regions are facing tighter cleanliness and inclusion standards that effectively require ladle furnace and vacuum degassing investments. In China, regulatory revisions have mandated cleanliness benchmarks aligned with recognized international bearing specifications, compressing the gap between domestic capability and global-tier performance. These changes raise capital requirements and accelerate the differentiation between mills that can meet advanced specifications and those that cannot.
- Demand fragmentation and qualification cycles: End-use sectors are increasingly requiring higher consistency, cleanliness, and traceable performance. Automotive powertrain designs, industrial machinery under higher cycle loads, and aerospace components all impose more stringent metallurgical expectations. At the same time, qualification timelines remain long, which limits how quickly new entrants can access premium segments and reinforces the advantage of established relationships and documented reliability.
For decision makers, these challenges translate into a simple but demanding reality: scale alone is insufficient. The winners will be those who combine cost discipline with technical capability, secure predictable input strategies, and align product development with the specifications that end users are rapidly institutionalizing.
Core Drivers of Market Change
Technological Innovation in Melting and Refining
Advances in secondary refining are central to the market's trajectory. Vacuum degassing and controlled ladle furnace treatments are no longer optional enhancements for premium bearing steel; they are becoming baseline requirements to manage inclusion content, control carbon and chromium distributions, and ensure consistent hardness and fatigue performance. Mills that have integrated these processes are better positioned to serve automotive and aerospace segments where failure risk is unacceptable and cleanliness tolerances are increasingly narrow. This technological shift also creates a natural filter in the competitive landscape: producers with modernized assets can capture higher-value orders, while those relying on older process chains face margin compression and reduced access to specification-driven demand.
Policy and Regulatory Tightening
Regulatory evolution is accelerating both capability upgrades and market realignment. The push toward cleanliness standards that mirror global bearing specifications is compelling domestic producers to invest in advanced refining, which in turn raises the bar for what qualifies as a competitive offering. Beyond product specifications, environmental and energy policies are reshaping operating economics. Energy cost trends, emissions considerations, and efficiency mandates are pushing producers to evaluate furnace optimization, process heat recovery, and more precise control over melting cycles. For companies operating across jurisdictions, regulatory divergence can become both a risk and an opportunity: early compliance and documentation can shorten sourcing approvals, while lagging capability can restrict market access.
Demand-Side Shifts Toward Reliability and Service Life
End users are increasingly prioritizing bearing steels that support longer service life, reduced maintenance intervals, and predictable performance under variable loads and speeds. Automotive manufacturers are seeking materials that can withstand higher rotational speeds and temperature variations while maintaining dimensional stability. Industrial machinery operators are under pressure to improve uptime and reduce total cost of ownership, which favors materials with consistent cleanliness and superior fatigue behavior. In aerospace and railway applications, where reliability is paramount, the demand for tighter control over microstructure and inclusion content is further reinforcing the move toward higher-specification grades. This demand-side evolution is not simply about volume growth; it is about a shift toward value-accretive specifications that reward technical differentiation and stable supply.
Supply Chain and Cost Structure Realignment
Raw material volatility and energy cost pressures are driving a rethinking of procurement and production strategies. Because iron ore and chromium price movements can materially affect total costs, producers are increasingly evaluating long-term contracting, alternative sourcing, and inventory buffering strategies to protect margins. At the same time, energy intensity is prompting attention to process efficiency and plant-level optimization. This environment favors organizations that can integrate metallurgical capability with disciplined procurement and operational flexibility, especially as end users seek suppliers who can offer stable pricing, documented quality, and continuity of supply in an unpredictable input environment.
Competitive Landscape and Leading Strategies
The market's concentrated structure reflects the technical and capital requirements of producing high-quality bearing steel at scale. Leading players are differentiating themselves through a combination of metallurgical specialization, application-targeted development, and selective capacity or product expansion. The result is a landscape where competitive advantage is increasingly tied to specification readiness, process control, and the ability to serve demanding end markets without compromising consistency.
Strategic Positioning Among Key Players
Several companies illustrate distinct paths to differentiation. Specialist steelmakers focused on high-tech engineering grades are building reputation and backlog in automotive and industrial bearing applications by offering dedicated high carbon bearing steel grades with tight tolerances and proven reliability. In Japan, producers with integrated portfolios and strong aerospace and industrial bearing focus are expanding capacity or refining product lines to capture premium demand, signaling a deliberate move toward higher-value applications. In China, major producers are leveraging environmentally conscious production methods and broadening their processed bearing steel offerings for industrial machinery, while others are expanding product ranges to address industrial performance requirements more comprehensively. These strategies point to a broader pattern: successful participants are aligning product development with the most specification-sensitive applications, investing in process capability, and using application-focused portfolios to build switching costs and customer loyalty.
Recent Developments as Strategic Signals
Recent company actions underscore where value is being sought. Capacity expansion directed at aerospace demand reflects the premium that highly controlled bearing steel commands in sectors where failure risk is unacceptable and documentation is rigorous. New product launches targeting industrial machinery indicate an effort to broaden exposure to high-performance applications while building on existing commercial relationships. Taken together, these moves suggest a market in which growth is increasingly captured by producers that can move beyond generic supply and into application-engineered solutions with verified performance.
Market Structure Evolution
The market is likely to see continued consolidation among producers that can fund advanced refining, maintain consistent quality, and serve demanding applications, while smaller or less-equipped mills may face pressure to specialize, partner, or exit higher-specification segments. New entry remains challenging due to qualification cycles and capital intensity, but targeted partnerships, subcontracting, and niche product development can provide pathways for specialized players. For buyers, this environment rewards diversification of qualified suppliers where feasible, combined with deeper collaboration with preferred producers to secure consistency, lead times, and specification alignment.
PW Consulting
Future Outlook: Trends and Commercial Implications
Trend One: Specification Upgrading as the New Baseline
Over the next three to five years, cleanliness and inclusion control are expected to become standard expectations across more applications, not just aerospace or premium automotive niches. Mills that have already invested in advanced refining will be able to serve a wider range of orders with minimal additional reconfiguration, while others will face rising obsolescence risk for legacy process chains. The commercial opportunity lies in aligning product portfolios with the specifications that procurement and engineering teams are institutionalizing, and in building the documentation and traceability that accelerate sourcing decisions.
High Strength Steel Market
Trend Two: Cost and Supply Resilience as a Competitive Moat
Given the sensitivity of production costs to iron ore, chromium, and energy prices, companies that can stabilize input exposure and optimize energy use will be better positioned to offer reliable pricing and continuity. This is likely to become a differentiator in bids and long-term supply agreements, especially for industrial machinery and railway applications where procurement teams value predictability. The strategic play is to combine technical quality with procurement and operational discipline, turning cost resilience into a repeatable advantage rather than a temporary buffer.
Bearing Steel Market
Trend Three: Application-Linked Product Development
As end-use requirements become more segmented, generic bearing steel offerings will increasingly give way to grades developed with specific application profiles in mind. The most attractive opportunities will be in segments where performance improvements translate directly into measurable gains: reduced wear, extended service intervals, higher load capacity, or better stability under variable conditions. Producers and suppliers that can co-develop grades with end users, supported by consistent process control and documented test data, are likely to capture stronger positioning and more defensible margins.
Risks and Uncertainties
The outlook is not without risk. Continued raw material and energy volatility could erode margins for producers without hedging or efficiency strategies. Regulatory divergence across regions may complicate global supply strategies and increase compliance costs. Qualification lead times and documentation burdens may slow the ability of new or upgraded players to access premium segments. Finally, demand patterns in automotive and industrial machinery can shift with broader economic cycles, influencing order timing and inventory behavior. Navigating these uncertainties will require a balance of technical readiness, supply discipline, and relationship depth.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to ensure that process capability matches the specifications that buyers are increasingly demanding. Investments in secondary refining, process control, and quality documentation are not optional enhancements; they are becoming prerequisites for access to higher-value orders and longer-term agreements. Manufacturers should also evaluate procurement and energy strategies as part of a holistic competitive plan, since input volatility can quickly undermine the benefits of technical differentiation. Aligning product development with application profiles and maintaining close dialogue with key customers can help convert specification readiness into repeat business.
For investors, the market rewards companies that combine metallurgical capability with disciplined cost management and clear application focus. Asset quality, specification breadth, and the ability to serve demanding segments are indicators of resilience and pricing power, while exposure to volatile input markets and legacy process chains can create disproportionate risk. Monitoring capacity actions, product launches, and regulatory-driven upgrades can provide early signals about which players are likely to expand their share of premium demand versus those that may face margin pressure.
For procurement and sourcing leaders, the emphasis should be on qualifying suppliers not only for price but for specification compliance, consistency, and supply continuity.Diversification of qualified sources can reduce concentration risk, while deeper collaboration with preferred producers can secure better alignment on lead times, cleanliness requirements, and documentation standards. In a market where cost volatility and specification upgrades are reshaping supply options, a procurement strategy that values technical reliability alongside price will be better positioned to protect downstream performance and total cost of ownership.
The high carbon bearing steel market is entering a phase where technical precision, regulatory compliance, and supply resilience converge to define competitive advantage. Detailed segmentation data, regional dynamics, and company-level development timelines can sharpen these strategic choices further, providing the granularity needed to prioritize investments, qualify suppliers, and time market entries with greater confidence.
For detailed analysis of this topic, please visit the official page: High Carbon Bearing Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com