

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Engineered Wooden Flooring Market 2026: Why 7% CAGR Signals a Structural Shift in Global Resale Value
By pmarketresearch, 2026-09-21
Navigating the Engineered Wooden Flooring Market: Strategic Trends and Commercial Opportunities Through 2032
The engineered wooden flooring market has moved from a niche alternative to traditional solid hardwood into a mainstream specification across residential, commercial, and hospitality projects. With a base-year valuation of $215.0 million in 2025 and a projected trajectory reaching $344.79 million by 2032, the sector is expanding at a compound annual growth rate of 6.98%. This growth is not merely a function of population or housing starts; it reflects a structural shift in how developers, architects, and homeowners evaluate durability, dimensional stability, sustainability, and total cost of ownership. The historical arc from $153.44 million in 2020 to the current baseline underscores a market that has consistently outpaced broader flooring segments, driven by product maturation and broader acceptance in demanding environments.
For executive teams, investors, and procurement leaders, the numbers tell only part of the story. The real strategic question is how to position within a market that is simultaneously consolidating around scale players, fragmenting through specialized product innovation, and confronting a rapidly shifting regulatory and cost environment. The period from 2026 through 2032 will reward firms that can align product roadmaps with specification trends, manage tariff and supply chain volatility, and communicate verifiable performance advantages to architects, contractors, and end users.
Laminate Flooring Market
Market Status and Core Challenges
The engineered wooden flooring market operates at a crossroads of growth and complexity. Revenue has climbed steadily from $158.68 million in 2021 through $179.78 million in 2022, $186.76 million in 2023, and $204.56 million in 2024, before reaching the 2025 baseline. The forecast window projects continued acceleration, with figures moving from $225.53 million in 2026 to $249.32 million in 2027, $258.33 million in 2028, $272.59 million in 2029, $296.86 million in 2030, $329.9 million in 2031, and $344.79 million in 2032. This trajectory signals a market that is scaling but also increasingly sensitive to macroeconomic, regulatory, and competitive dynamics.
Fragmented Competition with Moderate Concentration
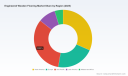
Market concentration remains relatively low, with the top three players accounting for approximately 24.6% of revenue and the top five reaching about 26.2%. This structure indicates a competitive landscape where scale advantages exist but do not dominate, leaving space for specialized manufacturers, regional brands, and product-led disruptors. The moderate concentration also means that pricing power is distributed, and differentiation increasingly depends on performance claims, warranty structures, finish technology, and specification support rather than volume alone.
Key Challenges and Inflection Points
Several structural challenges are reshaping how companies compete and how buyers evaluate engineered wooden flooring:
- Regulatory and tariff volatility: The trade environment has become a defining variable. Reciprocal tariffs of up to 20% on imported engineered wood flooring and related hardwood/plywood from key origins took effect in October 2025, altering cost structures and sourcing strategies. Complementing this, a preliminary affirmative determination in the antidumping investigation on hardwood and decorative plywood imports from China was issued in January 2026, adding further uncertainty to cross-border supply chains. While earlier Section 232 measures on wood products initially excluded engineered wood flooring, subsequent reciprocal measures have closed part of that gap, creating a more complex compliance and cost landscape.
- Material and chemical compliance pressures: Formaldehyde emission limits continue to push manufacturers toward low-VOC and zero-emission resins. This is not a marginal compliance issue; it affects formulation choices, supplier selection, production line adaptation, and marketing claims. Companies that can verify low-emission performance and communicate it credibly gain an edge in specification-driven segments, while those slower to adapt face rising compliance costs and potential reputational risk.
- Differentiation in a maturing product category: As engineered wooden flooring becomes more commonplace, buyers increasingly compare technical attributes—scratch resistance, dimensional stability, waterproof or water-resistant variants, plank dimensions, and finish durability—rather than treating the category as a generic alternative. This raises the bar for product development and specification support, and it compresses margins for undifferentiated offerings.
Key Drivers of Market Change
The market's expansion is being pulled by a combination of technology, regulation, demand-side behavior, and supply chain economics. These forces interact in ways that create both opportunities and constraints for different business models.
Technology Innovation and Performance Breakthroughs
Product innovation is shifting from aesthetic replication toward verifiable performance. Acrylic-infused engineered wood flooring, for example, is engineered for superior scratch resistance, dimensional stability, and carbon reduction, directly addressing long-standing concerns about wear in high-traffic residential and commercial settings. Tarkett's pure natural engineered wood flooring lines emphasize durable, recyclable hardwood construction, aligning performance with sustainability narratives that resonate with specification teams and environmentally conscious buyers. Mullican Flooring's Eloquence engineered oak collection, launched in April 2025, features an aluminum-oxide finish and a 50-year warranty, signaling a push toward longer-life positioning and confidence-based marketing. AHF Products' Bruce-engineered hardwood extends similar logic with up to 50-year residential warranties and prefinished protective coatings, reinforcing durability as a commercial message. Meanwhile, Mohawk's TecWood and other engineered hardwood lines with factory-finished options, waterproof variants, and wide-plank configurations illustrate how product portfolios are broadening to meet diverse installation environments and design preferences.
These innovations matter because they change the value proposition. When scratch resistance, stability, and finish longevity are demonstrable, engineered wooden flooring competes more effectively against luxury vinyl and other resilient alternatives in spaces where wood aesthetics are desired but traditional solid hardwood is impractical. For manufacturers, the implication is clear: R&D and finish technology are becoming core differentiators, not support functions.
Policy and Regulatory Environment
Regulation is no longer a background condition; it is an active driver of product design and sourcing strategy. Formaldehyde emission limits are accelerating adoption of low-VOC and zero-emission resins across North American manufacturers, as reflected in recent industry outlook commentary. This shift influences raw material procurement, production processes, and certification pathways. At the same time, trade measures are reshaping cost structures. The reciprocal tariffs that began in October 2025 and the January 2026 preliminary determination in the antidumping investigation on Chinese hardwood and decorative plywood imports create a dual pressure: costs for certain imported inputs or finished goods may rise, while domestic and allied-source supply chains gain relative attractiveness.
For businesses, the regulatory driver cuts both ways. It raises the cost of non-compliance and the complexity of sourcing, but it also creates opportunities for manufacturers that can document compliance, secure relevant certifications, and offer supply chain transparency. Mohawk Flooring's October 2025 NWFA/NOFMA certification for engineered wood flooring products is a concrete example of how industry recognition can reinforce credibility in a compliance-sensitive environment.
Demand-Side Shifts in Consumer and Business Behavior
Demand is being reshaped by changing expectations around aesthetics, durability, and sustainability. Residential applications continue to represent the largest share of market value, reflecting homeowners' preference for wood aesthetics combined with the practical advantages of engineered construction in environments where moisture, subfloor conditions, or installation speed matter. Commercial and hospitality segments, while smaller in relative terms, are influenced by different dynamics: specification criteria, lifecycle cost, maintenance requirements, and brand alignment with sustainability goals.
In practice, this means specification teams and procurement groups are weighing more than initial price. They are increasingly attentive to finish warranties, dimensional stability claims, maintenance regimes, and environmental profiles. The growth in wide-plank configurations, matte and satin finishes, and extra-long boards—seen across several leading collections—indicates that design preferences are evolving toward larger, more contemporary formats that still rely on engineered construction for stability. For suppliers, this demands closer engagement with specifiers and a clearer articulation of how product attributes translate into installation and maintenance benefits.
Supply Chain and Cost Structure Changes
Tariffs, antidumping actions, and resin compliance requirements are collectively reshaping cost structures. Imported engineered wood flooring and related substrates face higher effective costs under reciprocal measures, while domestic and allied-source alternatives may benefit from relative price competitiveness and lower compliance friction. At the same time, the shift toward low-VOC and zero-emission resins can alter input costs and require production adjustments, affecting both margins and time-to-market for reformulated products.
Supply chain resilience is becoming a strategic priority. Companies that diversify sourcing, secure reliable substrate supplies, and invest in factory-finished capabilities can reduce exposure to import volatility and improve delivery predictability. For investors and executives, the key is to view cost structure not as a static input but as a dynamic variable shaped by trade policy, chemical regulations, and manufacturing geography.
Competitive Landscape and Leading Strategies
The competitive field combines established scale players with specialized manufacturers and regional brands, each pursuing different levers of differentiation. The market's moderate concentration leaves room for multiplewinning positions, but sustaining them requires clear strategic focus.
Strategic Positioning and Differentiators Among Leading Companies
Several patterns emerge when examining how leading firms position their engineered wooden flooring offerings:
- Performance and warranty leadership: Mullican Flooring and AHF Products emphasize long-duration warranties and advanced finishes, using durability claims to justify premium positioning and build specifier confidence. Mullican's Eloquence collection, with its aluminum-oxide finish and 50-year warranty, exemplifies a durability-first narrative.
- Water resistance and format expansion: Mohawk Industries extends its portfolio with waterproof variants, factory-finished options, and wide-plank configurations, targeting environments where moisture and contemporary design preferences intersect. This broadens the addressable use cases beyond traditional dry interiors.
- Sustainability and material purity: Tarkett's pure natural engineered wood flooring lines focus on durable, recyclable hardwood construction, aligning with specification trends that value recyclability and material transparency. This positions the brand in projects where environmental messaging is part of the value proposition.
- Finish aesthetics and board dimensions: Shaw Industries Group's core engineered hardwood collections feature matte and satin finishes, extra-long boards, and sustainable options, reflecting a design-driven approach that meets evolving 인테리어 preferences while maintaining performance credibility.
- Certification and compliance credibility: Mohawk Flooring's NWFA/NOFMA certification achievement in October 2025 illustrates how industry recognition can reinforce trust in a market where performance claims and compliance are under greater scrutiny.
- Specialized engineered profiles: Mercier Wood Flooring's engineered 1/2-inch and 3/4-inch hard maple and oak planks in collections such as Idol and Legend, and Nydree Flooring's acrylic-infused engineered wood flooring with superior scratch resistance, dimensional stability, and carbon reduction, show how specialized formulations and dimensions can carve out distinct positions.
Evolution of the Competitive Structure
The market is not trending toward a single dominant model. Instead, it is evolving through a combination of consolidation at the top, specialization in the middle, and continued entry from focused newcomers. Scale players leverage breadth, distribution, and specification support to defend share, while specialized manufacturers compete on technical attributes, finish technology, and targeted applications. Regional brands and niche entrants can thrive by focusing on particular wood species, plank dimensions, finish systems, or sustainability credentials that resonate with local specification communities.
This structure suggests that competitive advantage will increasingly come from the ability to combine product performance with credible certification, reliable supply, and strong specifier engagement. Price competition alone is unlikely to sustain differentiation in a market where buyers are comparing warranties, emission profiles, and installation practicality alongside aesthetics.
Future Trends and Commercial Opportunities (2026–2032)
Looking ahead, several trends are likely to shape how the market grows and where opportunities emerge. These are not speculative narratives; they are grounded in current product directions, regulatory signals, and the observed trajectory of market size through 2032.
Trend 1: Performance-Led Differentiation Will Become the Default Expectation
As engineered wooden flooring becomes more widely specified, buyers will increasingly expect demonstrable performance rather than categorical claims. Scratch resistance, dimensional stability, finish longevity, and moisture handling will move from nice-to-have attributes to baseline evaluation criteria. Commercial opportunity lies in developing and communicating verifiable test data, offering meaningful warranties, and aligning finish technologies with real-world use cases. The risk is that product claims outpace substantiation, which can erode trust and invite scrutiny from specifiers and regulators.
LVT Flooring Market
Trend 2: Regulatory and Trade Dynamics Will Continue to Reshape Sourcing and Cost
The combination of emission limits, reciprocal tariffs, and antidumping measures indicates that trade and compliance will remain central variables. Companies that build diversified, resilient sourcing strategies and maintain clear compliance documentation will be better positioned to manage cost swings and specification requirements. Commercial opportunity exists for manufacturers that can offer stable supply, transparent compliance, and competitive total cost despite import pressures. The uncertainty lies in the potential for further trade measures and the pace at which emission standards tighten, both of which can alter cost structures and product roadmaps.
Trend 3: Design Formats and Sustainability Narratives Will Co-Drive Specification
The movement toward wider planks, longer boards, and matte or satin finishes reflects a design evolution that engineered construction is well suited to support. Simultaneously, sustainability considerations—recyclable construction, low-emission resins, carbon reduction claims—are becoming part of specification decisions in commercial and hospitality projects. Commercial opportunity lies in product lines that marry contemporary formats with credible environmental profiles and durable finishes. The risk is greenwashing or overstatement; buyers and specifiers are increasingly adept at distinguishing substantiated claims from marketing language.
Implications for Commercial Opportunity
Taken together, these trends point to several opportunity spaces. Manufacturers can capture share by investing in finish and infusion technologies that improve durability and stability, then communicating those benefits through warranties and certification. Distributors and retailers can differentiate through specifier education, installation support, and clear guidance on where engineered wooden flooring outperforms alternatives. Investors can look for companies with defensible product technology, credible compliance posture, and flexible sourcing strategies that can absorb trade volatility. Across all roles, the ability to connect product attributes to real installation and maintenance outcomes will be a critical value driver.
Strategic Actions for Decision-Makers
Different roles in the value chain face distinct priorities, but all benefit from a disciplined approach to product, compliance, and specification strategy.
PW Consulting
For Manufacturers and Brand Leaders
- Prioritize finish and material technologies that deliver measurable improvements in scratch resistance, dimensional stability, and moisture handling, and back them with meaningful warranties and third-party recognition where appropriate.
- Strengthen compliance documentation and low-emission formulations to meet tightening formaldehyde and VOC expectations, turning compliance into a specification advantage rather than a cost center.
- Diversify sourcing and manufacturing footprints to reduce exposure to import tariffs and antidumping actions, while maintaining cost competitiveness and delivery reliability.
For Investors and Capital Allocators
- Evaluate target companies on the strength of their product differentiation, warranty structures, certification posture, and ability to manage trade and compliance risk, not solely on revenue growth.
- Favor businesses with flexible supply chains and clear positioning in performance or sustainability, as these attributes are better placed to withstand regulatory and tariff volatility.
- Monitor consolidation patterns and specialization trends to identify where scale advantages are accruing and where niche leaders may be attractive acquisition or partnership candidates.
For Procurement and Specification Teams
- Evaluate engineered wooden flooring options against total lifecycle criteria—durability, maintenance, emission compliance, warranty support, and installation practicality—rather than initial unit cost alone.
- Seek suppliers that provide verifiable performance data, relevant certifications, and clear guidance on suitable applications, especially where moisture, traffic, or subfloor conditions are concerns.
- Build sourcing flexibility to account for tariff and compliance shifts, and prioritize suppliers with transparent supply chains and stable delivery records.
Conclusion
The engineered wooden flooring market is expanding along a clear growth path, but the nature of that growth is changing. Value is shifting from category acceptance to performance substantiation, from price competition to differentiated finish and material technologies, and from static sourcing to resilient, compliance-aware supply chains. The period from 2026 through 2032 will reward organizations that can align product innovation with specification realities, navigate trade and regulatory dynamics, and communicate credible, verifiable advantages to buyers and specifiers.
For leaders seeking deeper segment-level detail, granular competitive benchmarks, and tailored strategic recommendations, PW Consulting's full report on the engineered wooden flooring market provides the structured data and scenario analysis needed to move from insight to execution.
For detailed analysis of this topic, please visit the official page: Engineered Wooden Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LV and MV Switchgear Market: Why the 6.98% CAGR Reshapes Global Competition
By pmarketresearch, 2026-09-21
LV and MV Switchgear Market: Strategic Trends and Commercial Opportunities
The global LV and MV switchgear market has entered a phase of sustained expansion, reaching an estimated USD 21.5 billion in revenue in 2025 and projected to surpass USD 34.4 billion by 2032. This trajectory reflects a compound annual growth rate of approximately 7 percent across the 2026-2032 forecast period, accelerating from a 2020 baseline of USD 16.3 billion. The growth is not merely a function of incremental demand but a structural realignment driven by electrification, grid modernization, and regulatory shifts that are rewriting procurement requirements and technology roadmaps. For executives navigating capital allocation, product portfolios, or supply chain strategy, the market signals a transition from commoditized equipment sales to solution-oriented, digitally integrated power distribution ecosystems.
Understanding where value is being created requires looking beyond headline revenue figures. The market is dispersing across multiple layers: voltage class, application vertical, and geography all shape competitive positioning, but the underlying dynamics are converging around three themes. First, environmental mandates are forcing a rapid redesign of medium-voltage architectures. Second, digital connectivity has moved from a differentiator to a baseline expectation across both low-voltage and medium-voltage segments. Third, raw material volatility and manufacturing capacity constraints are reshaping margin structures and accelerating regionalization of supply chains. These forces are redistributing advantage among established multinationals, specialized niche players, and agile regional manufacturers.
Metal-Clad Switchgear Market
Market Landscape: Scale, Structure, and Structural Tension
Macro Trajectory and Concentration Dynamics
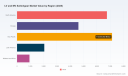
The market's growth path from 2020 through 2025 demonstrates resilience against macroeconomic headwinds, with revenue climbing steadily despite supply chain disruptions and inflationary pressures. The forecast period extends this momentum, with projections indicating acceleration in the latter half of the decade as utility capital programs mature and industrial electrification ramps up. Importantly, the market remains moderately fragmented. The top three players account for roughly 24.6 percent of total revenue, while the top five reach approximately 26.2 percent. This concentration level suggests a market where scale advantages exist but are not insurmountable, and where differentiated technology, regional service networks, and specification-winning capabilities can sustain profitable positions for focused competitors.
Three Defining Challenges
The industry is navigating a set of intersecting pressures that qualify any straightforward growth narrative. First, environmental regulation is compressing product lifecycles. The prohibition on new SF6-filled medium-voltage switchgear at or below 24 kV, effective from January 2026 under EU Regulation (EU) 2024/573, has shifted procurement specifications and capital planning timelines. Public procurement notices on the EU TED portal now reference SF6-free solutions in grid reinforcement projects, meaning manufacturers and system integrators must align product roadmaps with compliance deadlines that are already in force. This transition is not simply a substitution exercise; it requires revalidation of insulation performance, thermal management, and field service protocols, adding complexity to project execution.
Second, raw material costs are eroding margin predictability. Copper traded between USD 8,400 and USD 9,500 per ton during 2024-2025, while CRGO steel surpassed USD 3,000 per ton. These input pressures cut low-voltage OEM margins by up to four percentage points in some periods. Simultaneously, prices for aluminum mill shapes and primary and secondary nonferrous metals rose more than 25 percent over the past year, affecting enclosures, busbars, and structural components. The cumulative effect is that cost pass-through is uneven across regions and customer contracts, making pricing strategy and inventory management more strategic than operational.
Third, the market is experiencing a bifurcation between volume-driven standardization and value-driven customization. End-users in industrial and utility segments increasingly demand digitally connected equipment that integrates with monitoring, protection, and asset management platforms. At the same time, price sensitivity persists in commercially oriented segments where standardization is the norm. Winning in this environment requires clear segmentation of product architecture, production processes, and service models, because the economic logic of a commodity-style feeder panel differs fundamentally from that of a smart, configurable substation assembly.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Architecture
Environmental Regulation as a Technology Accelerant
Regulatory pressure is no longer a compliance cost center; it is reshaping the innovation pipeline. The EU's prohibition on SF6-filled medium-voltage switchgear up to 24 kV has catalyzed commercial momentum for SF6-free alternatives, including dry air, vacuum, and clean air insulation technologies. Schneider Electric's AirSeT portfolio exemplifies this shift, positioning SF6-free medium-voltage solutions with digital connectivity as a response to both regulatory directionality and customer sustainability targets. The same regulatory environment is forcing board-level decisions on urban substation modernization, as upgrade programs now must account for SF6-free specifications that alter project timelines, specification processes, and capital planning assumptions.
Beyond Europe, regulatory and policy signals are aligning with decarbonization and grid resilience goals. Utilities and large industrials are under increasing scrutiny to reduce greenhouse gas footprints, and switchgear selection is becoming a visible component of Scope 1 and Scope 2 reporting. This creates a commercial advantage for manufacturers that can offer verified SF6-free solutions with documented performance, because procurement teams need defensible specifications that withstand both internal sustainability reviews and external stakeholder expectations.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Digital Connectivity as a Value Multiplier
Digitalization has moved from a premium add-on to a structural requirement across both low-voltage and medium-voltage segments. Smart switchgear with embedded sensing, condition monitoring, and communication interfaces enables predictive maintenance, faster fault isolation, and integration into broader grid management platforms. Schneider Electric's introduction of the FeederSeT smart, compact, and digitally connected low-voltage switchgear range for indoor and outdoor applications illustrates how manufacturers are embedding connectivity into core product lines rather than treating it as a separate SKU. For utilities and industrials, the value proposition extends beyond reliability: digital switchgear reduces downtime, improves asset utilization, and supports lifecycle cost optimization, which matters as labor constraints and skilled technician shortages become more acute.
The commercial implication is that differentiation is shifting from physical protection performance alone to data-enabled service models. Manufacturers that can combine robust hardware with analytics, remote visibility, and integration with customer energy management systems are capturing higher value-share and deeper customer relationships. This trend also raises the barrier for entrants that lack software, data architecture, and service delivery capabilities.
Demand-Side Shifts: Electrification and Grid Modernization
Demand growth is being shaped by two reinforcing currents. On the utility and infrastructure side, grid reinforcement programs, renewable integration, and electrification of transport and heating are driving medium-voltage expansion. Mitsubishi Electric's order for 84 kV dry air insulated switchgear from Kansai Transmission and Distribution in Japan reflects how high-voltage, SF6-free solutions are entering mainstream transmission and distribution modernization programs. On the industrial side, reshoring, data center expansion, and electrification of process heat are increasing power distribution density, which in turn drives demand for compact, reliable, and digitally manageable switchgear.
For commercial and residential applications, the pattern is more heterogeneous. Some regions are experiencing steady replacement and upgrade cycles, while others see demand tied to building electrification and local grid constraints. The common thread is that end-users increasingly evaluate switchgear not only on protection performance but also on footprint, maintainability, and compatibility with digital energy management strategies. This shifts the purchasing dynamic from lowest-capital-cost to total-cost-of-ownership considerations, which favors suppliers with strong engineering support and lifecycle service offerings.
Supply Chain and Cost Structure Reconfiguration
The supply chain environment is prompting strategic recalibration. Input cost volatility, combined with the need for specialized insulation materials and digital components, is pushing manufacturers toward longer-term supplier agreements, dual-sourcing, and regional production footprints. Hitachi Energy's announcement of a USD 1 billion investment in transformer and grid equipment manufacturing with a new factory in Virginia signals how major players are committing to domestic capacity expansion in response to demand growth and supply chain resilience priorities. For the broader LV and MV switchgear ecosystem, such capacity investments indicate a multi-year ramp in manufacturing capability, but also a lag between investment announcements and commercially available incremental capacity, which can sustain pricing tension in the near term.
At the same time, component availability for digital subsystems, including sensors, communication modules, and control electronics, introduces dependency on semiconductor and electronics supply dynamics that differ from traditional electromechanical supply chains. Manufacturers that integrate these capabilities internally or through tightly managed partnerships gain flexibility, while those dependent on fragmented supplier bases face more variable lead times and quality risk.
Competitive Landscape: Positioning, Differentiation, and Structural Evolution
Strategic Positioning Among Leading Players
The competitive set spans global multinationals with broad power distribution portfolios and specialized manufacturers with focused application expertise. Siemens AG emphasizes a comprehensive medium-voltage power distribution portfolio anchored in smart grid capabilities, vacuum technology, and 24 kV ratings serving utilities and industrial applications, positioning reliability and system integration as core themes. Schneider Electric pairs a smart low-voltage FeederSeT range with SF6-free AirSeT medium-voltage solutions, using digital connectivity and regulatory alignment to appeal to customers managing both operational performance and sustainability obligations. ABB Ltd. maintains a broad medium and low-voltage equipment manufacturing footprint, including digital switchgear and regional production capabilities, with an emphasis on power distribution breadth and engineering integration. Eaton Corporation focuses on custom low and medium-voltage solutions for industrial, commercial, and utility power distribution, leveraging application engineering and configuration flexibility. Mitsubishi Electric's 84 kV dry air insulated and SF6-free solutions highlight a focus on grid modernization and renewable integration with high-voltage technology differentiation.
On the specialized side, Enercon Power provides custom-designed low and medium-voltage switchgear up to 15 kV with UL891 and UL1558 certification, serving on-site industrial and defense applications where specification precision and certification rigor matter. RESA Power and BCS Switchgear address markets that value remanufactured and custom new equipment, offering metal-clad, metal-enclosed, and pad-mounted styles across voltage ranges up to 38 kV, appealing to cost-conscious buyers who still require performance and reliability. LS Electric Co., Ltd. targets optimized medium-voltage switchgear for primary and secondary distribution across industrial, commercial, and residential applications, while Liyond provides medium-voltage switchgear solutions including GIS, KYN, RMU, and other configurations, competing on configurable product breadth and regional service reach.
Differentiation and Competitive Wedges
Several strategic wedges are shaping competitive outcomes. One is regulatory-ready SF6-free performance. As SF6 restrictions tighten and procurement specifications reference SF6-free requirements, manufacturers with validated alternatives and established certification paths are positioned to win specification decisions earlier in project cycles. A second wedge is digital service integration. Suppliers that offer not just connected hardware but also interoperable data formats, remote diagnostics, and preventive maintenance programs are building switching costs and recurring value streams. A third wedge is application-specific customization and certification. In industrial, defense, and specialized utility contexts, the ability to deliver UL-certified, code-compliant, and site-specific designs with reliable lead times creates a defensible niche that broad-line competitors may under-serve.
A fourth, often underappreciated, wedge is supply assurance. In a period of input cost volatility and capacity ramp-up, customers are assigning premium value to suppliers that can commit to delivery, maintain inventory buffers, and provide transparent lead-time visibility. This favors players with disciplined operations, multi-site manufacturing, and strong supplier relationships, and it is particularly relevant for large projects where delays carry significant penalty and reputational risk.
Structural Evolution: Consolidation, Fragmentation, and New Entrants
The market's moderate concentration suggests room for targeted consolidation, particularly in remanufacturing, specialty customization, and regional service segments where scale Economics are less dominant than technical capability and customer relationships. At the same time, fragmentation persists because application diversity and local code requirements sustain demand for smaller, agile suppliers that can respond quickly to niche specifications. New entrants are most likely to emerge where digital-native approaches, modular product platforms, or regional manufacturing models can offer meaningful cost or responsiveness advantages, but their success will depend on navigating certification, field validation, and service infrastructure requirements that are difficult to replicate quickly.
A plausible evolution path is a barbell structure: large multinationals expanding their integrated smart and SF6-free portfolios while consolidating service and aftermarket channels, and a layer of specialized manufacturers strengthening positions in high-specification industrial, defense, and regional utility applications where customization and certification expertise command premium economics. The middle ground of undifferentiated commodity switchgear faces the greatest pressure from input cost volatility, digital expectations, and regulatory-driven redesign cycles.
Future Trends and Commercial Implications
Trend One: SF6-Free Medium-Voltage Becomes Specification Default
Over the next three to five years, SF6-free solutions will move from an environmentally motivated alternative to a default consideration for medium-voltage switchgear at or below 24 kV in regulated markets, with influence extending to procurement specifications in other regions through multinational customer policies and utility sustainability commitments. The commercial opportunity lies in developing validated product lines, supporting documentation, and field service capabilities that reduce specification risk for customers. The uncertainty is whether alternative insulation technologies can achieve cost parity at scale and whether project timelines can absorb revalidation and training requirements without delaying capital programs.
Trend Two: Digital Integration Drives Recurring Value and Switching Costs
Digital connectivity will increasingly be treated as part of the core product architecture rather than an accessory. Expect broader adoption of condition monitoring, remote diagnostics, and integration with energy and asset management platforms, particularly in industrial and utility settings where downtime costs and labor constraints are acute. Manufacturers that build interoperable data layers and service offerings can capture higher-margin recurring revenue and deepen customer lock-in. The risk is that digital fragmentation and cybersecurity requirements raise integration complexity, and that customers demand open standards that reduce the proprietary advantage of any single supplier.
Trend Three: Regionalization and Capacity Investment Redraw Supply Economics
Capacity investments and supply chain regionalization will reshape lead times, cost structures, and competitive geography over the forecast period. Large manufacturing commitments signal a multi-year expansion cycle, but near-term supply tightness may persist in specific components and regions, sustaining pricing tension for commoditized segments while allowing premium economics for differentiated, certified, and digitally enabled products. The opportunity is for manufacturers and integrators that can combine regional supply assurance with specification-winning technology and service. The uncertainty is whether macroeconomic conditions, trade policy, or raw material disruptions could alter the pace of capacity realization and whether demand growth in certain verticals might outpace available qualified capacity.
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Align product roadmaps explicitly with SF6-free requirements and digital connectivity expectations. Treat regulatory deadlines and customer sustainability specifications as design constraints from the outset rather than late-stage adaptations. Prioritize validated insulation alternatives, certification completeness, and field service readiness, because specification wins increasingly depend on defensible performance documentation and compliance clarity. In parallel, structure product architectures to separate high-volume standardized lines from configurable, digitally enabled offerings so that margin structures and production processes match the economic logic of each segment.
- Invest in SF6-free validation, certification pathways, and lifecycle documentation to reduce customer specification risk.
- Build interoperable digital service capabilities, including remote monitoring, predictive maintenance, and data integration, as part of the core offering rather than an add-on.
- Segment manufacturing and pricing strategies to protect margins against raw material volatility while preserving competitiveness in standardized segments.
For Investors and Capital Allocators
Focus on firms with clear differentiation in SF6-free technology, digital service integration, and application-specific customization, rather than relying solely on scale. The moderate market concentration implies that targeted capabilities can sustain strong positioning, but the same dynamics are compressing margins in undifferentiated commodity segments. Evaluate exposure to regulatory-driven demand acceleration, regional capacity expansion, and recurring service revenue potential, while scrutinizing raw material sensitivity, certification risk, and lead-time reliability.
- Differentiate between scale advantages and capability advantages; in a moderately fragmented market, technology and service differentiation can generate premium economics.
- Assess exposure to regulatory tailwinds and digital service monetization, and weigh these against input cost sensitivity and supply chain concentration risk.
- Watch for consolidation opportunities in remanufacturing, specialty customization, and regional service where technical capability and customer relationships matter more than commodity scale.
For Procurement and Supply Chain Leaders
Treat switchgear selection as a total-cost-of-ownership decision shaped by regulatory compliance, digital integration, service availability, and supply assurance. Specification processes should account for SF6-free requirements, lead-time reliability, and compatibility with energy and asset management platforms, because these factors increasingly determine operational resilience and lifecycle cost. Where projects span multiple regulatory jurisdictions or involve multinational operations, standardize specifications around future-proofed architectures to reduce rework and re-procurement risk later in the project lifecycle.
PW Consulting
- Embed SF6-free and digital connectivity requirements early in specification and evaluation criteria to avoid late-stage redesigns and timeline disruptions.
- Prioritize suppliers with transparent lead times, regional supply assurance, and certified performance documentation, particularly for critical industrial and utility projects.
- Evaluate total lifecycle economics, including maintenance, downtime risk, and data integration, rather than focusing solely on upfront capital cost.
Positioning for the Next Phase of Value Creation
The LV and MV switchgear market is transitioning from a hardware-centric equipment market to a solution-oriented domain where regulatory compliance, digital service, and supply assurance differentiate winners. Revenue growth to the mid-2030s reflects real structural demand, but value capture will favor those who can navigate SF6-free transition timelines, integrate digital capabilities into core product architecture, and manage the margin impact of raw material volatility through disciplined segmentation and supply strategy. For manufacturers, investors, and procurement leaders, the immediate task is to align decision frameworks with these dynamics rather than treating them as peripheral concerns. More detailed segmentation data, regional demand breakdowns, and company-level competitive assessments can sharpen execution planning, and readers seeking that level of granularity can explore the full PW Consulting research report for comprehensive figures and tailored strategic recommendations.
For detailed analysis of this topic, please visit the official page: LV and MV Switchgear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Desiccant Dehumidifier Market 2032: Why 6.35% CAGR Signals a Structural Shift
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Desiccant Dehumidifier Market
Market Landscape and Core Challenges
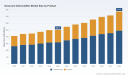
The global desiccant dehumidifier market has demonstrated consistent expansion over the past half-decade, moving from approximately 412.45 million USD in 2020 to 502.4 million USD in 2025. Forward projections indicate a steady climb toward 773.2 million USD by 2032, supported by a compound annual growth rate of 6.35 percent across the 2026 to 2032 horizon. This trajectory reflects more than incremental demand; it signals a structural shift in how critical environments manage moisture, energy, and operational reliability. While conventional condensation-based systems continue to serve standard comfort and residential applications, industries requiring precise humidity control, low dewpoints, or operation in sub-ambient conditions are increasingly turning to desiccant technologies as a non-negotiable infrastructure component.
The market structure itself reveals a moderately concentrated landscape. The three largest players command roughly 54 percent of total revenue, while the top five extend their combined share to 62 percent. Such concentration suggests that scale, established technical reputations, and long-term service networks play a significant role in winning high-stakes contracts. Yet the remaining market share is widely distributed across regional specialists, application-focused integrators, and emerging product developers. This fragmentation is not a sign of weakness; rather, it creates room for differentiated positioning, niche innovation, and targeted partnerships, especially in sectors where humidity control is tightly coupled to process yield, equipment longevity, and regulatory compliance.
Despite the favorable growth outlook, the industry is navigating several inflection points that will shape competitive outcomes over the next cycle. First, energy efficiency expectations are rising at a pace that challenges legacy system architectures. Facility operators and engineering teams are no longer evaluating dehumidifiers solely on moisture removal capacity; they are scrutinizing total energy consumption, integration with existing HVAC infrastructure, and the ability to maintain performance without inflating operating expenses. Second, regulatory and standards-driven requirements are reshaping procurement criteria. Cleanroom specifications, refrigerant phase-down pressures, and energy conservation mandates are influencing not just which technologies are permitted, but how quickly specifications must adapt to remain compliant. Third, supply chain resilience and material availability are becoming strategic concerns. The performance of desiccant media, the durability of rotating wheel assemblies, and the availability of precision control components all affect product reliability and lead times, particularly when demand spikes across multiple regions simultaneously.
These challenges do not diminish the market outlook; they redefine the basis of competition. Manufacturers and buyers alike are moving from a commodity mindset toward a performance-and-integration mindset, where the value of a dehumidification system is measured by its ability to stabilize environments, reduce lifecycle costs, and adapt to tightening operational rules.
Key Demand Drivers
Technology Innovation and Performance Breakthroughs
Technological advancement is one of the most visible forces expanding the addressable market for desiccant dehumidification. Recent product introductions highlight a clear direction: systems are becoming more scalable, more precise, and more compatible with conventional building and industrial infrastructure. Munters’ launch of the MX3 dehumidifier series in March 2026 illustrates this trend. Positioned as a scalable platform for full humidity and temperature control based on desiccant technology, the series reflects an engineering emphasis on flexibility across applications rather than a single-point solution. In parallel, Mojave Energy Systems introduced the AquaDry hydronic liquid desiccant air handling unit in May 2026, designed to deliver 25°F supply dewpoints using conventional chilled water. The significance of this development lies in its efficiency implication: by extending chiller capacity and improving efficiency by 20 percent, the product shows how desiccant systems can complement rather than compete with existing cooling infrastructure.
These innovations matter because they lower the practical barriers to adoption. When desiccant equipment can be integrated into standard chilled-water systems, when platforms can scale across different project sizes, and when dewpoint control becomes more predictable, procurement teams have stronger justification to specify desiccant solutions in new construction, retrofits, and mission-critical upgrades. The broader implication is that technology leadership is increasingly defined by integration capability, controllability, and energy optimization, not simply by moisture removal alone.
PW Consulting
Policy, Regulatory Pressure, and Standards Alignment
Regulatory and standards environments are exerting steady pressure on both equipment design and purchasing behavior. In the United States, the Department of Energy’s proposal to amend energy conservation standards for dehumidifiers, with a final rule anticipated around 2025 and 2028 referenced as a compliance benchmark, signals that efficiency requirements will continue to tighten. For manufacturers, this means product roadmaps must account for regulatory floors that may eliminate less efficient designs over time. For buyers, it means that today’s specification choices are increasingly linked to tomorrow’s compliance posture.
At the same time, international frameworks are reinforcing the case for desiccant adoption in specific settings. Strict energy efficiency and management practices associated with ISO 50001 are encouraging facilities that aim to reduce greenhouse gas emissions to consider desiccant dehumidifiers as part of broader decarbonization strategies. In parallel, EU regulations on refrigerants and energy efficiency have accelerated the transition to desiccant technology with zero ozone depletion potential, a shift reflected in a meaningful share of new commercial building projects. These regulatory dynamics are not abstract; they directly influence equipment selection in regions where compliance risk, operational reporting, and sustainability targets are closely tied to capital decisions.
Standards related to controlled environments are equally influential. ISO 14644 requirements for cleanroom operation in electronics and semiconductor manufacturing emphasize the need for precise humidity control, reinforcing desiccant dehumidifiers as a preferred option where process sensitivity is high. In such environments, humidity stability is not a comfort parameter; it is a quality and yield parameter, which makes the performance characteristics of desiccant systems especially valuable.
Demand-Side Shifts in Critical and Process-Sensitive Applications
Demand-side behavior is changing as more sectors recognize humidity control as a core operational requirement rather than a peripheral building service. Food and pharmaceutical operations continue to represent some of the most sensitive application spaces, where moisture management intersects with preservation, contamination control, and regulatory-grade environment stability. Electronics and semiconductor-related activities add another layer of demand intensity because tightly controlled cleanroom conditions are essential to manufacturing integrity. Energy and chemical applications further broaden the market base, particularly where process drying, corrosion mitigation, or moisture-sensitive storage create persistent operational needs.
Construction and adjacent sectors also contribute to demand, though often through different adoption logic. In these settings, desiccant equipment may be specified for temporary environmental control, moisture mitigation during build-out, or specialized indoor conditions where conventional systems are less effective. What unites these diverse applications is a growing expectation that humidity control should be robust, predictable, and compatible with broader facility goals. Buyers are increasingly willing to invest in systems that reduce downtime risk, protect sensitive assets, and support consistent process outcomes. This shift elevates desiccant dehumidifiers from optional equipment to strategic infrastructure in many procurement decisions.
Supply Chain and Cost Structure Considerations
Cost dynamics and material conditions are shaping how products are designed, sourced, and priced. The desiccant media landscape provides a useful example. Silica gel is positioned to lead the desiccants market with an estimated 38 percent revenue share in 2026, driven by strong adsorption capacity and established performance characteristics. For equipment manufacturers, the prevalence of such materials matters because media selection influences efficiency, regeneration requirements, service intervals, and overall system design. Any disruption in the availability or pricing of key materials can affect product economics and delivery timelines.
Beyond materials, the cost structure of desiccant dehumidifiers is influenced by precision component supply, manufacturing scale, and the cost of servicing complex installations over time. As competition intensifies and efficiency expectations rise, companies are under pressure to optimize not only initial equipment cost but also total cost of ownership. This encourages designs that reduce energy draw, extend service life, and simplify maintenance. It also encourages suppliers to strengthen inventory planning, diversify sourcing where possible, and align production with demand patterns that may vary by region and application. The practical result is that cost competitiveness in this market is becoming multidimensional, blending product engineering, operational efficiency, and supply chain discipline.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Leading Players
The competitive environment is shaped by a combination of established multinational players, application-focused specialists, and regional integrators. Munters Group, headquartered in Stockholm, continues to emphasize desiccant-based humidity and temperature control as a core offering, with recent product launches reinforcing its focus on scalable platforms and broad application coverage. Its positioning suggests an emphasis on technical breadth and repeatable engineering solutions that can be adapted across industrial, commercial, and process-sensitive environments.
Condair Group, based in Zurich, brings a comparable emphasis on controlled moisture management within broader HVAC and humidification/dehumidification contexts. Its strategy reflects the value of integrated environmental control, where desiccant dehumidification is positioned as part of a larger system logic rather than a standalone device. Bry-Air Inc., operating from Michigan, has long been associated with desiccant drying and humidity control solutions, and its market presence underscores the importance of application-specific expertise, especially where low dewpoint performance and robust drying capability are required.
Desiccant Dryer Market
Mojave Energy Systems, located in Sunnyvale, California, has carved out a distinct position through innovation that targets efficiency and integration with existing chilled-water infrastructure. Its liquid desiccant approach demonstrates how a company can differentiate by solving a practical operational problem: achieving aggressive dewpoint control while improving system efficiency. Climate by Design International, based in Minnesota, has focused on mission-critical applications where precise environmental control is essential. Its acquisition by Modine Manufacturing Company in October 2025 highlights a growing pattern in which larger industrial or HVAC-oriented firms absorb specialized capabilities to expand their desiccant dehumidification reach and strengthen their position in critical-environment segments. Trotec Laser GmbH, headquartered in Austria, represents the presence of firms whose desiccant-related offerings are tied to specific operational contexts and application expertise, reinforcing the broader theme that specialization remains a viable competitive route.
Differentiation and Competitive Advantage
Across these players, differentiation is increasingly built on several recurring advantages. One is application-specific engineering. Companies that can demonstrate proven performance in cleanrooms, drying processes, pharmaceutical environments, or mission-critical facilities gain credibility with buyers who face stringent operating requirements. Another is integration design. Products that connect cleanly with chilled-water systems, building management controls, or existing HVAC architecture reduce installation friction and improve operational continuity. A third is efficiency. As energy standards tighten and operating costs remain a central concern, the ability to deliver moisture control with lower energy penalties becomes a strong commercial argument.
Service capability and long-term support also matter. Desiccant systems often involve rotating wheels, regeneration configurations, media maintenance, and control calibration. Buyers evaluate not only initial equipment performance but also the reliability of service networks, spare part availability, and technical responsiveness. In a moderately concentrated market, these factors can be decisive, especially when projects require sustained uptime or when facilities operate under tight environmental tolerances.
Market Evolution: Consolidation, Differentiation, and New Entry
The landscape is evolving along multiple axes. Consolidation is evident where larger manufacturing or HVAC groups acquire specialized firms to expand technology coverage and market access. The Modine acquisition of Climate by Design International is a clear example of this logic, adding desiccant dehumidification technology and capacity for mission-critical applications to a broader portfolio. Such moves can accelerate product development, expand service reach, and strengthen competitive positioning in high-value segments.
At the same time, differentiation remains powerful. Exhibitions and trade presence continue to play an important role in market development. Dryer Air-Handling Equipment Co., Ltd. exhibited at AHR Expo 2026 in Las Vegas and participated at ARBS 2026 in Melbourne, displaying desiccant dehumidification solutions and reinforcing the relevance of face-to-face technical engagement in a market where performance claims, configuration options, and application fit need close examination. These events show that even as product platforms mature, customer education and technical demonstration remain essential.
New entry and expansion are also possible where innovation addresses an unresolved operational pain point. Liquid desiccant approaches, scalable platform designs, and efficiency-focused configurations all represent potential entry points for firms that can prove measurable advantages in real installations. The market is therefore unlikely to become uniformly consolidated; instead, it is more likely to sustain a layered structure in which broad-line players compete on scale and integration while specialists compete on application depth, unique technology, or service intensity.
Future Trends and Forward Outlook
Trend One: Efficiency-Led System Design Will Become the Default Expectation
Over the next three to five years, efficiency will likely move from a desirable feature to a baseline requirement. With regulatory trajectories pointing toward tighter energy standards and with facility operators under pressure to manage operating costs, desiccant systems will be judged increasingly on how well they work alongside other plant equipment. This trend favors designs that reduce regeneration energy demand, leverage waste heat or conventional chilled water intelligently, and integrate smoothly with facility controls. For commercial opportunity, this creates demand for upgraded retrofits, hybrid configurations, and engineering services that can optimize existing installations rather than simply replace equipment.
Trend Two: Critical-Environment Applications Will Drive Higher-Value Specifications
As cleanroom, pharmaceutical, food, electronics, and mission-critical applications continue to expand or modernize, specification quality will become more important. Buyers in these segments are likely to prioritize repeatability, dewpoint precision, documented compliance support, and reliability under continuous operation. This trend opens opportunities for manufacturers and integrators that can provide application-tailored solutions, validated performance data, and service models aligned with sensitive operating environments. It also raises the stakes for suppliers that cannot demonstrate credible control over the conditions their equipment is expected to maintain.
Trend Three: Regional Diversification and Localized Support Will Gain Importance
Although concentration among leading firms remains significant, regional demand patterns and local support requirements will continue to shape market dynamics. Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa each present distinct application mixes, regulatory contexts, and procurement cultures. Over time, successful players are likely to strengthen localized engineering support, regional service capacity, and market-specific product configurations. For businesses evaluating expansion or partnership, this suggests that presence and responsiveness in the target region may be as important as global brand recognition.
Risks and Uncertainties
Several uncertainties bear watching. Regulatory timelines can shift, and the pace of final rule implementation may influence product planning and procurement cycles. Energy price volatility and operational budget constraints could slow adoption in some segments if efficiency gains are not sufficiently compelling. Material supply conditions, including availability and cost of key desiccant media and precision components, could affect production stability and pricing. In addition, if conventional dehumidification technologies improve their efficiency or if alternative moisture-control methods gain traction in certain applications, competition may intensify in segments that today appear firmly aligned with desiccant solutions. These risks do not weaken the market outlook, but they reinforce the need for scenario-aware planning.
Actionable Guidance for Decision Makers
For Manufacturers and Product Strategists
Prioritize integration and efficiency in the next product cycle. Systems that can connect with conventional chilled-water infrastructure, offer scalable configurations, and deliver measurable efficiency gains are more likely to win specification attention in both new projects and retrofits. Equally important is the ability to support mission-critical and process-sensitive applications with documented performance and reliable service. Manufacturers should also review supply chain planning for desiccant media and precision components, since material conditions and lead times can shape both cost structure and customer confidence.
Household Dehumidifiers Market
For Investors and Corporate Development Teams
Focus on the segments where humidity control is tied to quality, yield, compliance, or uptime. Food and pharmaceuticals, electronics, energy, and chemical applications represent environments where desiccant dehumidification is often linked to core operational outcomes rather than peripheral comfort. Consolidation trends also suggest that specialized capabilities can become valuable acquisition targets, especially where they add technology, application depth, or mission-critical credibility to a broader portfolio. When evaluating opportunities, consider not only revenue potential but also the defensibility of application expertise, service capacity, and efficiency-oriented product design.
For Procurement and Facility Leaders
Evaluate desiccant dehumidifiers as part of a total-environment and total-cost strategy. The most relevant questions are not limited to moisture removal capacity; they extend to dewpoint performance, energy interaction with existing systems, maintenance requirements, and the supplier’s ability to support the specific operating conditions of the facility. Where regulations, cleanroom standards, or sustainability goals affect operations, ensure that equipment choices align with anticipated compliance and efficiency expectations. Specifying with a long-term view can reduce rework risk, improve operational stability, and better position the facility for evolving standards.
The desiccant dehumidifier market is advancing along a clear but multi-layered path. Growth is supported by expanding demand in critical applications, evolving efficiency expectations, and continued product innovation that makes desiccant systems more compatible with real-world infrastructure. At the same time, competitive success will depend on how well companies navigate regulatory change, material and supply chain conditions, and the increasing expectation that dehumidification equipment deliver measurable operational value over its full lifecycle. For decision makers seeking a more detailed view of segment dynamics, regional variation, application-specific demand patterns, and tailored strategic options, the broader research record offers a deeper competitive map and a more granular basis for planning.
For detailed analysis of this topic, please visit the official page: Desiccant Dehumidifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
CdTe Thin Film Solar Cell Market: Why 13.5% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-21
CdTe Thin Film Solar Cell Market: Strategic Trends and Commercial Opportunities Beyond 2030
The cadmium telluride (CdTe) thin film solar market has transitioned from a niche alternative to a mainstream force in utility-scale photovoltaic deployment. Sustained revenue expansion from the early 2020s through the mid-2020s, followed by a projected double-digit compound annual growth rate through the early 2030s, underscores a structural shift in how large-scale solar assets are designed, financed, and operated. With total market valuation crossing the five-billion threshold in 2025 and continuing to scale toward the mid-teens by 2032, CdTe is no longer competing solely on cost alone. It is competing on balance-of-system efficiency, land utilization, supply chain resilience, and regulatory alignment. For executives navigating energy transition portfolios, the question has shifted from whether CdTe merits attention to how its growth trajectory intersects with corporate decarbonization timelines, grid interconnection constraints, and domestic manufacturing incentives.
Market Landscape and Defining Constraints
The CdTe thin film sector has demonstrated consistent valuation growth over the historical period, with momentum carrying forward into the forecast window. This expansion reflects not just volume scaling but a maturation of the technology stack: improved deposition uniformity, better module-level power conversion, and increasingly refined balance-of-system assumptions that favor lower weight and higher temperature tolerance. The trajectory suggests that CdTe has crossed a commercial viability threshold in regions where land availability, interconnection queues, and capital efficiency dictate project economics. Yet the growth path is not frictionless. Several structural tensions are reshaping how developers, manufacturers, and financiers evaluate CdTe deployments.
PW Consulting
Key Commercial Tributaries Shaping the Next Cycle
One persistent challenge is the tension between scaling production capacity and maintaining material availability without creating volatility in tellurium sourcing. While CdTe modules consume significantly less semiconductor material per watt than crystalline silicon alternatives, tellurium remains a byproduct of copper refining, and its supply dynamics can shift with mining output, metal price cycles, and refining capacity. This does not make the material scarce by default, but it does require strategic procurement, long-term supply agreements, and recycling pathways that reduce exposure to commodity dislocation.
A second challenge lies in navigating a policy environment that rewards domestic manufacturing and clean energy deployment but introduces compliance complexity. Incentives tied to local content, labor standards, and supply chain transparency can accelerate adoption in certain markets while raising the barrier to entry in others. Companies that treat regulatory alignment as an afterthought risk delays in permitting, reduced eligibility for support mechanisms, or higher financing costs if counterparties perceive compliance risk.
A third challenge is the growing differentiation between rigid and flexible form factors across application contexts. Rigid CdTe modules continue to anchor utility-scale economics, where scale, predictable output, and balance-of-system savings dominate decision criteria. Flexible variants open different deployment scenarios, including curved surfaces, lighter mounting structures, and non-traditional infrastructure, but they must prove consistent performance and durability under varied environmental conditions. The market is not choosing one format over the other; it is dividing by use case, and the strategic implication is that product roadmaps must be aligned to application-specific value propositions rather than generalized claims.
Core Drivers Shaping Market Direction
Multiple forces are converging to push CdTe further into the mainstream of large-scale solar planning. The most consequential are technological progress, regulatory momentum, demand-side economics, and supply chain economics. Each driver reinforces the others, but their interaction is where the commercial opportunity becomes clearer.
Technology Innovation and Efficiency Gains
CdTe has benefited from steady laboratory and production-path efficiency improvements, narrowing the performance gap with competing technologies while preserving inherent advantages in material intensity and thermal behavior. Record efficiency levels achieved in research settings have reached the low twenty-three percent range, while leading manufacturers have advanced manufacturing-line performance toward the low twenty-two percent range in recent years. These gains matter because even modest efficiency improvements translate into lower land requirements, reduced racking costs, and better energy yield per installed watt in hot climates. The commercial narrative is shifting from “CdTe is cheaper to make” to “CdTe can deliver a more favorable system-level cost profile in specific deployment conditions.” For developers and asset owners, this reframing expands the addressable opportunity beyond pure cost parity and into performance-matched site selection.
Dye Sensitized Solar Cell Market
Policy and Regulatory Alignment
Government attention to CdTe has become more explicit, with policy documents and program offices highlighting cost reduction, domestic scale-up, and utility-scale deployment as priorities. This kind of directional clarity matters to capital allocation because it reduces uncertainty around long-term demand visibility. When public agencies outline technology-specific priorities, it often signals potential support pathways, research coordination, and procurement alignment. At the same time, the regulatory landscape remains uneven across jurisdictions. Some markets are simplifying incentives for local manufacturing and clean generation, while others impose trade, content, or traceability requirements that need to be factored into multi-region strategies. The companies gaining traction are those aligning their expansion plans with policy trajectories rather than betting against them.
Demand-Side Behavior and Asset Economics
Demand for CdTe is being reinforced by how large-scale solar projects are financed and evaluated. Utility-scale buyers increasingly prioritize not just module price but total installed cost, land efficiency, degradation profiles, and operating temperature characteristics. CdTe’s lower material intensity and higher temperature tolerance can improve yield in environments where silicon modules may lose more output to heat-related efficiency losses. Meanwhile, corporate procurement and integrated energy strategies are pushing developers to reduce development risk, shorten construction timelines, and secure equipment from suppliers with visible capacity pipelines. This demand profile favors manufacturers that can offer scale, predictable delivery, and performance documentation that aligns with lender and insurer requirements.
Supply Chain Structure and Cost Resilience
Cost dynamics in CdTe are shaped by a combination of material efficiency, manufacturing footprint, and logistics. Because CdTe cells consume far less semiconductor material than crystalline silicon technologies, the input cost profile can be more resilient when semiconductor demand spikes elsewhere in the electronics or battery ecosystems. However, resilience depends on how well manufacturers manage tellurium procurement, module assembly scale, and regional production location. Recent expansion activity in domestic manufacturing reflects a broader recognition that supply chain proximity can reduce lead-time risk, improve logistics predictability, and align with incentive structures. The strategic lesson is that CdTe competitiveness is not just about cell efficiency; it is about the end-to-end architecture of production, sourcing, and delivery.
Competitive Positioning and Landscape Evolution
The competitive landscape in CdTe remains concentrated, with a small group of manufacturers commanding the majority of market share. This concentration is not accidental. CdTe commercialization requires specialized deposition know-how, scale economics, long-term supply commitments, and a track record that satisfies utility procurement standards. First Solar exemplifies this profile, with a product focus centered on commercial CdTe thin-film modules built for utility-scale deployments, supported by established manufacturing facilities and continued research toward higher efficiency. Its strategic positioning rests on integrating cell technology with system-level value: module design choices that reduce balance-of-system cost, a manufacturing footprint that supports delivery consistency, and ongoing R&D intended to improve conversion performance while maintaining commercial reliability.
Strategic Differentiation in a Concentrated Market
Leaders in this space do not win purely on module pricing. Their differentiation tends to emerge from a combination of manufacturing scale, supply chain control, deployment track record, and technology roadmaps that are credible into the next product generation. Recent operational and financial milestones have shown how execution can reinforce market confidence. Record sales and income growth in CdTe-related business during a recent first-quarter reporting period signaled that demand visibility and production execution can align in favorable cycles. At the same time, the start of construction on a new large-capacity CdTe manufacturing facility in the United States highlighted a deliberate move to expand domestic production capacity, reduce supply-chain latency, and align with regional policy incentives. Together, these moves illustrate a broader pattern: competitive advantage is being built through capacity expansion synchronized with demand growth and regulatory momentum.
Consolidation, Entry Barriers, and Emerging Competition
Market concentration is likely to persist in the near term because credible scale, performance documentation, and utility-grade reliability create high entry barriers. New entrants can disrupt specific segments, particularly in flexible or specialized applications, but displacing incumbent share in utility-scale procurement requires more than product specifications. It requires financing acceptance, bankability, warranty confidence, and integration into developer procurement pipelines. This dynamic suggests a landscape where incumbents consolidate share through scale and execution, while smaller players compete around niche formats, regional partnerships, or differentiated use cases. The more interesting strategic tension is not imminent fragmentation, but the gradual broadening of the value chain: more integrated module-plus-balance-of-system offerings, more recycling and material recovery initiatives, and more partnerships linking manufacturers with developers, financiers, and equipment providers.
Forward Outlook: Three Strategic Trends
Looking across the current trajectory and the forces shaping it, three trends are likely to define the CdTe market over the next several years. Each carries a distinct commercial implication, and each carries uncertainty that decision-makers should price into planning assumptions.
Solar Cell Metal Paste Market
Trend One: Utility-Scale Dominance with System-Level Optimization
Utility-scale applications will remain the primary growth engine, but the competitive edge will increasingly come from system-level optimization rather than module cost alone. Land constraints, interconnection delays, and balance-of-system expenses mean that developers will favor solutions that reduce structural materials, lower installation complexity, and deliver reliable yield under local climate conditions. CdTe’s material efficiency and thermal characteristics position it well for this optimization path. The commercial opportunity lies in aligning module specifications with site-specific performance models, financing criteria, and operations planning. The risk is that over-optimizing for one metric may understate total lifecycle performance, especially if degradation behavior, soiling, or temperature profiles are not fully reflected in procurement assumptions.
Trend Two: Domestic Manufacturing as a Strategic Asset
As policy frameworks continue to emphasize local production and supply chain resilience, manufacturers with visible domestic capacity pipelines will gain an advantage in markets where incentives, procurement rules, or supply risk perception favor regional production. Expansion events in the United States reflect this direction, but similar dynamics can emerge elsewhere if governments tie support to local content, jobs, or supply stability. The opportunity for companies is to use manufacturing geography as a strategic asset rather than merely a production decision. The uncertainty comes from policy continuity, permitting timelines, and the risk that demand growth may not fully absorb new capacity if project development slows or interconnection bottlenecks persist.
Trend Three: Material Strategy and Circularity as Competitive Moats
Tellurium management, recycling pathways, and end-of-life module recovery will become more central to commercial strategy. Because CdTe’s material advantage depends on efficient use of semiconductor inputs, any supply disruption or regulatory shift around material handling can influence cost and market access. Companies that invest early in closed-loop material strategies, supplier diversification, and recovery infrastructure may convert a procurement challenge into a competitive moat. This trend also intersects with increasing attention to lifecycle accountability across the solar value chain. The risk is that circular infrastructure can require capital, coordination, and time, and the commercial payoff may be uneven across regions and regulatory regimes.
Action Considerations for Decision-Makers
The CdTe market is large enough and dynamic enough that generic strategy prescriptions are unlikely to be useful. More valuable is a clearer line of sight between a company’s role in the value chain and the forces currently reshaping procurement, capacity, and policy alignment.
-
For manufacturers and technology developers: prioritize roadmap investments that improve efficiency without compromising reliability, and treat supply chain resilience as a core product attribute. Capacity expansion decisions should be tied not only to near-term order books but to anticipated regional incentives, developer procurement cycles, and interconnection timelines. Efficiency gains are necessary, but bankability, delivery consistency, and lifecycle material strategy are increasingly what determine long-term share.
-
For investors and capital allocators: evaluate CdTe exposure through system-level economics rather than module price alone. Demand visibility, capacity timing, policy alignment, and balance-of-system value all influence whether growth translates into durable returns. Watch for indicators such as domestic manufacturing progress, utility procurement patterns, and any shifts in material sourcing or recycling infrastructure that could alter cost structures. Diversification across formats and applications may reduce dependence on a single deployment cycle.
-
For procurement teams and project developers: use CdTe where its system-level characteristics match site conditions and financing requirements. Evaluate performance models against local temperature profiles, land constraints, and installation complexity, and ensure that module specifications are supported by credible warranty and degradation documentation. Where domestic production incentives or supply chain resilience criteria matter, incorporate manufacturing geography and supply continuity into sourcing decisions rather than treating them as secondary considerations.
The broader takeaway is that CdTe has moved into a phase where its commercial trajectory depends less on proving basic viability and more on executing within a complex set of market, policy, and supply chain conditions. Companies that understand the interplay between efficiency progress, regional manufacturing strategy, material sourcing, and utility-scale economics will be better positioned to capture value as the market scales. For teams that need more granular segmentation, regional deployment patterns, application-level nuance, or scenario-based assessments of capacity and policy shifts, deeper intelligence can shorten the distance between strategic intent and execution.
For detailed analysis of this topic, please visit the official page: CdTe Thin Film Solar Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ski Gear & Equipment Market: What the 3.82% CAGR Trajectory and 279.44 Million Valuation Reveal About 2032
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Ski Gear & Equipment Market: A 2026 Outlook
Market Landscape and Core Challenges
The global ski gear and equipment market has demonstrated resilient growth over the past five years, transitioning from a post-pandemic recovery phase into a period of structural expansion. Valued at approximately $163.15 million in 2020, the market climbed steadily to reach $204.71 million by 2024, with 2025 marking a milestone of $215.0 million. This trajectory reflects a compound annual growth rate of 3.82 percent through 2032, suggesting that the industry is moving beyond cyclical fluctuations and settling into a more predictable expansion phase. However, the growth story is not uniform, and several structural challenges are reshaping how manufacturers, retailers, and investors approach the sector.
One of the most pressing challenges is the tightening regulatory environment surrounding safety and product compliance. Governing bodies such as the FIS have introduced mandatory safety equipment requirements for competitive levels, including cut-resistant undergarments and airbag back protectors, effective from the 2025–26 season. Simultaneously, the European Union's General Product Safety Regulation now mandates digital product passports for helmets and protective gear, requiring manufacturers to document material sourcing, lifecycle impacts, and disposal methods for online marketplaces. These regulatory shifts increase compliance costs and operational complexity, particularly for mid-sized players who lack dedicated regulatory affairs teams. For industry leaders, the challenge lies in integrating compliance into product development cycles without eroding margins or slowing time-to-market.
Ski Apparel Market
A second critical challenge stems from geopolitical trade dynamics and their impact on cost structures. Recent tariff implementations have introduced significant uncertainty into sourcing and pricing strategies. European imports of ski equipment face potential tariff increases of up to 15 percent, with certain steel and aluminum components subject to rates as high as 50 percent, while Chinese-origin goods face tariffs around 30 percent. Early indicators suggest these measures are driving retailer price increases in the range of 5 to 20 percent. For companies reliant on cross-border supply chains, this creates a dual pressure: absorbing higher input costs or passing them to consumers in a market where price sensitivity varies significantly by segment and geography. The ability to navigate these tariffs through supply chain diversification, localized production, or strategic inventory positioning has become a decisive competitive factor.
A third challenge involves the evolving safety-performance nexus in consumer expectations. The recent recall of specific ski boot models by Head USA, prompted by concerns that fluorescent yellow materials could deteriorate and break during falls, underscores the heightened scrutiny on product reliability. This incident, flagged by the U.S. Consumer Product Safety Commission, highlights how product safety failures can rapidly damage brand trust and trigger regulatory intervention. For manufacturers, the imperative is to strengthen quality assurance protocols and material testing, particularly for components exposed to harsh environmental conditions. For retailers, the challenge is balancing assortment breadth with risk management, ensuring that inventory decisions align with both consumer demand and compliance standards.
Key Drivers of Market Change
Technological Innovation and Performance Breakthroughs
Innovation remains a primary engine of growth in the ski gear and equipment market, with manufacturers increasingly focused on materials science, ergonomic design, and hybrid construction techniques. The recent launch of the AR ONE ski boot by Armada, featuring Hybrid Cabrio Construction, exemplifies the industry's shift toward modular, performance-oriented designs that balance durability with weight optimization. Such innovations are not limited to competitive equipment; they are increasingly filtering into consumer segments where riders demand gear that adapts to varying snow conditions, terrain types, and skiing styles. Technological advancement also extends to protective equipment, where airbag back protectors and cut-resistant fabrics are transitioning from elite competition to broader market adoption, driven by both regulatory requirements and consumer awareness of safety.
For businesses, the implication is clear: product differentiation is increasingly tied to engineering capability and material innovation rather than brand heritage alone. Companies that invest in R&D partnerships, proprietary material formulations, and rapid prototyping cycles are better positioned to capture premium segments and command pricing power. At the same time, innovation cycles are compressing, meaning that the window between concept and commercialization is narrowing. Manufacturers must align their development pipelines with seasonal launch calendars while ensuring that new products meet evolving safety and compliance standards from the outset.
Policy and Regulatory Environment as a Market Reshaping Force
Regulatory developments are no longer peripheral concerns; they are active drivers of product design, supply chain configuration, and market access. The FIS mandates for cut-resistant undergarments and airbag back protectors in alpine speed events have cascading effects on the broader equipment ecosystem. Manufacturers of protective gear must scale production of certified components, while ski equipment makers may need to adjust binding, boot, and apparel designs to integrate compatible safety features. In parallel, the EU's digital product passport requirement for helmets and protective gear introduces traceability obligations that affect material procurement, manufacturing documentation, and end-of-life handling.
These regulatory shifts create both operational burdens and strategic opportunities. Companies that proactively build compliance into their product architecture can reduce the risk of retrofit costs and market delays. Moreover, regulatory transparency can serve as a trust signal in a market where consumers and retailers are increasingly attentive to safety and sustainability claims. The challenge is that compliance is not uniform across regions, meaning that multinational players must navigate a patchwork of requirements. Businesses with agile regulatory functions and flexible manufacturing footprints are better equipped to manage this complexity, while smaller players may need to seek partnerships or standardize offerings to reduce compliance overhead.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer behavior in the ski market is evolving along multiple dimensions. There is growing demand for equipment that supports diverse skiing modalities, from alpine downhill to cross-country and ski touring. This diversification is reflected in the market's application segments, where ski touring and backcountry-oriented gear have gained traction among consumers seeking adventure-based experiences beyond traditional resort skiing. At the same time, performance apparel continues to command significant share, as riders prioritize weather adaptability, mobility, and lifestyle integration. The line between functional gear and fashion-forward outerwear is blurring, particularly in segments where brand identity and aesthetic appeal influence purchasing decisions.
On the enterprise side, retailers are recalibrating their assortment strategies in response to both demand trends and cost pressures. The establishment of seasonal retail locations, such as Perfect Moment's first European store at the Kitzbuhel ski resort, illustrates a strategic move toward experiential, location-based retail that aligns with resort ecosystems and local customer bases. This model allows brands to test market responsiveness, build community engagement, and capture high-intent purchase moments during peak seasons. For larger retail networks, the focus is shifting toward curated assortments that balance entry-level accessibility with performance-tier offerings, while managing inventory risk in an environment of volatile input costs.
Ski Apparel Market
Supply Chain and Cost Structure Evolution
Supply chain dynamics are undergoing significant recalibration as tariffs, material costs, and logistics constraints intersect. The tariff landscape described earlier is prompting companies to reconsider sourcing geographies, evaluate nearshoring options, and adjust pricing architectures. For equipment categories that rely heavily on metals such as steel and aluminum, the exposure to higher tariff rates is particularly acute, forcing manufacturers to weigh material substitution, component redesign, or supplier relocation. These decisions carry long-term implications for product performance, production costs, and lead times.
At the same time, the market's concentration characteristics—with a substantial share held by a limited number of leading firms—mean that supply chain advantages are not evenly distributed. Larger players with established supplier relationships and diversified sourcing networks can absorb shocks more effectively, while smaller or specialized manufacturers may face disproportionate pressure. This dynamic is likely to accelerate consolidation trends, as mid-sized companies seek partners or acquirers to strengthen supply chain resilience. For investors and strategic planners, supply chain adaptability is becoming a core criterion for evaluating market participants, alongside product innovation and brand strength.
Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive landscape is shaped by a mix of established multinational brands, specialized equipment manufacturers, and retail-focused players. Amer Sports Oyj stands out for its multi-brand portfolio strategy, encompassing Salomon, Atomic, Armada, and Peak Performance, which spans skis, boots, bindings, poles, helmets, and snowboarding gear. This breadth allows the company to address multiple customer segments and skiing disciplines under a coordinated brand architecture. Its sponsorship of 250 athletes at the Milano Cortina 2026 Winter Olympics and Paralympics, resulting in 87 medals, reinforces the value of elite sport alignment as a credibility and visibility driver. For Amer Sports, the strategy combines performance heritage with broad market coverage, leveraging Olympic association to strengthen brand equity across both competitive and consumer channels.
Groupe Rossignol and Fischer Sports GmbH represent another dimension of the landscape, with deep specialization in skis, boots, bindings, and poles. Rossignol's focus on core ski equipment and Fischer's emphasis on technical components position these companies as go-to suppliers for riders who prioritize performance precision. Their strategies often center on product craftsmanship, racing lineage, and European manufacturing identity, which resonate with segments that value technical credibility and heritage. LEKI Lenhart GmbH and Marker Völkl further illustrate the specialization trend, with LEKI concentrating on ski poles and accessories and Marker focusing on bindings. These focused players often compete on component-level innovation and compatibility, serving both end consumers and OEM partners who require reliable, standards-aligned parts.
PW Consulting
Decathlon occupies a distinct position through its mass-market, vertically integrated model, offering skis, boots, bindings, and accessories under its own brand. Its strategy emphasizes accessibility, value engineering, and broad availability, making it a significant force in entry-level and mid-tier segments. By controlling design, production, and retail, Decathlon can respond quickly to demand shifts and manage cost structures in ways that pure manufacturers may find difficult. Meanwhile, brands like The North Face and Volcom bring apparel and protective gear expertise into the ski space, leveraging outdoor lifestyle positioning to capture consumers who view ski wear as part of a broader active lifestyle rather than a purely functional category.
Specialized and niche manufacturers such as ON3P Skis, Black Crows, Peak Ski Company, Voile, and Union Binding Company highlight the market's fragmentation at the high-performance and specialty ends. These companies often compete on handmade craftsmanship, specific skiing disciplines, or innovative binding and pole technologies. Their growth trajectories are closely tied to community loyalty, influencer and athlete endorsements, and the ability to differentiate in crowded categories. Black Diamond Equipment and Scott Sports contribute to this mosaic with poles, helmets, goggles, and protective gear, reinforcing the importance of safety and accessory categories as complementary revenue streams. Blizzard-Tecnica USA illustrates the partnership and regionalization model, combining boot and binding expertise with localized distribution to serve specific market needs.
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The market's concentration profile suggests that a relatively small number of firms command a significant share of revenue, which typically points to barriers to scale in distribution, brand investment, and supply chain management. However, the presence of numerous specialized players indicates that differentiation remains viable in specific subcategories, particularly where performance, customization, or niche discipline focus matters. This duality creates a landscape where consolidation pressure exists alongside opportunities for focused entrants who can serve underserved segments or introduce disruptive product concepts.
Recent product launches and retail initiatives provide a window into how this evolution is unfolding. Armada's AR ONE boot launch and Black Crows' Corvus ski model update demonstrate continued investment in product refreshes and performance positioning, even as the broader market grows at a moderate pace. Union Binding Company's Atlas Step On snowboard binding, with its responsive waterproof layer and extruded 3D aluminum heelcup, reflects innovation in binding mechanisms that aim to improve usability and durability. Perfect Moment's seasonal store expansion in Kitzbuhel indicates that retail experimentation is active, with brands seeking closer proximity to end consumers in destination markets. Together, these developments suggest that competition is increasingly multidimensional: brands must perform across product innovation, safety compliance, retail experience, and brand storytelling simultaneously.
Future Trends for the Next 3–5 Years
Safety and Compliance as Standard Product Attributes
Over the next several years, safety equipment and regulatory compliance are expected to transition from optional enhancements to baseline product requirements across more market segments. The FIS mandates for cut-resistant undergarments and airbag back protectors, combined with EU digital product passport requirements, are likely to normalize safety-integrated design and traceability documentation. As these standards diffuse from competitive levels into consumer markets, manufacturers that have already embedded compliance into their development processes will face lower adaptation costs. Commercial opportunity lies in positioning safety and transparency as trust multipliers, particularly for protective gear and children's equipment where parental decision-making is influenced by certification and material clarity. The risk is that compliance complexity could pressure smaller players, potentially accelerating consolidation or prompting reliance on standardized component suppliers.
Tariff-Driven Reconfiguration of Sourcing and Pricing
Trade policy uncertainty is expected to persist as a structural factor influencing cost bases and product pricing. The recent tariff dynamics affecting European and Chinese imports suggest that companies will continue to explore supply chain diversification, material alternatives, and pricing architectures that balance margin protection with consumer affordability. Over the next 3–5 years, this may lead to a more regionally varied product landscape, where certain markets see localized sourcing or adjusted product specifications to mitigate tariff exposure. Commercial opportunity exists for manufacturers that can demonstrate supply chain flexibility, such as multi-region production capabilities or modular component designs that allow material substitutions without compromising performance. The risk is that prolonged tariff volatility could compress margins for brands unable to pass through costs or reconfigure sourcing quickly, particularly in price-sensitive segments.
Modal Diversification and Experiential Demand Growth
Demand for ski gear is likely to continue diversifying across skiing modalities, with ski touring and backcountry-oriented equipment gaining share among consumers seeking adventure and off-piste experiences. This trend aligns with broader outdoor recreation growth and the desire for differentiated experiences beyond traditional resort skiing. At the same time, experiential retail and resort-adjacent distribution models are expected to expand as brands seek to capture high-intent purchase moments and build local community engagement. Commercial opportunity lies in developing product lines and retail concepts that match the needs of specific skiing styles, while leveraging destination-based activations to drive trial, loyalty, and seasonal demand spikes. The risk is that modal diversification can fragment demand, requiring more sophisticated assortment planning and inventory management to avoid overstock in slower-moving categories.
Actionable Recommendations for Decision-Makers
For Manufacturers and Brand Leaders
Product development cycles should integrate safety and compliance requirements from the earliest design stages rather than treating them as post-launch adjustments. Aligning R&D with regulatory trajectories—such as cut-resistant materials, airbag protection integration, and digital product passport documentation—can reduce retrofit risk and accelerate market readiness. At the same time, manufacturers should evaluate supply chain exposure to tariff-sensitive materials and consider modular component strategies that provide flexibility without sacrificing performance. For brands with multi-category portfolios, balancing specialization with cross-category synergies can help capture demand across skiing modalities while maintaining clear value propositions for each segment.
For Investors and Strategic Planners
Evaluation of market participants should extend beyond brand recognition to include supply chain resilience, compliance capability, and product differentiation in high-growth subcategories. Companies with diversified sourcing, strong safety engineering, and clear positioning in either performance specialization or accessible value segments are better placed to navigate regulatory and trade uncertainties. Interest in experiential retail and resort-adjacent distribution also warrants attention, as these models can provide demand visibility and community leverage, though they require careful capital allocation and seasonal risk management. Given the market's moderate growth pace and concentrated structure, identifying players with adaptable operating models and credible innovation pipelines is essential for long-term value capture.
For Retailers and Procurement Teams
Assortment planning should account for both compliance evolution and tariff-influenced pricing dynamics. Curating a mix of entry-level accessibility and performance-tier offerings can help balance volume and margin, while close monitoring of safety recalls and regulatory updates can mitigate reputational and inventory risk. Procurement strategies that diversify supplier bases and anticipate material cost shifts can improve resilience, particularly for equipment categories with high metal content or complex component sourcing. Engaging with brands that provide clear documentation, traceability, and product safety assurance can also strengthen consumer trust and reduce downstream complication costs.
Closing Perspective
The ski gear and equipment market is entering a phase where growth is supported by product innovation, demand diversification, and brand-driven retail experimentation, but it is also being reshaped by regulatory mandates and trade-related cost pressures. Success in this environment depends on the ability to align product development with safety and compliance trajectories, build supply chain flexibility, and differentiate in a landscape that rewards both specialization and strategic breadth. The interplay of these forces will determine which companies capture premium segments, which retailers optimize assortment and risk, and which investors identify resilient business models with credible innovation pipelines.
For decision-makers seeking deeper segmentation data, region-specific dynamics, and customized strategic recommendations, the full PW Consulting research report provides a more granular view of market sizing, competitive benchmarking, and scenario analysis across the ski gear and equipment value chain.
For detailed analysis of this topic, please visit the official page: Ski Gear & Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
X-Ray Detectors Market: Why 6.5% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-21
The X-Ray Detectors Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The global X-ray detectors market has matured into a multi-billion-dollar ecosystem defined by steady expansion, technological refinement, and shifting procurement dynamics. Valued at approximately 355 million USD in 2020, the market reached 487 million USD by 2025, reflecting a compound annual growth rate of 6.5 percent. Projections indicate the sector will approach 757 million USD by 2032, driven by synchronized upgrades in medical imaging infrastructure, industrial inspection requirements, and security screening demands. While the headline trajectory appears linear, the underlying mechanics are anything but static. Regional demand patterns, modality transitions, and regulatory pacing are reshaping how manufacturers position their portfolios and how end-users evaluate capital expenditure. For executives and investors tracking this space, the central question is no longer whether growth will continue, but where value will concentrate and which strategic moves will separate margin-accretive players from commoditized participants.
Understanding the current state of the X-ray detectors market requires moving beyond aggregate revenue figures and examining the structural forces that dictate pricing power, adoption curves, and competitive positioning.
-
From replacement cycles to capability upgrades. Procurement decisions are increasingly tied to performance thresholds rather than routine turnover. Higher detective quantum efficiency, improved modulation transfer function, and reduced pixel sizes are now mainstream expectations rather than premium differentiators.
-
Capital constraints meet technology ambition. Hospitals, industrial facilities, and security agencies operate under tighter operating budgets, yet the clinical and operational case for advanced detectors continues to strengthen. This tension creates a selective upgrade environment where financing models, refurbished components, and phased deployments gain strategic relevance.
-
Concentration remains moderate, but differentiation is intensifying. The market is not dominated by a handful of suppliers, leaving room for specialized entrants, regional champions, and cross-industry players to capture niches through application-specific engineering and integration expertise.
The market is expanding, but expansion alone does not guarantee profitable positioning. Several structural challenges are redefining the rules of engagement.
Transitioning Imaging Standards and Performance Expectations
Radiography workflows are no longer satisfied with basic digital capture. Diagnostic accuracy requirements, workflow integration, and throughput expectations are pushing detector specifications toward higher resolution, lower noise, and faster readout capabilities. This shift creates a performance arms race in which incremental engineering gains must be paired with system-level compatibility, software integration, and serviceability. Manufacturers that treat detectors as standalone components risk losing relevance as integrated imaging ecosystems become the default purchasing unit.
Regulatory Friction and Time-to-Market Pressure
Approval pathways for X-ray detectors continue to tighten, particularly where clinical or public safety claims intersect with evolving regulatory expectations. Substantial equivalence demonstrations, performance metric validation, and post-market conformity requirements add development overhead and extend launch timelines. This dynamic favors companies with mature quality systems, established predicate device strategies, and the ability to absorb compliance costs without losing product cadence. For newer entrants, regulatory navigation is not merely a procedural hurdle; it is a strategic barrier that shapes market access and competitive velocity.
Cost Structure Compression and Budget Sensitivity
Service and maintenance budgets in healthcare settings have experienced sustained pressure, while manufacturing scale in East Asia is compressing detector pricing. The combined effect is a market where mid-tier institutions can upgrade within existing capital envelopes, but where traditional pricing models face erosion. At the same time, demand for refurbished detector components is gaining traction as organizations balance performance aspirations against budget realism. This environment rewards manufacturers that can offer credible lifecycle economics, flexible configuration options, and durable hardware economics rather than relying on premium positioning alone.
Key Drivers Reshaping the Market
Growth in the X-ray detectors market is not being pulled by a single force. It is being shaped by converging technical, regulatory, demand-side, and supply-side dynamics that interact differently across medical, industrial, and security use cases.
Flat Panel X Ray Detectors Market
Technical Innovation and System-Level Integration
Detector technology is advancing along multiple vectors simultaneously. Flat-panel and solid-state designs continue to improve image metrics while enabling more compact form factors and broader deployment flexibility. Recent product activity illustrates how performance refinement is becoming a core competitive lever. In mid-2025, Canon Medical Systems and Konica Minolta introduced new detector lines with improved pixel size, modulation transfer function, and detective quantum efficiency for mobile X-ray units, incorporating Vieworks detectors and imaging software. Around the same period, Carestream Health expanded its DRX-Evolution Plus and DRX-Compass systems with Lux HD 35 and Lux HD 43 detectors, reinforcing the industry’s focus on clinical efficiency and mobile workflow compatibility.
These developments point to a broader pattern: detectors are increasingly optimized not only for image quality, but for portability, integration with software ecosystems, and adaptability across fixed and mobile configurations. For manufacturers, the strategic implication is clear. Superior pixel performance must be paired with usable system integration, reliable service support, and compatibility with existing clinical or industrial workflows. For buyers, the opportunity lies in technologies that improve throughput and diagnostic confidence without disrupting established operating procedures.
Policy, Reimbursement, and Regulatory Alignment
Demand for X-ray imaging is strongly influenced by reimbursement structures and approval pathways. In the United States, diagnostic X-ray tests are covered under Medicare when performed in outpatient settings or as part of initial preventive physical examinations, reinforcing the relevance of high-quality detector solutions in routine clinical environments. At the same time, FDA 510(k) clearances for X-ray detectors require demonstration of substantial equivalence to predicate devices, with performance metrics including modulation transfer function and detective quantum efficiency. Stricter regulatory approvals, including FDA 510(k) and EU MDR certifications, increase development costs and slow new technology launches, but they also create a competitive moat for organizations that can move through the process efficiently.
The regulatory environment is therefore a double-edged sword. It raises the barrier for fragmented, low-quality entrants while rewarding established players with robust compliance infrastructure and predictable product pipelines. For investors and corporate strategists, regulatory capacity is increasingly a strategic asset, not just a compliance function. Companies that can shorten time-to-clearance without sacrificing performance credibility gain advantage in both clinical and security segments where certification timing directly affects revenue realization.
Demand-Side Behavior and Operational Economics
End-user behavior is shifting from technology adoption for its own sake toward value justified by workflow efficiency, diagnostic reliability, and total cost of ownership. In healthcare, the emphasis is on reducing retakes, improving patient throughput, and integrating detectors with mobile and stationary systems in ways that minimize operational disruption. In industrial and security applications, the demand logic centers on inspection accuracy, detection sensitivity, and the ability to deploy imaging solutions in constrained environments. This demand evolution favors solutions that balance image performance with practical usability and maintenance economics.
A related shift is the growing acceptance of lifecycle-based procurement. With hospital service budgets tightened by roughly 13 percent in recent years, interest in refurbished detector components has increased. Rather than signaling a collapse in new equipment demand, this trend suggests a more segmented market in which premium new systems coexist with cost-conscious refurbishment and component-level replacement strategies. Manufacturers and channel partners that can address both new-capital and lifecycle-extension needs are better positioned to retain share across economic cycles.
Supply Chain Scale and Competitive Pricing Dynamics
Manufacturing scale in East Asia is compressing detector pricing, enabling mid-tier hospitals to upgrade within existing capital budgets. This development expands the addressable market by lowering financial barriers to adoption, but it also intensifies price competition and puts pressure on margin structures for suppliers that cannot offset pricing with differentiation. The strategic response is not simply to compete on cost, but to build value through performance credibility, integration depth, regional service coverage, and application-specific customization. In practice, the pricing environment is pushing the market toward a bifurcated structure: cost-competitive volume segments and performance-leading specialty segments.
Competitive Landscape and Leadership Strategies
The competitive field in X-ray detectors is broad, spanning established electronics and imaging conglomerates, specialized detector manufacturers, and regional players with strong local service footprints. The market remains moderately concentrated, leaving room for distinct strategic positions rather than a single dominant template. What separates leading players is not merely scale, but the ability to align detector technology with application needs, regulatory readiness, and integration economics.
Several companies illustrate how strategic positioning is evolving.
-
Varex Imaging Corporation emphasizes digital flat-panel detectors for medical imaging systems, with seamless integration between detectors, X-ray tubes, and software for high-resolution applications. This system-aligned approach supports customers seeking cohesive performance rather than isolated component upgrades.
-
Hamamatsu Photonics K.K. focuses on high-performance flat-panel and solid-state detectors used in medical radiography and industrial applications, leveraging deep expertise in photon detection technologies to address both clinical and non-medical imaging demands.
-
Canon Inc. advances flat-panel detectors integrated into digital X-ray systems with improved modulation transfer function and detective quantum efficiency for diagnostic imaging, reinforcing a strategy centered on diagnostic confidence and system-level refinement.
-
Carestream Health, Inc. highlights DRX series digital radiography detectors and mobile X-ray solutions for clinical efficiency, appealing to institutions prioritizing flexible deployment and workflow mobility.
-
Konica Minolta, Inc. pursues flat-panel and solid-state detectors for high-quality medical imaging with smaller pixel sizes and superior image metrics, aligning with the broader push toward higher-resolution diagnostic capabilities.
-
Thales Group extends solid-state and flat-panel X-ray detectors across medical and security applications, illustrating how detector technology can bridge very different end-use requirements through robust engineering and application versatility.
PW Consulting -
Teledyne Technologies Incorporated provides digital imaging solutions and detectors for X-ray systems, including Teledyne DALSA components, positioning around component-grade capabilities and specialized imaging architectures.
-
Rayence Co., Ltd. offers high-performance flat-panel detectors for medical applications, with recent regulatory milestones underscoring the importance of clearance pathways in expanding commercial availability.
-
Detection Technology Plc specializes in solid-state detectors for X-ray imaging, representing a focused strategy around detector core technology and materials expertise.
-
Vieworks Co., Ltd. delivers digital flat-panel detectors for radiology and industrial use, combining medical and cross-sector applicability to diversify demand exposure.
-
Trixell centers on flat-panel detectors for medical imaging, competing in a segment where integration compatibility and image consistency are critical purchasing criteria.
-
Agfa-Gevaert Group covers digital radiography and computed radiography detectors, balancing modern flat-panel offerings with established computed radiography capabilities that remain relevant in certain procurement environments.
-
Fujifilm Holdings Corporation supplies flat-panel detectors for digital X-ray systems, drawing on broader imaging heritage to support system integration and image processing ecosystems.
-
Analogic Corporation focuses on advanced X-ray detectors and imaging components, often serving applications where component reliability and interoperability are paramount.
-
Siemens Healthineers provides integrated detectors and solutions for X-ray imaging systems, with recent activity reflecting the value of cleared, system-ready technologies in accelerating adoption.
The competitive story is not simply a roster of names, but a pattern of differentiation. Leading players tend to cluster around several strategic postures. Some compete through system integration and software compatibility, positioning detectors as enablers of seamless workflows. Others compete through raw imaging performance and materials science, emphasizing resolution, noise characteristics, and detector efficiency. A third group competes through application breadth, spanning medical, industrial, and security markets to diversify demand and leverage shared core technologies. A fourth group competes through regional service strength and procurement flexibility, which becomes especially important where budget sensitivity and lifecycle economics shape buying decisions.
Market Structure Evolution: Consolidation, Specialization, and Entry Barriers
The market is unlikely to collapse into a single dominant architecture. Instead, it is evolving toward a layered structure. At one level, larger imaging and electronics players continue to strengthen their position by embedding detectors into broader platform ecosystems. At another level, specialized detector companies retain advantage by focusing on core sensor technology, niche applications, or regional service networks. New entry remains possible, but the combination of performance expectations, regulatory clearance requirements, and integration complexity raises the practical barriers to meaningful competition.
Strategic consolidation is likely to occur more through capability acquisition and partnership than through blunt market consolidation. Detector technology increasingly intersects with software, tube integration, mobile deployment, and workflow optimization. Companies that can combine detector performance with application-specific engineering and regulatory readiness will capture more value than those competing on detector specifications alone. Recent regulatory and product activity supports this interpretation: cleared systems and refined detector lines are being launched not as isolated components, but as parts of broader imaging solutions that promise faster deployment, better compatibility, and clearer clinical or operational value.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of market development will likely be defined by how companies navigate the intersection of performance improvement, procurement economics, and regulatory cadence. Three trends appear particularly consequential.
Performance Convergence Becomes the Baseline, Not the Differentiator
Improved pixel size, modulation transfer function, and detective quantum efficiency are rapidly moving from premium features to baseline expectations. Over the next several years, competitive advantage will shift toward how well detectors fit into real-world workflows, how reliably they operate in mobile and fixed configurations, and how effectively they support service continuity. The commercial opportunity lies in bundling detector performance with integration services, software compatibility, and deployment models that reduce total operating friction. The risk is that undifferentiated performance claims become table stakes, compressing pricing for suppliers that cannot demonstrate system-level value.
Expanded Access Through Cost Compression and Refurbishment Ecosystems
Lower detector pricing driven by manufacturing scale is broadening access for mid-tier institutions and expanding the pool of feasible upgrades. This opens new volume opportunities, but also encourages a more segmented market where refurbished components and lifecycle extensions play a larger role. Companies that build credible refurbished supply chains, component-level service offerings, and flexible financing models can capture demand that would otherwise slip to informal or lower-quality channels. The strategic risk is margin dilution if pricing pressure outpaces value differentiation, making it essential to pair cost competitiveness with clear performance and service guarantees.
Regulatory Pace as a Strategic Filter
Approval requirements will continue to shape market entry and product timing. FDA 510(k) clearances and EU MDR-related conformity expectations increase development costs and slow launches, but they also create a filtering mechanism that favors organizations with disciplined regulatory execution. Over the coming years, the ability to move cleared technologies into market-ready systems will be a meaningful competitive advantage, especially when paired with demonstrated performance equivalence and reliable imaging metrics. The uncertainty lies in how regulatory expectations evolve across regions and applications, which can shift timing advantage between competitors and alter the pace of adoption for new detector architectures.
These trends suggest that the market’s next growth phase will reward companies that treat detectors as part of a broader value proposition rather than as standalone hardware. Opportunities will emerge in mobile imaging optimization, industrial inspection specialization, security screening upgrades, and lifecycle services that extend the useful life of existing capital. Risks will concentrate in segments where pricing erosion, regulatory delay, or integration gaps weaken commercial viability.
Strategic Implications for Decision Makers
For executives, investors, and procurement leaders, the X-ray detectors market offers a structurally attractive growth path, but only when approached with clear positioning and disciplined execution.
For Manufacturers and Technology Providers
-
Align detector development with system-level integration. Image metrics matter, but compatibility with tubes, software, mobile deployment, and service networks increasingly determines commercial success.
-
Build differentiated positions through application specificity. Medical, industrial, and security segments have distinct performance and economics requirements; broadGeneric offerings risk competing in the most price-sensitive zones.
-
Strengthen regulatory and quality infrastructure as a strategic asset. Faster, more predictable clearance pathways can translate directly into competitive timing advantages and revenue realization.
For Investors and Corporate Development Teams
-
Evaluate value based on integration depth and application reach, not detector specifications alone. Companies that link detector technology to workflow efficiency and lifecycle economics are better positioned to sustain margins.
-
Watch for consolidation through capability rather than scale. Partnerships, component acquisitions, and regional service expansion may create more durable advantage than broad headcount or plant expansion.
-
Monitor pricing pressure points and refurbishment demand as indicators of market segmentation. These dynamics can reveal where premium positioning is sustainable and where volume strategies will dominate.
For Procurement Leaders and End-User Organizations
-
Evaluate total cost of ownership rather than sticker price. Detector selection should account for integration effort, service availability, downtime risk, and compatibility with existing systems.
-
Consider phased and lifecycle-aware procurement strategies. As refurbished components and cost-compressed new systems expand options, organizations can balance performance goals with capital constraints without sacrificing operational continuity.
Radiation Detector Market -
Prioritize solutions with clear performance metrics and regulatory readiness. Verified equivalence, documented image metrics, and predictable support reduce implementation risk and improve long-term value capture.
Moving From Direction to Detail
The X-ray detectors market is expanding along a clear trajectory, but the strategic value lies in understanding where growth is most defensible, where pricing and regulatory dynamics will reshape competition, and how technology refinement translates into commercial advantage. Aggregate growth tells part of the story; segment-specific demand, application economics, regulatory timing, and integration depth determine who captures the most value.
Detailed breakdowns of regional dynamics, product-type shifts, application-level demand patterns, and company-level developments can sharpen planning significantly. For teams evaluating market entry, portfolio optimization, investment allocation, or procurement strategy, a comprehensive report with segmented data and customized scenario analysis provides the granularity needed to convert high-level trends into executable decisions. The opportunity is not simply to track where the market is going, but to identify the specific moves that will create durable advantage as detector performance, cost structures, and regulatory expectations continue to evolve.
For detailed analysis of this topic, please visit the official page: X-ray Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cycling Sunglasses Market: How 7.3% CAGR and Polarized Demand Redefine Growth Through 2032
By pmarketresearch, 2026-09-21
Cycling Sunglasses Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global cycling sunglasses market has demonstrated steady expansion over the past five years, evolving from a niche performance accessory into a mainstream category shaped by recreational cycling growth, advanced lens technologies, and heightened awareness of eye protection. Revenue surpassed the $1 billion mark in 2025, reflecting a compound annual growth rate of 7.3 percent across the forecast horizon through 2032. This trajectory signals a mature yet still expanding category, where incremental innovation and brand differentiation increasingly determine competitive outcomes. The market's progression from 2020 to 2025 established a foundation of consistent demand, and the forward curve suggests that growth will remain anchored by volume increases in recreational segments, premiumization in performance lines, and geographic expansion in developing cycling markets.
PW Consulting
Despite the favorable demand environment, the sector faces several structural challenges that warrant careful strategic attention. First, the category is concentrated among a small group of established brands, with the top three players accounting for roughly 45 percent of revenue and the top five capturing approximately 62 percent. This concentration creates a high barrier for new entrants seeking shelf space, retailer relationships, and consumer trust, while simultaneously pressuring incumbents to defend share through continuous product refreshes and margin management. Second, the market is increasingly bifurcated between high-performance polarized offerings and lower-priced alternatives, forcing manufacturers to navigate a narrow path between premium positioning and volume accessibility. Third, regulatory expectations around UV protection and optical safety have become baseline requirements rather than differentiators, compressing the scope for compliance-driven marketing and shifting competitive focus toward performance features, fit engineering, and lens adaptability.
For decision-makers, the implication is clear: growth is attainable, but it will be captured by firms that can balance scale with specificity. The companies that thrive will be those that align product architecture with distinct use cases, invest in lens and frame technologies that deliver measurable riding benefits, and build brand narratives that resonate beyond generic sport aesthetics. The market's next phase will reward strategic clarity over broad participation.
Key Demand Drivers
Technological Innovation in Optics and Frame Engineering
Technological advancement remains the most potent driver of category evolution. Lens technologies that adapt to changing light conditions, reduce glare, and improve contrast are no longer optional features; they are central to product value propositions. Photochromic formulations, polarized treatments, and specialized tint architectures are enabling riders to maintain visual clarity across variable terrain and weather conditions. At the frame level, materials such as bio-based plastics, lightweight composites, and ventilated designs are improving comfort during extended rides while supporting integration with helmets and aggressive riding postures. Recent product introductions illustrate this direction: a major brand launched a cycling model featuring 3D-plane molded lens technology designed to improve seamless frame blending, while another introduced a photochromic variant with enhanced soft-touch finishes tailored for winter cycling conditions. In parallel, limited-edition releases and anniversary editions have demonstrated that brand heritage and design storytelling can coexist with technical innovation, creating differentiated offerings that command attention in a crowded field.
For manufacturers, the strategic question is not whether to invest in optics and materials innovation, but how to prioritize development Roadmaps against cost constraints and time-to-market pressures. The opportunity lies in linking specific technologies to measurable riding benefits—such as reduced eye fatigue, improved contrast on shaded descents, or better ventilation at high speed—and communicating those benefits with precision. Companies that treat lens and frame engineering as a core competency rather than a commodity specification will be better positioned to defend premium pricing and build repeat purchase behavior.
Policy, Regulation, and Safety Expectations
Regulatory norms and safety expectations are reshaping the baseline for product acceptance. UV400 certification has become an expected standard, with market verification efforts confirming that reputable brands meet minimum protection thresholds across tested models. In addition, photochromic functionality and windproof performance are increasingly treated as practical necessities for safe cycling, particularly in conditions where sudden light changes or high-speed airflow can impair vision. These expectations do not merely constrain the market; they raise the floor for quality and push weaker offerings out of contention. The result is a more credible competitive environment in which brand trust is reinforced by demonstrable safety performance rather than marketing claims alone.
From a strategic standpoint, compliance should be viewed as a table-stakes prerequisite that enables broader differentiation. Brands that proactively validate UV protection, lens durability, and environmental resilience can use those verifications as trust signals in retail channels, online content, and cycling community engagement. The risk for complacent players is that safety expectations become a hygiene factor that consumers assume rather than reward, leaving little competitive advantage for those who treat compliance as the endpoint rather than the starting point.
Shifts in Consumer and Enterprise Behavior
Demand-side behavior is evolving as cycling participation broadens beyond elite road racing and specialist mountain biking into commuting, gravel riding, fitness cycling, and trail recreation. This diversification expands the addressable base but also fragments use cases, requiring more nuanced product segmentation. Recreational riders often prioritize comfort, style, and value, while performance-oriented cyclists emphasize optical clarity, helmet compatibility, and environmental protection. At the same time, replacement cycles are influenced by wear, seasonal collection updates, and the desire for newer lens technologies, creating recurring demand beyond the initial purchase. Retail channels are also shifting, with direct-to-consumer engagement, specialty retail partnerships, and content-driven discovery all playing roles in how products reach end users.
For commercial players, the key insight is that one product architecture rarely serves all audiences effectively. Brands that align their portfolios with distinct rider profiles—road, trail, mixed-use, and entry-level recreation—can improve conversion and reduce the risk of cannibalization. Enterprise buyers, including bike retailers and cycling clubs, increasingly seek products that can be merchandised by use case and supported with clear technical explanations, making portfolio clarity a sales enablement tool as much as a product strategy.
Supply Chain and Cost Structure Dynamics
Cost structures and supply chain reliability continue to influence margin trajectories and product planning. Lens manufacturing, frame molding, coating processes, and packaging all carry cost implications that can erode profitability if not managed with discipline. At the same time, volatility in input materials and production capacity can affect launch timing and inventory availability, particularly for brands operating with tight release calendars or limited-edition runs. Companies that strengthen supplier relationships, standardize high-performing components across multiple SKUs, and balance premium materials with cost-efficient configurations are better equipped to protect margins while maintaining product quality.
The commercial opportunity here lies in design-for-manufacturing discipline. When optical performance, frame durability, and fit are engineered with production realities in mind, brands can scale more confidently and respond faster to demand signals. In a market where differentiation is increasingly defined by execution quality, supply chain competence becomes a strategic asset rather than a back-office function.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of established performance eyewear brands and specialized cycling-focused players, each pursuing distinct positioning strategies. Several companies have built reputations around advanced optics and sport-specific designs. One premium brand has emphasized advanced optics and coverage in models tailored for cycling, reinforcing a high-performance identity. Another has leveraged proprietary lens technologies in road and trail models, using color-contrast performance as a core differentiator. A European manufacturer has focused on performance eyewear with bio-plastic frames and designs optimized for cycling helmet integration, while an affordable sport brand has targeted wide field of view and vented lens designs for cycling, running, and trail use. Additional specialized brands have introduced models with 3D-molded lenses and wind protection, photochromic reactiv technologies, curved professional designs, impact protection oriented toward trail and road use, and prescription-ready options with pantoscopic tilt.
These profiles reveal a market where differentiation is increasingly tied to specific performance attributes rather than generic sport branding. The most effective strategies combine optical advantage, functional fit, and clear use-case positioning. Brands that communicate a precise rider benefit—such as improved contrast on variable terrain, better helmet compatibility, or enhanced wind protection—tend to stand out more convincingly than those relying on broad performance claims. Limited editions and anniversary releases further illustrate how scarcity and brand heritage can be used to deepen engagement without diluting core product lines.
The competitive structure is evolving along two parallel paths. On one side, concentration among leading brands supports consolidation pressure, as larger players leverage distribution reach, brand recognition, and portfolio breadth to maintain share. On the other side, specialized entrants and niche brands continue to carve out positions by focusing on affordability, specific riding disciplines, or distinct design philosophies. This dual dynamic suggests a market that is neither fully consolidating nor fully fragmenting, but rather stratifying into premium performance segments, value-oriented categories, and discipline-specific niches. New entrants that succeed will likely do so by solving a particular rider problem exceptionally well rather than by attempting to compete across the entire spectrum.
For observers of the competitive landscape, the strategic signal is that brand architecture matters as much as product architecture. Companies that maintain clear segmentation, avoid unnecessary overlap between models, and reinforce channel-specific value propositions are better placed to protect positioning. Those that blur their lines across price points and use cases risk weakening brand perception and inviting comparison on price rather than value.
Future Trends and Strategic Risks
Over the next three to five years, the cycling sunglasses market is likely to be shaped by several interrelated trends. The first is a continued shift toward adaptive lens technologies that reduce the need for multiple lens swaps and improve convenience across changing conditions. Photochromic and contrast-enhancing solutions are expected to gain prominence as riders seek versatility without sacrificing performance. The second trend is deeper integration between eyewear design and helmet ecosystems, with fit, ventilation, and coverage becoming coordinated considerations rather than isolated product features. This integration will matter increasingly as cyclists choose gear as a system rather than as standalone accessories. The third trend is broader geographic expansion in developing cycling markets, where participation growth and rising disposable incomes can create new volume opportunities, even as localized preferences and pricing sensitivity require tailored go-to-market approaches.
Bicycle Riding Glasses Market
These trends open commercial opportunities for brands that can translate technical features into everyday riding advantages. Adaptive lenses can support premium positioning if they are framed around convenience and visual consistency. Helmet-compatible engineering can become a selling point for performance segments where fit and aerodynamics matter. Geographic expansion can be pursued through selective channel partnerships and region-specific product configurations rather than blanket global launches. In each case, the opportunity depends on disciplined positioning and a clear link between feature investment and user benefit.
At the same time, several risks merit attention. Commodity pressure on lens coatings and frame materials could compress margins, especially for brands competing on price without strong brand equity. Regulatory expectations may continue to rise, requiring ongoing verification and testing investments that smaller players may struggle to absorb. Demand fragmentation could increase inventory complexity, making it harder to balance breadth of assortment with operational efficiency. Finally, fashion and style influences may intensify competition from adjacent sport and lifestyle eyewear categories, drawing consumer attention away from specialized cycling features. Companies that monitor these risks early and build flexibility into product planning will be better prepared to respond without sacrificing strategic direction.
Sunglasses Market
Action Guidance for Decision-Makers
Manufacturers should prioritize portfolio clarity and technology-to-benefit alignment. Rather than expanding SKU counts indiscriminately, the more effective approach is to consolidate around well-defined rider segments and ensure each product carries a distinguishable performance advantage. Development resources should be directed toward lens and frame attributes that riders can perceive directly, and go-to-market messaging should explain those advantages in practical terms. Supply chain resilience and manufacturing efficiency should be treated as strategic levers, particularly for brands that intend to scale premium offerings without sacrificing margin integrity.
Investors should evaluate category participants based on the durability of their differentiation rather than short-term launch activity. Brands with proprietary optical technologies, credible safety validation, and clear segment focus are better positioned to sustain pricing power and repeat demand. It is also worth assessing whether a company's distribution strategy matches its product strategy, since strong products can underperform if channel alignment is weak. In a growing but concentrated market, the most compelling opportunities often sit with companies that can defend a specific niche while building enough operational scale to manage cost and launch cadence effectively.
Retailers and procurement teams should focus on assortment design that simplifies choice for end users while preserving performance credibility. Grouping products by riding context, explaining lens and frame benefits in plain language, and selecting brands with verifiable protection standards can improve both conversion and post-purchase satisfaction. Procurement decisions should account for replacement demand and seasonal variation, ensuring inventory is aligned with the rhythm of product refreshes and regional riding cycles. In practice, the strongest assortment strategies combine trusted performance anchors with accessible entry options, allowing customers to move up or down based on need rather than forcing a single price-tier decision.
For stakeholders seeking a more detailed view of segmentation, regional dynamics, and competitive benchmarks, a comprehensive research report can provide the granularity needed to translate these strategic themes into operational plans. Detailed breakdowns of product types, application contexts, regional revenue distributions, and recent product releases can support sharper forecasting, portfolio decisions, and channel planning. In a market where execution is increasingly differentiated by specificity, access to structured intelligence can help turn broad trends into targeted action.
For detailed analysis of this topic, please visit the official page: Cycling Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Audio Interfaces Market: 6.08% CAGR and Strategic Shifts Reshaping 2026–2032
By pmarketresearch, 2026-09-21
Audio Interfaces Market: Strategic Trends and Commercial Opportunities (2026–2032)
The audio interfaces market has transitioned from a peripheral accessory category to a strategic infrastructure segment within the broader professional and prosumer audio ecosystem. Over the past five years, the market has demonstrated consistent expansion, with total revenue climbing from approximately $138.0 million in 2020 to $229.95 million in 2025. The forward trajectory remains robust, with projected growth from $244.9 million in 2026 to $348.87 million by 2032, reflecting a compound annual growth rate of 6.08 percent. This expansion is not merely a function of incremental adoption; it signals a structural shift in how creators, broadcasters, educators, and enterprises capture, process, and distribute high-fidelity audio. As digital content production becomes more decentralized and quality expectations rise, audio interfaces have emerged as critical nodes in the signal chain, influencing everything from latency performance to workflow integration and downstream monetization.
Despite the favorable growth profile, the market is navigating a set of structural inflection points that demand strategic recalibration. First, the interface between hardware performance and software ecosystem compatibility has become a decisive purchasing criterion. Buyers increasingly evaluate latency consistency, driver stability, and integration with digital audio workstations, cloud collaboration platforms, and hardware DSP architectures rather than isolating analog-to-digital converter specifications in isolation. Second, pricing pressure from component inflation and logistics volatility is compressing margins for mid-tier manufacturers, forcing a sharper focus on portfolio segmentation, bundled software value, and lifecycle support models. Third, the competitive landscape is maturing into a differentiated arena where engineering pedigree, connectivity standards, and channel-count flexibility define premium positioning, while cost-efficient, feature-focused designs target the expanding home and project-studio segments. These dynamics create both friction and opportunity, rewarding companies that can balance technical credibility with ecosystem breadth and cost discipline.
Key Drivers of Market Expansion
Technological Innovation and Real-Time Processing Architecture
The market’s momentum is heavily influenced by advances in converter design, clocking precision, and low-latency connectivity pathways. Recent product iterations from leading manufacturers demonstrate a clear emphasis on high dynamic range preamplification, transparent signal paths, and integrated digital processing options that reduce reliance on external outboard gear. For example, the release of the Digiface AES 14x16 USB interface in February 2026 highlights how bus-powered designs with extensive digital I/O are becoming central to multi-channel studio configurations where rack space, power delivery, and signal routing efficiency matter as much as raw fidelity. At the same time, updates to popular USB-based studio lines now emphasize preamp clarity and enhanced dynamic range, indicating that even entry-to-mid-tier devices are being engineered to a higher performance baseline to remain competitive.
Beyond hardware improvements, the convergence of interface design with software ecosystems is reshaping value creation. Manufacturers that embed native plugin integration, console-grade routing paradigms, and high-resolution conversion architectures are extending the functional role of the interface from simple signal conversion to an integrated hub for mixing, monitoring, and processing. This trend is particularly visible in professional Thunderbolt-oriented lines that combine fast connectivity with high-resolution converters, enabling studios to maintain tighter control over signal integrity while leveraging host-based or hardware DSP workflows. The practical implication is that technological leadership is increasingly defined by integration rather than isolated specifications.
Regulatory and Geopolitical Pressures on Component Sourcing
Regulatory dynamics are exerting meaningful influence on product economics and supply continuity. Trade restrictions affecting semiconductor components, including those used in digital-to-analog and analog-to-digital conversion and digital signal processing, have introduced upward pressure on sourcing costs for key electronic parts. These constraints ripple through the value chain, affecting bill-of-materials planning and forcing manufacturers to make earlier design decisions around component substitution, alternate sourcing, and buffer inventory strategies. The impact is not uniform across the market; premium and high-throughput designs with specialized chip requirements are more exposed to supply contention than standardized connectivity-led products.
Sustainability regulation is also becoming a design constraint rather than a marketing consideration. Regulatory frameworks aligned with environmental and circular-economy objectives are pushing manufacturers toward eco-friendly design practices and recyclable material usage, particularly in chassis construction, packaging, and internal component lifecycle planning. In parallel, export controls and rare earth export restrictions have broadened the scope of supply risk by affecting materials and memory-related components that intersect with electronics production. For audio interface producers, the operational message is clear: long-term competitiveness will depend on navigating procurement diversification, compliance readiness, and product architecture choices that reduce exposure to concentrated sourcing pathways.
Demand-Side Shifts in Content Production and Professional Workflows
The demand picture is being reshaped by the expansion of professional content creation beyond traditional studio environments. Remote collaboration, location-based recording, live streaming, serialized podcast production, and hybrid event broadcasting have increased the need for interfaces that combine portability, channel density, and robust connectivity. Professional-grade applications continue to anchor a significant share of revenue, but the broader application landscape is growing as project studios, educational institutions, and enterprise media teams standardize on equipment that supports repeatable, high-quality capture workflows. This demand broadening is not simply about volume; it is about workflow flexibility, where multi-channel I/O, digital expansion options, and class-compliant operation can determine whether a device fits into a given production environment.
At the same time, end-user expectations are maturing. Buyers are less willing to accept trade-offs in preamp transparency, driver stability, or expandability when those limitations disrupt a production pipeline. This has accelerated interest in interfaces that offer console-grade input characteristics, structured insert paths, and high channel counts, especially in environments where multiple sources must be captured simultaneously without compromising signal quality. The commercial result is a market in which product credibility is increasingly tied to real-world workflow reliability rather than spec-sheet visibility alone.
Supply Chain and Cost Structure Dynamics
Component price volatility across integrated circuits, metal chassis materials, and logistics channels is reshaping cost structures for original equipment production. This pressure is especially relevant for manufacturers balancing premium feature sets with competitive pricing. In practice, companies are responding by rethinking product architecture: consolidating features into higher-value tiers, refining SKU breadth to manage inventory risk, and aligning product roadmaps with connectivity trends that reduce reliance on cost-sensitive legacy pathways. These adjustments are not purely defensive; they influence product positioning, time-to-market strategy, and the ability to sustain margin health through cycles of input-cost variation. The market is gradually moving toward designs that optimize for both performance and manufacturability, with supply chain resilience becoming a strategic differentiator rather than an operational afterthought.
Competitive Landscape and Leading Strategies
Differentiation Through Engineering Heritage and Ecosystem Alignment
The competitive field is defined by manufacturers that have anchored their positions in distinct value propositions. Focusrite has built a strong commercial presence through widely adopted USB-based studio lines, most notably the Scarlett series with fourth-generation updates that emphasize high dynamic range preamps and Clarity+ options for professional recording. This strategy blends accessibility with a recognizable performance baseline, making the portfolio a frequent reference point in education, project studios, and entry-level professional setups. Universal Audio has pursued a more DSP-centric model by pairing Thunderbolt interfaces such as the Apollo X | Gen 2 series with integrated UAD plugin workflows and high-resolution converters, effectively positioning the interface as part of a broader processing environment for professional studios.
RME has carved out a reputation for reliability and channel flexibility, with Fireface and Digiface USB lines including the AES model that supports high channel counts and class-compliant operation. This positioning appeals to facilities and advanced users who prioritize stable drivers, extensive digital expansion, and predictable performance under demanding routing conditions. Audient has focused on console-grade preamp character through its iD series, with the iD48 interface reflecting an emphasis on eight console preamps and DB25 inserts for professional recording, reinforcing a heritage-driven value proposition centered on analog quality and structured signal handling. PreSonus, through its Quantum and Studio series, has targeted multi-channel recording use cases with Thunderbolt support and high channel counts, while Solid State Logic has extended its console lineage into rackmount interfaces such as the SSL 18, which brings advanced preamp technology and eight console-grade mic/line inputs into a format designed for professional signal management.
Additional specialist players contribute to the market’s breadth. Apogee Electronics has maintained a presence in high-end FireWire and Thunderbolt interfaces, with Crystal preset technology associated with superior audio quality in demanding recording contexts. MOTU has offered flexible high input/output configurations through the 8pre and UltraLite series with Thunderbolt connectivity, while Antelope Audio’s Orion and Verge series combine ADAT and Thunderbolt pathways for professional multi-channel applications. TASCAM continues to broaden its professional audio interface footprint with models like the Model 24, which emphasize robust connectivity options and practical studio integration. Collectively, these companies illustrate a market where differentiation is achieved through a combination of connectivity architecture, preamp and converter philosophy, channel scalability, and software ecosystem alignment.
Strategic Positioning and Evolution of the Market Structure
The market concentration pattern suggests a moderately fragmented landscape, with a concentrated upper tier and a broad long tail of specialized and regional participants. A leading group of manufacturers accounts for a meaningful share of revenue, but the remaining share is distributed across brands with distinct audience segments, feature emphases, and geographic reach. This structure is evolving through two complementary forces. On one side, consolidation and partnership activity are likely to increase as larger players expand portfolios, acquire capabilities in DSP integration, or strengthen distribution and software ecosystems. On the other side, differentiation remains viable because audio interface adoption spans diverse environments, from mobile recording and broadcast to multi-room facilities and hybrid enterprise media operations.
Worldwide Sound Cards Market
New entrants and expanding incumbents are increasingly competing on workflow completeness rather than hardware alone. Interfaces that offer stable drivers, predictable latency, digital expansion compatibility, and strong integration with popular production software are gaining traction because they reduce friction across the entire recording and post-production pipeline. Meanwhile, premium manufacturers are reinforcing their advantage through converter transparency, preamp character, and high channel-count flexibility, while value-oriented players continue to address the growing home and project-studio base with streamlined feature sets and accessible pricing. The net effect is a market that is both consolidating at the top and remaining functionally segmented by use case and budget.
PW Consulting
Forward Outlook: Three Signals to Watch (2026–2032)
Connectivity and Ecosystem-Centric Interfaces Will Define Premium Demand
Over the next several years, interfaces that combine high-throughput connectivity, stable driver behavior, and meaningful software integration are likely to capture disproportionate attention in professional and advanced prosumer settings. USB and Thunderbolt pathways will continue to dominate based on current demand patterns, but the strategic battleground will be how effectively an interface fits into broader production workflows, including DSP offload, plugin ecosystems, digital expansion, and multi-location collaboration. Commercial opportunity lies in building product lines that are not only technically competent but also interoperable with the software and operational conventions that shape real-world usage. The risk is that features become decoupled from actual workflow needs, resulting in specifications that do not translate into adoption or customer retention.
Sustainability, Supply Diversification, and Component Strategy Will Become Competitive Advantages
Regulatory alignment and sourcing resilience are moving from compliance concerns to strategic assets. Manufacturers that proactively manage eco-friendly design requirements, recyclable materials, and component-diversification strategies will be better positioned to sustain product rollouts and margin stability. This is particularly important given ongoing exposure to semiconductor-related trade constraints, rare earth export controls affecting additional elements, and volatility in integrated circuits and logistics costs. The upside is that companies with disciplined sourcing and design-for-manufacturing approaches can improve predictability and reduce launch risk. The uncertainty is that regulatory and geopolitical conditions can shift quickly, making multi-region sourcing and component substitution strategies essential rather than optional.
Channel Density, Expandability, and Workflow Reliability Will Shape the Next Wave of Adoption
As professional and hybrid content production becomes more distributed, demand for interfaces that support simultaneous multi-source capture and clean signal routing will continue to rise. Products that offer scalable channel counts, digital I/O flexibility, and robust insertion and monitoring architectures are likely to see sustained interest among studios, broadcasters, and enterprise content teams. At the same time, the home studio segment will keep expanding, creating a dual-track market in which premium multi-channel solutions and accessible entry designs both have viable commercial paths. The opportunity is in clearly mapping product tiers to distinct workflow requirements so that pricing, feature sets, and support models align with user expectations. The risk is fragmentation without focus, where broad SKU lists dilute engineering attention and complicate supply management.
Actionable Guidance for Decision-Makers
For manufacturers, the strategic priority is to balance engineering credibility with ecosystem integration and supply resilience. Product roadmaps should account for connectivity pathways that reflect actual workflow demand, while also ensuring that preamp and converter quality, driver stability, and digital expansion options support long-term user retention. Equally important is designing for manufacturability and sourcing flexibility, especially where semiconductor constraints and component price volatility can affect cost structures. A disciplined approach to SKU breadth and tiered feature sets can help protect margins while preserving pathways to both premium and volume-oriented segments.
For investors, the market offers a plausible growth trajectory, but value creation will depend on company-level execution rather than category momentum alone. Assessment should focus on differentiation durability, software and DSP integration potential, distribution strength, and exposure to component and regulatory risk. Companies that can demonstrate consistent product cadence, meaningful ecosystem alignment, and proactive supply strategy are better positioned to convert market growth into sustained revenue and margin stability. Due diligence should also consider the ability to navigate regulatory shifts tied to environmental requirements and semiconductor-related trade constraints, since these factors increasingly influence production economics.
For procurement and strategic buyers, the evaluation framework should extend beyond headline specifications to include workflow compatibility, driver reliability, expandability, and long-term support. In professional environments, total cost of ownership is shaped not only by purchase price but also by integration effort, channel scalability, and the likelihood of future expansion. Given ongoing volatility in sourcing and regulatory conditions, it is advisable to verify supply continuity commitments, component strategies, and lifecycle support where possible. More detailed segmentation data, regional dynamics, and company-specific assessments can further inform purchasing and planning decisions, and may be accessed through the full PW Consulting research report for those seeking deeper granularity and tailored recommendations.
Worldwide Music Production Equipment Market
For detailed analysis of this topic, please visit the official page: Audio Interfaces Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Furfural Market 2026: Beyond the 5.6% CAGR Story, What's Really Driving Growth to $844.2M
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Furfural Market Through 2032
The furfural market is entering a period of structural expansion, driven by the convergence of bio-based material demand, regional feedstock advantages, and evolving downstream applications. From a base of approximately 580.0 million USD in 2025, the market is projected to reach 844.2 million USD by 2032, reflecting a compound annual growth rate of 5.6 percent. The trajectory since 2020 shows a consistent upward path, with revenue climbing from 420.5 million USD to 561.5 million USD by 2024, before settling into the current baseline. This growth is not merely cyclical; it reflects deeper shifts in how industrial resins, solvents, and chemical intermediates are sourced, formulated, and integrated into broader sustainability strategies. For executives and investors, the question is no longer whether the market is expanding, but where value will concentrate and which strategic moves will capture it.
PW Consulting
Mapping the Current Landscape
The market’s structure reveals several defining characteristics. Asia Pacific accounts for the largest revenue share, reflecting both production scale and proximity to key agricultural feedstocks. North America and Europe follow as substantial markets, each with distinct demand profiles shaped by industrial manufacturing practices and regulatory expectations. Latin America and the Middle East and Africa round out the geographic footprint, contributing smaller but strategically important volumes tied to regional biomass availability and niche applications. In terms of product types, furfuryl alcohol dominates the revenue composition, underlining its central role in foundry resins and specialty chemical pathways. Solvents and chemical intermediates represent smaller but increasingly relevant segments, particularly as downstream formulators seek bio-derived alternatives with tailored performance characteristics. By application, foundry resins remain the primary demand driver, while refineries and a broader set of industrial uses provide additional volume and diversification. The industry’s competitive structure is moderately concentrated, with the top five players capturing roughly 38 percent of total revenue and the top three holding about 32 percent. This level of concentration suggests room for differentiated positioning while also indicating that scale, feedstock access, and product specialization will continue to matter.
Critical Challenges and Inflection Points
Despite the positive growth arc, the market faces several challenges that will shape competitive outcomes over the next few years.
-
Raw material dependency and feedstock volatility remain central concerns. Corn cob currently represents the dominant feedstock, driven by its high pentosane content and comparatively efficient processing economics. Yet reliance on a single feedstock category introduces exposure to agricultural cycles, regional supply disruptions, and shifting crop economics. Suppliers that can diversify feedstock streams without compromising yield or cost structure will be better positioned to manage volatility.
-
Product differentiation and quality consistency are becoming more demanding as downstream users integrate furfural-derived materials into higher-value applications. The launch of a new high-purity furfural grade for bio-polymer synthesis and advanced resin applications, with improved color stability, signals that performance thresholds are rising. Formulators and end-users increasingly expect not only bio-based content but also predictable handling, stability, and compatibility across complex resin and solvent systems.
-
Capacity expansion and integration decisions are creating both opportunity and execution risk. Investments aimed at expanding production capacity, particularly where biomass processing is integrated into existing mills or agricultural operations, can unlock scale advantages. However, these projects require careful alignment of feedstock logistics, capital deployment, and downstream offtake. Misaligned expansion can lead to utilization gaps or margin pressure, especially in a market where regional feedstock abundance does not automatically translate into competitive cost leadership.
Key Drivers Shaping Market Direction
Technological Innovation and Process Breakthroughs
Advancements in biomass conversion and product purification are reshaping what furfural can deliver. The development of high-purity grades tailored for bio-polymer synthesis and advanced resin applications demonstrates how incremental improvements in color stability and consistency can open new use cases. At the same time, feedstocks such as sugarcane bagasse are expected to grow faster than other input categories, with a projected CAGR of 7.2 percent, supported by abundance in sugar-producing regions. This shift matters because feedstock choice influences not only cost but also the narrative around sustainability, supply security, and regional competitiveness. Producers that can convert diverse agricultural residues into reliable, high-quality output while maintaining cost discipline are likely to gain an edge in both traditional and emerging applications.
Policy and Regulatory Environment
Regulatory and policy dynamics are increasingly influential in shaping demand and investment priorities. Bio-based content expectations, industrial emissions considerations, and broader sustainability targets are nudging formulators and manufacturers toward renewable feedstock alternatives. While furfural has long been used in foundry resins and solvents, the regulatory backdrop is helping reframe it as part of a wider shift toward bio-derived chemical inputs. This does not automatically guarantee demand growth, but it does create a more favorable context for applications where bio-based positioning aligns with compliance goals, customer preferences, and corporate sustainability commitments. The practical effect is a market where regulatory signals reinforce product development priorities and encourage investment in grades that meet evolving performance and traceability expectations.
Demand-Side Shifts in Consumer and Enterprise Behavior
Downstream demand is evolving as enterprises seek materials that fit both performance and sustainability criteria. Foundry resins continue to anchor demand, but there is growing interest in solvent and intermediate applications where bio-based attributes can differentiate offerings in competitive procurement environments. In parallel, advanced resin and bio-polymer pathways are drawing attention from formulators who value color stability, purity, and consistent handling characteristics. This demand-side evolution is not a sudden replacement of conventional materials; rather, it is a gradual migration in specific applications where bio-derived inputs can deliver comparable performance while supporting broader environmental and branding objectives. Companies that understand which applications are most sensitive to these shifts can prioritize product grades and commercial messaging accordingly.
Supply Chain and Cost Structure Dynamics
Cost competitiveness in furfural production is closely tied to feedstock logistics, regional biomass availability, and integration with existing agricultural or processing operations. Feedstock advantages are often regional rather than universal, which means that producers with access to reliable, low-cost biomass streams can achieve meaningful margin resilience. At the same time, supply chain design matters increasingly for quality consistency and delivery reliability. Investments that connect feedstock sourcing, conversion capacity, and downstream distribution in a coherent way can reduce exposure to price swings and improve customer confidence. Conversely, fragmented supply chains or overreliance on a single input source can undermine cost stability and limit flexibility when market conditions change.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of integrated agricultural processors, specialty producers, and regional exporters, each with a distinct strategic posture.
-
Central Romana Corporation operates from the Dominican Republic with a focus on furfural and furfuryl alcohol production derived from sugarcane bagasse within integrated sugar operations. This model highlights the value of linking furfural production to an existing agricultural and processing ecosystem, which can improve feedstock reliability and operational efficiency.
-
Illovo Sugar Africa has built a presence in South Africa by producing furfural from sugarcane bagasse and maize residues, with capacity expansion planned at its Saiccor Mill. The company’s approach underscores how regional sugar and residue streams can support scalable production, especially where mill integration reduces feedstock handling costs.
-
Pennakem LLC operates in the United States, manufacturing furfural from agricultural residues for foundry resins, solvents, and chemical intermediates. Its positioning reflects a broad downstream orientation, which can help balance demand fluctuations across application areas.
-
Silvateam S.p.A. in Italy emphasizes bio-based furfural and furfuryl alcohol derivatives with a focus on high-quality biomass-derived products. This quality-oriented stance is well suited to customers seeking consistent performance and a clear bio-based value proposition.
-
Trans Furans Chemicals bvba, based in Belgium, specializes in furfural and derivatives, including a newer high-purity grade designed for bio-polymers. Its product development signal illustrates how specialty grades can create differentiation in applications where color stability and purity are decision factors.
-
KRBL Ltd in India produces furfural from rice husk within integrated rice milling operations. This feedstock strategy leverages an agricultural byproduct stream that can offer cost and availability advantages in regions with strong rice processing infrastructure.
-
Hongye Holding Group Corporation Ltd is a major Chinese producer and exporter with integrated biomass processing and a broad distribution network. Scale, export reach, and integrated operations can support competitive positioning in both domestic and international markets.
-
Lenzing AG, based in Austria, supplies furfural-based specialty chemicals, including inputs for dissolving pulp and bio-based materials. Its role shows how furfural can intersect with higher-value fiber and material pathways, broadening the application context beyond traditional industrial uses.
Collectively, these players illustrate a market where strategic positioning is shaped by feedstock access, product specialization, and downstream alignment. Some competitors rely on integration with sugar or rice operations to secure feedstock and reduce cost exposure. Others pursue product differentiation through higher-purity grades or specialty derivatives that meet specific application requirements. The trend appears to be moving toward a blend of consolidation among scale-advantaged producers and fragmentation among niche specialists targeting performance-sensitive applications. New entrants and expanding producers are likely to focus on either regional feedstock advantages or product grades that address emerging bio-polymer and advanced resin needs. In this environment, the most resilient strategies will combine reliable feedstock economics with clear product differentiation and strong customer-specific application support.
Future Trends and Strategic Implications
Trend Toward Feedstock Diversification and Regional Advantage
Over the next three to five years, feedstock strategy will become an increasingly visible competitive factor. While corn cob remains dominant, the faster growth projected for sugarcane bagasse indicates that regional biomass abundance will matter more as producers seek cost resilience and supply stability. This trend creates opportunities for operations located near sugar-producing or residue-rich agricultural zones, especially where integration with existing mills or processing facilities can lower handling and conversion costs. At the same time, it raises the importance of logistics, seasonality planning, and feedstock flexibility. Companies that treat feedstock strategy as a core competitive lever rather than an operational detail will be better equipped to sustain margins through agricultural and market cycles.
Expansion of High-Purity and Specialty Grade Applications
A second trend is the gradual extension of furfural into more performance-sensitive applications. The introduction of high-purity grades for bio-polymer synthesis and advanced resin applications points to a broader shift in which bio-based inputs are expected to meet tighter specifications for color stability, consistency, and compatibility. As these grades gain traction, they can open revenue streams beyond the largest traditional applications, particularly where formulators value differentiated material properties. The commercial implication is that product development and quality assurance will become more important profit drivers, not just volume plays. Suppliers that can reliably deliver specialty grades with documented performance benefits may be able to command stronger positioning in procurement discussions and expand into higher-value customer segments.
Methylal Market
Integration of Sustainability Expectations into Procurement Decisions
A third trend is the deepening integration of sustainability considerations into industrial procurement. Even where performance remains the primary decision factor, bio-based content and supply chain transparency are increasingly part of the evaluation framework. This does not replace cost or quality as decision criteria, but it adds a layer that can influence supplier selection, especially in applications where corporate sustainability goals or customer expectations are active. The opportunity lies in aligning product communication, traceability, and application support with the way buyers now evaluate materials. The uncertainty is that sustainability preferences can vary significantly by region, industry, and procurement culture, so broad claims may be less effective than application-specific value propositions backed by consistent product quality.
Decision-Maker Playbook
For manufacturers, the priority is to connect feedstock strategy, product quality, and application focus in a way that supports both cost resilience and differentiation. Diversifying feedstock exposure where feasible, investing in grades that meet higher purity or stability expectations, and aligning product portfolios with the applications most likely to adopt bio-based inputs can improve competitive positioning. Manufacturers should also assess whether integration with existing agricultural or processing operations can reduce feedstock risk and improve economics without overextending capital or operational complexity.
For investors, the opportunity is to distinguish between volume-driven growth and value-driven growth. Capacity expansion can be attractive, but returns will depend on feedstock advantage, utilization discipline, and access to applications that reward quality and specialization. Investor scrutiny should extend beyond headline capacity figures to include feedstock mix, regional supply dynamics, product grade strategy, and the strength of downstream customer relationships. Projects that combine regional biomass access with clear differentiation in higher-value applications are more likely to deliver durable competitive advantage.
For procurement and supply chain leaders, the focus should be on evaluating suppliers not only on price but also on consistency, grade suitability, and the ability to support application-specific requirements. As higher-purity and specialty grades become more relevant, procurement decisions may need to balance conventional cost optimization with performance reliability and bio-based alignment. Building supplier partnerships that provide transparency on feedstock sources, product specifications, and quality consistency can reduce procurement risk while supporting broader sustainability objectives.
5-hydroxymethylfurfural (5-HMF) (CAS 67-47-0) Market
The furfural market is moving through a phase where growth is increasingly tied to feedstock economics, product specialization, and the way sustainability expectations are embedded into industrial procurement. Companies that treat these forces as interconnected rather than separate issues will be better prepared to capture value as the market expands toward 2032. Detailed segmentation data, regional nuance, and application-level forecasts can sharpen these decisions further, and the full research report provides that level of granularity for teams seeking a more precise basis for strategy and investment planning.
For detailed analysis of this topic, please visit the official page: Furfural Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Reclosable Fasteners Market: Why 6.98% CAGR Reshapes Strategy Through 2032
By pmarketresearch, 2026-09-21
The Strategic Trajectory of the Reclosable Fasteners Market: Navigating Growth from 2026 to 2032
1. Market Landscape and Core Challenges
The global market for reclosable fasteners has matured into a structured growth corridor, with revenue expanding from approximately $163 million in 2020 to an estimated $215 million in 2025. Over the historical period, the segment demonstrated steady recovery and accelerated adoption across technical and consumer-facing applications. Looking ahead through 2032, the trajectory points toward sustained expansion, with the market projected to reach roughly $345 million. This forward path implies a compound annual growth rate of 6.98 percent, a pace that outstrips broad industrial averages and signals deepening integration into high-value supply chains. The growth is not uniform across all channels; rather, it reflects a rebalancing toward applications where functional reliability, repeated engagement cycles, and material performance carry direct operational or safety implications.
Several structural challenges now sit at the center of the market’s evolution. First, raw material volatility has become a persistent margin pressure. Polypropylene resin costs fluctuate in tandem with crude oil and natural gas feedstock pricing, making cost forecasting difficult for converters and OEMs that operate on fixed-margin contracts. Nylon continues to dominate material usage in hook and loop fasteners, capturing roughly 42.7 percent of material consumption due to its strength and temperature resistance, but its price sensitivity and processing complexity introduce variability for manufacturers seeking consistent unit economics. Second, performance thresholds are rising. High cycle life requirements up to 10,000 openings are increasingly standard for automotive and medical reclosable fasteners, pushing suppliers to redesign engagement systems, optimize molding and cutting tolerances, and validate durability under repeated stress. Third, regulatory and certification demands are reshaping qualification pathways. Fire-retardant and UV-resistant formulations are now required for hook and loop fasteners in aerospace and transportation applications, while medical and hygiene segments impose their own biocompatibility, cleanability, and traceability expectations. These requirements lengthen development timelines and raise the barrier for new entrants, but they also create defensible positioning for suppliers that can demonstrate verified compliance.
2. Core Drivers of Market Change
Technical Innovation and Form-Factor Evolution
Innovation in reclosable fasteners is shifting from incremental material swaps to purpose-built engagement architectures. Mushroom-shaped stems, side-release mechanisms, and hook-to-hook closures are being engineered for specific engagement forces, peel angles, and environmental exposures rather than generic attachment. At recent industry gatherings, APLIX S.A. showcased an Easylock hook-to-hook reclosable closure designed for flexible packaging, signaling a move toward closures that can be operated quickly, resealed cleanly, and integrated into automated packaging lines. The same company introduced SoftGrip Signature side tape and a SoftGrip Cross Over hook for diapers, reflecting a broader push to balance tactile comfort, retention strength, and manufacturability in hygiene applications. These developments illustrate a transition in which fasteners are treated less as commodity attachment components and more as engineered interfaces that influence product usability, assembly speed, and end-user perception.
Policy and Regulatory Pressure as a Design Constraint
Regulatory expectations are no longer a downstream compliance burden; they are increasingly a front-end design constraint. In transportation and aerospace, fire-retardant and UV-resistant formulations are mandatory for many fastener applications, which narrows the field of acceptable material systems and rewards suppliers with established testing protocols and documentation. In medical and hygiene environments, requirements around cycle durability, cleanability, and material consistency raise the bar for qualification. The practical effect is a segmentation of the market by trust and verification. Suppliers that can provide repeatable performance data, material certifications, and application-specific validation reduce friction for OEMs navigating complex approval processes. This dynamic strengthens incumbents with established qualification libraries while creating entry points for specialists that can move faster in niche regulatory niches.
Demand-Side Shifts in End-Use Behavior
End-user and OEM behavior is changing in ways that favor reclosable solutions over fixed fastening where serviceability, modularity, and reusability matter. In footwear and apparel, comfort, adjustability, and repairability are gaining weight as product cycles lengthen and circularity expectations rise. In transportation, modular interior components and cable management systems increasingly rely on fasteners that can be engaged and disengaged repeatedly during assembly, maintenance, and reconfiguration. Industrial manufacturing continues to adopt reclosable fasteners for temporary fixtures, jigs, and reusable protective covers where quick changeover reduces downtime. Medical and hygiene applications drive demand for closures that maintain seal integrity while supporting frequent handling and controlled opening. These demand shifts create a broader acceptance floor for reclosable fasteners, particularly where repeated engagement delivers measurable operational benefits rather than purely aesthetic value.
Supply Chain and Cost Structure Realignment
Supply chain dynamics are reshaping how manufacturers think about sourcing, conversion, and localization. Material availability, resin pricing, and processing capacity all feed into total cost of ownership, and volatility in polypropylene feedstock pricing keeps cost planning under pressure. At the same time, lead-time reliability and specification consistency have become as important as unit price for OEM buyers, particularly in transportation and medical segments where qualification cycles are long and substitution is costly. The result is a growing emphasis on supplier partnerships that offer not only competitive pricing but also predictable delivery, validated material grades, and the ability to support custom die-cutting, adhesive backing, and molded configurations. Cost structure discussions are increasingly framed around resilience and qualification risk rather than headline price alone.
3. Competitive Landscape and Leading Strategies
The market remains moderately fragmented, with the top three participants holding about 24.6 percent of revenue and the top five reaching approximately 26.2 percent. This concentration pattern indicates that scale alone does not dominate the segment; instead, differentiation comes from application expertise, material engineering, and the ability to serve demanding certification regimes. Incumbents are using product breadth, cycle-life validation, and specialty formulations to defend share, while smaller converters and regional specialists compete by serving specific end markets, offering rapid customization, or focusing on niche performance needs such as high-temperature resistance or fire-retardant tape systems.
PW Consulting
3M Company anchors part of the market with Dual Lock reclosable fasteners and hook and loop offerings that rely on mushroom-shaped stems for blind attachment, paired with high cycle life and pressure-sensitive adhesive options. The strategic emphasis here is on engagement reliability and versatile integration, allowing the portfolio to reach into contexts where adhesive backing and repeatable locking are both important. Velcro Companies B.V. provides ALFA-LOK and standard hook and loop reclosable fasteners for automotive, medical, and industrial uses, leaning into brand recognition and established application credentials. APLIX S.A. produces textile, plastic, and molded hook and loop tapes with options for high cycle life, fire retardancy, and UV resistance, extending into automotive, aircraft, and packaging applications; the company’s recent exhibit presence and product introductions underscore an intent to broaden closure formats for packaging and hygiene use cases. Halco USA manufactures and converts specialty hook and loop reclosable fasteners, including mushroom-cap systems, with a focus on transportation and industrial OEMs. Hook and Loop Technology GmbH supplies high-temperature and fire-retardant systems and tapes for aerospace and industrial use, effectively positioning around harsh-environment performance. kragoTEC GmbH develops self-adhesive and custom hook and loop tapes and fasteners for technical textiles and industrial applications, emphasizing tailored configurations where standard products fall short.
Across these players, several strategic patterns stand out. Asset-rich entrants compete on engineering breadth, documented durability, and the ability to offer adhesives, molded options, and specialty coatings. Application-focused specialists compete on speed to specification, regional service, and deep knowledge of a single segment’s qualification path. Meanwhile, the rise of new closure formats and packaging-oriented reclosable solutions is broadening the competitive field beyond traditional hook and loop dynamics. The market is evolving through a combination of consolidation pressure among converters seeking scale in qualification and conversion, alongside fragmentation at the application level where specialized performance requirements reward focused expertise. New entrants tend to succeed when they solve a specific reliability, comfort, or compliance problem rather than trying to displace incumbents on price in commodity-grade volume.
What the Competitive Pattern Means for Buyers and Suppliers
For buyers, the practical takeaway is that supplier selection is increasingly a risk-management decision. Proven cycle-life data, fire-retardant or UV-resistant validation where required, and reliable conversion capability often matter more than minor price differences, because qualification and field performance carry long-term implications. For suppliers, the winning posture combines a credible performance narrative with the operational discipline to deliver consistent material grades and custom formats at scale. The most resilient players are those that can move quickly from a market need—such as a lighter closure for packaging or a high-cycle medical-grade fastener—to validated production without sacrificing repeatability.
4. Forward Outlook: Trends Shaping the Next 3 to 5 Years
The market’s next phase will likely be defined by tighter alignment between fastener performance and application economics, more explicit sustainability and material traceability expectations, and continued diversification of closure formats beyond conventional hook and loop. Three trends are particularly important.
- Performance-led specification replaces generic sourcing. As cycle-life expectations climb and regulatory requirements tighten, buyers will increasingly specify fasteners by validated performance attributes rather than by broad product families. This shift favors suppliers that can document opening cycles, engagement force ranges, environmental resistance, and adhesive behavior in application-specific terms. The commercial opportunity lies in helping OEMs translate performance requirements into fastener architectures that also reduce assembly time or improve serviceability.
- Material strategy becomes a competitive lever. With nylon maintaining a large share of material usage and polypropylene costs tied to feedstock volatility, companies that can blend performance with cost predictability will gain margin advantage. Expect continued experimentation with blends, surface treatments, and additive strategies that preserve strength and temperature resistance while moderating exposure to resin price swings. Producers that can offer stable material grades and transparent sourcing will be better positioned in contracts where price stability matters as much as performance.
- Closure formats expand into packaging and hygiene at scale. The introduction of hook-to-hook and side-release concepts for packaging and hygiene applications points to a broader use case set where reclosable behavior supports reusability, consumer convenience, and line integration. As these formats mature, they will create demand not only for the fasteners themselves but also for the conversion, adhesive, and automation interfaces around them. The opportunity is strongest for suppliers that can align product design with packaging line requirements and hygiene handling expectations.
These trends carry meaningful upside but also uncertainty. Feedstock volatility can compress margins if not managed through hedging, formulation choices, or contract structuring. Regulatory expectations can shift as standards evolve in medical, transportation, and packaging domains, requiring suppliers to keep validation packages current. Finally, competition from alternative attachment methods, including adhesive films, snap systems, and reusable mechanical closures, may pressure share in segments where reclosable fasteners must demonstrate clear functional advantage to justify adoption.
5. Strategic Actions for Decision-Makers
For manufacturers and converters, the priority is to build a performance-and-compliance narrative that buyers can rely on. That means investing in cycle-life validation, documenting fire-retardant or UV-resistant readiness where relevant, and standardizing custom conversion capabilities such as die-cutting and adhesive backing so that customers can move from specification to production with less friction. Suppliers that can reduce qualification time while maintaining material consistency will capture more sticky, application-specific demand.
For investors, the attractive entry points are not necessarily in undifferentiated volume but in suppliers with clear application specialization and defensible qualification libraries. Segments where repeated engagement improves serviceability, line speed, or user experience are more likely to sustain pricing power than commodity attachment markets. Attention to material cost exposure is also important; businesses with robust sourcing strategies, formulation flexibility, or contract structures that blunt feedstock volatility will generally weather margin pressure better than those dependent on spot pricing.
Fasteners Market
For procurement and sourcing leaders, the focus should shift from unit price to total cost of qualification and field reliability. Where high cycle life, environmental resistance, or regulatory compliance are in play, specification changes can create downstream cost and risk. Selecting suppliers with verified performance data and stable conversion capacity reduces the probability of re-qualification, short-term shortages, or field failures. Building preference for suppliers that can provide predictable delivery and application support is often more valuable than marginal price concessions, particularly in transportation, medical, and industrial contexts.
Hook-and-Loop Fasteners Market
The reclosable fasteners market is entering a period in which differentiation will be determined by how well suppliers translate performance, compliance, and material reliability into practical value for end applications. Deeper segmentation by material, application, and region, together with company-level benchmarking and scenario planning around feedstock volatility and regulatory change, can sharpen decision-making beyond the directional trends outlined here. For organizations that need segmented revenue perspectives, application-specific qualification pathways, or supplier comparison frameworks tailored to a particular end market, the full PW Consulting report provides detailed breakdowns and customized guidance to support those decisions.
For detailed analysis of this topic, please visit the official page: Reclosable Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com