

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
LV and MV Switchgear Market: Why the 6.98% CAGR Reshapes Global Competition

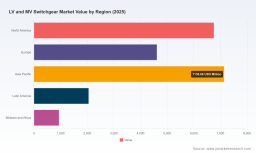
LV and MV Switchgear Market: Strategic Trends and Commercial Opportunities
The global LV and MV switchgear market has entered a phase of sustained expansion, reaching an estimated USD 21.5 billion in revenue in 2025 and projected to surpass USD 34.4 billion by 2032. This trajectory reflects a compound annual growth rate of approximately 7 percent across the 2026-2032 forecast period, accelerating from a 2020 baseline of USD 16.3 billion. The growth is not merely a function of incremental demand but a structural realignment driven by electrification, grid modernization, and regulatory shifts that are rewriting procurement requirements and technology roadmaps. For executives navigating capital allocation, product portfolios, or supply chain strategy, the market signals a transition from commoditized equipment sales to solution-oriented, digitally integrated power distribution ecosystems.
Understanding where value is being created requires looking beyond headline revenue figures. The market is dispersing across multiple layers: voltage class, application vertical, and geography all shape competitive positioning, but the underlying dynamics are converging around three themes. First, environmental mandates are forcing a rapid redesign of medium-voltage architectures. Second, digital connectivity has moved from a differentiator to a baseline expectation across both low-voltage and medium-voltage segments. Third, raw material volatility and manufacturing capacity constraints are reshaping margin structures and accelerating regionalization of supply chains. These forces are redistributing advantage among established multinationals, specialized niche players, and agile regional manufacturers.
Metal-Clad Switchgear Market
Market Landscape: Scale, Structure, and Structural Tension
Macro Trajectory and Concentration Dynamics
The market's growth path from 2020 through 2025 demonstrates resilience against macroeconomic headwinds, with revenue climbing steadily despite supply chain disruptions and inflationary pressures. The forecast period extends this momentum, with projections indicating acceleration in the latter half of the decade as utility capital programs mature and industrial electrification ramps up. Importantly, the market remains moderately fragmented. The top three players account for roughly 24.6 percent of total revenue, while the top five reach approximately 26.2 percent. This concentration level suggests a market where scale advantages exist but are not insurmountable, and where differentiated technology, regional service networks, and specification-winning capabilities can sustain profitable positions for focused competitors.
Three Defining Challenges
The industry is navigating a set of intersecting pressures that qualify any straightforward growth narrative. First, environmental regulation is compressing product lifecycles. The prohibition on new SF6-filled medium-voltage switchgear at or below 24 kV, effective from January 2026 under EU Regulation (EU) 2024/573, has shifted procurement specifications and capital planning timelines. Public procurement notices on the EU TED portal now reference SF6-free solutions in grid reinforcement projects, meaning manufacturers and system integrators must align product roadmaps with compliance deadlines that are already in force. This transition is not simply a substitution exercise; it requires revalidation of insulation performance, thermal management, and field service protocols, adding complexity to project execution.
Second, raw material costs are eroding margin predictability. Copper traded between USD 8,400 and USD 9,500 per ton during 2024-2025, while CRGO steel surpassed USD 3,000 per ton. These input pressures cut low-voltage OEM margins by up to four percentage points in some periods. Simultaneously, prices for aluminum mill shapes and primary and secondary nonferrous metals rose more than 25 percent over the past year, affecting enclosures, busbars, and structural components. The cumulative effect is that cost pass-through is uneven across regions and customer contracts, making pricing strategy and inventory management more strategic than operational.
Third, the market is experiencing a bifurcation between volume-driven standardization and value-driven customization. End-users in industrial and utility segments increasingly demand digitally connected equipment that integrates with monitoring, protection, and asset management platforms. At the same time, price sensitivity persists in commercially oriented segments where standardization is the norm. Winning in this environment requires clear segmentation of product architecture, production processes, and service models, because the economic logic of a commodity-style feeder panel differs fundamentally from that of a smart, configurable substation assembly.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Architecture
Environmental Regulation as a Technology Accelerant
Regulatory pressure is no longer a compliance cost center; it is reshaping the innovation pipeline. The EU's prohibition on SF6-filled medium-voltage switchgear up to 24 kV has catalyzed commercial momentum for SF6-free alternatives, including dry air, vacuum, and clean air insulation technologies. Schneider Electric's AirSeT portfolio exemplifies this shift, positioning SF6-free medium-voltage solutions with digital connectivity as a response to both regulatory directionality and customer sustainability targets. The same regulatory environment is forcing board-level decisions on urban substation modernization, as upgrade programs now must account for SF6-free specifications that alter project timelines, specification processes, and capital planning assumptions.
Beyond Europe, regulatory and policy signals are aligning with decarbonization and grid resilience goals. Utilities and large industrials are under increasing scrutiny to reduce greenhouse gas footprints, and switchgear selection is becoming a visible component of Scope 1 and Scope 2 reporting. This creates a commercial advantage for manufacturers that can offer verified SF6-free solutions with documented performance, because procurement teams need defensible specifications that withstand both internal sustainability reviews and external stakeholder expectations.
Worldwide Environmentally Friendly Gas Insulated Switchgear Market
Digital Connectivity as a Value Multiplier
Digitalization has moved from a premium add-on to a structural requirement across both low-voltage and medium-voltage segments. Smart switchgear with embedded sensing, condition monitoring, and communication interfaces enables predictive maintenance, faster fault isolation, and integration into broader grid management platforms. Schneider Electric's introduction of the FeederSeT smart, compact, and digitally connected low-voltage switchgear range for indoor and outdoor applications illustrates how manufacturers are embedding connectivity into core product lines rather than treating it as a separate SKU. For utilities and industrials, the value proposition extends beyond reliability: digital switchgear reduces downtime, improves asset utilization, and supports lifecycle cost optimization, which matters as labor constraints and skilled technician shortages become more acute.
The commercial implication is that differentiation is shifting from physical protection performance alone to data-enabled service models. Manufacturers that can combine robust hardware with analytics, remote visibility, and integration with customer energy management systems are capturing higher value-share and deeper customer relationships. This trend also raises the barrier for entrants that lack software, data architecture, and service delivery capabilities.
Demand-Side Shifts: Electrification and Grid Modernization
Demand growth is being shaped by two reinforcing currents. On the utility and infrastructure side, grid reinforcement programs, renewable integration, and electrification of transport and heating are driving medium-voltage expansion. Mitsubishi Electric's order for 84 kV dry air insulated switchgear from Kansai Transmission and Distribution in Japan reflects how high-voltage, SF6-free solutions are entering mainstream transmission and distribution modernization programs. On the industrial side, reshoring, data center expansion, and electrification of process heat are increasing power distribution density, which in turn drives demand for compact, reliable, and digitally manageable switchgear.
For commercial and residential applications, the pattern is more heterogeneous. Some regions are experiencing steady replacement and upgrade cycles, while others see demand tied to building electrification and local grid constraints. The common thread is that end-users increasingly evaluate switchgear not only on protection performance but also on footprint, maintainability, and compatibility with digital energy management strategies. This shifts the purchasing dynamic from lowest-capital-cost to total-cost-of-ownership considerations, which favors suppliers with strong engineering support and lifecycle service offerings.
Supply Chain and Cost Structure Reconfiguration
The supply chain environment is prompting strategic recalibration. Input cost volatility, combined with the need for specialized insulation materials and digital components, is pushing manufacturers toward longer-term supplier agreements, dual-sourcing, and regional production footprints. Hitachi Energy's announcement of a USD 1 billion investment in transformer and grid equipment manufacturing with a new factory in Virginia signals how major players are committing to domestic capacity expansion in response to demand growth and supply chain resilience priorities. For the broader LV and MV switchgear ecosystem, such capacity investments indicate a multi-year ramp in manufacturing capability, but also a lag between investment announcements and commercially available incremental capacity, which can sustain pricing tension in the near term.
At the same time, component availability for digital subsystems, including sensors, communication modules, and control electronics, introduces dependency on semiconductor and electronics supply dynamics that differ from traditional electromechanical supply chains. Manufacturers that integrate these capabilities internally or through tightly managed partnerships gain flexibility, while those dependent on fragmented supplier bases face more variable lead times and quality risk.
Competitive Landscape: Positioning, Differentiation, and Structural Evolution
Strategic Positioning Among Leading Players
The competitive set spans global multinationals with broad power distribution portfolios and specialized manufacturers with focused application expertise. Siemens AG emphasizes a comprehensive medium-voltage power distribution portfolio anchored in smart grid capabilities, vacuum technology, and 24 kV ratings serving utilities and industrial applications, positioning reliability and system integration as core themes. Schneider Electric pairs a smart low-voltage FeederSeT range with SF6-free AirSeT medium-voltage solutions, using digital connectivity and regulatory alignment to appeal to customers managing both operational performance and sustainability obligations. ABB Ltd. maintains a broad medium and low-voltage equipment manufacturing footprint, including digital switchgear and regional production capabilities, with an emphasis on power distribution breadth and engineering integration. Eaton Corporation focuses on custom low and medium-voltage solutions for industrial, commercial, and utility power distribution, leveraging application engineering and configuration flexibility. Mitsubishi Electric's 84 kV dry air insulated and SF6-free solutions highlight a focus on grid modernization and renewable integration with high-voltage technology differentiation.
On the specialized side, Enercon Power provides custom-designed low and medium-voltage switchgear up to 15 kV with UL891 and UL1558 certification, serving on-site industrial and defense applications where specification precision and certification rigor matter. RESA Power and BCS Switchgear address markets that value remanufactured and custom new equipment, offering metal-clad, metal-enclosed, and pad-mounted styles across voltage ranges up to 38 kV, appealing to cost-conscious buyers who still require performance and reliability. LS Electric Co., Ltd. targets optimized medium-voltage switchgear for primary and secondary distribution across industrial, commercial, and residential applications, while Liyond provides medium-voltage switchgear solutions including GIS, KYN, RMU, and other configurations, competing on configurable product breadth and regional service reach.
Differentiation and Competitive Wedges
Several strategic wedges are shaping competitive outcomes. One is regulatory-ready SF6-free performance. As SF6 restrictions tighten and procurement specifications reference SF6-free requirements, manufacturers with validated alternatives and established certification paths are positioned to win specification decisions earlier in project cycles. A second wedge is digital service integration. Suppliers that offer not just connected hardware but also interoperable data formats, remote diagnostics, and preventive maintenance programs are building switching costs and recurring value streams. A third wedge is application-specific customization and certification. In industrial, defense, and specialized utility contexts, the ability to deliver UL-certified, code-compliant, and site-specific designs with reliable lead times creates a defensible niche that broad-line competitors may under-serve.
A fourth, often underappreciated, wedge is supply assurance. In a period of input cost volatility and capacity ramp-up, customers are assigning premium value to suppliers that can commit to delivery, maintain inventory buffers, and provide transparent lead-time visibility. This favors players with disciplined operations, multi-site manufacturing, and strong supplier relationships, and it is particularly relevant for large projects where delays carry significant penalty and reputational risk.
Structural Evolution: Consolidation, Fragmentation, and New Entrants
The market's moderate concentration suggests room for targeted consolidation, particularly in remanufacturing, specialty customization, and regional service segments where scale Economics are less dominant than technical capability and customer relationships. At the same time, fragmentation persists because application diversity and local code requirements sustain demand for smaller, agile suppliers that can respond quickly to niche specifications. New entrants are most likely to emerge where digital-native approaches, modular product platforms, or regional manufacturing models can offer meaningful cost or responsiveness advantages, but their success will depend on navigating certification, field validation, and service infrastructure requirements that are difficult to replicate quickly.
A plausible evolution path is a barbell structure: large multinationals expanding their integrated smart and SF6-free portfolios while consolidating service and aftermarket channels, and a layer of specialized manufacturers strengthening positions in high-specification industrial, defense, and regional utility applications where customization and certification expertise command premium economics. The middle ground of undifferentiated commodity switchgear faces the greatest pressure from input cost volatility, digital expectations, and regulatory-driven redesign cycles.
Future Trends and Commercial Implications
Trend One: SF6-Free Medium-Voltage Becomes Specification Default
Over the next three to five years, SF6-free solutions will move from an environmentally motivated alternative to a default consideration for medium-voltage switchgear at or below 24 kV in regulated markets, with influence extending to procurement specifications in other regions through multinational customer policies and utility sustainability commitments. The commercial opportunity lies in developing validated product lines, supporting documentation, and field service capabilities that reduce specification risk for customers. The uncertainty is whether alternative insulation technologies can achieve cost parity at scale and whether project timelines can absorb revalidation and training requirements without delaying capital programs.
Trend Two: Digital Integration Drives Recurring Value and Switching Costs
Digital connectivity will increasingly be treated as part of the core product architecture rather than an accessory. Expect broader adoption of condition monitoring, remote diagnostics, and integration with energy and asset management platforms, particularly in industrial and utility settings where downtime costs and labor constraints are acute. Manufacturers that build interoperable data layers and service offerings can capture higher-margin recurring revenue and deepen customer lock-in. The risk is that digital fragmentation and cybersecurity requirements raise integration complexity, and that customers demand open standards that reduce the proprietary advantage of any single supplier.
Trend Three: Regionalization and Capacity Investment Redraw Supply Economics
Capacity investments and supply chain regionalization will reshape lead times, cost structures, and competitive geography over the forecast period. Large manufacturing commitments signal a multi-year expansion cycle, but near-term supply tightness may persist in specific components and regions, sustaining pricing tension for commoditized segments while allowing premium economics for differentiated, certified, and digitally enabled products. The opportunity is for manufacturers and integrators that can combine regional supply assurance with specification-winning technology and service. The uncertainty is whether macroeconomic conditions, trade policy, or raw material disruptions could alter the pace of capacity realization and whether demand growth in certain verticals might outpace available qualified capacity.
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Align product roadmaps explicitly with SF6-free requirements and digital connectivity expectations. Treat regulatory deadlines and customer sustainability specifications as design constraints from the outset rather than late-stage adaptations. Prioritize validated insulation alternatives, certification completeness, and field service readiness, because specification wins increasingly depend on defensible performance documentation and compliance clarity. In parallel, structure product architectures to separate high-volume standardized lines from configurable, digitally enabled offerings so that margin structures and production processes match the economic logic of each segment.
- Invest in SF6-free validation, certification pathways, and lifecycle documentation to reduce customer specification risk.
- Build interoperable digital service capabilities, including remote monitoring, predictive maintenance, and data integration, as part of the core offering rather than an add-on.
- Segment manufacturing and pricing strategies to protect margins against raw material volatility while preserving competitiveness in standardized segments.
For Investors and Capital Allocators
Focus on firms with clear differentiation in SF6-free technology, digital service integration, and application-specific customization, rather than relying solely on scale. The moderate market concentration implies that targeted capabilities can sustain strong positioning, but the same dynamics are compressing margins in undifferentiated commodity segments. Evaluate exposure to regulatory-driven demand acceleration, regional capacity expansion, and recurring service revenue potential, while scrutinizing raw material sensitivity, certification risk, and lead-time reliability.
- Differentiate between scale advantages and capability advantages; in a moderately fragmented market, technology and service differentiation can generate premium economics.
- Assess exposure to regulatory tailwinds and digital service monetization, and weigh these against input cost sensitivity and supply chain concentration risk.
- Watch for consolidation opportunities in remanufacturing, specialty customization, and regional service where technical capability and customer relationships matter more than commodity scale.
For Procurement and Supply Chain Leaders
Treat switchgear selection as a total-cost-of-ownership decision shaped by regulatory compliance, digital integration, service availability, and supply assurance. Specification processes should account for SF6-free requirements, lead-time reliability, and compatibility with energy and asset management platforms, because these factors increasingly determine operational resilience and lifecycle cost. Where projects span multiple regulatory jurisdictions or involve multinational operations, standardize specifications around future-proofed architectures to reduce rework and re-procurement risk later in the project lifecycle.
PW Consulting
- Embed SF6-free and digital connectivity requirements early in specification and evaluation criteria to avoid late-stage redesigns and timeline disruptions.
- Prioritize suppliers with transparent lead times, regional supply assurance, and certified performance documentation, particularly for critical industrial and utility projects.
- Evaluate total lifecycle economics, including maintenance, downtime risk, and data integration, rather than focusing solely on upfront capital cost.
Positioning for the Next Phase of Value Creation
The LV and MV switchgear market is transitioning from a hardware-centric equipment market to a solution-oriented domain where regulatory compliance, digital service, and supply assurance differentiate winners. Revenue growth to the mid-2030s reflects real structural demand, but value capture will favor those who can navigate SF6-free transition timelines, integrate digital capabilities into core product architecture, and manage the margin impact of raw material volatility through disciplined segmentation and supply strategy. For manufacturers, investors, and procurement leaders, the immediate task is to align decision frameworks with these dynamics rather than treating them as peripheral concerns. More detailed segmentation data, regional demand breakdowns, and company-level competitive assessments can sharpen execution planning, and readers seeking that level of granularity can explore the full PW Consulting research report for comprehensive figures and tailored strategic recommendations.
For detailed analysis of this topic, please visit the official page: LV and MV Switchgear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com