

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ski Gear & Equipment Market: What the 3.82% CAGR Trajectory and 279.44 Million Valuation Reveal About 2032

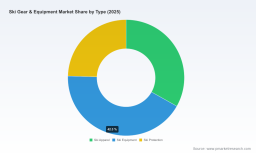
Strategic Shifts and Commercial Opportunities in the Ski Gear & Equipment Market: A 2026 Outlook
Market Landscape and Core Challenges
The global ski gear and equipment market has demonstrated resilient growth over the past five years, transitioning from a post-pandemic recovery phase into a period of structural expansion. Valued at approximately $163.15 million in 2020, the market climbed steadily to reach $204.71 million by 2024, with 2025 marking a milestone of $215.0 million. This trajectory reflects a compound annual growth rate of 3.82 percent through 2032, suggesting that the industry is moving beyond cyclical fluctuations and settling into a more predictable expansion phase. However, the growth story is not uniform, and several structural challenges are reshaping how manufacturers, retailers, and investors approach the sector.
One of the most pressing challenges is the tightening regulatory environment surrounding safety and product compliance. Governing bodies such as the FIS have introduced mandatory safety equipment requirements for competitive levels, including cut-resistant undergarments and airbag back protectors, effective from the 2025–26 season. Simultaneously, the European Union's General Product Safety Regulation now mandates digital product passports for helmets and protective gear, requiring manufacturers to document material sourcing, lifecycle impacts, and disposal methods for online marketplaces. These regulatory shifts increase compliance costs and operational complexity, particularly for mid-sized players who lack dedicated regulatory affairs teams. For industry leaders, the challenge lies in integrating compliance into product development cycles without eroding margins or slowing time-to-market.
Ski Apparel Market
A second critical challenge stems from geopolitical trade dynamics and their impact on cost structures. Recent tariff implementations have introduced significant uncertainty into sourcing and pricing strategies. European imports of ski equipment face potential tariff increases of up to 15 percent, with certain steel and aluminum components subject to rates as high as 50 percent, while Chinese-origin goods face tariffs around 30 percent. Early indicators suggest these measures are driving retailer price increases in the range of 5 to 20 percent. For companies reliant on cross-border supply chains, this creates a dual pressure: absorbing higher input costs or passing them to consumers in a market where price sensitivity varies significantly by segment and geography. The ability to navigate these tariffs through supply chain diversification, localized production, or strategic inventory positioning has become a decisive competitive factor.
A third challenge involves the evolving safety-performance nexus in consumer expectations. The recent recall of specific ski boot models by Head USA, prompted by concerns that fluorescent yellow materials could deteriorate and break during falls, underscores the heightened scrutiny on product reliability. This incident, flagged by the U.S. Consumer Product Safety Commission, highlights how product safety failures can rapidly damage brand trust and trigger regulatory intervention. For manufacturers, the imperative is to strengthen quality assurance protocols and material testing, particularly for components exposed to harsh environmental conditions. For retailers, the challenge is balancing assortment breadth with risk management, ensuring that inventory decisions align with both consumer demand and compliance standards.
Key Drivers of Market Change
Technological Innovation and Performance Breakthroughs
Innovation remains a primary engine of growth in the ski gear and equipment market, with manufacturers increasingly focused on materials science, ergonomic design, and hybrid construction techniques. The recent launch of the AR ONE ski boot by Armada, featuring Hybrid Cabrio Construction, exemplifies the industry's shift toward modular, performance-oriented designs that balance durability with weight optimization. Such innovations are not limited to competitive equipment; they are increasingly filtering into consumer segments where riders demand gear that adapts to varying snow conditions, terrain types, and skiing styles. Technological advancement also extends to protective equipment, where airbag back protectors and cut-resistant fabrics are transitioning from elite competition to broader market adoption, driven by both regulatory requirements and consumer awareness of safety.
For businesses, the implication is clear: product differentiation is increasingly tied to engineering capability and material innovation rather than brand heritage alone. Companies that invest in R&D partnerships, proprietary material formulations, and rapid prototyping cycles are better positioned to capture premium segments and command pricing power. At the same time, innovation cycles are compressing, meaning that the window between concept and commercialization is narrowing. Manufacturers must align their development pipelines with seasonal launch calendars while ensuring that new products meet evolving safety and compliance standards from the outset.
Policy and Regulatory Environment as a Market Reshaping Force
Regulatory developments are no longer peripheral concerns; they are active drivers of product design, supply chain configuration, and market access. The FIS mandates for cut-resistant undergarments and airbag back protectors in alpine speed events have cascading effects on the broader equipment ecosystem. Manufacturers of protective gear must scale production of certified components, while ski equipment makers may need to adjust binding, boot, and apparel designs to integrate compatible safety features. In parallel, the EU's digital product passport requirement for helmets and protective gear introduces traceability obligations that affect material procurement, manufacturing documentation, and end-of-life handling.
These regulatory shifts create both operational burdens and strategic opportunities. Companies that proactively build compliance into their product architecture can reduce the risk of retrofit costs and market delays. Moreover, regulatory transparency can serve as a trust signal in a market where consumers and retailers are increasingly attentive to safety and sustainability claims. The challenge is that compliance is not uniform across regions, meaning that multinational players must navigate a patchwork of requirements. Businesses with agile regulatory functions and flexible manufacturing footprints are better equipped to manage this complexity, while smaller players may need to seek partnerships or standardize offerings to reduce compliance overhead.
Demand-Side Shifts in Consumer and Enterprise Behavior
Consumer behavior in the ski market is evolving along multiple dimensions. There is growing demand for equipment that supports diverse skiing modalities, from alpine downhill to cross-country and ski touring. This diversification is reflected in the market's application segments, where ski touring and backcountry-oriented gear have gained traction among consumers seeking adventure-based experiences beyond traditional resort skiing. At the same time, performance apparel continues to command significant share, as riders prioritize weather adaptability, mobility, and lifestyle integration. The line between functional gear and fashion-forward outerwear is blurring, particularly in segments where brand identity and aesthetic appeal influence purchasing decisions.
On the enterprise side, retailers are recalibrating their assortment strategies in response to both demand trends and cost pressures. The establishment of seasonal retail locations, such as Perfect Moment's first European store at the Kitzbuhel ski resort, illustrates a strategic move toward experiential, location-based retail that aligns with resort ecosystems and local customer bases. This model allows brands to test market responsiveness, build community engagement, and capture high-intent purchase moments during peak seasons. For larger retail networks, the focus is shifting toward curated assortments that balance entry-level accessibility with performance-tier offerings, while managing inventory risk in an environment of volatile input costs.
Ski Apparel Market
Supply Chain and Cost Structure Evolution
Supply chain dynamics are undergoing significant recalibration as tariffs, material costs, and logistics constraints intersect. The tariff landscape described earlier is prompting companies to reconsider sourcing geographies, evaluate nearshoring options, and adjust pricing architectures. For equipment categories that rely heavily on metals such as steel and aluminum, the exposure to higher tariff rates is particularly acute, forcing manufacturers to weigh material substitution, component redesign, or supplier relocation. These decisions carry long-term implications for product performance, production costs, and lead times.
At the same time, the market's concentration characteristics—with a substantial share held by a limited number of leading firms—mean that supply chain advantages are not evenly distributed. Larger players with established supplier relationships and diversified sourcing networks can absorb shocks more effectively, while smaller or specialized manufacturers may face disproportionate pressure. This dynamic is likely to accelerate consolidation trends, as mid-sized companies seek partners or acquirers to strengthen supply chain resilience. For investors and strategic planners, supply chain adaptability is becoming a core criterion for evaluating market participants, alongside product innovation and brand strength.
Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive landscape is shaped by a mix of established multinational brands, specialized equipment manufacturers, and retail-focused players. Amer Sports Oyj stands out for its multi-brand portfolio strategy, encompassing Salomon, Atomic, Armada, and Peak Performance, which spans skis, boots, bindings, poles, helmets, and snowboarding gear. This breadth allows the company to address multiple customer segments and skiing disciplines under a coordinated brand architecture. Its sponsorship of 250 athletes at the Milano Cortina 2026 Winter Olympics and Paralympics, resulting in 87 medals, reinforces the value of elite sport alignment as a credibility and visibility driver. For Amer Sports, the strategy combines performance heritage with broad market coverage, leveraging Olympic association to strengthen brand equity across both competitive and consumer channels.
Groupe Rossignol and Fischer Sports GmbH represent another dimension of the landscape, with deep specialization in skis, boots, bindings, and poles. Rossignol's focus on core ski equipment and Fischer's emphasis on technical components position these companies as go-to suppliers for riders who prioritize performance precision. Their strategies often center on product craftsmanship, racing lineage, and European manufacturing identity, which resonate with segments that value technical credibility and heritage. LEKI Lenhart GmbH and Marker Völkl further illustrate the specialization trend, with LEKI concentrating on ski poles and accessories and Marker focusing on bindings. These focused players often compete on component-level innovation and compatibility, serving both end consumers and OEM partners who require reliable, standards-aligned parts.
PW Consulting
Decathlon occupies a distinct position through its mass-market, vertically integrated model, offering skis, boots, bindings, and accessories under its own brand. Its strategy emphasizes accessibility, value engineering, and broad availability, making it a significant force in entry-level and mid-tier segments. By controlling design, production, and retail, Decathlon can respond quickly to demand shifts and manage cost structures in ways that pure manufacturers may find difficult. Meanwhile, brands like The North Face and Volcom bring apparel and protective gear expertise into the ski space, leveraging outdoor lifestyle positioning to capture consumers who view ski wear as part of a broader active lifestyle rather than a purely functional category.
Specialized and niche manufacturers such as ON3P Skis, Black Crows, Peak Ski Company, Voile, and Union Binding Company highlight the market's fragmentation at the high-performance and specialty ends. These companies often compete on handmade craftsmanship, specific skiing disciplines, or innovative binding and pole technologies. Their growth trajectories are closely tied to community loyalty, influencer and athlete endorsements, and the ability to differentiate in crowded categories. Black Diamond Equipment and Scott Sports contribute to this mosaic with poles, helmets, goggles, and protective gear, reinforcing the importance of safety and accessory categories as complementary revenue streams. Blizzard-Tecnica USA illustrates the partnership and regionalization model, combining boot and binding expertise with localized distribution to serve specific market needs.
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The market's concentration profile suggests that a relatively small number of firms command a significant share of revenue, which typically points to barriers to scale in distribution, brand investment, and supply chain management. However, the presence of numerous specialized players indicates that differentiation remains viable in specific subcategories, particularly where performance, customization, or niche discipline focus matters. This duality creates a landscape where consolidation pressure exists alongside opportunities for focused entrants who can serve underserved segments or introduce disruptive product concepts.
Recent product launches and retail initiatives provide a window into how this evolution is unfolding. Armada's AR ONE boot launch and Black Crows' Corvus ski model update demonstrate continued investment in product refreshes and performance positioning, even as the broader market grows at a moderate pace. Union Binding Company's Atlas Step On snowboard binding, with its responsive waterproof layer and extruded 3D aluminum heelcup, reflects innovation in binding mechanisms that aim to improve usability and durability. Perfect Moment's seasonal store expansion in Kitzbuhel indicates that retail experimentation is active, with brands seeking closer proximity to end consumers in destination markets. Together, these developments suggest that competition is increasingly multidimensional: brands must perform across product innovation, safety compliance, retail experience, and brand storytelling simultaneously.
Future Trends for the Next 3–5 Years
Safety and Compliance as Standard Product Attributes
Over the next several years, safety equipment and regulatory compliance are expected to transition from optional enhancements to baseline product requirements across more market segments. The FIS mandates for cut-resistant undergarments and airbag back protectors, combined with EU digital product passport requirements, are likely to normalize safety-integrated design and traceability documentation. As these standards diffuse from competitive levels into consumer markets, manufacturers that have already embedded compliance into their development processes will face lower adaptation costs. Commercial opportunity lies in positioning safety and transparency as trust multipliers, particularly for protective gear and children's equipment where parental decision-making is influenced by certification and material clarity. The risk is that compliance complexity could pressure smaller players, potentially accelerating consolidation or prompting reliance on standardized component suppliers.
Tariff-Driven Reconfiguration of Sourcing and Pricing
Trade policy uncertainty is expected to persist as a structural factor influencing cost bases and product pricing. The recent tariff dynamics affecting European and Chinese imports suggest that companies will continue to explore supply chain diversification, material alternatives, and pricing architectures that balance margin protection with consumer affordability. Over the next 3–5 years, this may lead to a more regionally varied product landscape, where certain markets see localized sourcing or adjusted product specifications to mitigate tariff exposure. Commercial opportunity exists for manufacturers that can demonstrate supply chain flexibility, such as multi-region production capabilities or modular component designs that allow material substitutions without compromising performance. The risk is that prolonged tariff volatility could compress margins for brands unable to pass through costs or reconfigure sourcing quickly, particularly in price-sensitive segments.
Modal Diversification and Experiential Demand Growth
Demand for ski gear is likely to continue diversifying across skiing modalities, with ski touring and backcountry-oriented equipment gaining share among consumers seeking adventure and off-piste experiences. This trend aligns with broader outdoor recreation growth and the desire for differentiated experiences beyond traditional resort skiing. At the same time, experiential retail and resort-adjacent distribution models are expected to expand as brands seek to capture high-intent purchase moments and build local community engagement. Commercial opportunity lies in developing product lines and retail concepts that match the needs of specific skiing styles, while leveraging destination-based activations to drive trial, loyalty, and seasonal demand spikes. The risk is that modal diversification can fragment demand, requiring more sophisticated assortment planning and inventory management to avoid overstock in slower-moving categories.
Actionable Recommendations for Decision-Makers
For Manufacturers and Brand Leaders
Product development cycles should integrate safety and compliance requirements from the earliest design stages rather than treating them as post-launch adjustments. Aligning R&D with regulatory trajectories—such as cut-resistant materials, airbag protection integration, and digital product passport documentation—can reduce retrofit risk and accelerate market readiness. At the same time, manufacturers should evaluate supply chain exposure to tariff-sensitive materials and consider modular component strategies that provide flexibility without sacrificing performance. For brands with multi-category portfolios, balancing specialization with cross-category synergies can help capture demand across skiing modalities while maintaining clear value propositions for each segment.
For Investors and Strategic Planners
Evaluation of market participants should extend beyond brand recognition to include supply chain resilience, compliance capability, and product differentiation in high-growth subcategories. Companies with diversified sourcing, strong safety engineering, and clear positioning in either performance specialization or accessible value segments are better placed to navigate regulatory and trade uncertainties. Interest in experiential retail and resort-adjacent distribution also warrants attention, as these models can provide demand visibility and community leverage, though they require careful capital allocation and seasonal risk management. Given the market's moderate growth pace and concentrated structure, identifying players with adaptable operating models and credible innovation pipelines is essential for long-term value capture.
For Retailers and Procurement Teams
Assortment planning should account for both compliance evolution and tariff-influenced pricing dynamics. Curating a mix of entry-level accessibility and performance-tier offerings can help balance volume and margin, while close monitoring of safety recalls and regulatory updates can mitigate reputational and inventory risk. Procurement strategies that diversify supplier bases and anticipate material cost shifts can improve resilience, particularly for equipment categories with high metal content or complex component sourcing. Engaging with brands that provide clear documentation, traceability, and product safety assurance can also strengthen consumer trust and reduce downstream complication costs.
Closing Perspective
The ski gear and equipment market is entering a phase where growth is supported by product innovation, demand diversification, and brand-driven retail experimentation, but it is also being reshaped by regulatory mandates and trade-related cost pressures. Success in this environment depends on the ability to align product development with safety and compliance trajectories, build supply chain flexibility, and differentiate in a landscape that rewards both specialization and strategic breadth. The interplay of these forces will determine which companies capture premium segments, which retailers optimize assortment and risk, and which investors identify resilient business models with credible innovation pipelines.
For decision-makers seeking deeper segmentation data, region-specific dynamics, and customized strategic recommendations, the full PW Consulting research report provides a more granular view of market sizing, competitive benchmarking, and scenario analysis across the ski gear and equipment value chain.
For detailed analysis of this topic, please visit the official page: Ski Gear & Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com