

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Reclosable Fasteners Market: Why 6.98% CAGR Reshapes Strategy Through 2032

The Strategic Trajectory of the Reclosable Fasteners Market: Navigating Growth from 2026 to 2032
1. Market Landscape and Core Challenges
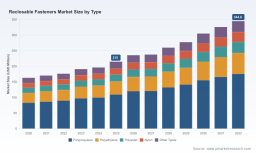
The global market for reclosable fasteners has matured into a structured growth corridor, with revenue expanding from approximately $163 million in 2020 to an estimated $215 million in 2025. Over the historical period, the segment demonstrated steady recovery and accelerated adoption across technical and consumer-facing applications. Looking ahead through 2032, the trajectory points toward sustained expansion, with the market projected to reach roughly $345 million. This forward path implies a compound annual growth rate of 6.98 percent, a pace that outstrips broad industrial averages and signals deepening integration into high-value supply chains. The growth is not uniform across all channels; rather, it reflects a rebalancing toward applications where functional reliability, repeated engagement cycles, and material performance carry direct operational or safety implications.
Several structural challenges now sit at the center of the market’s evolution. First, raw material volatility has become a persistent margin pressure. Polypropylene resin costs fluctuate in tandem with crude oil and natural gas feedstock pricing, making cost forecasting difficult for converters and OEMs that operate on fixed-margin contracts. Nylon continues to dominate material usage in hook and loop fasteners, capturing roughly 42.7 percent of material consumption due to its strength and temperature resistance, but its price sensitivity and processing complexity introduce variability for manufacturers seeking consistent unit economics. Second, performance thresholds are rising. High cycle life requirements up to 10,000 openings are increasingly standard for automotive and medical reclosable fasteners, pushing suppliers to redesign engagement systems, optimize molding and cutting tolerances, and validate durability under repeated stress. Third, regulatory and certification demands are reshaping qualification pathways. Fire-retardant and UV-resistant formulations are now required for hook and loop fasteners in aerospace and transportation applications, while medical and hygiene segments impose their own biocompatibility, cleanability, and traceability expectations. These requirements lengthen development timelines and raise the barrier for new entrants, but they also create defensible positioning for suppliers that can demonstrate verified compliance.
2. Core Drivers of Market Change
Technical Innovation and Form-Factor Evolution
Innovation in reclosable fasteners is shifting from incremental material swaps to purpose-built engagement architectures. Mushroom-shaped stems, side-release mechanisms, and hook-to-hook closures are being engineered for specific engagement forces, peel angles, and environmental exposures rather than generic attachment. At recent industry gatherings, APLIX S.A. showcased an Easylock hook-to-hook reclosable closure designed for flexible packaging, signaling a move toward closures that can be operated quickly, resealed cleanly, and integrated into automated packaging lines. The same company introduced SoftGrip Signature side tape and a SoftGrip Cross Over hook for diapers, reflecting a broader push to balance tactile comfort, retention strength, and manufacturability in hygiene applications. These developments illustrate a transition in which fasteners are treated less as commodity attachment components and more as engineered interfaces that influence product usability, assembly speed, and end-user perception.
Policy and Regulatory Pressure as a Design Constraint
Regulatory expectations are no longer a downstream compliance burden; they are increasingly a front-end design constraint. In transportation and aerospace, fire-retardant and UV-resistant formulations are mandatory for many fastener applications, which narrows the field of acceptable material systems and rewards suppliers with established testing protocols and documentation. In medical and hygiene environments, requirements around cycle durability, cleanability, and material consistency raise the bar for qualification. The practical effect is a segmentation of the market by trust and verification. Suppliers that can provide repeatable performance data, material certifications, and application-specific validation reduce friction for OEMs navigating complex approval processes. This dynamic strengthens incumbents with established qualification libraries while creating entry points for specialists that can move faster in niche regulatory niches.
Demand-Side Shifts in End-Use Behavior
End-user and OEM behavior is changing in ways that favor reclosable solutions over fixed fastening where serviceability, modularity, and reusability matter. In footwear and apparel, comfort, adjustability, and repairability are gaining weight as product cycles lengthen and circularity expectations rise. In transportation, modular interior components and cable management systems increasingly rely on fasteners that can be engaged and disengaged repeatedly during assembly, maintenance, and reconfiguration. Industrial manufacturing continues to adopt reclosable fasteners for temporary fixtures, jigs, and reusable protective covers where quick changeover reduces downtime. Medical and hygiene applications drive demand for closures that maintain seal integrity while supporting frequent handling and controlled opening. These demand shifts create a broader acceptance floor for reclosable fasteners, particularly where repeated engagement delivers measurable operational benefits rather than purely aesthetic value.
Supply Chain and Cost Structure Realignment
Supply chain dynamics are reshaping how manufacturers think about sourcing, conversion, and localization. Material availability, resin pricing, and processing capacity all feed into total cost of ownership, and volatility in polypropylene feedstock pricing keeps cost planning under pressure. At the same time, lead-time reliability and specification consistency have become as important as unit price for OEM buyers, particularly in transportation and medical segments where qualification cycles are long and substitution is costly. The result is a growing emphasis on supplier partnerships that offer not only competitive pricing but also predictable delivery, validated material grades, and the ability to support custom die-cutting, adhesive backing, and molded configurations. Cost structure discussions are increasingly framed around resilience and qualification risk rather than headline price alone.
3. Competitive Landscape and Leading Strategies
The market remains moderately fragmented, with the top three participants holding about 24.6 percent of revenue and the top five reaching approximately 26.2 percent. This concentration pattern indicates that scale alone does not dominate the segment; instead, differentiation comes from application expertise, material engineering, and the ability to serve demanding certification regimes. Incumbents are using product breadth, cycle-life validation, and specialty formulations to defend share, while smaller converters and regional specialists compete by serving specific end markets, offering rapid customization, or focusing on niche performance needs such as high-temperature resistance or fire-retardant tape systems.
PW Consulting
3M Company anchors part of the market with Dual Lock reclosable fasteners and hook and loop offerings that rely on mushroom-shaped stems for blind attachment, paired with high cycle life and pressure-sensitive adhesive options. The strategic emphasis here is on engagement reliability and versatile integration, allowing the portfolio to reach into contexts where adhesive backing and repeatable locking are both important. Velcro Companies B.V. provides ALFA-LOK and standard hook and loop reclosable fasteners for automotive, medical, and industrial uses, leaning into brand recognition and established application credentials. APLIX S.A. produces textile, plastic, and molded hook and loop tapes with options for high cycle life, fire retardancy, and UV resistance, extending into automotive, aircraft, and packaging applications; the company’s recent exhibit presence and product introductions underscore an intent to broaden closure formats for packaging and hygiene use cases. Halco USA manufactures and converts specialty hook and loop reclosable fasteners, including mushroom-cap systems, with a focus on transportation and industrial OEMs. Hook and Loop Technology GmbH supplies high-temperature and fire-retardant systems and tapes for aerospace and industrial use, effectively positioning around harsh-environment performance. kragoTEC GmbH develops self-adhesive and custom hook and loop tapes and fasteners for technical textiles and industrial applications, emphasizing tailored configurations where standard products fall short.
Across these players, several strategic patterns stand out. Asset-rich entrants compete on engineering breadth, documented durability, and the ability to offer adhesives, molded options, and specialty coatings. Application-focused specialists compete on speed to specification, regional service, and deep knowledge of a single segment’s qualification path. Meanwhile, the rise of new closure formats and packaging-oriented reclosable solutions is broadening the competitive field beyond traditional hook and loop dynamics. The market is evolving through a combination of consolidation pressure among converters seeking scale in qualification and conversion, alongside fragmentation at the application level where specialized performance requirements reward focused expertise. New entrants tend to succeed when they solve a specific reliability, comfort, or compliance problem rather than trying to displace incumbents on price in commodity-grade volume.
What the Competitive Pattern Means for Buyers and Suppliers
For buyers, the practical takeaway is that supplier selection is increasingly a risk-management decision. Proven cycle-life data, fire-retardant or UV-resistant validation where required, and reliable conversion capability often matter more than minor price differences, because qualification and field performance carry long-term implications. For suppliers, the winning posture combines a credible performance narrative with the operational discipline to deliver consistent material grades and custom formats at scale. The most resilient players are those that can move quickly from a market need—such as a lighter closure for packaging or a high-cycle medical-grade fastener—to validated production without sacrificing repeatability.
4. Forward Outlook: Trends Shaping the Next 3 to 5 Years
The market’s next phase will likely be defined by tighter alignment between fastener performance and application economics, more explicit sustainability and material traceability expectations, and continued diversification of closure formats beyond conventional hook and loop. Three trends are particularly important.
- Performance-led specification replaces generic sourcing. As cycle-life expectations climb and regulatory requirements tighten, buyers will increasingly specify fasteners by validated performance attributes rather than by broad product families. This shift favors suppliers that can document opening cycles, engagement force ranges, environmental resistance, and adhesive behavior in application-specific terms. The commercial opportunity lies in helping OEMs translate performance requirements into fastener architectures that also reduce assembly time or improve serviceability.
- Material strategy becomes a competitive lever. With nylon maintaining a large share of material usage and polypropylene costs tied to feedstock volatility, companies that can blend performance with cost predictability will gain margin advantage. Expect continued experimentation with blends, surface treatments, and additive strategies that preserve strength and temperature resistance while moderating exposure to resin price swings. Producers that can offer stable material grades and transparent sourcing will be better positioned in contracts where price stability matters as much as performance.
- Closure formats expand into packaging and hygiene at scale. The introduction of hook-to-hook and side-release concepts for packaging and hygiene applications points to a broader use case set where reclosable behavior supports reusability, consumer convenience, and line integration. As these formats mature, they will create demand not only for the fasteners themselves but also for the conversion, adhesive, and automation interfaces around them. The opportunity is strongest for suppliers that can align product design with packaging line requirements and hygiene handling expectations.
These trends carry meaningful upside but also uncertainty. Feedstock volatility can compress margins if not managed through hedging, formulation choices, or contract structuring. Regulatory expectations can shift as standards evolve in medical, transportation, and packaging domains, requiring suppliers to keep validation packages current. Finally, competition from alternative attachment methods, including adhesive films, snap systems, and reusable mechanical closures, may pressure share in segments where reclosable fasteners must demonstrate clear functional advantage to justify adoption.
5. Strategic Actions for Decision-Makers
For manufacturers and converters, the priority is to build a performance-and-compliance narrative that buyers can rely on. That means investing in cycle-life validation, documenting fire-retardant or UV-resistant readiness where relevant, and standardizing custom conversion capabilities such as die-cutting and adhesive backing so that customers can move from specification to production with less friction. Suppliers that can reduce qualification time while maintaining material consistency will capture more sticky, application-specific demand.
For investors, the attractive entry points are not necessarily in undifferentiated volume but in suppliers with clear application specialization and defensible qualification libraries. Segments where repeated engagement improves serviceability, line speed, or user experience are more likely to sustain pricing power than commodity attachment markets. Attention to material cost exposure is also important; businesses with robust sourcing strategies, formulation flexibility, or contract structures that blunt feedstock volatility will generally weather margin pressure better than those dependent on spot pricing.
Fasteners Market
For procurement and sourcing leaders, the focus should shift from unit price to total cost of qualification and field reliability. Where high cycle life, environmental resistance, or regulatory compliance are in play, specification changes can create downstream cost and risk. Selecting suppliers with verified performance data and stable conversion capacity reduces the probability of re-qualification, short-term shortages, or field failures. Building preference for suppliers that can provide predictable delivery and application support is often more valuable than marginal price concessions, particularly in transportation, medical, and industrial contexts.
Hook-and-Loop Fasteners Market
The reclosable fasteners market is entering a period in which differentiation will be determined by how well suppliers translate performance, compliance, and material reliability into practical value for end applications. Deeper segmentation by material, application, and region, together with company-level benchmarking and scenario planning around feedstock volatility and regulatory change, can sharpen decision-making beyond the directional trends outlined here. For organizations that need segmented revenue perspectives, application-specific qualification pathways, or supplier comparison frameworks tailored to a particular end market, the full PW Consulting report provides detailed breakdowns and customized guidance to support those decisions.
For detailed analysis of this topic, please visit the official page: Reclosable Fasteners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com